
 Israel Lubricants Market | 2026-2036
Israel Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Lubricants Market Insights
A shortage of certified lubricant formulation chemists is redrawing competitive boundaries among Israeli blenders. Shell PLC leverages its global technical center network to sustain R&D depth locally, while Paz LTD anchors its position through backward integration into base oil logistics at the Ashdod port. Sonol competes on retail channel density, with service stations covering the Negev-to-Galilee transit corridors.
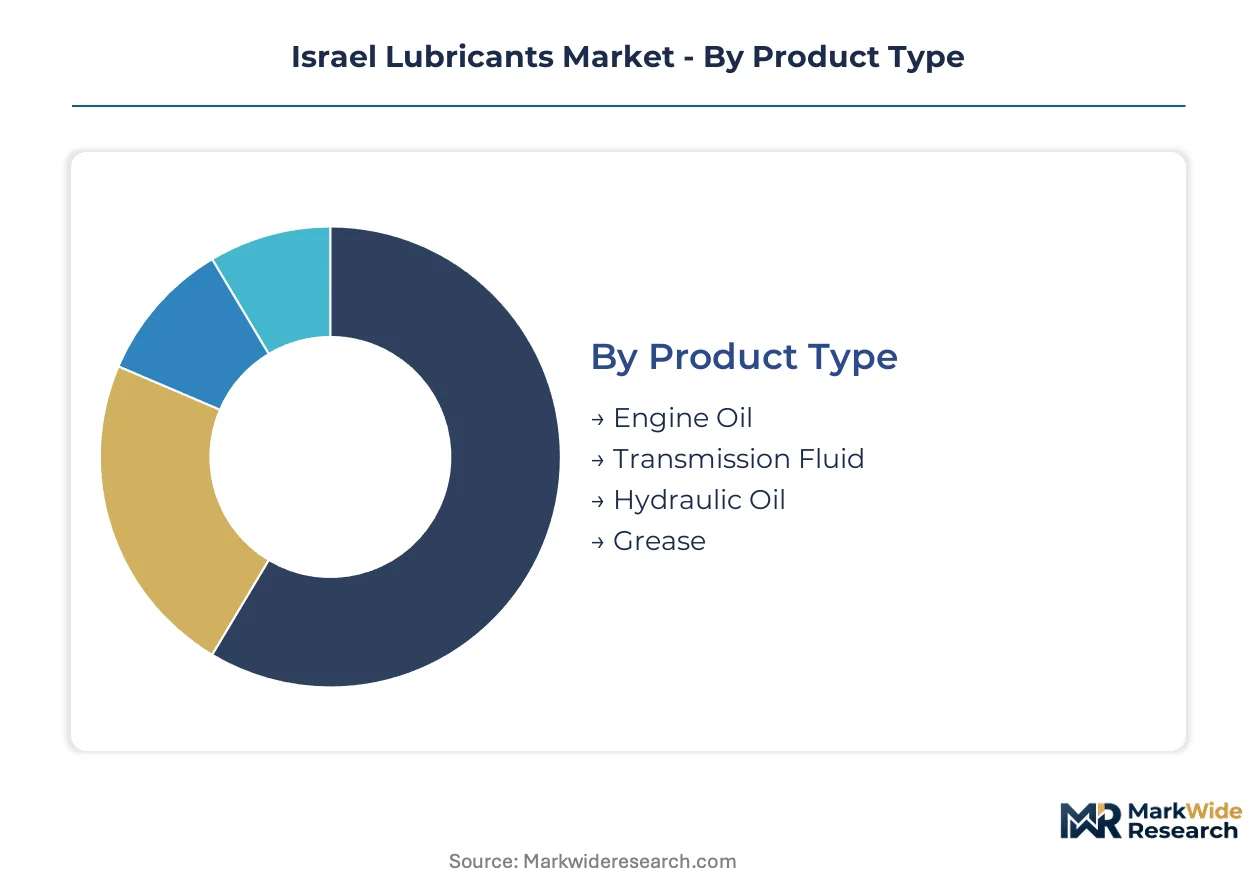
Lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear between mechanical surfaces, with viscosity grades and oxidation stability determining suitability for specific operating temperatures and loads. Their primary purpose spans engine protection, power transmission, and equipment longevity across mobile and stationary machinery. Engine oil occupies the dominant share of product type revenue given Israel's vehicle fleet age profile and extended drain-interval requirements. Industrial application demand is accelerating fastest among manufacturing plants in the Central District, where metalworking and food-processing equipment upgrades drive synthetic-grade conversion.
The Ministry of Environmental Protection enforces waste-oil collection and recycling quotas that compel reformulation toward extended-life and re-refinable chemistries. BIS-equivalent Israeli standards for lubricant performance certification, aligned with SAE and API specifications, govern market access for imported finished products. Fleet operators and industrial procurement managers must monitor regulatory tightening on zinc and phosphorus content limits, as these restrictions will force additive package redesigns and supplier qualification resets within the coming planning cycle.
Market Dynamics
Israel's lubricants sector is being restructured by the Ministry of Environmental Protection's waste-oil recycling mandates, which force blenders to reformulate toward extended-drain and re-refinable chemistries while tightening additive content limits.
Growth Catalysts
- Automotive OEM procurement intensity:Vehicle manufacturers in the Tel Aviv-Jerusalem corridor are demanding higher-specification synthetic formulations for powertrain warranties.
- Extended-drain chemistry mandates:Ministry of Environmental Protection quotas on waste-oil collection push reformulation toward longer service intervals and biodegradability.
- Central District industrial upgrading:Metalworking and food-processing equipment modernization in manufacturing clusters accelerates synthetic-grade conversion.
Market Restraints
- Base oil import dependency:Israel lacks domestic base oil production, leaving blenders exposed to Mediterranean shipping disruptions and port congestion at Ashdod.
- Certified formulation chemist scarcity:The shallow talent pool for lubricant R&D specialists limits blender technical capacity and slows new product qualification.
- Zinc and phosphorus content ceilings:Pending Ministry of Environmental Protection restrictions on anti-wear additives force costly additive package redesigns.
Strategic Opportunities
- Negev logistics corridor penetration:Fleet density along the Beersheba-Eilat transit route remains underserved by premium lubricant service infrastructure.
- Food-grade synthetic conversion:HACCP-aligned manufacturing plants in the Sharon Plain offer a regulatory-tailwind segment for NSF-registered lubricant suppliers.
- Re-refining infrastructure gaps:Domestic waste-oil re-refining capacity shortfalls create white space for circular-economy joint ventures with European technology licensors.
Industry Challenges
- Additive qualification timelines:BIS-equivalent Israeli standards alignment with evolving API SP and ILSAC GF-6 specifications stretches certification cycles to 18-24 months.
- Legacy fleet compatibility:Israel's aging vehicle parc requires blenders to maintain backward-compatible formulations alongside next-generation low-viscosity grades, duplicating SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Lubricants Market |
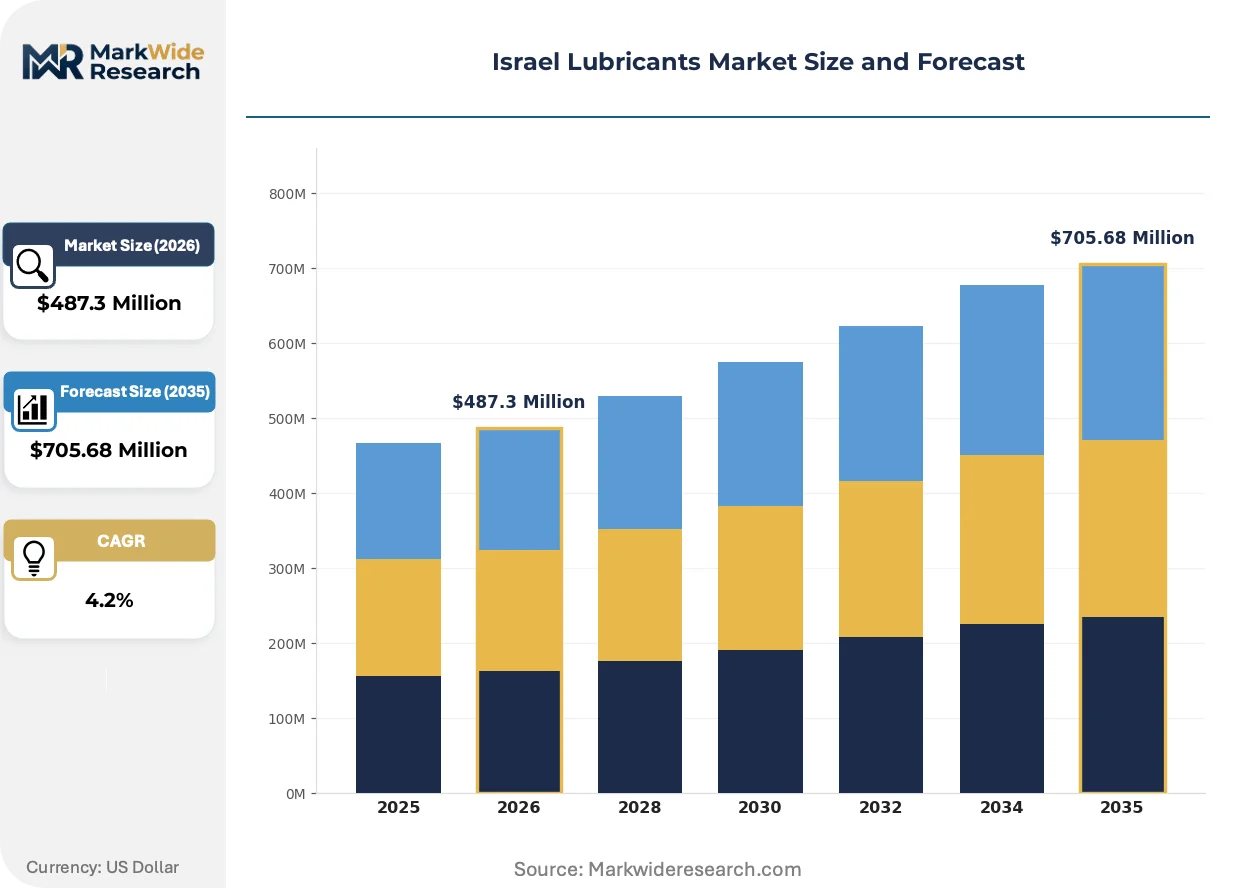
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $705.68 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Grease Application: Automotive, Industrial, Marine, Aerospace End User: Manufacturing Plants, Automotive OEMs, Repair Shops, Fleet Operators Packaging Type: Bottles, Drums, Bulk, Pails |
| Companies Covered | Shell PLC, Delkol, Paz LTD, Chevron Corporation, LIQUI MOLY GmbH, Sonol, ExxonMobil Corporation, TotalEnergies, BP PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Lubricants Market Trends and Innovations
Formulation chemistry, regulatory compliance architecture, and procurement modalities are simultaneously transforming how lubricants are specified, supplied, and consumed across Israeli industrial and automotive segments.
Polyalkylene glycol (PAG) and ester-based synthetic base stocks are fragmenting the traditional mineral-oil-dominant product mix. Food-processing and precision metalworking operations in the Central District are adopting these chemistries for thermal stability and biodegradability. The shift is fragmenting blender R&D priorities between legacy mineral portfolios and high-performance synthetic lines.
Israel's Ministry of Environmental Protection is tightening enforcement of waste-oil collection quotas and advancing zinc/phosphorus content limits for engine oils. These measures compel additive suppliers to redesign anti-wear packages and force blenders to requalify product lines. Fleet operators face compliance-driven supplier resets during the current procurement cycle.
Centralized procurement by multi-site fleet operators is compressing distributor margins and consolidating volume into direct manufacturer agreements. Traditional service-station channels in peripheral regions are losing share to mobile lubricant delivery services and on-site bulk storage installations. The behavioral shift is most pronounced along the Tel Aviv-Haifa industrial belt where logistics density supports vendor-managed inventory models.
Israel Lubricants Market Segmentation
Segmentation in Israel's lubricants market reveals how regulatory pressure from the Ministry of Environmental Protection and geographic concentration of industrial activity reshape procurement patterns across product categories. Understanding these divides exposes where formulation chemistry investments concentrate and where distribution infrastructure gaps persist.
Product Type:
Ministry of Environmental Protection mandates on waste-oil recycling and zinc/phosphorus content differentiate performance requirements across lubricant chemistries.
- Engine Oil:Formulations combine Group II/III base stocks with detergent-dispersant additive packages calibrated to SAE viscosity grades and API SP specifications. Demand concentrates in the Tel Aviv-Jerusalem corridor where fleet density and aging vehicle parc sustain high consumption, though pending zinc/phosphorus ceilings force additive package redesigns that stretch qualification timelines to 18-24 months.
- Hydraulic Oil:Anti-wear formulations with zinc-based chemistry dominate current industrial use, though ISO VG 32-68 synthetic conversions are accelerating in Central District manufacturing clusters. Food-processing plants in the Sharon Plain are driving NSF-registered synthetic adoption for HACCP compliance, fragmenting blender R&D priorities between legacy mineral portfolios and high-performance synthetic lines.
- Transmission Fluid:ATF and gear oil formulations specified to OEM fill requirements for powertrain warranties.
- Grease:Lithium-complex and calcium-sulfonate thickeners for bearing and chassis lubrication in Negev-to-Galilee transit corridors.
Established volume favors engine oil; emerging adoption favors hydraulic oil synthetic conversion.
Application:
Customer procurement scale and technical specification intensity separate application segments by margin structure and channel access.
- Automotive:Passenger vehicle and commercial fleet lubrication spans OEM fill, service-fill, and retail aftermarket channels. Centralized procurement by multi-site fleet operators along the Tel Aviv-Haifa industrial belt compresses distributor margins and consolidates volume into direct manufacturer agreements, while peripheral regions lose share to mobile delivery services.
- Industrial:Metalworking, food-processing, and general manufacturing equipment lubrication demands thermal stability and biodegradability. Central District plant modernization accelerates synthetic-grade conversion, with polyalkylene glycol and ester-based base stocks fragmenting the traditional mineral-oil-dominant product mix.
- Marine:Port of Ashdod and Eilat vessel lubrication subject to MARPOL discharge regulations.
- Aerospace:Military and commercial aviation specifications with MIL-PRF qualification requirements.
Volume concentration sits with automotive; steepest expansion trajectory belongs to industrial synthetic conversion.
End User:
Procurement technical capability and volume scale determine whether lubricant supply flows through distributor networks or direct manufacturer relationships.
- Fleet Operators:Multi-vehicle logistics and transit companies with centralized technical procurement functions. Tel Aviv-Jerusalem corridor density supports vendor-managed inventory models and on-site bulk storage installations, bypassing traditional service-station channels.
- Manufacturing Plants:Metalworking and food-processing facilities with equipment-specific lubrication programs. HACCP-aligned plants in the Sharon Plain offer regulatory-tailwind segments for NSF-registered suppliers, while waste-oil collection quotas compel reformulation toward extended-life chemistries.
- Automotive OEMs:Vehicle manufacturers specifying fill-for-life and warranty-aligned formulations.
- Repair Shops:Fragmented aftermarket service providers dependent on distributor delivery schedules.
Procurement consolidation favors fleet operators; technical specification intensity favors manufacturing plants.
Packaging Type:
Logistics infrastructure density and consumption scale determine packaging economics across Israel's geographic corridors.
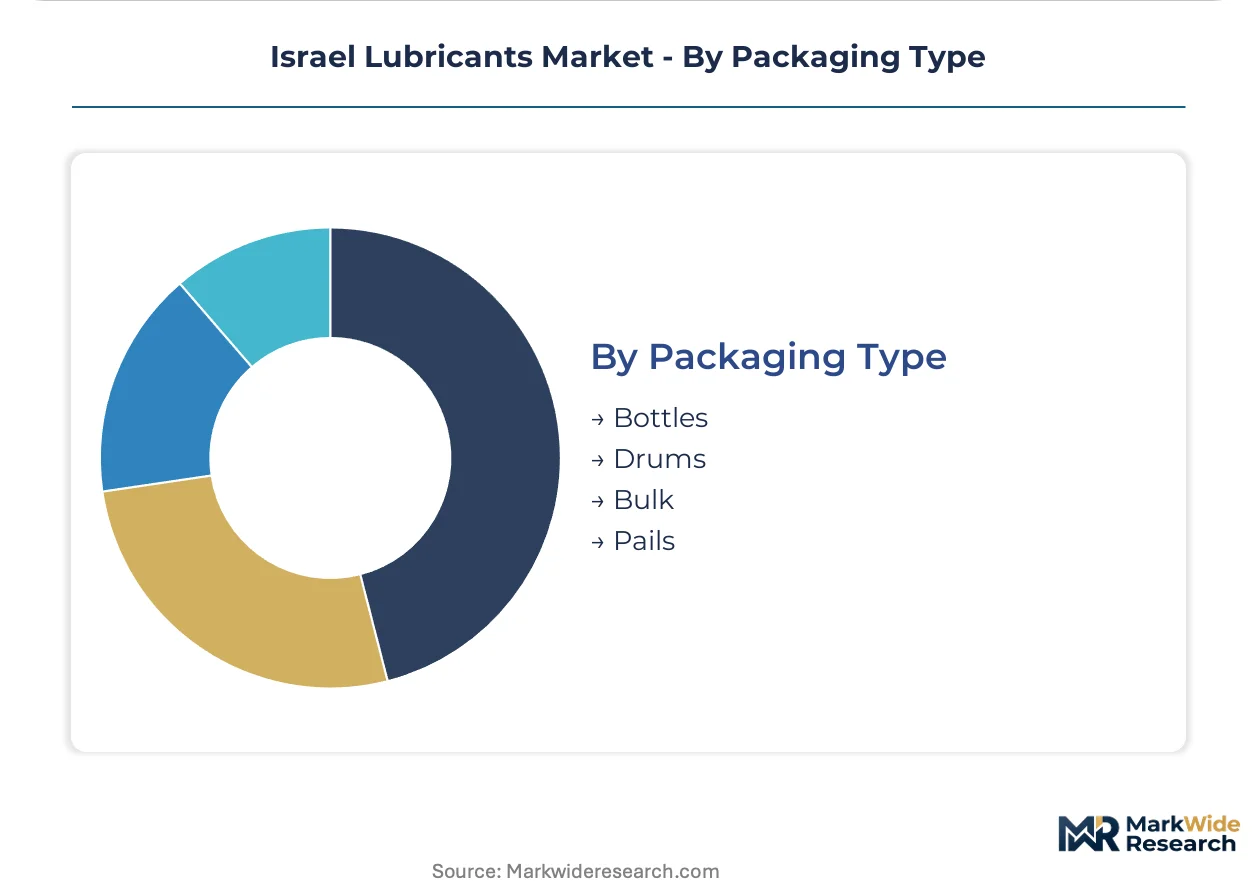
- Bulk:Tanker and tote deliveries to manufacturing plants and fleet depots with on-site storage infrastructure. Central District industrial clusters and Tel Aviv-Jerusalem corridor logistics density support this modality, displacing drum and pail volumes.
- Drums:200-liter steel containers for mid-volume industrial and fleet accounts without bulk storage capital.
- Pails:20-liter plastic containers for repair shops and small industrial accounts.
- Bottles:1-5 liter retail and service-fill packaging for aftermarket channels.
Cost efficiency favors bulk; geographic reach favors bottles in peripheral regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Environmental Protection anchors regulatory intensity across Israel's lubricants sector, with sub-regional demand patterns diverging sharply between industrial corridors and peripheral transit routes.
Tel Aviv-Jerusalem Corridor
Fleet density and automotive OEM procurement sustain the highest lubricant consumption volumes in Israel. The Ministry of Environmental Protection's waste-oil collection quotas compel local blenders toward extended-drain formulations. Centralized procurement by multi-site logistics operators is displacing traditional service-station channels through vendor-managed inventory installations.
Central District
Metalworking and food-processing plant modernization accelerates synthetic-grade conversion across manufacturing clusters. BIS-equivalent Israeli standards alignment with API specifications governs product qualification timelines. HACCP-aligned facilities in the Sharon Plain are driving NSF-registered lubricant adoption for compliance-sensitive production environments.
Ashdod Port Zone
Israel's base oil import dependency concentrates exposure at this Mediterranean terminal, where Paz LTD maintains backward integration into logistics infrastructure. Port congestion and shipping disruptions create supply volatility for domestic blenders. Marine lubrication demand from vessel traffic adds a secondary consumption layer distinct from automotive and industrial segments.
Negev-to-Galilee Transit Corridors
Sonol's service station network covers these peripheral routes where fleet operators face underserved premium lubricant infrastructure. The Beersheba-Eilat logistics spine exhibits lower distributor density than central regions. Mobile lubricant delivery services are capturing share from traditional brick-and-mortar channels in these corridors.
Haifa Industrial Belt
Petrochemical and refining adjacent industries generate specialized lubrication requirements distinct from general manufacturing. The concentration of heavy process equipment sustains demand for high-viscosity industrial grades. Local procurement patterns favor direct manufacturer relationships over distributor intermediaries due to volume scale and technical specification intensity.
Israel Lubricants Market Competitive Landscape
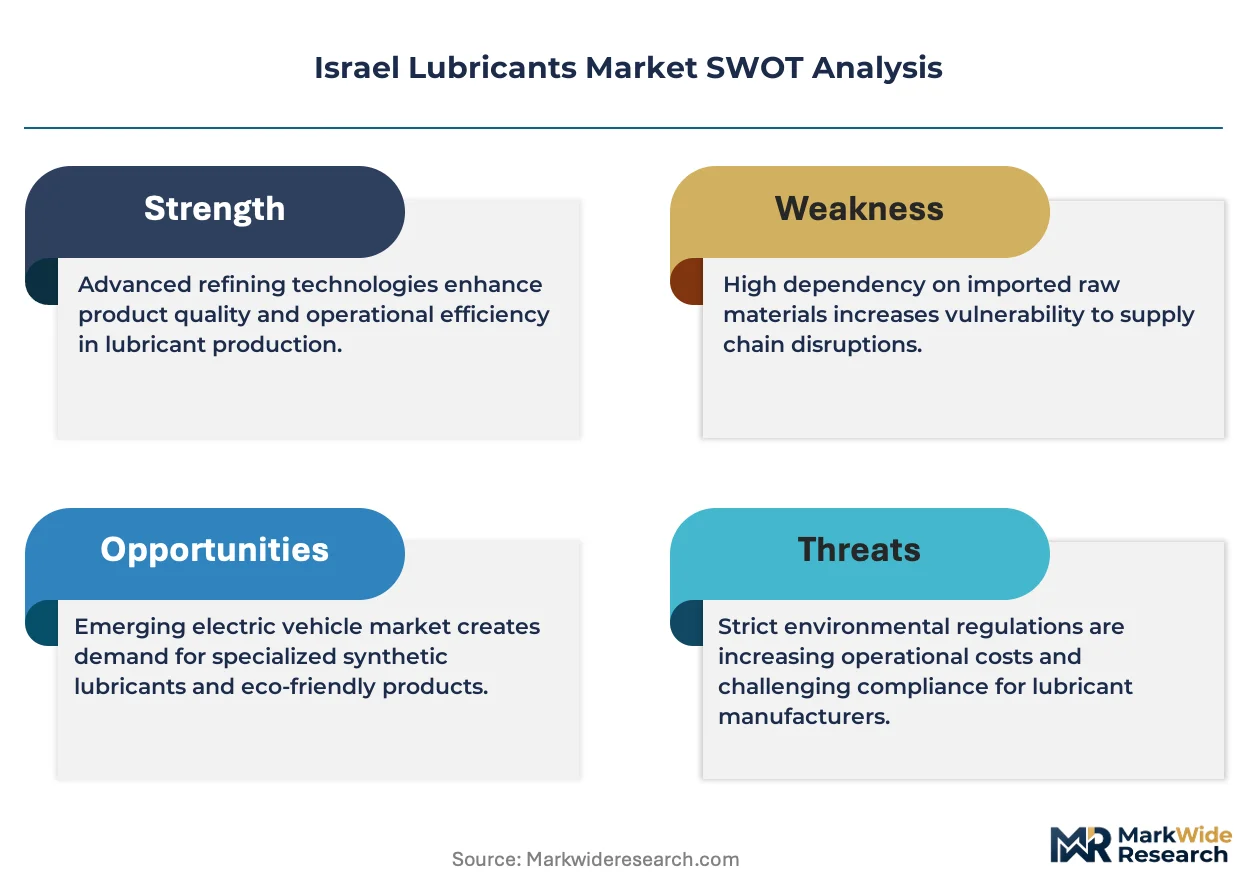
A small set of integrated leaders sits above a broader specialist tier in Israel's lubricants sector, with competitive boundaries redrawn by formulation chemistry capabilities and distribution infrastructure control. The market structure reflects global majors leveraging technical center networks against domestic blenders anchoring positions through port logistics and retail channel density. Three archetypes dominate: multinational integrated suppliers with R&D depth, domestic blenders with backward integration into base oil logistics, and retail-channel specialists covering geographic corridors. Competitive moves concentrate on additive package requalification to meet pending zinc and phosphorus content ceilings, and on bulk storage infrastructure deployment to capture fleet operator procurement consolidation.
Within the multinational tier, Shell PLC and Chevron Corporation exemplify integrated suppliers sustaining technical capabilities through global R&D networks. Among domestic operators, Paz LTD anchors its position through captive port logistics at Ashdod, while Sonol occupies the retail-channel specialist archetype with corridor coverage extending to peripheral regions. LIQUI MOLY GmbH represents the premium-formulation import segment serving specification-intensive automotive and industrial accounts. These three named entities—Shell PLC, Paz LTD, and Sonol—collectively illustrate how competitive positioning in Israel's lubricants market maps to control points in supply chain infrastructure, technical qualification depth, and geographic channel density.
| Leading Market Players |
|---|
| Shell PLC |
| Delkol |
| Paz LTD |
| Chevron Corporation |
| LIQUI MOLY GmbH |
| Sonol |
| ExxonMobil Corporation |
| TotalEnergies |
| BP PLC |
| Others |
Pricing and Supply Chain Analysis
Synthetic base stock substitution for Group I mineral oils is redrawing supply geography toward Mediterranean Group III and PAO import terminals while compressing price premiums between mineral and synthetic grades. This chemistry migration simultaneously concentrates blender procurement at Ashdod port logistics nodes and intensifies volume-based pricing leverage for fleet operators with centralized technical procurement functions.
Pricing Analysis
Price spreads between Tel Aviv-Jerusalem corridor fleet contracts and Negev peripheral retail channels reflect logistics density differentials rather than formulation quality gaps. Three-tier pricing structure across premium synthetic, standard hydrocracked, and economy mineral grades differentiates on API SP certification status and bulk delivery scale. Cost compression in the standard tier is intensifying because additive package redesigns for zinc/phosphorus compliance stretch qualification timelines. Fleet operators with vendor-managed inventory installations exhibit lowest price sensitivity; fragmented repair shops in Galilee transit corridors face highest cost pass-through exposure.
Supply Chain Analysis
Inventory strategy across Israeli blenders tilts toward just-in-time base oil stocking at Ashdod port tank farms rather than strategic stockpiles, exposing operations to Mediterranean shipping disruption. Supply draws from Belgium, Netherlands, and UAE Group III production hubs, with PAO and ester specialty stocks sourced from German and US Gulf Coast manufacturers. Raw material dependencies center on Group II/III base oils, zinc dialkyldithiophosphate anti-wear additives, and detergent-dispersant packages. Single-source vulnerability concentrates in Ashdod port congestion, where Paz LTD maintains captive berth access. Distribution runs through direct manufacturer agreements with fleet operators, bypassing traditional drum-and-pail distributor networks in high-density corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's lubricants sector demands substitution defense against extended-drain synthetic formulations that displace mineral-oil service-fill volumes and compress incumbent margin structures.
For Market Incumbents: Secure additive package requalification pipelines to meet Ministry of Environmental Protection zinc/phosphorus ceilings before competitor qualification cycles complete. Anchor backward integration into Ashdod port storage infrastructure to defend against Mediterranean shipping volatility that threatens just-in-time inventory models. Prioritize NSF-registered synthetic line extensions for Sharon Plain food-processing accounts where HACCP compliance creates specification stickiness against price competition. For New Entrants and Emerging Players: Anchor in Negev-to-Galilee transit corridor service infrastructure where Sonol's retail density leaves bulk delivery and mobile lubricant services underserved. Target Beersheba-Eilat fleet operators with on-site storage installations and vendor-managed inventory propositions that bypass established distributor relationships. Lead with re-refining joint venture proposals to European technology licensors, exploiting domestic waste-oil collection quota enforcement that outpaces local reprocessing capacity. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors blenders with captive port logistics and additive qualification depth over pure retail-channel specialists. Long-term viability over the coming decade hinges on reformulation capabilities for biodegradable and extended-drain chemistries rather than mineral-oil volume scale. Acquisition target archetype: domestic blenders with Ashdod storage assets and pending API SP product qualifications. Signal to watch: Ministry of Environmental Protection enforcement intensity on waste-oil recycling quotas as indicator of circular-economy infrastructure investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Port Storage | Paz LTD's captive Ashdod berth access insulates against Mediterranean shipping congestion that disrupts competitor inventory cycles. |
| Additive Package Requalification | Shell PLC's global technical center network accelerates Ministry of Environmental Protection compliance timelines versus domestic blender capacity constraints. |
| NSF-Registered Synthetic Line Launch | Food-processing plants in Sharon Plain require HACCP-aligned lubricants that command specification premiums over standard industrial grades. |
| Re-Refining Joint Venture | European technology licensors can exploit domestic waste-oil collection quota shortfalls through circular-economy infrastructure partnerships. |
| Mobile Lubricant Service Deployment | Fleet operators along Beersheba-Eilat corridor lack premium service infrastructure that centralized procurement models now demand. |
Research Methodology
A standing panel of lubricant formulation chemists, fleet procurement managers, Ministry of Environmental Protection compliance officers, and Ashdod port logistics coordinators provided ongoing calibration throughout the study period. Primary interviews with blend plant technical directors and industrial maintenance supervisors combined with secondary validation from Israeli customs trade records, Ministry of Environmental Protection enforcement disclosures, and API certification databases. Bottom-up volume builds across product type and application segments triangulated against top-down macroeconomic indicators and automotive fleet registration data.
Consistency checks against external benchmarks validated projection outputs against Mediterranean base oil import trends and regional lubricant consumption patterns. The analytical framework modeled segmentation across product chemistry tiers, end-use applications, procurement channel structures, and geographic consumption clusters throughout the forecast period. CAGRs derived from regression analysis of historical consumption trajectories, fleet age profile evolution, and industrial equipment modernization rates. Industry-specific inputs included Ministry of Environmental Protection regulatory timeline assumptions and synthetic-grade conversion elasticity in Central District manufacturing clusters.
Material uncertainties — regulatory enforcement intensity on zinc/phosphorus content limits, Mediterranean shipping disruption frequency, and certified formulation chemist labor market depth — sit outside the modeled envelope. Forecasts reflect assumptions about additive supplier qualification timelines and fleet operator procurement consolidation trajectories. Revision becomes warranted when Ministry of Environmental Protection enforcement crosses thresholds that accelerate waste-oil recycling infrastructure investment or compress blender margin structures beyond modeled sensitivity ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Synthetic Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Poland Lubricants Market
Lubricants
Power Steering Fluids Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Norway Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Drilling Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market