
 Synthetic Dyes Market | 2026-2036
Synthetic Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Dyes Market Outlook
The gap between premium high-fastness dyes and commodity sulfur grades is expanding as downstream buyers split procurement by performance tier. Huntsman Corporation leverages its integrated intermediates position to sustain margins in reactive dye lines. Archroma differentiates through specialty finishing chemistries that lock in color durability for athletic textiles. Zhejiang Longsheng Group anchors volume supply through captive production of dye intermediates in eastern China.
Synthetic dyes are organic or inorganic colorants synthesized from petroleum-derived aromatic hydrocarbons, typically formulated with defined tinctorial strength and specified light-fastness ratings for industrial substrate coloring. These compounds serve primarily to impart permanent, reproducible color to textiles, coatings, and plastics through selective absorption and fixation mechanisms. Azo dyes occupy the largest volume share across the analysis window due to their cost-efficient synthesis and broad substrate compatibility. Reactive dyes represent the fastest-expanding product category as textile manufacturers shift toward cellulosic and blended fiber portfolios requiring covalent bond formation. Powder formulations retain dominant share in bulk chemical trade, though liquid dispersions are gaining ground among paint producers seeking metered dosing efficiency.
REACH registration requirements in Europe, EPA effluent guidelines in the United States, and China's MEE discharge standards collectively restrict azo dye precursors and mandate wastewater treatment investments across manufacturing sites. India's Central Pollution Control Board enforcement of zero-liquid-discharge mandates in Gujarat and Tamil Nadu dye clusters is forcing capacity consolidation among smaller compounders. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging permissible substance lists and treatment cost structures.
Market Dynamics
REACH registration deadlines and India's zero-liquid-discharge mandates are compressing formulation choices while concentrating production among integrated intermediates producers capable of absorbing compliance costs.
Growth Catalysts
- Reactive dye chemistry:Textile mills in Bangladesh and Vietnam are expanding covalent-bond dye procurement for cellulosic-synthetic blends, replacing conventional direct dyes in knitwear processing.
- EU Green Deal chemistry restrictions:The bloc's tightening limits on aromatic amine releases are redirecting R&D budgets toward low-impact azo alternatives with certified biodegradation profiles.
- Gujarat chemical belt concentration:Integrated dye intermediate capacity along the Golden Corridor anchors regional supply security for South Asian textile exporters.
Market Restraints
- Petroleum-derived feedstock volatility:Naphtha and benzene price swings compress margins for commodity azo manufacturers lacking backward integration into aromatics.
- Effluent treatment capex burden:India's Central Pollution Control Board enforcement of membrane-based zero-liquid-discharge systems eliminates smaller compounders operating below 500-ton annual capacity.
- Natural dye substitution in premium apparel:Organic cotton certifiers and luxury fashion houses are specifying plant-derived colorants for capsule collections, capping synthetic penetration at the top price tier.
Strategic Opportunities
- Digital textile printing ink formulations:Reactive and acid dye dispersions optimized for piezoelectric printheads are capturing share in made-to-order apparel platforms across Turkey and Portugal.
- China's dual carbon goals:Provincial MEE discharge standards are accelerating consolidation, creating acquisition targets for multinational formulators with clean chemistry portfolios.
- Performance athletic wear finishing:Specialty dyes with built-in antimicrobial and moisture-wicking properties command price premiums in Southeast Asian sportswear export contracts.
Industry Challenges
- Colorimetric calibration expertise shortage:Formulation chemists capable of matching spectral data across substrate batches command compensation premiums that strain mid-tier dye houses.
- Legacy effluent infrastructure retrofit complexity:Tamil Nadu tannery-dye clusters face 18-24 month timelines to integrate anaerobic digesters with existing oxidation ponds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Dyes Market |
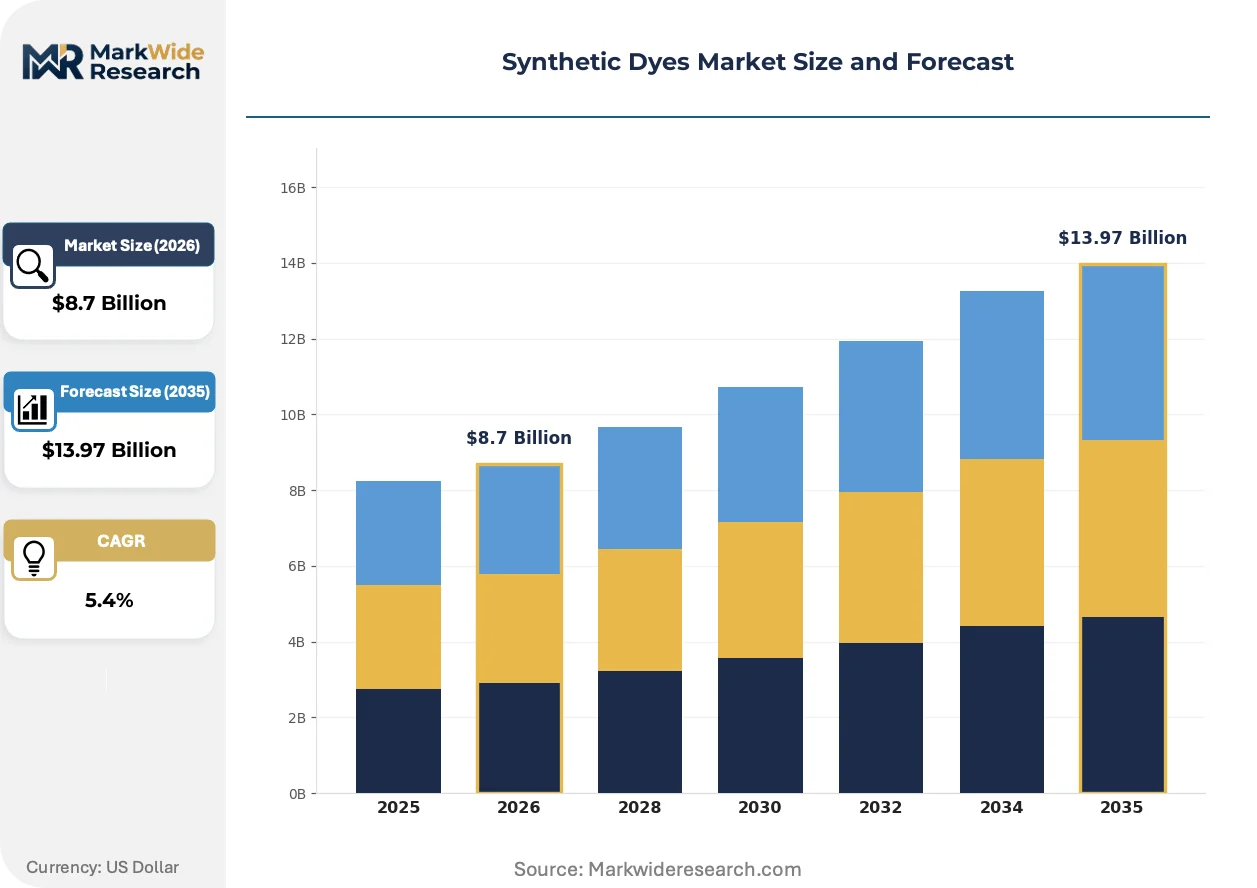
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azo Dyes, Anthraquinone Dyes, Reactive Dyes, Direct Dyes Application: Textiles, Coatings, Plastics, Paper Form: Liquid, Powder, Granular, Paste End User: Textile Manufacturers, Paint Producers, Plastic Processors, Ink Producers |
| Companies Covered | Huntsman Corporation, DIC Corporation, BASF SE, Atul Ltd, Zhejiang Longsheng Group Co. Ltd., Archroma, Clariant AG, Sun Chemical, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Dyes Market Strategic Shifts
Digital color matching platforms and closed-loop water systems are compressing batch-to-batch variation while redefining competitive advantage around sustainability verification rather than tinctorial strength alone.
Single-bath dyeing auxiliaries are unifying pretreatment, dyeing, and finishing stages into consolidated process sequences. Denim laundries in Mexico and Morocco are adopting these systems to cut water consumption by half. The technology is unifying previously fragmented chemical supplier relationships around full-process formulation partners capable of guaranteeing shade consistency.
REACH authorization requirements for chromium-based mordant dyes are forcing leather tanneries toward metal-free alternatives. The European Chemicals Agency's sunset date enforcement is accelerating reformulation timelines. Italian automotive upholstery suppliers are most affected, shifting procurement specifications to pre-certified dye lots before the 2026 deadline.
Brand-led chemical management protocols are displacing traditional distributor relationships. Major apparel retailers in Germany and the Netherlands are mandating ZDHC-compliant dye lots with blockchain-verified batch records. Tier-one fabric mills in Pakistan are responding by bypassing traders and contracting directly with audited formulators holding bluesign approval.
Synthetic Dyes Market Segmentation
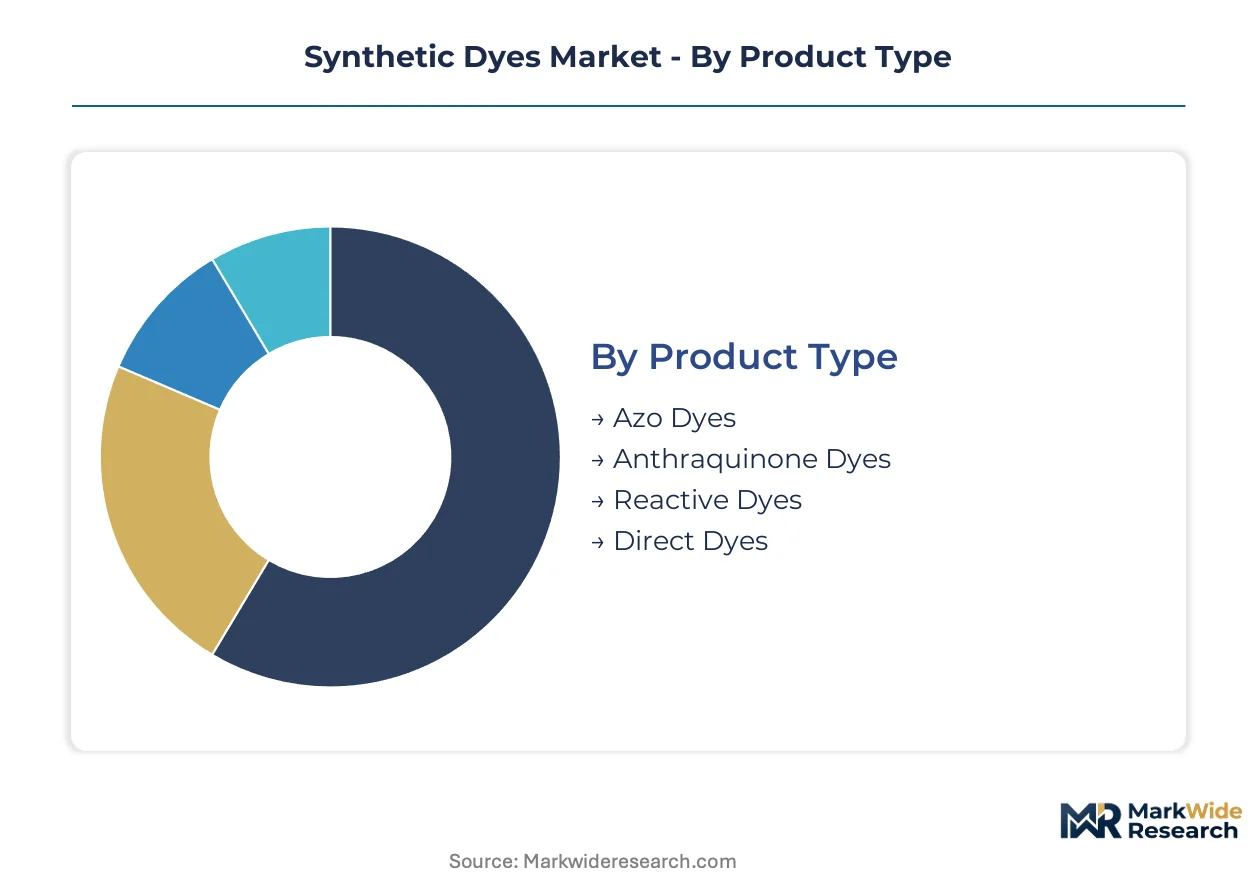
Segmentation in synthetic dyes reveals how capital allocation, regulatory exposure, and substrate compatibility split procurement budgets across industrial buyers. Formulation chemistries and physical delivery forms carry distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across synthesis routes, with multi-step aromatic substitution sequences demanding dedicated reactor trains and effluent handling systems.
- Azo Dyes:These nitrogen-double-bond chromophores dominate volume production through diazotization-coupling reactions using aniline derivatives. Textile mills in Bangladesh and Vietnam specify commodity azo grades for bulk cotton dyeing where light-fastness requirements remain moderate. REACH restrictions on aromatic amine precursors are forcing reformulation investments among European manufacturers.
- Reactive Dyes:Covalent bond formation with cellulosic hydroxyl groups delivers superior wash-fastness for blended fiber portfolios. Mills across Gujarat's chemical belt are expanding procurement of vinylsulfone and triazine-based reactive systems for synthetic-cotton knitwear exports to EU retailers.
- Anthraquinone Dyes:Carbonyl-centered chromophores provide high light-fastness for automotive upholstery and outdoor textiles. Synthesis requires expensive brominated intermediates that limit production to integrated aromatics producers.
- Direct Dyes:Water-soluble azo variants for uncomplicated cotton applications face displacement by reactive alternatives in quality-sensitive segments.
Azo dye capacity absorbs the bulk of installed chemical synthesis infrastructure; reactive dye volumes are expanding most quickly across South Asian textile clusters.
Application:
Substrate chemistry dictates fixation mechanisms and determines which dye classes penetrate each industrial segment.
- Textiles:Fiber-specific dyeing—cotton with reactives, wool with acids, synthetics with disperse systems—consumes the majority of formulated output. Integrated mills in Tamil Nadu and Pakistan's Faisalabad cluster are consolidating chemical procurement around full-process suppliers capable of guaranteeing shade consistency across batch runs.
- Plastics:High-temperature stable solvent dyes for polyethylene terephthalate and polyamide masterbatch production require specialized thermal stability testing. Automotive interior specifications from German OEMs are tightening migration resistance standards.
- Coatings:Pigment dispersions for architectural and industrial paints prioritize opacity and weathering resistance over substrate reactivity.
- Paper:Basic dyes for tissue and packaging grades operate on thin margins with minimal technical service requirements.
Textile applications command the deepest technical engagement; plastics dyeing is climbing the fastest as automotive lightweighting expands polymer content.
Form:
Physical state determines logistics costs, dosing precision, and dust exposure compliance across manufacturing environments.
- Powder:Dry formulations retain dominant share in bulk chemical trade, particularly for azo and direct dye shipments to South Asian compounders. Dust containment systems and respiratory protection protocols add operational overhead.
- Liquid:Pumpable dispersions eliminate dust hazards and enable metered dosing for automated textile dyeing ranges. Paint producers in Turkey and Portugal are specifying liquid reactive and acid dye concentrates for digital textile printing ink formulations.
- Granular:Low-dust free-flowing particles bridge handling convenience with concentrated tinctorial strength for mid-tier dye houses.
- Paste:High-solid dispersions for specific printing applications where viscosity control is critical.
Powder forms retain the largest installed packaging and handling infrastructure; liquid dispersions are gaining share fastest among automated processing lines.
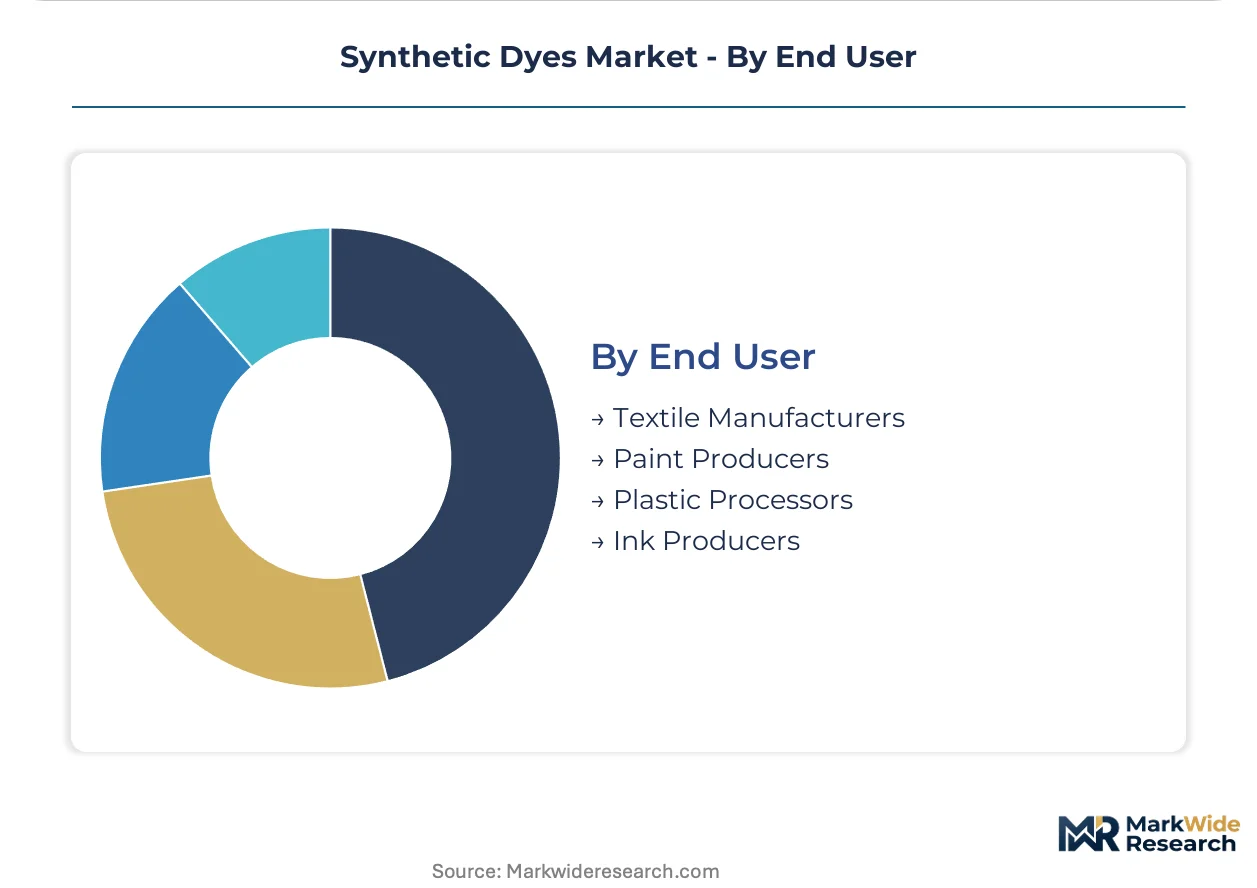
End User:
Buyer sophistication and specification power fragment the customer base across formulation service requirements and compliance documentation demands.
- Textile Manufacturers:Fabric mills and garment processors drive reactive dye specification with ZDHC-compliant chemistry mandates from German and Dutch retailers. Direct contracting with audited formulators is displacing traditional distributor relationships in Pakistan's tier-one supply base.
- Paint Producers:Coating formulators prioritize colorimetric consistency and weathering data over fixation chemistry, sourcing pigment dispersions from specialized color houses.
- Plastic Processors:Compounders and masterbatch producers require thermal stability certification and migration testing for automotive and food-contact applications.
- Ink Producers:Narrow-format digital printing specialists demand sub-micron particle dispersions compatible with piezoelectric printhead tolerances.
Textile manufacturers absorb the majority of technical sales resources; ink producers for digital textile printing represent the steepest expansion trajectory in customer category development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's chemical belt along the Golden Corridor anchors global synthetic dye supply, with integrated intermediates capacity feeding textile clusters across South Asia and export markets.
China
Zhejiang province drives reactive dye output for cellulosic fiber blends, with provincial MEE discharge standards forcing consolidation among smaller compounders. The country's dual carbon goals accelerate capacity rationalization in eastern manufacturing zones. Yangtze River Delta dye houses are absorbing compliance costs through captive intermediates production.
India
Gujarat's Ankleshwar-Vapi corridor concentrates azo and reactive dye formulation for Bangladesh and Vietnam textile mills. Central Pollution Control Board zero-liquid-discharge mandates eliminate sub-500-ton compounders. Tamil Nadu's Tiruppur cluster retrofits effluent infrastructure for knitwear export compliance.
Germany
Specialty anthraquinone production serves automotive upholstery specifications from Stuttgart and Munich OEMs. REACH authorization deadlines for chromium-based mordants force leather tanneries toward metal-free alternatives. Baden-Württemberg chemical parks host reformulation R&D for low-impact azo alternatives.
United States
EPA effluent guidelines restrict aromatic amine precursors in Georgia and North Carolina textile processing. Digital textile printing ink demand concentrates in North Carolina's Research Triangle for piezoelectric dispersion development. Automotive lightweighting expands polymer dye procurement from Detroit-area masterbatch compounders.
Bangladesh
Dhaka-Chittagong apparel exporters specify reactive dye systems for EU retailer ZDHC compliance. German and Dutch brand chemical management protocols displace traditional distributor relationships. Local mills bypass traders to contract directly with audited formulators holding bluesign approval.
Synthetic Dyes Market Competitive Environment
Premium-margin players sit above commodity-margin players across intermediates integration and sustainability certification dimensions. The vendor base splits between integrated aromatics producers absorbing regulatory costs and fragmented compounders facing capacity elimination. Three archetypes dominate: backward-integrated intermediates specialists, full-process formulation partners, and digital printing dispersion developers. Consolidation accelerates through acquisition of distressed assets in China's eastern provinces and strategic partnerships for blockchain-verified batch tracking.
Among diversified chemical conglomerates, BASF SE and Clariant AG occupy positions spanning specialty and commodity tiers, while Huntsman Corporation exemplifies intermediates-integrated reactive dye supply. Zhejiang Longsheng Group Co. Ltd. represents the scale-driven archetype through captive eastern China production bases.
| Leading Market Players |
|---|
| Huntsman Corporation |
| DIC Corporation |
| BASF SE |
| Atul Ltd |
| Zhejiang Longsheng Group Co. Ltd. |
| Archroma |
| Clariant AG |
| Sun Chemical |
| Lanxess AG |
| Others |
Value Chain & Pricing Dynamics
Naphtha and benzene feedstock costs cascade through three distinct pricing tiers as integrated aromatics producers in Gujarat and Zhejiang capture margin premiums unavailable to fragmented compounders. Petroleum-derived input volatility compresses commodity azo margins while reactive dye specialists with captive intermediate supply defend price positioning.
Pricing Analysis
Wash-fastness performance and ZDHC certification grade anchor value-based pricing for reactive dye portfolios. Three-tier pricing structure across premium, standard, and economy levels separates bluesign-approved formulations from REACH-compliant grades and unregistered commodity batches. Pricing pressure stems from Bangladeshi mills consolidating procurement around direct-audited supplier contracts. Small compounders below 500-ton annual capacity exhibit highest price sensitivity; automotive upholstery specifiers show lowest.
Supply Chain Analysis
Aniline and nitrobenzene intermediate supply rests on integrated producers along China's Yangtze River Delta and India's Golden Corridor. Captive naphtha cracking, brominated anthraquinone precursors, and vinylsulfone reactive systems constitute critical input dependencies. Single-source vulnerability concentrates in European specialty anthraquinone supply for automotive applications. Distribution runs through direct mill contracts displacing traditional trader networks in Pakistan and Bangladesh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's Central Pollution Control Board zero-liquid-discharge mandates erect capital barriers that eliminate sub-scale competitors and entrench integrated formulators with membrane-based treatment infrastructure.
For Market Incumbents: Deepen backward integration into dye intermediates to absorb REACH and MEE compliance costs without margin erosion. Expand reactive dye capacity in Gujarat's chemical belt to serve Bangladeshi ZDHC-compliant procurement consolidation. Prioritize blockchain-verified batch tracking partnerships with German retailers seeking supply chain transparency. For New Entrants and Emerging Players: Enter via digital textile printing ink formulations for Turkey and Portugal's made-to-order apparel platforms, where sub-micron dispersion expertise commands premium positioning. Target specialty finishing chemistries for Southeast Asian sportswear exports requiring antimicrobial and moisture-wicking properties. Pursue direct contracting relationships with tier-one Pakistani mills bypassing traditional dye traders. For Investors and Strategic Acquirers: Provincial MEE discharge standard enforcement in China's eastern provinces is the leading indicator that consolidation-acquisition windows are opening for clean-chemistry portfolios. Five-to-ten-year viability favors integrated intermediates producers with audited effluent systems over fragmented commodity compounders. Watch for distressed asset listings among sub-500-ton Chinese compounders facing dual carbon goal compliance deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Intermediates | Captive naphtha and aniline supply insulates Huntsman and Longsheng from petroleum volatility. |
| Zero-Liquid-Discharge Infrastructure Investment | Membrane-based treatment systems enable Gujarat compounders to retain CPCB operating licenses. |
| Bluesign and ZDHC Certification Acquisition | Pre-certified dye lots unlock direct contracting with German and Dutch apparel retailers. |
| Digital Textile Printing Dispersion Development | Piezoelectric-compatible reactive inks capture share in Turkey's made-to-order apparel sector. |
| Specialty Finishing Chemistry Partnerships | Antimicrobial dye systems command price premiums in Southeast Asian sportswear export contracts. |
Study Parameters
SEC 10-K filings, customs and trade databases, and Cefic industry reports formed the secondary backbone, cross-referenced with primary interviews across plant managers at integrated dye houses, procurement leads at Bangladeshi textile mills, distribution channel partners in Pakistan, and technical R&D directors at specialty formulators. Bottom-up and top-down triangulation validated volume estimates against disclosed capacity figures and regional production cluster output.
Bottom-up modeling anchored forecasts to disclosed reactor train capacities and utilization rates across Gujarat, Zhejiang, and Tamil Nadu production hubs, while top-down cross-checks applied end-use consumption coefficients from textile, coating, and plastics applications. Segmentation dimensions included dye chemistry class, physical delivery form, substrate application, and regional regulatory cluster. CAGRs derived from capacity expansion announcements and substitution elasticity between reactive and direct dye systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petroleum feedstock price shocks or accelerated EU aromatic amine restriction timelines. Projections reflect assumptions regarding MEE enforcement consistency and ZDHC adoption velocity among tier-one apparel retailers. A small set of named triggers—provincial discharge standard acceleration, REACH sunset date revisions, and digital printing penetration rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Global Pigments Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Phthalocyanine Pigments Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Global Cosmetic Dyes Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
White Pigment Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Pigment Dispersions Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market