
 South Korea Automotive Lubricants Market | 2026-2036
South Korea Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Lubricants Market Analytics
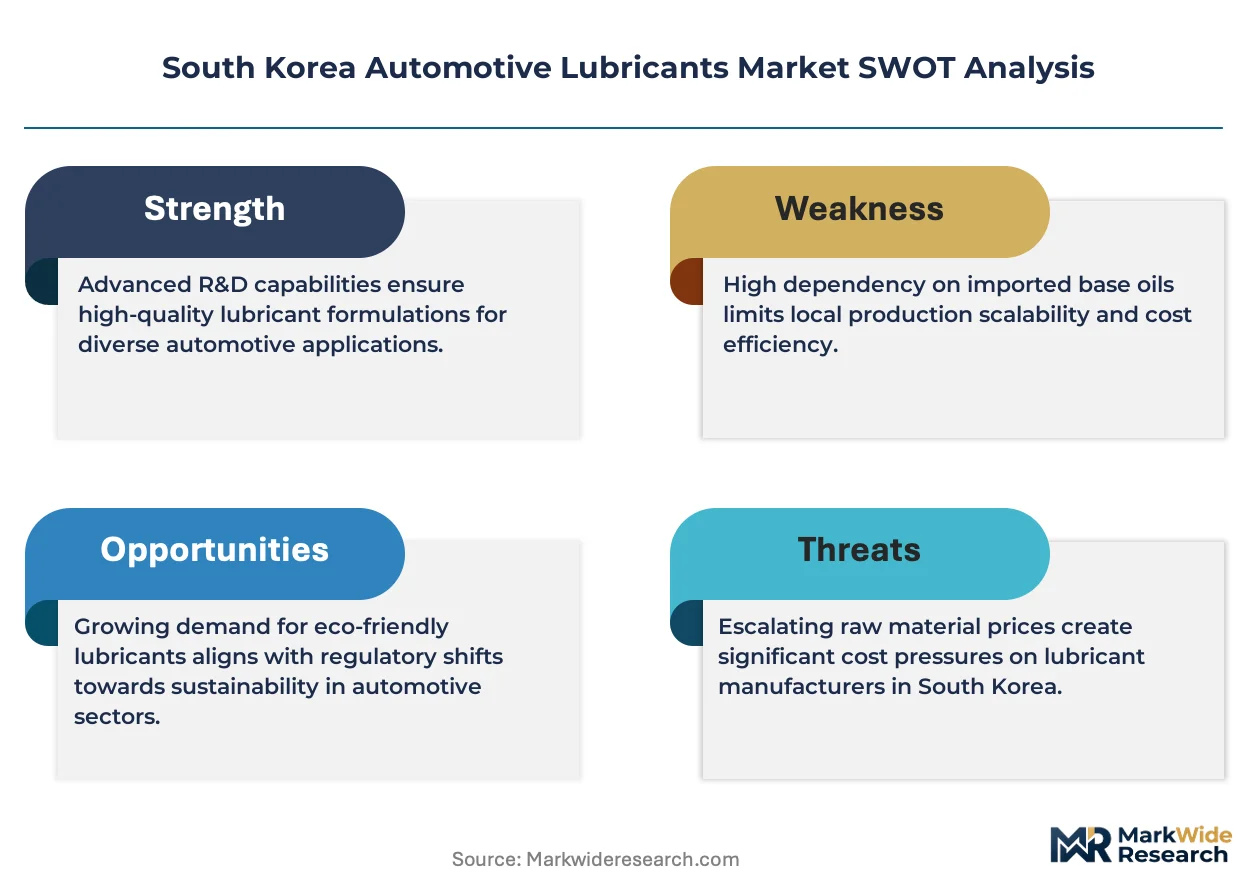
Electrification-compatible lubricant formulations is reconfiguring product development priorities across South Korea's automotive supply base. SK Innovation anchors domestic base oil production through integrated refining complexes in Ulsan. Hyundai Oilbank leverages captive petrochemical infrastructure to supply OEM fill programs. GS Caltex competes in premium synthetic segments through differentiated Group III+ capacity.
Automotive lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear in powertrain components; viscosity grades such as SAE 0W-20 and 5W-30 dominate modern Korean passenger car specifications, with total base number retention determining drain interval extension. Engine oil occupies the largest value pool given fleet-wide consumption volumes, while transmission fluid generates higher per-liter margins amid precision dual-clutch and CVT requirements. Heavy-duty vehicles sustain grease demand through chassis and wheel bearing applications despite electrification headwinds in lighter segments.
MFDS chemical safety assessments and K-REACH registration obligations constrain imported additive packages, compelling reformulation around domestically approved chemistries. South Korea's alignment with ISO 6743 lubricant classification standards shapes OEM specification harmonization, while the country's national emissions regulator enforces fuel economy credits that indirectly tighten lubricant viscosity targets. Stakeholders must monitor EV penetration rates and hybrid architecture ratios to calibrate portfolio transitions between internal combustion formulations and thermal management fluids.
Market Dynamics
Electrification of South Korea's passenger vehicle fleet is fragmenting traditional engine oil demand while simultaneously creating parallel requirements for battery thermal management fluids and e-axle greases. This bifurcation is forcing reformulation investments across the domestic supply base.
Growth Catalysts
- Commercial fleet synthetic conversion:Logistics operators serving Busan port corridors are mandating extended-drain synthetic grades to reduce vehicle downtime and maintenance labor costs.
- K-REACH compliance localization:Domestic additive registration requirements are incentivizing Korean blenders to develop approved chemistry packages, reducing import dependency for critical friction modifiers.
- Hyundai-Kia captive demand:OEM fill specifications for turbocharged GDI engines are tightening viscosity grade requirements, pulling premium lubricant volumes through authorized service networks.
Market Restraints
- Group II base oil margin compression:Refinery overcapacity across Northeast Asia is depressing spot prices for conventional base stocks, squeezing blender profitability on mineral formulations.
- EV penetration trajectory uncertainty:Inconsistent government subsidy levels for battery electric vehicles are complicating long-term volume planning for combustion-engine lubricant portfolios.
- Additive import concentration:Specialty chemical packages for anti-wear and detergent functions remain concentrated among non-Korean suppliers, exposing blenders to currency and tariff volatility.
Strategic Opportunities
- Sejong smart city mobility trials:Autonomous shuttle fleets operating in the administrative capital are specifying novel lubrication intervals that favor condition-monitoring service models over fixed schedules.
- Heat pump fluid cross-application:Thermal management chemistries developed for EV batteries are finding secondary demand in residential HVAC systems, opening adjacent revenue pools.
- Carbon border adjustment readiness:EU CBAM preparatory requirements are prompting Korean exporters to document lubricant lifecycle emissions, creating first-mover positioning for low-carbon formulation certifications.
Industry Challenges
- Tribology-specialist scarcity:Korean universities are producing insufficient graduates with expertise in friction chemistry and lubricant rheology to staff expanding R&D programs.
- Dual chemistry platform management:Blenders must simultaneously maintain legacy combustion formulations and build thermal fluid capabilities without duplicating fixed asset bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Lubricants Market |
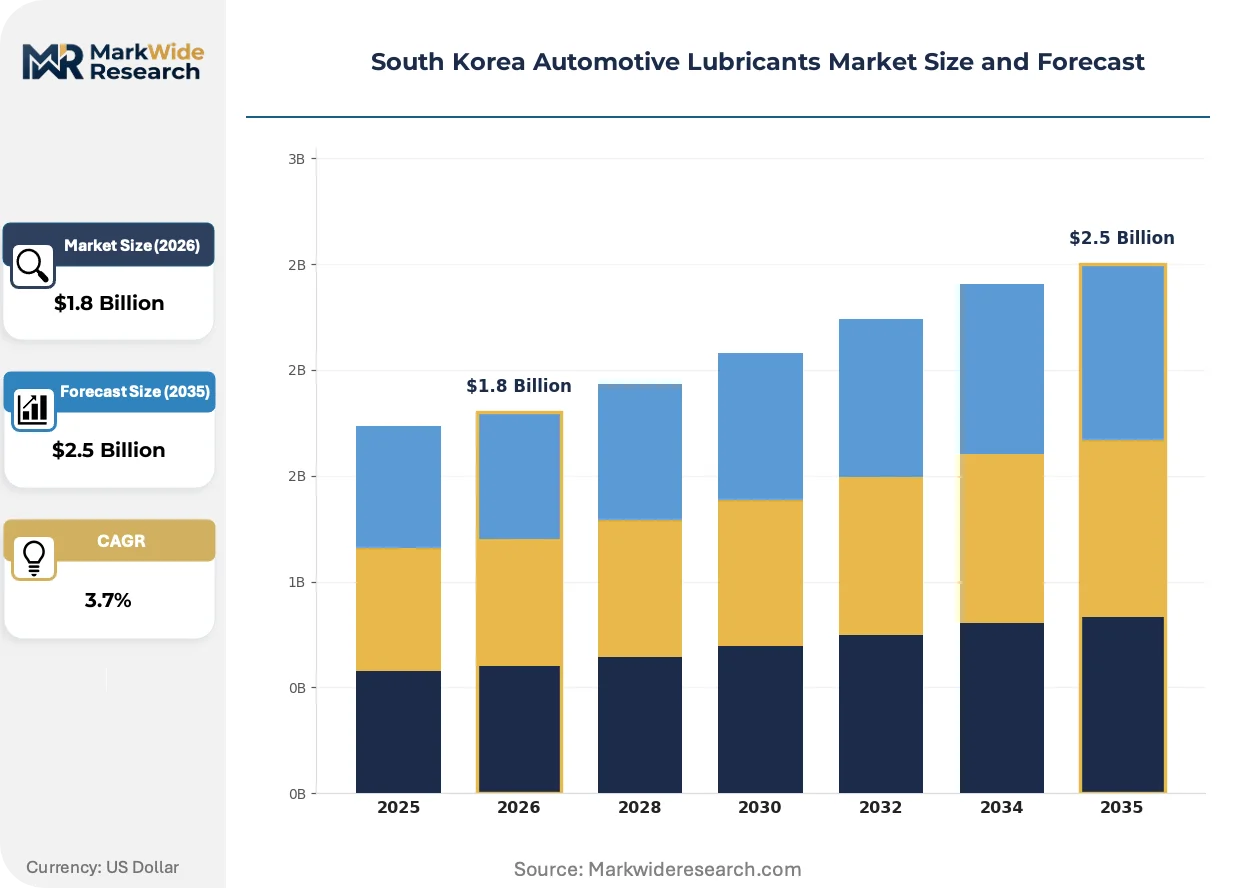
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Motorcycles Distribution Channel: Retail Stores, Online Platforms, Service Stations, Wholesalers End User: Fleet Operators, Individual Users, OEMs, Aftermarket Providers |
| Companies Covered | Hyundai Oilbank, BP (Castrol), SK Innovation, FUCHS, Royal Dutch Shell, S-Oil Corporation, ExxonMobil Corporation, Motul, GS Caltex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Lubricants Market Evolving Landscape
Formulation science is pivoting from friction reduction toward thermal conductivity optimization as powertrain architectures diversify. This reorientation is reshaping additive priorities, base oil selection criteria, and the technical specifications that define product-market fit.
Polyalkylene glycol-based thermal fluids are rendering obsolete conventional glycol-water mixtures in battery pack cooling circuits. Korean EV manufacturers are specifying these chemistries for their superior dielectric properties and temperature stability. The transition is compressing demand for traditional antifreeze formulations while expanding the addressable market for specialty synthetic base stocks.
MFDS chemical safety assessments are tightening notification requirements for lubricant additives containing novel molecular structures. Korean blenders are responding by pre-registering alternative chemistries through domestic toxicology partnerships. The regulatory friction most affects imported additive packages, accelerating localization of friction modifier and antioxidant supply chains.
Fleet maintenance departments are unbundling lubricant procurement from authorized dealer service contracts, establishing direct supply relationships with blenders for bulk deliveries. Independent quick-lube chains in Seoul-Incheon corridors are capturing this volume through consignment inventory arrangements. The disintermediation is most pronounced among express delivery operators managing thousand-vehicle diesel fleets.
South Korea Automotive Lubricants Market Segmentation
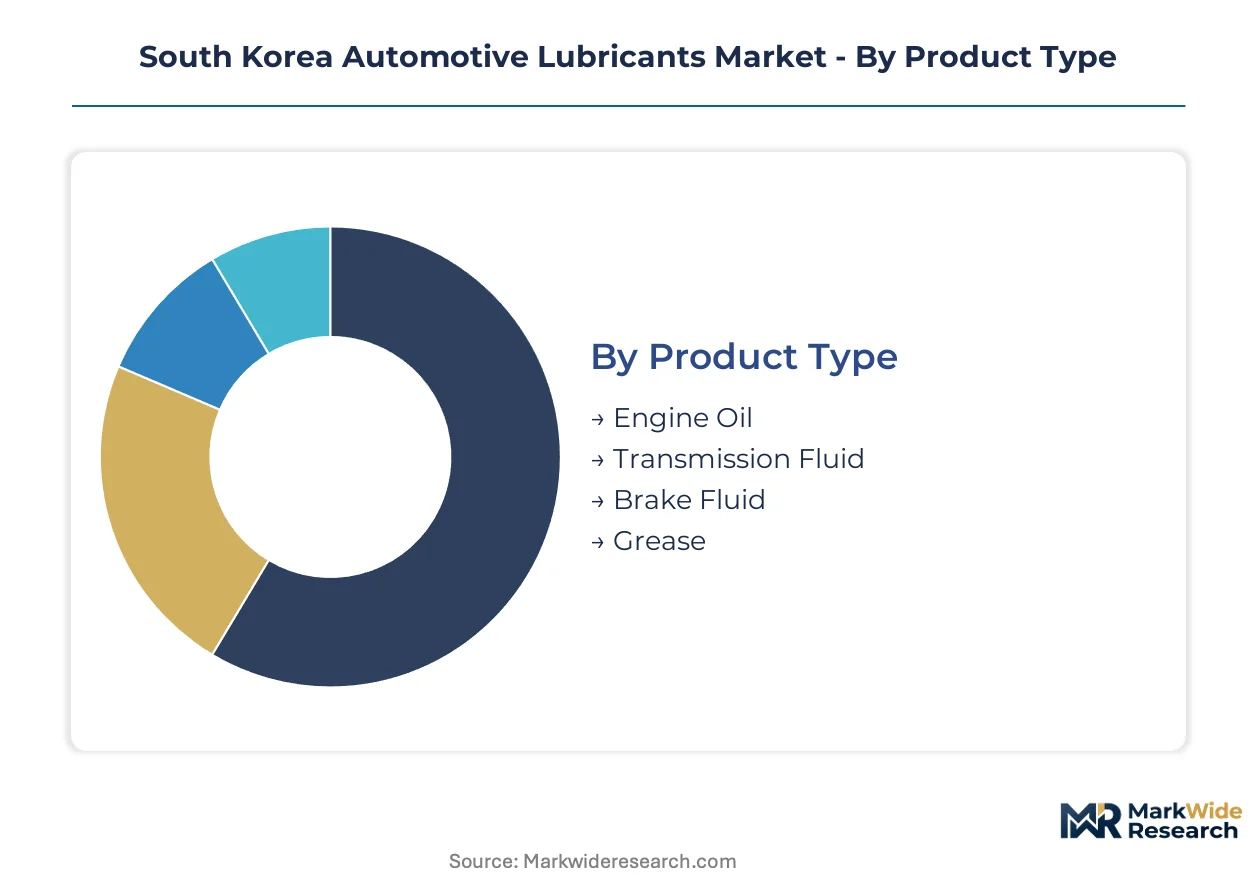
Segmentation reveals how electrification and fleet modernization are fragmenting traditional lubricant demand pools across South Korea's automotive value chain. Product specifications now diverge sharply between combustion-engine heritage formulations and emerging thermal management chemistries.
Product Type:
Mature mineral-based formulations coexist with emerging synthetic and specialty thermal fluid categories, reflecting the powertrain transition underway in Korean vehicle manufacturing.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages, these lubricants reduce friction in crankshaft and camshaft assemblies. Demand concentrates in Seoul-Incheon service corridors serving aging gasoline fleets, though EV penetration is compressing volume growth in passenger car segments.
- Transmission Fluid:Precision-blended synthetic formulations meeting dual-clutch and CVT specifications generate premium margins through OEM fill programs. Hyundai-Kia's eight-speed automatic transmission ramp-up in Asan and Gwangju plants is pulling specialized low-viscosity ATF volumes through captive supply agreements.
- Brake Fluid:Glycol-ether based hydraulic media with high boiling point specifications for ABS and ESP systems.
- Grease:Lithium-complex and polyurea-thickened lubricants for chassis, wheel bearings, and CV joints in commercial applications.
Engine Oil retains volume leadership; Transmission Fluid holds the steepest expansion curve.
Application:
Customer archetypes span individual owners, centralized fleet procurement departments, and OEM captive demand, each imposing distinct formulation and packaging requirements.
- Passenger Vehicles:Light-duty gasoline and diesel cars dominate consumption of SAE 0W-20 and 5W-30 grades. Seoul metropolitan area dealerships are the primary channel, though direct-to-consumer online sales are eroding traditional service network capture.
- Commercial Vehicles:Express delivery and logistics fleets operating Busan port corridors specify extended-drain synthetic grades to minimize downtime. CJ Logistics and Hanjin Transportation have centralized lubricant procurement away from dealer networks toward direct blender relationships.
- Heavy-Duty Vehicles:Construction equipment and long-haul trucks sustain high-TBN diesel engine oil demand.
- Motorcycles:Two-stroke and four-stroke formulations for domestic commuter and recreational segments.
Passenger Vehicles anchor current revenue; Commercial Vehicles are climbing the fastest as fleet operators consolidate procurement.
Distribution Channel:
Channel economics reflect inventory velocity, technical service requirements, and the disintermediation pressure from bulk fleet purchasing.
- Retail Stores:Home improvement chains and automotive specialty retailers stock DIY-grade mineral oils and synthetic blends. E-Mart and Lotte Mart hypermarkets in Gyeonggi Province capture weekend maintenance shoppers seeking convenience.
- Online Platforms:Coupang and Naver Smart Store are capturing individual user demand through next-day delivery of packaged lubricants. The channel bypasses traditional technical consultation, requiring blenders to embed specification guidance in product listings.
- Service Stations:SK Energy and GS Caltex forecourt locations provide emergency top-up and basic oil change services.
- Wholesalers:Regional distributors supply independent garages and quick-lube chains with bulk drum and tote deliveries.
Service Stations retain the broadest geographic footprint; Online Platforms are gaining share fastest among younger vehicle owners.
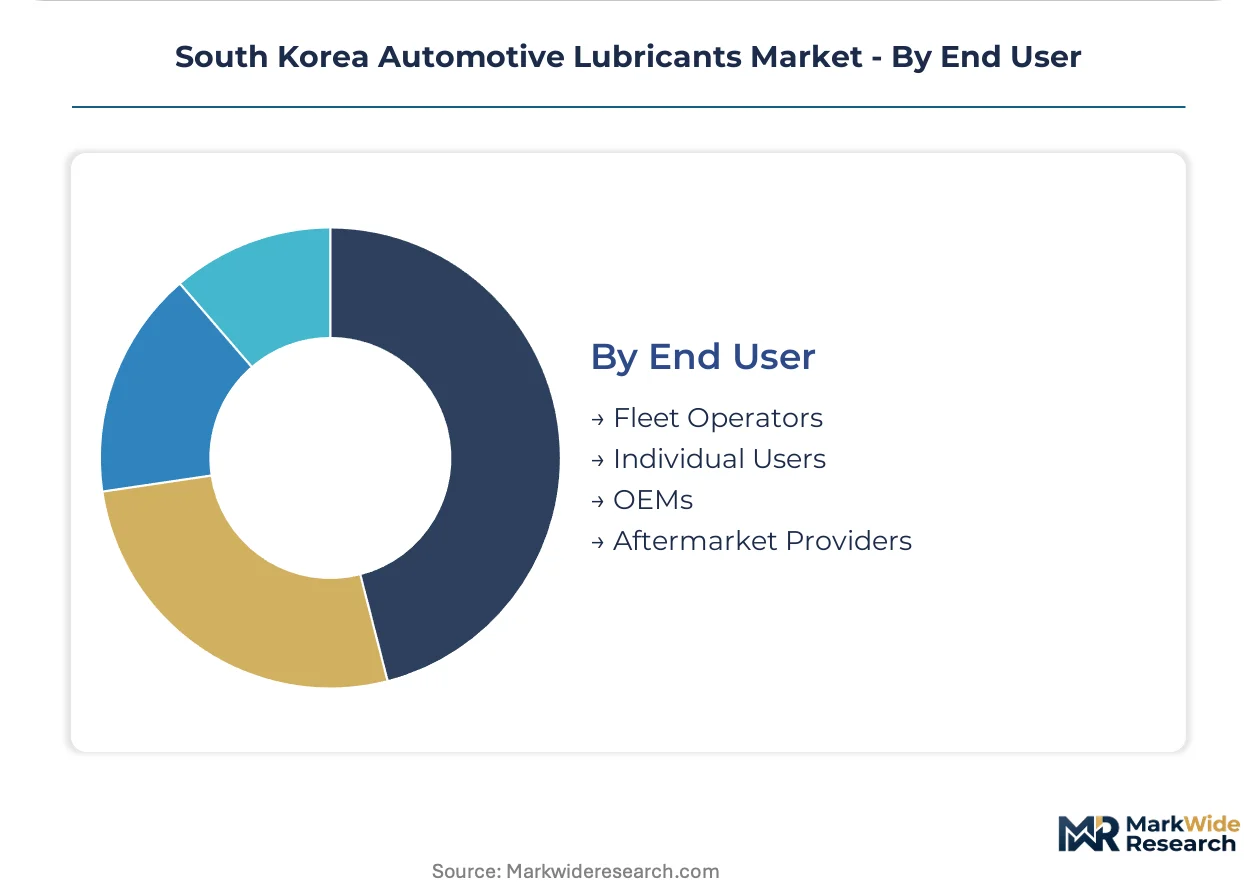
End User:
Procurement sophistication varies dramatically across user types, from specification-driven OEM technical centers to price-sensitive individual maintainers.
- Fleet Operators:Centralized procurement departments at logistics and rental companies negotiate annual volume contracts with blenders. Kia Motors' Moheom rental subsidiary and Lotte Rental have implemented telematics-linked condition monitoring to optimize drain intervals.
- Individual Users:Owner-maintainers purchasing through retail or online channels, often deferring to vehicle manufacturer recommendations without independent technical assessment.
- OEMs:Hyundai Motor Company and Kia Corporation specify factory-fill lubricants for new vehicle production at Asan, Hwaseong, and Gwangju assembly plants.
- Aftermarket Providers:Independent service chains and franchise quick-lube operators purchasing through wholesale distribution.
Fleet Operators command the most favorable pricing through volume consolidation; OEMs maintain the strictest formulation and certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and OEM technical centers concentrate lubricant procurement in manufacturing corridors and port logistics clusters, with regulatory compliance requirements varying sharply across sub-regional industrial bases.
Seoul Capital Area
Passenger vehicle service networks and express delivery fleets drive synthetic lubricant consumption across Gyeonggi Province and Incheon. MFDS chemical safety assessments constrain additive formulations used in metropolitan maintenance facilities. Pangyo Techno Valley hosts lubricant R&D centers developing K-REACH-compliant chemistry packages for domestic blenders.
Busan-Ulsan
Commercial vehicle fleets serving Korea's largest port mandate extended-drain synthetic grades to minimize cargo handling downtime. The national emissions regulator enforces fuel economy credits that tighten lubricant viscosity specifications for heavy-duty diesel engines. Ulsan refining complexes anchor domestic base oil production through integrated petrochemical infrastructure.
Daegu-Gyeongbuk
Automotive component manufacturing clusters generate captive demand for metalworking fluids and machinery lubricants. K-REACH registration obligations for imported additives compel local reformulation around domestically approved friction modifiers. Gumi industrial parks concentrate precision machining operations requiring high-performance cutting fluid specifications.
Daejeon-Sejong
Government fleet procurement and autonomous mobility trials create novel lubrication service models favoring condition monitoring over fixed intervals. The Sejong administrative capital hosts smart city pilot programs specifying predictive maintenance protocols for shuttle fleets. Public sector vehicle pools negotiate centralized supply contracts bypassing traditional dealer networks.
Gwangju-Honam
Hyundai-Kia assembly operations at the Gwangju plant pull specialized transmission fluid volumes through captive supply agreements. Regional agricultural equipment fleets sustain grease demand for chassis and hydraulic applications. Honam petrochemical infrastructure supports downstream lubricant blending capacity serving southwestern distribution corridors.
South Korea Automotive Lubricants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around refinery-integrated blenders and international additive technology licensors. Domestic conglomerate-affiliated lubricant divisions leverage captive base oil supply and OEM fill relationships. Strategic archetypes divide between integrated petrochemical producers, international brand licensors, and specialty synthetic formulators. Competitive moves center on K-REACH compliance localization and thermal fluid portfolio expansion for electrified powertrains.
Among integrated domestic producers, SK Innovation and GS Caltex exemplify the refinery-anchored archetype leveraging Ulsan and Yeosu petrochemical infrastructure for base oil supply security. Hyundai Oilbank occupies a position within the captive OEM demand tier, drawing on refinery integration to serve factory-fill programs. BP (Castrol) and Royal Dutch Shell represent the international brand licensing model, importing additive technology packages subject to domestic chemical registration requirements. These groupings illustrate how competitive positioning fragments across supply chain control points, regulatory compliance capabilities, and powertrain transition readiness.
| Leading Market Players |
|---|
| Hyundai Oilbank |
| BP (Castrol) |
| SK Innovation |
| FUCHS |
| Royal Dutch Shell |
| S-Oil Corporation |
| ExxonMobil Corporation |
| Motul |
| GS Caltex |
| Others |
Value Network & Pricing Analysis
Refinery overcapacity across Northeast Asia is compressing Group II base oil spot prices and forcing Korean blenders into defensive pricing postures. This utilization imbalance simultaneously erodes mineral formulation margins and accelerates synthetic grade conversion as suppliers chase premium positioning.
Pricing Analysis
Cost-plus contracts indexed to Singapore Group II/III base oil quotations dominate blender-OEM supply agreements. Pricing stratifies across premium synthetic, mid-tier synthetic blend, and economy mineral tiers, with volume scale and K-REACH certification grade as primary differentiation levers. Cost compression in economy mineral segments is intensifying because Northeast Asian refinery expansions have outpaced regional demand growth. Fleet operators consolidating thousand-vehicle procurement contracts exhibit highest price sensitivity, while OEM technical centers maintain lowest sensitivity due to specification-lock-in.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard in blender-distributor relationships, with GS Caltex and SK Innovation offering supply-chain finance facilities to secure channel loyalty. Base oil supply concentrates in South Korea, Japan, and Singapore, with additive packages drawing from Germany, the United States, and Japan. Single-source vulnerability for specialty friction modifiers and detergent chemistries exposes blenders to currency volatility. Distribution runs through refinery-integrated bulk terminals, regional wholesalers, and consignment arrangements at quick-lube chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation is shifting buyer power toward centralized technical departments and away from fragmented dealer networks. CJ Logistics and Hanjin Transportation now negotiate direct annual volume contracts, compressing intermediary margins.
For Market Incumbents: Build formulation moats around K-REACH pre-registered additive packages to lock out import-dependent competitors. Deepen captive base oil supply through Ulsan and Yeosu refinery integration to defend against Group II margin erosion. Secure OEM fill specifications for electrified powertrains before thermal fluid standards crystallize.
For New Entrants and Emerging Players: Build out Sejong smart city autonomous shuttle lubrication service models, where condition-monitoring protocols remain undefined and incumbent relationships are weakest. Target government fleet procurement as the most penetrable buyer archetype, bypassing entrenched dealer networks through telematics-linked predictive maintenance offerings.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-focused blenders with multi-year service contracts and consignment inventory arrangements. Long-term viability rests on dual-chemistry platform management capability spanning combustion formulations and thermal fluids. Monitor EV penetration rate inflections and hybrid architecture ratios as portfolio transition signals.
| Strategic Initiative | Industry Significance |
|---|---|
| K-REACH Additive Localization | Domestic toxicology partnerships reduce import dependency and accelerate regulatory approval timelines for SK Innovation. |
| Thermal Fluid Capacity Buildout | Polyalkylene glycol production lines capture battery cooling demand from Hyundai-Kia EV platforms in Asan and Gwangju. |
| Fleet Direct Supply Agreements | Bypassing dealer networks locks in CJ Logistics and Hanjin Transportation volume through multi-year maintenance contracts. |
| Condition-Monitoring Service Models | Sejong autonomous shuttle trials establish predictive maintenance protocols that favor data-integrated lubricant suppliers. |
| Carbon Border Adjustment Readiness | Lifecycle emissions documentation positions Korean exporters for EU CBAM compliance and premium market access. |
Research Methodology
A spread of perspectives from refinery operations managers, fleet procurement directors, OEM technical specification engineers, and aftermarket distribution partners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against MFDS chemical safety filings, K-REACH registration databases, customs trade statistics, and SEC disclosures from integrated petrochemical producers. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with segmentation across product type, application, distribution channel, and end user modeled throughout the projection horizon. Vehicle propulsion architecture mix and EV penetration scenarios served as key forecast inputs, with CAGRs derived from iterative reconciliation of production capacity, fleet turnover rates, and regulatory compliance timelines.
Practitioners should monitor government subsidy levels for battery electric vehicles and hybrid architecture adoption ratios for early signals of portfolio transition timing. Forecasts reflect assumptions about K-REACH enforcement intensity and base oil capacity utilization across Northeast Asia. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Metalworking Fluids Market
Lubricants
Marine Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
South Korea Lubricants Market
Lubricants
Argentina Lubricants Market
Lubricants
Global Finished Lubricant Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Power Steering Fluids Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Lubricated Tracks Market
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Chile Lubricants Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Jordan Lubricants Market