
 Africa Lubricants Market | 2026-2036
Africa Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Lubricants Market Analysis
Aftermarket technical support revenue is fragmenting across the Africa Lubricants Market as distributors compete for service-margin pools previously captured by integrated suppliers. TotalEnergies leverages its Francophone West African retail network to anchor blending and logistics operations in Senegal and Côte d'Ivoire. Sasol dominates synthetic base stock supply through its Secunda refinery complex, while Engen Petroleum competes via coastal import terminals in Mozambique and Tanzania.
Africa lubricants comprise refined petroleum-derived or synthetic base oils blended with performance additives to achieve specified viscosity grades, oxidation stability, and wear-protection characteristics for friction reduction in mechanical systems. Engine Oil commands the largest volume share across the continent due to Africa's expanding vehicle parc and extended drain intervals in tropical operating conditions. Industrial applications within the End User segment exhibit the fastest structural expansion, driven by cement manufacturing, mining, and food processing investments in Ethiopia and Ghana. Grease formulations for heavy machinery in the Application category sustain premium pricing where remote operations limit re-lubrication frequency.
South Africa's Department of Mineral Resources and Energy enforces environmental compliance protocols that shift demand toward biodegradable hydraulic fluids, while Nigeria's Standards Organisation mandates product certification for imported lubricants. The African Organisation for Standardisation harmonizes regional testing methods, though enforcement remains uneven across member states. Stakeholders must monitor evolving national petroleum product regulations and assess localized blending capacity before committing capital to distribution infrastructure.
Market Dynamics
South Africa's Department of Mineral Resources and Energy enforcement of stricter environmental compliance standards for industrial fluids is compressing formulation timelines and forcing blenders to accelerate biodegradable base stock substitution across hydraulic and turbine applications.
Growth Catalysts
- Mining Equipment Lubrication:Expanding procurement budgets for open-pit and underground extraction machinery across Zambia and the Democratic Republic of Congo are pulling high-viscosity hydraulic fluids and extreme-pressure gear oils into bulk supply contracts.
- REACH-Aligned Environmental Protocols:South Africa's adoption of European chemical hazard classification frameworks is creating certified product premiums that reward early compliance investments by local formulators.
- Gas Turbine Maintenance Cycles:Nigeria's power generation sector synthetic lubricant consumption is accelerating as independent power producers extend equipment uptime between overhauls through predictive oil analysis programs.
Market Restraints
- Group III+ Base Oil Import Dependence:Synthetic feedstock supply concentrates in Sasol's Secunda refinery complex, creating single-source vulnerability for high-performance formulations during planned maintenance turnarounds.
- Counterfeit Product Penetration:Nigeria's Standards Organisation certification mandates face enforcement gaps at land border entry points, diluting brand integrity for licensed importers.
- Extended Drain Interval Technology:Advanced additive packages enabling 15,000-kilometer service cycles are compressing lubricant volume demand per vehicle despite parc expansion.
Strategic Opportunities
- Ethiopian Cement Manufacturing Cluster:Greenfield kiln investments in the Oromia region lack established lubricant supply relationships, creating first-mover anchoring potential for technical service bundling.
- Food-Grade NSF H1 Certification:Ghana's processing sector expansion is mandating incidental-contact lubricants for packaging machinery, opening formulation specialization margins.
- Digital Oil Analysis Platforms:Integration of IoT sensors with cloud-based degradation modeling is enabling condition-monitoring subscription revenue streams that displace transactional product sales.
Industry Challenges
- Blending Technician Certification:The African Organisation for Standardisation harmonized testing methods require laboratory competency verification that outpaces vocational training program output in Kenya and Tanzania.
- Legacy Equipment Compatibility:Biodegradable hydraulic fluid seal compatibility issues with 1980s-era mining fleets force dual inventory maintenance and complicate technical support protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Lubricants Market |
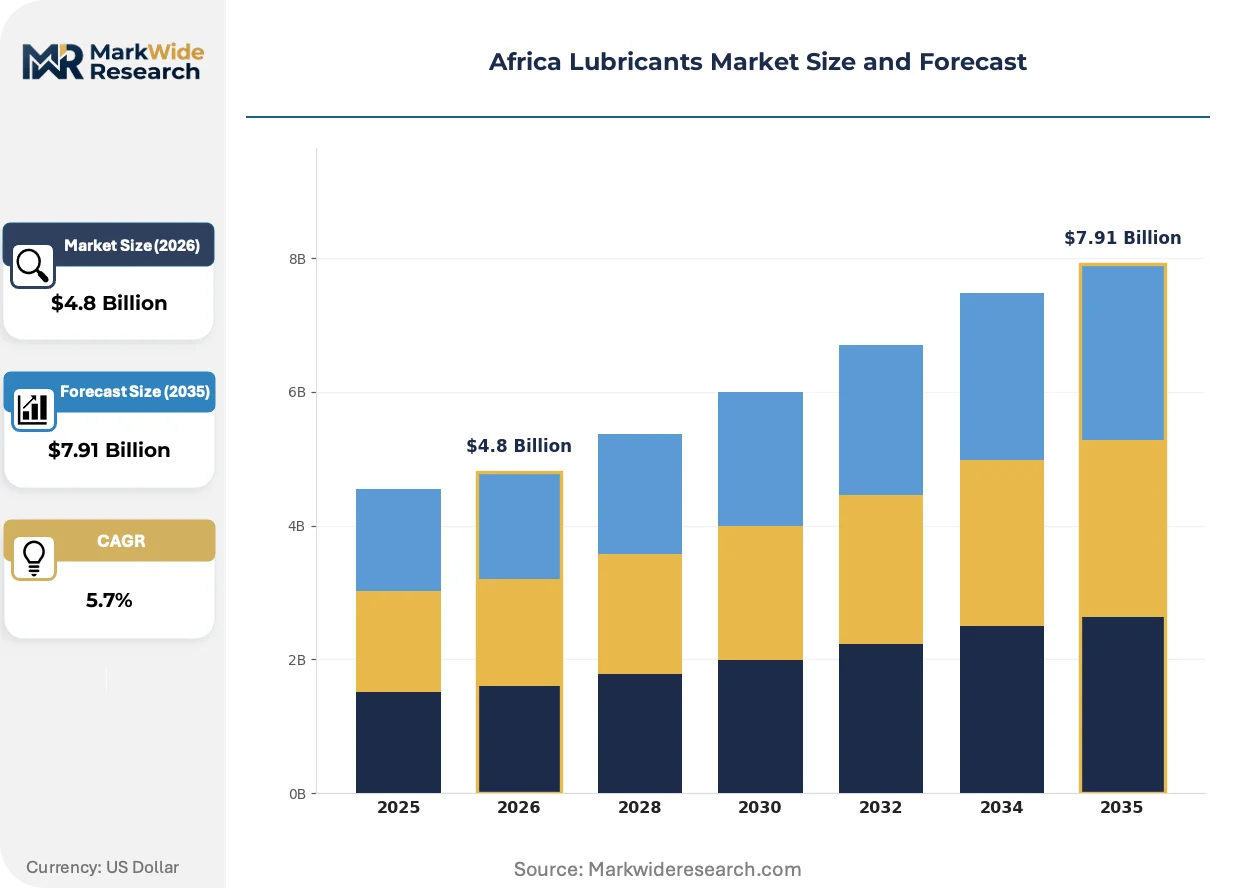
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Oil, Gear Oil, Grease End User: Automotive, Industrial, Marine, Aerospace Distribution Channel: Online, Retail Stores, Wholesalers, Distributors Application: Machinery, Vehicles, Equipment, Motors |
| Companies Covered | BP Plc, Fuchs Petrolub AG, Royal Dutch Shell Plc, Sasol, Engen Petroleum, TotalEnergies, Chevron Corporation, Sinopec Limited, Exxon Mobil Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Lubricants Market Emerging Trajectories
Formulation chemistry and service delivery models are diverging across price-performance tiers as environmental mandates accelerate and aftermarket technical support unbundles from product supply.
Polyalkylene glycol synthetic base stocks are migrating from niche compressor applications into mainstream hydraulic systems operating in high-moisture underground mining environments. Anglo American's South African platinum operations have completed fleet-wide conversion to PAG-based fluids over eighteen-month rollout schedules. This technology shift is compressing mineral oil volume share in premium industrial segments while opening reclamation service revenue pools through PAG's inherent separability from water contamination.
South Africa's Department of Mineral Resources and Energy environmental compliance protocols now mandate biodegradable hydraulic fluid deployment in surface water-proximate mining licenses. Industrial consequence includes accelerated additive supplier qualification timelines and reformulation costs passed through three-year contract escalators. The mining application segment is responding through consolidated procurement consortia that spread certification compliance investments across multiple operator balance sheets.
Aftermarket technical support revenue is fragmenting as independent distributors capture service-margin pools previously monopolized by integrated suppliers. Engen Petroleum's coastal import terminals in Mozambique and Tanzania now compete with regional blending facilities offering localized formulation adjustments and rapid sample turnaround. This channel restructuring is most visible in Francophone West Africa, where TotalEnergies' retail network anchoring in Senegal and Côte d'Ivoire faces unbundled technical service competition from specialized mining-sector distributors.
Africa Lubricants Market Segmentation
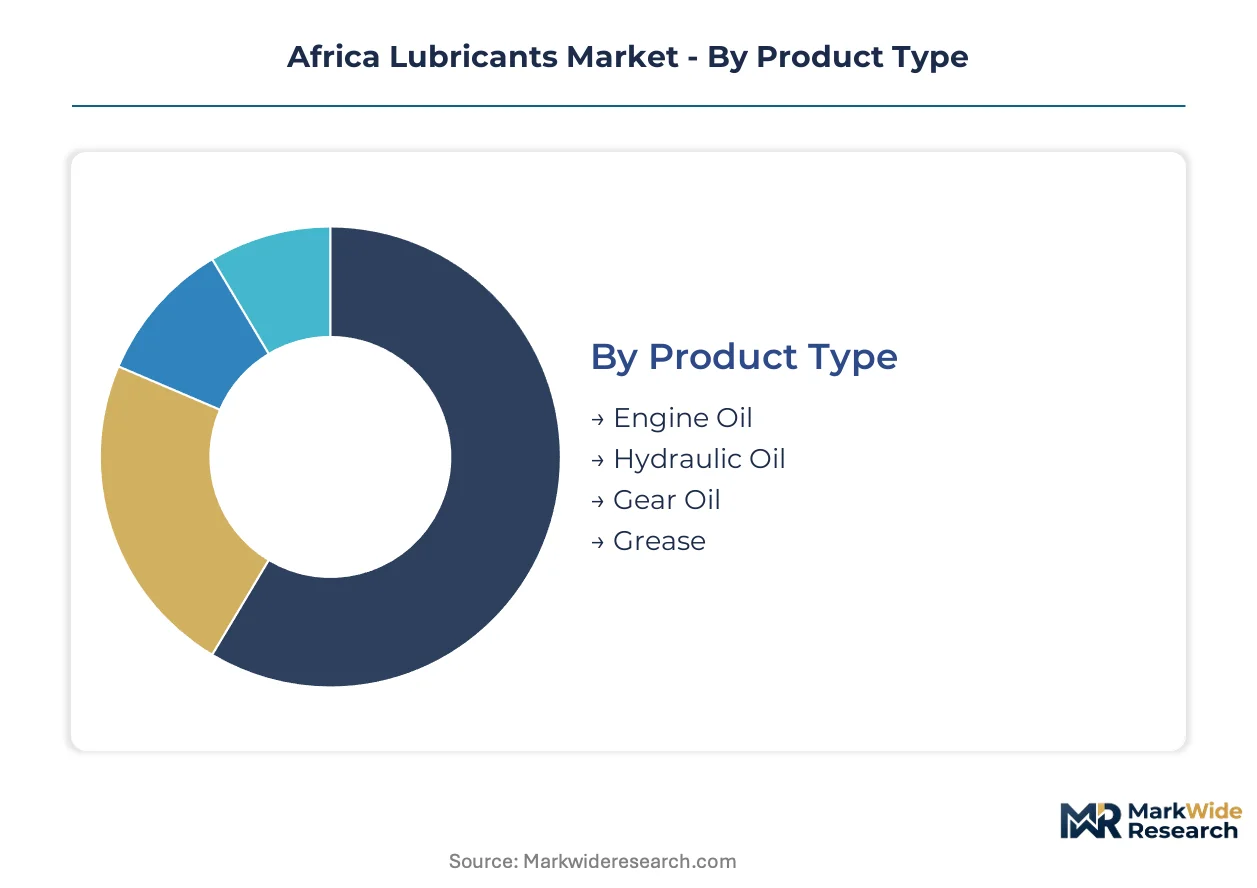
Product differentiation across viscosity grades and additive packages creates distinct margin pools that reward technical specification capabilities. End-user procurement patterns diverge sharply between maintenance-contract fleets and spot-buying industrial operators.
Product Type:
Mature mineral formulations dominate volume, while synthetic and biodegradable chemistries accelerate in premium industrial niches.
- Engine Oil:Blended from Group I-III base stocks with detergent-dispersant additive packages meeting API SP and ACEA C3 specifications. Nigeria's power generation sector and South Africa's commercial trucking fleets concentrate demand for extended-drain synthetics. Tropical operating conditions with high ambient temperatures accelerate oxidation stress, forcing shorter service intervals for mineral formulations.
- Hydraulic Oil:Anti-wear formulations with zinc dithiophosphate chemistry for high-pressure pump protection. Zambia and Democratic Republic of Congo open-pit mining operations pull high-viscosity ISO VG 68 grades into bulk supply contracts. South Africa's Department of Mineral Resources and Energy mandates biodegradable alternatives for surface water-proximate licenses, compressing formulation timelines.
- Gear Oil:Extreme-pressure formulations with sulfur-phosphorus additive systems for hypoid gear protection.
- Grease:Thickened lubricants with lithium complex or calcium sulfonate soap structures for bearings and chassis points.
Engine Oil handles the majority of throughput; Hydraulic Oil is the fastest mover on share.
End User:
Customer procurement sophistication spans from price-sensitive fleet operators to specification-driven OEM service contracts.
- Automotive:Passenger car and commercial vehicle service-fill demand concentrated in urban corridors. Ethiopia's expanding vehicle parc and Ghana's used-vehicle import dependency create divergent quality-tier requirements.
- Industrial:Cement manufacturing, mining, and food processing investments in Ethiopia and Ghana drive the steepest expansion trajectory. Predictive maintenance programs and oil analysis subscriptions displace transactional bulk purchasing.
- Marine:Two-stroke crosshead engine oils and trunk piston formulations for coastal shipping and inland waterways.
- Aerospace:Synthetic turbine oils meeting MIL-PRF-23699 specifications for commercial aviation ground support.
Automotive commands absolute volume; Industrial climbs the fastest on share.
Distribution Channel:
Channel power shifts from integrated suppliers toward unbundled technical service providers with localized blending capability.
- Online:E-procurement platforms capturing small fleet and workshop orders with transparent pricing and rapid delivery scheduling.
- Retail Stores:Branded lubricant bays at fuel stations and auto parts chains serving DIY consumers and informal mechanics.
- Wholesalers:Volume aggregators supplying independent workshops with private-label and licensed brand alternatives.
- Distributors:Technical service bundling with oil analysis, reclamation, and on-site blending adjustments for mining and industrial accounts.
Distributors handle the majority of industrial throughput; Online is expanding most quickly in automotive aftermarket.
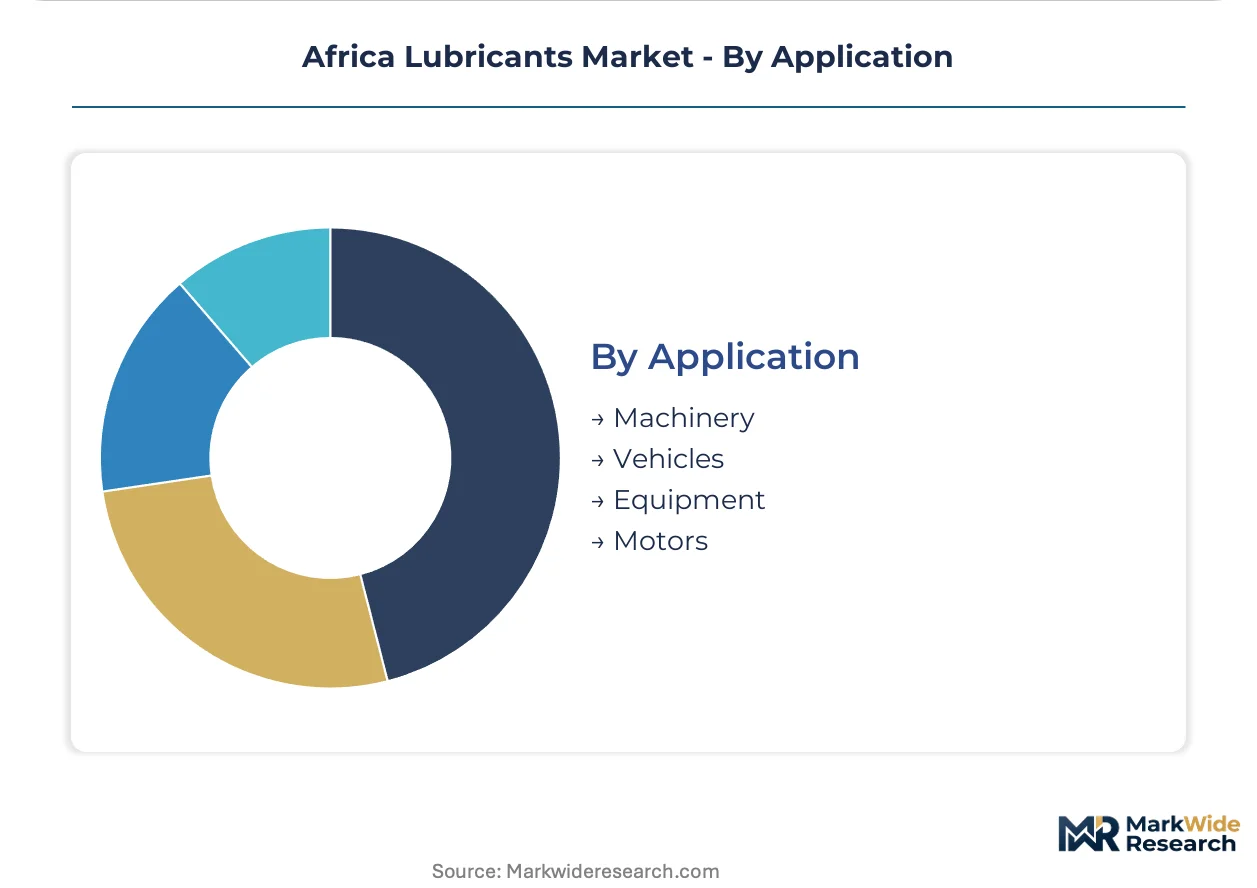
Application:
Equipment duty cycles and contamination exposure determine formulation durability requirements and re-lubrication frequency economics.
- Machinery:Fixed industrial equipment including compressors, pumps, and gearboxes operating in controlled environments with scheduled maintenance access.
- Vehicles:On-road and off-road mobile equipment subject to dust ingress, temperature cycling, and variable load factors.
- Equipment:Heavy construction and mining machinery with centralized lubrication systems and extreme contamination exposure.
- Motors:Electric motor bearing lubrication with polyurea or lithium grease formulations for high-speed, low-torque applications.
Vehicles handles the majority of throughput; Equipment is gaining share fastest on mining investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa consumes synthetic and biodegradable formulations at rates exceeding regional norms, while Nigeria and Francophone West Africa remain anchored to mineral-based engine oils for cost-sensitive fleet operations.
South Africa
Platinum and gold mining operations in the North West and Limpopo provinces pull high-viscosity hydraulic fluids into bulk contracts. The Department of Mineral Resources and Energy enforces REACH-aligned chemical hazard protocols that compress formulation timelines for biodegradable alternatives. The Secunda refinery complex anchors synthetic base stock supply for domestic blenders serving industrial accounts.
Nigeria
Independent power producers operating gas turbine installations in Lagos and Rivers states accelerate synthetic lubricant consumption through predictive maintenance programs. The Standards Organisation mandates product certification for imported lubricants, though enforcement gaps persist at land border entry points. The Niger Delta industrial corridor concentrates demand for extended-drain formulations in thermal power generation.
Zambia
Open-pit copper extraction in the Copperbelt Province drives procurement of extreme-pressure gear oils and high-viscosity hydraulic fluids for haul truck fleets. The country's environmental regulator requires water-proximate mining licenses to deploy biodegradable hydraulic alternatives. Kitwe and Ndola host consolidated procurement consortia spreading certification compliance investments across multiple operator balance sheets.
Ethiopia
Greenfield cement kiln investments in the Oromia region lack established lubricant supply relationships, creating first-mover anchoring potential for technical service bundling. The Ethiopian Conformity Assessment Enterprise mandates quality verification for imported industrial fluids. The Addis Ababa industrial zone exhibits fastest structural expansion in food-grade NSF H1 certified formulations for packaging machinery.
Senegal and Côte d'Ivoire
Francophone West African retail networks anchor blending and logistics operations serving mining and marine applications. The African Organisation for Standardisation harmonizes regional testing methods, though enforcement remains uneven across member states. Dakar and Abidjan port facilities compete for coastal import terminal positioning against Mozambique and Tanzania alternatives.
Africa Lubricants Market Vendor Landscape
Capability concentration sits with integrated refiners controlling synthetic base stock supply; scale advantage sits with coastal importers leveraging import terminal networks for regional distribution. The market structures around three tiers: captive refinery operators, multinational integrated suppliers, and unbundled technical service distributors. Strategic moves center on blending facility localization and predictive maintenance service bundling displacing transactional product sales.
Within the integrated multinational tier, TotalEnergies and Royal Dutch Shell Plc exemplify archetypes competing through retail network anchoring and Francophone West African logistics positioning. Sasol occupies a distinct position as the domestic synthetic base stock anchor through its Secunda refinery complex, while Engen Petroleum represents the coastal import terminal model competing via Mozambique and Tanzania facilities. These three patterns illustrate how supply-side configuration determines competitive positioning across mineral, synthetic, and biodegradable formulation segments.
| Leading Market Players |
|---|
| BP Plc |
| Fuchs Petrolub AG |
| Royal Dutch Shell Plc |
| Sasol |
| Engen Petroleum |
| TotalEnergies |
| Chevron Corporation |
| Sinopec Limited |
| Exxon Mobil Corporation |
| Others |
Supply Flow & Price Mechanics
Durban-Johannesburg freight corridors carry synthetic base stocks from Sasol's Secunda refinery to coastal blending terminals, with transport cost differentials creating price spreads between inland mining contracts and coastal industrial supply. Long-term offtake agreements for Group III+ synthetic feedstocks lock in volume commitments that insulate premium formulators from spot market volatility, while spot-buying cement manufacturers in Ethiopia face price escalators tied to biodegradable additive certification costs. Three-tier pricing structure across premium synthetic, standard mineral, and economy recycled formulations separates OEM service-fill contracts from informal workshop purchases, with price differentiation resting on API certification tier and after-sales technical support bundling. Pricing pressure stems from counterfeit mineral oil penetration at Nigerian land borders, compressing margins for licensed importers serving cost-sensitive commercial vehicle fleets. Independent power producers in Nigeria exhibit lowest price sensitivity due to gas turbine downtime costs, while informal mechanics in Ghana's used-vehicle market prioritize per-liter cost over drain interval performance.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between mining consortia and synthetic base stock suppliers, locking in three-year price bands with volume minimums that disadvantage spot buyers. Premium-mid-economy pricing differentiation separates NSF H1 food-grade certified formulations for Ghanaian packaging machinery from standard hydraulic fluids in Zambian copper extraction, with certification investment costs passed through contract escalators. Cost compression in mineral-based engine oils is intensifying because extended drain interval additive packages reduce per-vehicle volume demand despite parc expansion. Independent power producers operating gas turbine installations exhibit lowest price sensitivity, while informal automotive workshops in Francophone West Africa prioritize per-liter acquisition cost over technical service bundling.
Supply Chain Analysis
South Africa's Department of Mineral Resources and Energy environmental compliance protocols function as de facto export controls limiting biodegradable formulation technology flows to unlicensed blenders, concentrating high-performance supply among REACH-aligned domestic producers. Geographic supply concentration centers on South Africa's Secunda refinery complex for synthetic base stocks, Nigeria's Lagos port corridor for imported additive packages, and Senegal's Dakar blending facilities serving Francophone West Africa. Raw material dependencies draw from polyalkylene glycol synthetic chemistries, zinc dithiophosphate anti-wear additives, and lithium complex grease thickeners. Single-source vulnerability persists around Sasol's planned maintenance turnarounds for Group III+ feedstocks. Distribution runs through coastal import terminals in Mozambique and Tanzania competing with regional blending facilities offering localized formulation adjustments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH-aligned environmental compliance creates defensive moats for early-certification investments, with switching costs locking mining operators into qualified supplier relationships across multi-year equipment life cycles.
For Market Incumbents: Pre-empt unbundled technical service competition by acquiring oil analysis platform capabilities before independent distributors capture predictive maintenance subscription revenue. Consolidate procurement consortia relationships in Zambian copper mining to spread biodegradable certification costs across multiple operator balance sheets. Counter emerging entrant threat from Chinese additive suppliers by anchoring long-term offtake contracts with Secunda refinery capacity additions. For New Entrants and Emerging Players: Ethiopian cement manufacturing clusters in the Oromia region offer first-mover anchoring potential where greenfield kiln investments lack established lubricant supply relationships. Target food-grade NSF H1 certification gaps in Ghana's packaging machinery sector through technical service bundling with rapid sample turnaround laboratories. Pursue digital oil analysis platform partnerships as the primary go-to-market angle to displace transactional product sales with condition-monitoring subscriptions. For Investors and Strategic Acquirers: Regional blending facilities with localized formulation capability and African Organisation for Standardisation laboratory accreditation represent the priority acquisition archetype for coastal import terminal positioning. Long-term viability over the coming decade hinges on biodegradable formulation chemistry transitions and predictive maintenance service revenue displacement. Watch for inflection signals in South Africa's Department of Mineral Resources and Energy enforcement intensity at surface water-proximate mining licenses.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Certification | South Africa's environmental compliance mandates create certified product premiums rewarding early investments. |
| Digital Oil Analysis Platform Integration | IoT sensor deployments enable condition-monitoring subscriptions displacing transactional bulk sales. |
| Coastal Blending Facility Localization | Mozambique and Tanzania terminals compete for Francophone West African logistics positioning. |
| Long-term Mining Consortium Contracts | Procurement consortia spread REACH-aligned compliance investments across multiple operator balance sheets. |
| Food-Grade NSF H1 Specialization | Ghana's packaging machinery sector mandates incidental-contact lubricants opening formulation margins. |
Methodological Framework
The analysis maps engine oil, hydraulic fluid, gear oil, and grease formulation segments, each validated through blending facility managers, mining procurement directors, and aftermarket service technicians. Primary interviews with plant engineers at Zambian copper operations, technical directors at Ghanaian food processing facilities, and distribution channel partners in Senegal and Côte d'Ivoire combined with secondary validation from customs trade data, African Organisation for Standardisation harmonized testing protocols, and national petroleum product regulations. Bottom-up volume triangulation across end-user procurement patterns and top-down value estimation from refinery capacity disclosures anchored forecast ranges.
Assumption sets held fixed include continued enforcement of South Africa's REACH-aligned environmental protocols and sustained gas turbine maintenance cycle extensions by Nigerian independent power producers, while varying biodegradable adoption rates across water-proximate mining licenses and digital oil analysis platform penetration in industrial accounts. Segmentation dimensions modeled encompass product type viscosity grades, end-user industry verticals, distribution channel power structures, and application equipment duty cycles. CAGRs derived from base stock supply capacity expansion timelines and additive technology substitution curves across the projection horizon, with synthetic lubricant consumption in power generation and mining equipment serving as primary demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed additive suppliers or accelerated biodegradable mandate expansion by national environmental regulators would shift outcomes. Material shifts in South Africa's Department of Mineral Resources and Energy enforcement intensity or Sasol's Secunda refinery turnaround schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Hydro Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Norway Lubricants Market