
 Canada Automotive Lubricants Market | 2026-2036
Canada Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Lubricants Market Outlook
Modular service bundling is repositioning how fleet operators and independent garages purchase lubricants, shifting volume from standalone product sales to integrated maintenance packages. Shell Plc leverages its retail network to anchor bundled oil-change services at Canadian Tire locations. Imperial Oil Limited dominates direct-to-fleet contracts through its Esso-branded service stations. Petro-Canada Lubricants Inc. specializes in synthetic formulations for cold-climate engine protection.
Canada automotive lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and electric powertrain systems, with SAE viscosity grades defining cold-start flow and high-temperature film strength. Their primary purpose is extending component life and maintaining fuel efficiency across temperature extremes from Yellowknife to Windsor. Engine oil occupies the largest volume share given universal internal combustion engine dependency, while SAE 0W-20 grades are gaining fastest in passenger car segments driven by OEM fill specifications. Heavy-duty trucks generate concentrated margin pools due to extended drain intervals and premium synthetic requirements.
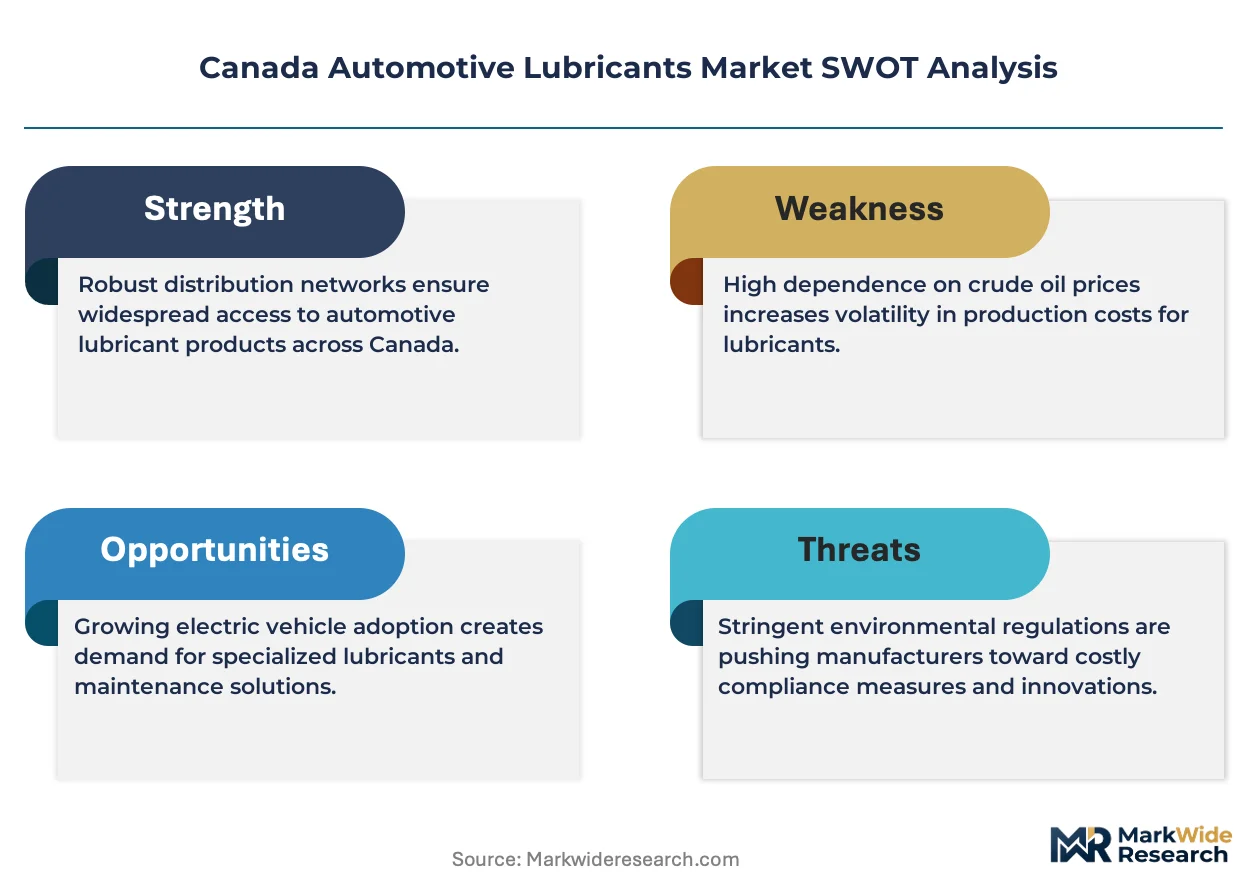
Health Canada and Environment and Climate Change Canada regulate lubricant toxicity and environmental discharge standards, while the Canadian General Standards Board maintains performance benchmarks that shape product certification and market access. These frameworks compel reformulation toward lower volatility base stocks and enhanced biodegradability. Stakeholders must monitor evolving electric vehicle powertrain fluid specifications and provincial carbon pricing mechanisms that alter total cost-of-ownership calculations for fleet operators.
Market Dynamics
Canada's automotive lubricants sector faces a structural pivot as Environment and Climate Change Canada's Clean Fuel Regulations force reformulation of base stocks toward lower volatility and enhanced biodegradability, compressing margins for conventional mineral oil producers while elevating synthetic blend premiums.
Growth Catalysts
- Clean Fuel Regulations:Environment and Climate Change Canada's tightening standards on product formulation are accelerating demand for advanced synthetic lubricants that meet lower volatility requirements.
- Commercial Fleet Expansion:Heavy-duty truck operators across Alberta and Saskatchewan are extending drain intervals through premium synthetic adoption, concentrating volume in high-margin categories.
- Electric Powertrain Fluid Specifications:OEM fill requirements for hybrid and battery-electric vehicles are creating new formulation categories for thermal management and gear protection fluids.
Market Restraints
- Group III+ Base Oil Supply Concentration:North American refining capacity for high-performance base stocks remains limited to a handful of Gulf Coast and Sarnia Corridor facilities.
- Platinum Group Metal Cost Volatility:Catalytic dewaxing processes for low-temperature pour-point oils expose formulators to palladium and platinum price swings.
- Extended Drain Interval Technology:Synthetic formulations lasting 25,000+ kilometers are compressing per-vehicle lubricant consumption volumes in the passenger car segment.
Strategic Opportunities
- Quebec Transport Logistics Hubs:Montreal's intermodal freight corridors present concentrated fleet operator demand for bulk synthetic contracts with integrated fluid analysis services.
- Provincial Carbon Pricing Mechanisms:British Columbia and Quebec's carbon credit systems alter total cost-of-ownership calculations, favoring lubricants that improve fuel efficiency metrics.
- Modular Service Bundling:Integrated maintenance packages combining oil changes, fluid analysis, and component inspection are displacing standalone product sales at independent garages.
Industry Challenges
- EV Powertrain Fluid Standardization Delays:SAE and ISO working groups have yet to finalize performance benchmarks for electric vehicle thermal management fluids, forcing formulators to navigate competing OEM proprietary specifications.
- Biodegradability Certification Timelines:OECD 301B and Environment Canada toxicity testing protocols extend new product introduction cycles by 18-24 months.
- Cold-Climate Formulation Expertise Scarcity:Chemists skilled in -40°C viscosity retention and pumpability engineering are concentrated among a shrinking pool of legacy Canadian refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Lubricants Market |
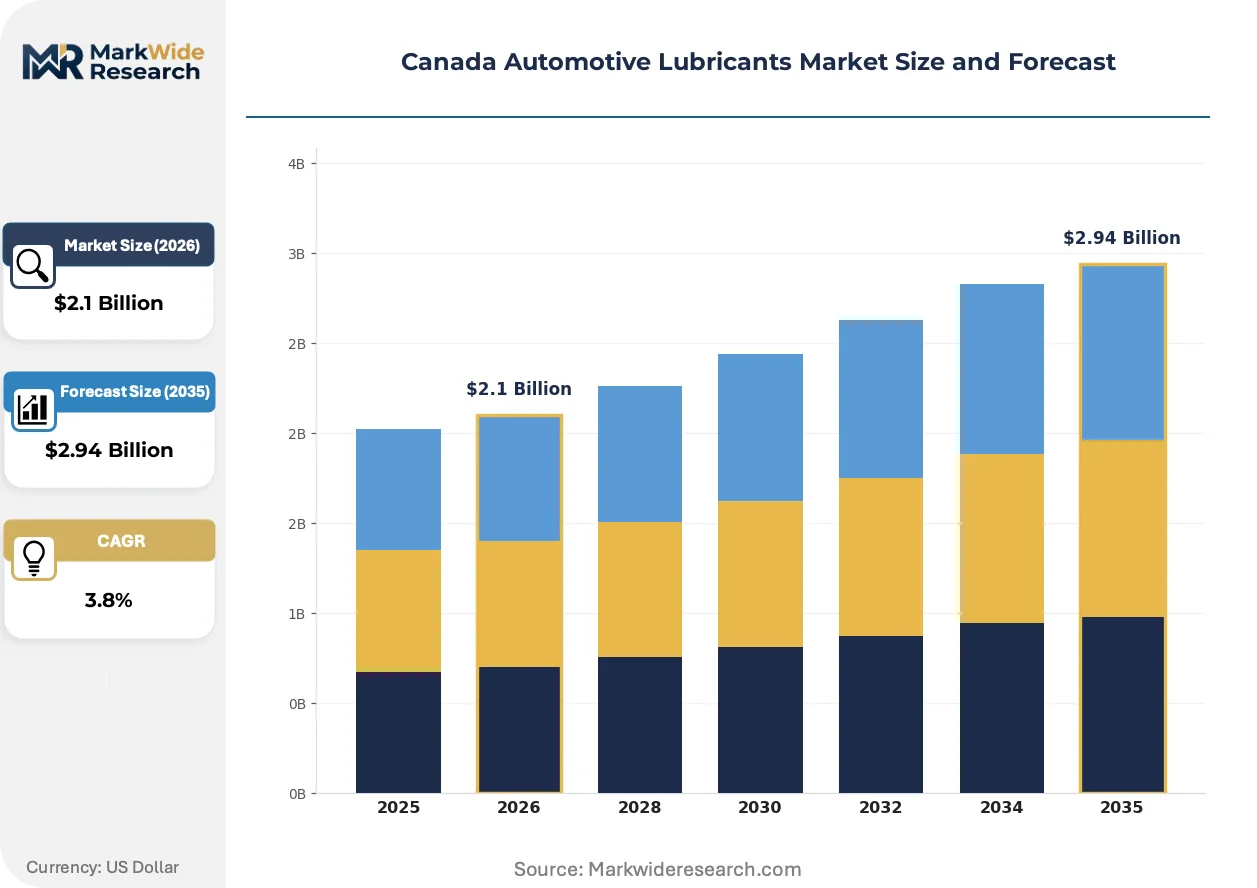
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Grease Viscosity Grade: SAE 0W-20, SAE 5W-30, SAE 10W-40, SAE 15W-50 End User: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Distribution Channel: Retail, Wholesale, Online, Service Stations |
| Companies Covered | Valvoline Inc, Chevron Corporation, Shell Plc, TotalEnergies, ExxonMobil Corporation, Imperial Oil Limited, Petro-Canada Lubricants Inc., FUCHS, BP p.l.c., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Lubricants Market Strategic Shifts
Synthetic base oil technology is unifying performance tiers across Canada's automotive lubricants landscape, collapsing distinctions between passenger car and heavy-duty formulations while regulatory pressure accelerates biodegradability mandates.
Polyalphaolefin (PAO) and gas-to-liquid (GTL) base stocks are unifying what were historically separate product lines for gasoline engines, diesel powertrains, and industrial gearboxes. Fleet operators in Ontario's manufacturing corridor are consolidating SKUs around multi-grade synthetics rated for both API SP and CK-4 service categories. This convergence is compressing distributor inventories and favoring formulators with backward integration into base oil production.
Health Canada's evolving toxicity screening under the Canadian Environmental Protection Act is forcing lubricant marketers to submit revised Safety Data Sheets with enhanced aquatic toxicity data. The industrial consequence is a wholesale retreat from zinc dialkyldithiophosphate (ZDDP) anti-wear packages toward boron and molybdenum alternatives. Passenger car motor oils face the steepest compliance burden, with Quebec's provincial environmental standards adding secondary disclosure requirements beyond federal baselines.
Fleet procurement departments are consolidating lubricant purchasing through national account structures, displacing the traditional jobber-distributor model that served independent repair shops. Bulk tank monitoring systems with automated reorder triggers are replacing periodic manual inventory checks. This behavioral shift is most visible across Western Canada's oil sands transport corridors, where integrated logistics providers negotiate direct supply agreements with refiners.
Canada Automotive Lubricants Market Segmentation
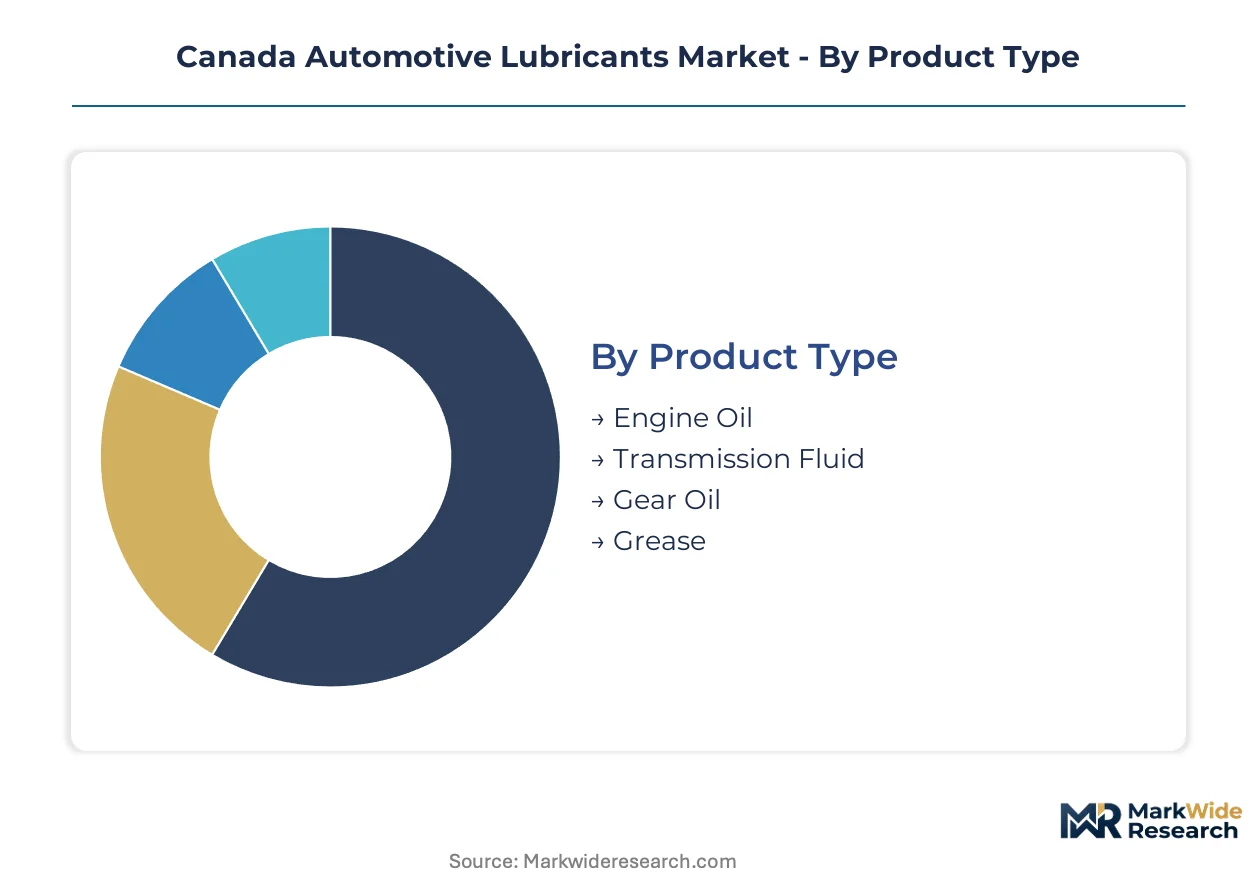
Canada's automotive lubricants market fragments across four distinct axes that determine formulation chemistry, purchasing behavior, and margin structure. Product type and viscosity grade define technical specifications, while end-user category and distribution channel shape commercial relationships and pricing power.
Product Type:
Cost tier separates buyers seeking commodity protection from those investing in extended-drain premium formulations.
- Engine Oil:Formulated hydrocarbon-based fluids reduce friction and dissipate heat in internal combustion powertrains. Ontario's manufacturing corridor concentrates passenger car demand driven by OEM fill specifications for SAE 0W-20 grades.
- Transmission Fluid:Specialized formulations with friction modifiers and thermal stabilizers enable smooth gear engagement across temperature extremes. Alberta's commercial fleet operators prioritize synthetic ATF for extended service intervals in heavy-duty applications.
- Gear Oil:Extreme-pressure additives protect differentials and manual transmissions under high-torque loads.
- Grease:Thickened lubricants with soap or complex soap bases seal out contaminants in chassis and wheel bearing applications.
Engine oil leads volumes today; transmission fluid is expanding most quickly as automatic transmission penetration rises.
Viscosity Grade:
Application temperature range dictates grade selection, with cold-climate pumpability requirements dominating Canadian specification patterns.
- SAE 0W-20:Ultra-low viscosity synthetic formulations enable rapid cold-start flow while maintaining high-temperature film strength. Quebec's transport logistics hubs specify this grade for hybrid powertrains seeking fuel efficiency credits under provincial carbon pricing mechanisms.
- SAE 5W-30:Multi-grade workhorse balancing winter protection and summer durability across the widest temperature window. Saskatchewan's agricultural and construction equipment fleets standardize on this grade for year-round operational flexibility.
- SAE 10W-40:Higher viscosity reserve for aging engines and severe-service conditions.
- SAE 15W-50:Racing and high-performance specialty applications requiring elevated temperature stability.
SAE 5W-30 holds the largest installed base; SAE 0W-20 is climbing the fastest as OEM fill specifications tighten.
End User:
Customer type determines volume scale, with fleet procurement consolidating purchasing power against fragmented retail demand.
- Passenger Cars:Individual owners and lease operators consuming standardized drain-interval products. British Columbia's urban centers concentrate demand for synthetic blends as consumers respond to carbon credit incentives for improved fuel efficiency.
- Commercial Vehicles:Light-duty vans and trucks operating on predictable maintenance schedules with bulk purchasing agreements. Manitoba's prairie logistics networks negotiate direct supply contracts with integrated fluid analysis services.
- Motorcycles:Specialized wet-clutch-compatible formulations for recreational and commuter two-wheelers.
- Heavy-Duty Trucks:Long-haul and vocational applications requiring API CK-4 and FA-4 service category compliance for extended drain intervals.
Passenger cars generate the highest unit volumes; heavy-duty trucks deliver the steepest margin expansion trajectory.
Distribution Channel:
Supply concentration varies dramatically, with integrated service networks displacing traditional jobber-distributor relationships.
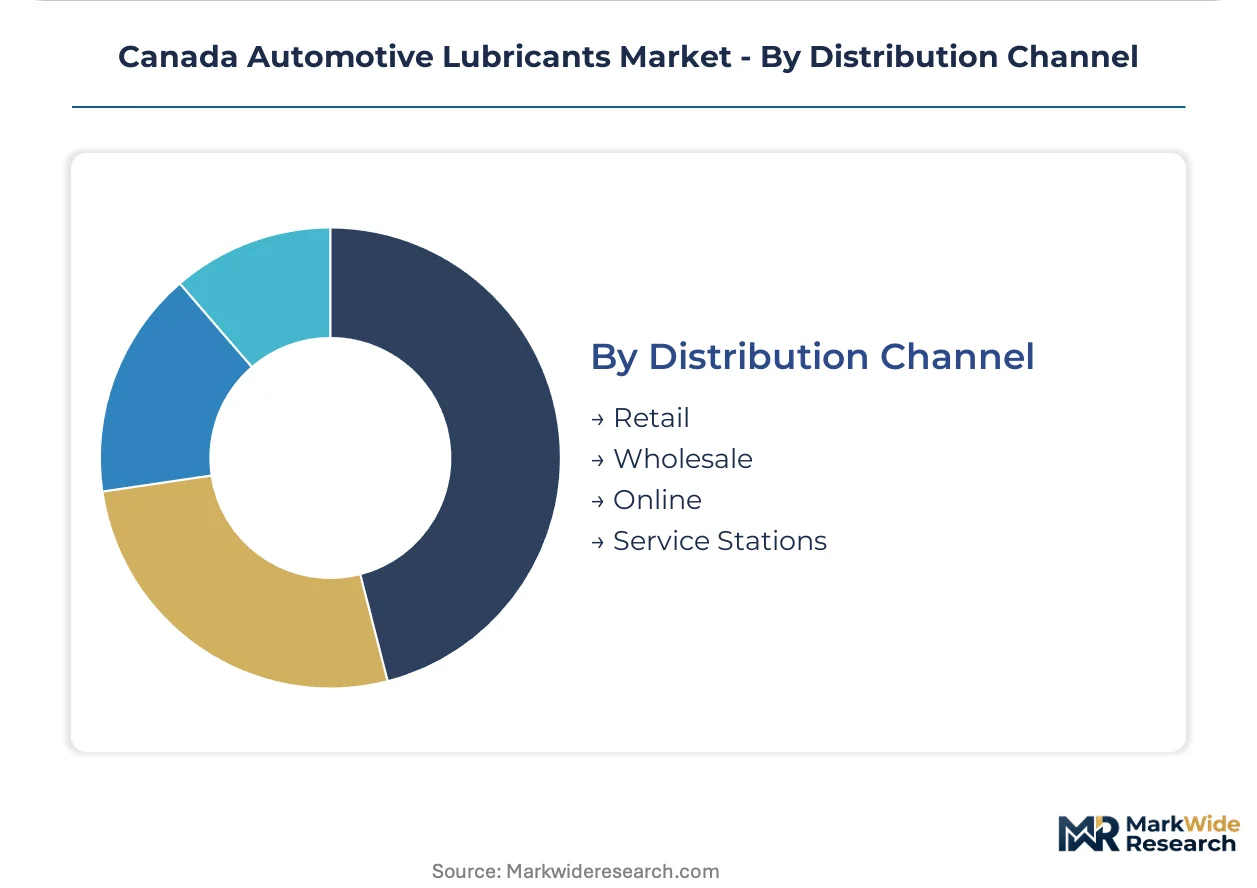
- Retail:Mass merchandisers and automotive specialty stores serving DIY consumers with packaged goods. Canadian Tire locations anchor bundled oil-change services that reposition lubricants as service inputs rather than standalone products.
- Wholesale:Distributor networks supplying independent garages and smaller fleet operators with bulk deliveries and inventory management.
- Online:Direct-to-consumer and B2B platforms enabling price transparency and subscription-based reordering for predictable consumption patterns.
- Service Stations:Branded quick-lube and maintenance facilities capturing installed-base loyalty through OEM-affiliated specification compliance.
Service stations capture the highest per-transaction value; online channels are gaining share fastest as fleet procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's manufacturing corridor established Canada's automotive lubricants industry through Detroit-Windsor supply chain integration in the early twentieth century. Quebec's transport logistics networks and Alberta's oil sands extraction created parallel demand centers. Provincial environmental regulations now reshape formulation standards across these historical production clusters.
Ontario
Passenger car assembly plants in Windsor and Oshawa drive OEM fill specifications for SAE 0W-20 synthetic grades. Environment and Climate Change Canada's Clean Fuel Regulations force base stock reformulation toward lower volatility. Toronto's suburban fleet operators consolidate purchasing through national account structures with integrated fluid analysis.
Quebec
Montreal's intermodal freight corridors generate concentrated demand for bulk synthetic contracts in heavy-duty applications. The province's carbon credit system alters total cost-of-ownership calculations for transport operators. Quebec's environmental standards layer secondary disclosure requirements beyond federal toxicity baselines.
Alberta
Oil sands transport fleets and commercial trucking operators extend drain intervals through premium synthetic adoption. The province's energy sector concentration creates specialized demand for severe-service formulations. Calgary-based logistics providers negotiate direct supply agreements with integrated fluid monitoring systems.
British Columbia
Urban centers in Vancouver and Victoria concentrate demand for synthetic blends as consumers respond to carbon credit incentives. The province's carbon pricing mechanism favors lubricants improving fuel efficiency metrics. Pacific port logistics hubs generate marine and intermodal freight lubricant requirements.
Saskatchewan
Agricultural and construction equipment fleets standardize on SAE 5W-30 grades for year-round operational flexibility across prairie temperature extremes. The province's mining and resource extraction sectors create severe-service formulation demand. Regina-based fleet operators prioritize bulk purchasing agreements with predictive maintenance integration.
Canada Automotive Lubricants Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation technology and cold-climate engineering capability. Shell Plc and Imperial Oil Limited anchor the upper tier through retail network density and direct fleet contracts. The market structure consolidates around three strategic archetypes: integrated refiner-marketers with captive base oil supply, specialty synthetic formulators with cold-climate expertise, and service-station operators bundling lubricants into maintenance packages. Competitive moves center on backward integration into base oil production and modular service bundling displacing standalone product sales.
Within the integrated refiner-marketer tier, Shell Plc and Imperial Oil Limited exemplify players leveraging retail network scale to anchor bundled services. Petro-Canada Lubricants Inc. occupies a position among specialty formulators with synthetic expertise for severe climate conditions. These three companies represent the dominant competitive archetypes: network-anchored bundling, direct fleet contracting, and climate-specialized formulation.
| Leading Market Players |
|---|
| Valvoline Inc |
| Chevron Corporation |
| Shell Plc |
| TotalEnergies |
| ExxonMobil Corporation |
| Imperial Oil Limited |
| Petro-Canada Lubricants Inc. |
| FUCHS |
| BP p.l.c. |
| Others |
Value Chain & Pricing Dynamics
Chemists skilled in -40°C viscosity retention and pumpability engineering in the Sarnia Corridor and Edmonton region command wage premiums that compress margins at the commodity tier while supporting synthetic blend pricing power. Labor-cost differentials between legacy refiner technical staff and general formulators drive spreads between premium and economy product lines.
Pricing Analysis
Three-tier pricing structure across premium synthetic, mid-grade blend, and mineral economy levels governs Canadian automotive lubricant transactions. Price differentiation rests on API service category compliance and OEM fill certification status, with CK-4 and SP-rated products commanding substantial premiums over obsolete SN and CJ-4 grades. Pricing pressure stems from extended drain interval technology compressing per-vehicle consumption volumes. Fleet procurement departments exhibit lowest price sensitivity due to total cost-of-ownership modeling, while independent garages and DIY consumers show highest elasticity.
Supply Chain Analysis
API and CGSB certification requirements gate market access, forcing formulators through 18-24 month validation cycles before commercial launch. Base stock supply concentrates in United States Gulf Coast refineries, Sarnia Corridor facilities, and select European Group III+ producers. Raw material dependencies include polyalphaolefin feedstocks, gas-to-liquid base oils, and platinum-group metal catalysts for dewaxing processes. Single-source vulnerability runs through North American Group III+ capacity concentration. Distribution runs through integrated refiner-marketer captive networks, national account direct contracts, and diminishing independent jobber channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's automotive lubricants sector offers margin expansion through synthetic premiumization and service bundling, with reformulation costs already absorbed creating operating leverage as Clean Fuel Regulations tighten.
For Market Incumbents: Acquire fluid analysis and predictive maintenance technology capabilities to anchor fleet customer retention against modular service competitors. Consolidate backward integration into PAO and GTL base oil production to secure supply continuity through Group III+ capacity constraints. Defend against independent garage displacement by embedding lubricant sales within Canadian Tire and Esso-branded bundled maintenance packages. For New Entrants and Emerging Players: Cold-climate formulation IP for electric powertrain thermal management fluids offers unclaimed white space as SAE and ISO standards remain unresolved. Target Quebec transport logistics hubs with carbon credit-eligible synthetic contracts, leveraging provincial environmental standards as competitive moat. Pursue direct-to-fleet digital procurement platforms with automated bulk tank monitoring to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale synthetic formulators lacking retail network scale but holding CGSB-certified product portfolios. Long-term viability hinges on electric vehicle fluid specification capture as internal combustion volumes plateau. Watch for finalization of SAE J3071 and ISO 19243 thermal management fluid standards as inflection signal for first-mover premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive PAO and GTL supply secures margins against Group III+ capacity bottlenecks in Gulf Coast and Sarnia Corridor. |
| Modular Service Bundling Expansion | Integrated oil-change and fluid analysis packages at Canadian Tire locations reposition lubricants as service inputs. |
| Electric Powertrain Fluid Development | Early formulation for SAE J3071 thermal management standards captures OEM fill specifications ahead of standardization. |
| Carbon Credit-Eligible Product Certification | Quebec and British Columbia provincial mechanisms reward lubricants improving fleet fuel efficiency metrics. |
| Predictive Maintenance Technology Acquisition | Bulk tank monitoring with automated reorder triggers locks in fleet procurement through integrated logistics contracts. |
Study Parameters
Bottom-up fleet operator and garage consumption modeling reconciled against top-down refiner production and base oil import tracking forms the analytical core. Primary interviews with lubricant formulators, fleet procurement managers, aftermarket distributors, and Canadian Tire category buyers combined with secondary validation from Environment and Climate Change Canada regulatory filings, Canadian General Standards Board certification databases, and customs trade data. Triangulation across supply-side capacity assessments and demand-side consumption patterns ensures statistical integrity.
Input-output matrices map base oil supply volumes through formulation stages to end-use consumption across passenger car, commercial vehicle, and heavy-duty truck segments. Segmentation dimensions include product type, viscosity grade, end-user category, and distribution channel, with propulsion architecture added to capture electric powertrain fluid emergence. CAGRs derive from regression analysis against vehicle fleet growth, drain interval extension trends, and synthetic penetration rates. Forecast inputs incorporate Clean Fuel Regulations compliance costs and provincial carbon pricing mechanism adoption patterns.
The model holds under stable regulatory implementation timelines; deviation in electric vehicle adoption velocity or biodegradability certification acceleration would shift volume trajectories. Forecasts reflect documented assumptions regarding OEM fill specification evolution and fleet procurement consolidation. Specific risks include SAE/ISO standardization delays for EV fluids and platinum-group metal price volatility affecting synthetic base stock economics. A model refresh is warranted upon material change in Environment and Climate Change Canada toxicity screening protocols or finalization of electric powertrain fluid performance benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Solid/Dry Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
Indonesia Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
Lube Skid Market
Lubricants
Brazil Lubricants Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
High Performance Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Fire Resistant Fluids Market