
 Brazil Lubricants Market | 2026-2036
Brazil Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Lubricants Market Outlook
Fleet operators is bifurcating Brazil's lubricant demand away from individual vehicle owners toward centralized procurement programs. Petrobras anchors national supply through its refineries and captive distribution network. Shell plc differentiates via synthetic formulations targeting extended drain intervals. Cosan Lubrificantes competes aggressively in the sugar-ethanol machinery segment with tailored hydraulic solutions.
Lubricants are formulated mixtures of base oils and functional additives engineered to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically classified under SAE J300 for engine oils and ISO 3448 for industrial fluids. Engine oil generates the largest revenue pool given Brazil's substantial on-road fleet, though grease commands premium margins in mining and heavy equipment applications where contamination resistance justifies higher unit pricing. Industrial machinery operation represents the fastest-growing application channel as Brazilian manufacturing capacity expands.
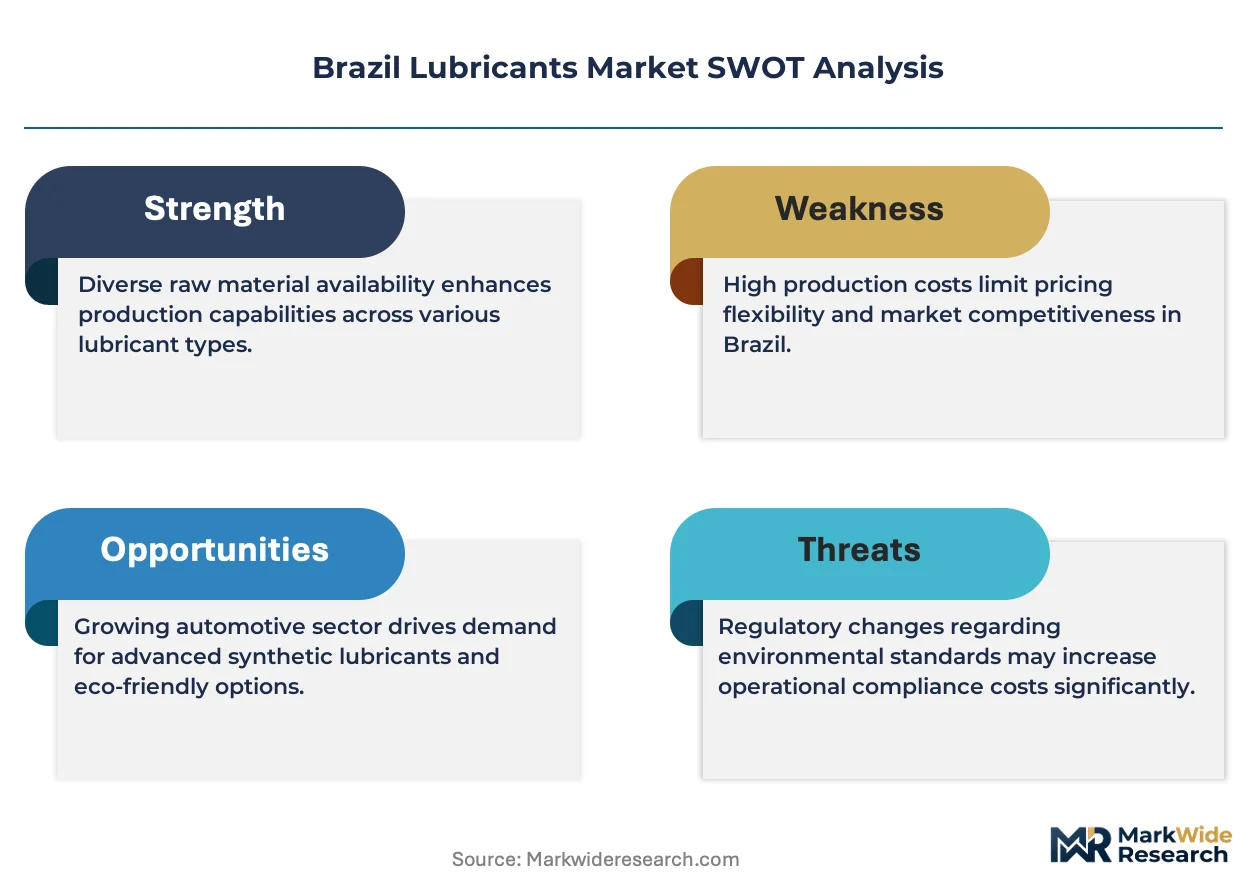
ANP enforces fuel and lubricant quality standards that mandate minimum performance benchmarks for products sold domestically, while INMETRO certification requirements create compliance barriers for imported formulations. ANVISA oversees workplace exposure limits that push industrial buyers toward lower-toxicity synthetic alternatives. Stakeholders must monitor biofuel blending mandates and their compatibility implications for lubricant additive chemistry.
Market Dynamics
Fleet operator consolidation in Brazil's automotive sector is redirecting lubricant procurement toward centralized volume contracts, compressing distributor margins while elevating technical specification requirements for synthetic formulations.
Growth Catalysts
- ANP fuel-quality mandates:Stricter ethanol-blend compatibility requirements are accelerating synthetic lubricant adoption as conventional mineral formulations face premature degradation.
- Sugar-ethanol machinery expansion:Brazil's agro-industrial sector is generating specialized hydraulic fluid demand tailored to high-moisture, high-temperature harvest conditions.
- São Paulo manufacturing corridor concentration:Industrial machinery density in this state is creating localized lubricant consumption clusters that reward just-in-time distribution investments.
Market Restraints
- Base oil import dependency:Brazil's limited domestic Group II/III base oil production exposes formulators to currency volatility and freight cost fluctuations.
- INMETRO certification timelines:Extended product registration procedures create launch delays that disadvantage imported formulations against established domestic portfolios.
- Extended drain interval technology:Synthetic formulations with longer service life are compressing overall lubricant volume demand per vehicle-kilometer.
Strategic Opportunities
- Minas Gerais mining belt penetration:Underdeveloped distribution infrastructure in this heavy equipment-intensive region offers first-mover advantages for specialized grease and hydraulic fluid suppliers.
- Bio-based additive convergence:Compatibility between renewable ester chemistry and Brazil's mandated biofuel blends opens formulation differentiation pathways unavailable in fossil-dependent markets.
- Direct fleet contracting channels:Bypassing traditional distributor networks through long-term service agreements captures volume commitments and technical partnership status.
Industry Challenges
- ANVISA workplace exposure compliance:Industrial buyers are demanding rapid reformulation to meet tightening toxicity thresholds for mineral oil mist limits.
- Legacy equipment compatibility:Synthetic seal swell characteristics require extensive field validation before adoption in Brazil's aged on-road fleet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Lubricants Market |
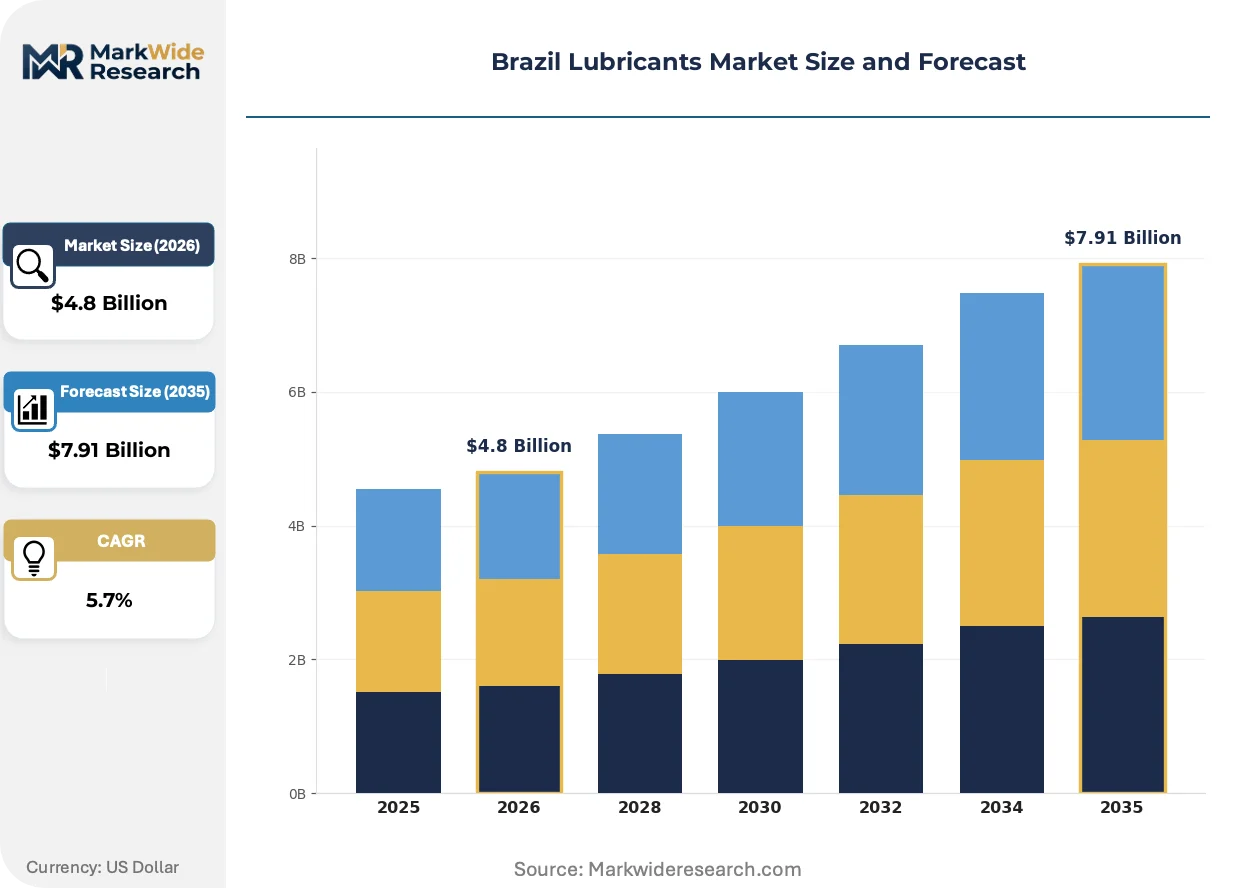
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Oil, Gear Oil, Grease End User: Automotive, Industrial, Marine, Aerospace Application: Automotive Maintenance, Machinery Operation, Marine Engine, Heavy Equipment Distribution Channel: Online Retail, Auto Parts Store, Wholesale, Direct Sales |
| Companies Covered | Petrobras, Shell plc, ExxonMobil Corporation, Iconic Lubrificantes, TotalEnergies, Cosan Lubrificantes, BP Plc (Castrol), Petronas Lubricants International, FUCHS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Lubricants Market Strategic Shifts
Formulation chemistry and procurement architecture are evolving in parallel across Brazil's lubricant sector, with bio-based additive platforms and fleet-direct contracting models gaining operational traction against established mineral-oil-distributor conventions.
Polyalphaolefin-based synthetic engine oils are supplanting Group I mineral formulations in Brazil's heavy-duty fleet segment. Large transport operators with centralized maintenance facilities are adopting these fluids to extend drain intervals and reduce downtime. This substitution is compressing commodity lubricant volume while elevating technical service requirements among distributors.
ANP Resolution 784 establishes mandatory performance benchmarks for lubricants sold in Brazil, including specific wear and deposit control tests. The regulation forces importers to conduct local engine testing that domestic refiners can shortcut through captive laboratory access. Formulators are responding by pre-certifying portfolios through Petrobras-affiliated testing channels.
Centralized procurement by multi-state fleet operators is consolidating purchasing authority away from regional distributors. Large logistics companies in Rio de Janeiro's port zone are negotiating direct supply agreements with blenders, disintermediating traditional wholesale channels. This concentration is most visible in São Paulo's interstate trucking corridors where fuel-card-integrated lubricant purchasing is becoming standard practice.
Brazil Lubricants Market Segmentation
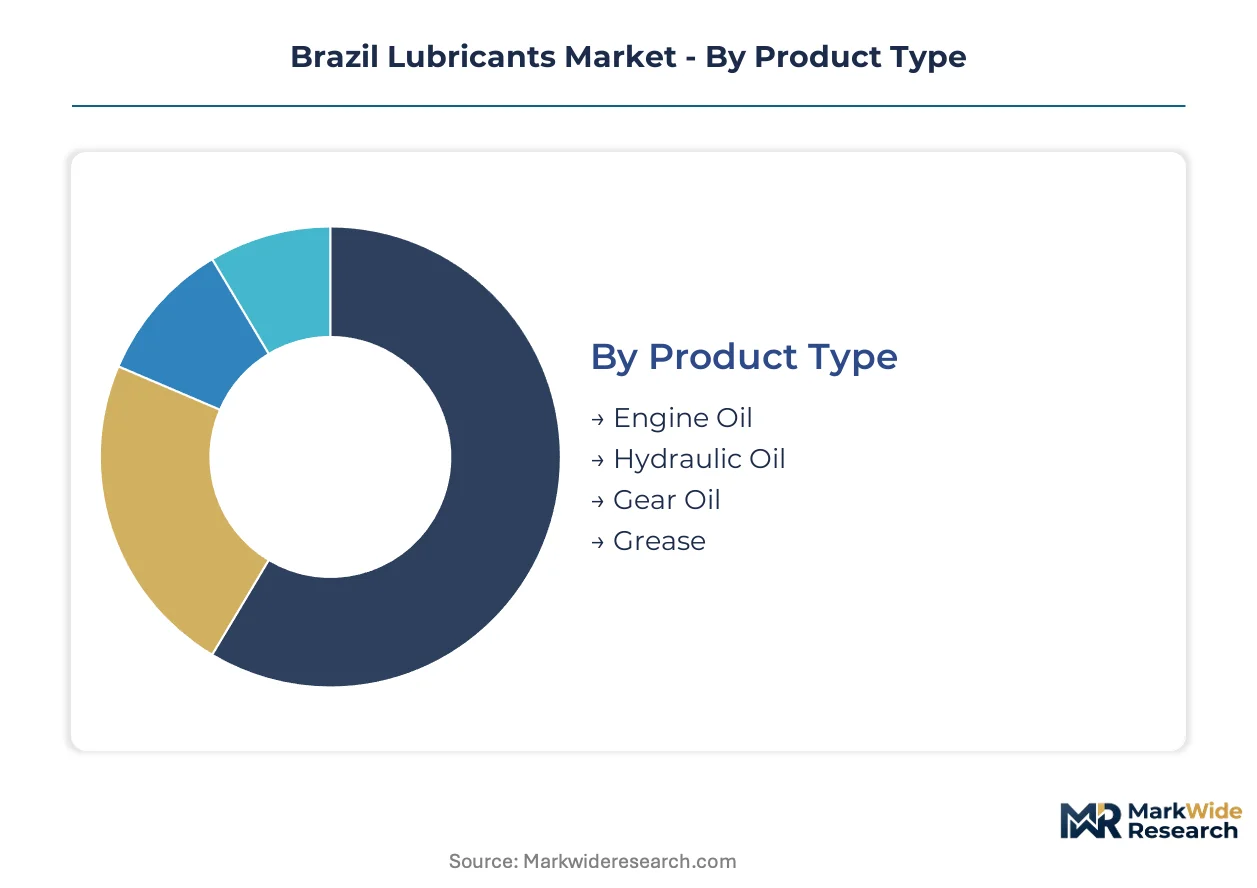
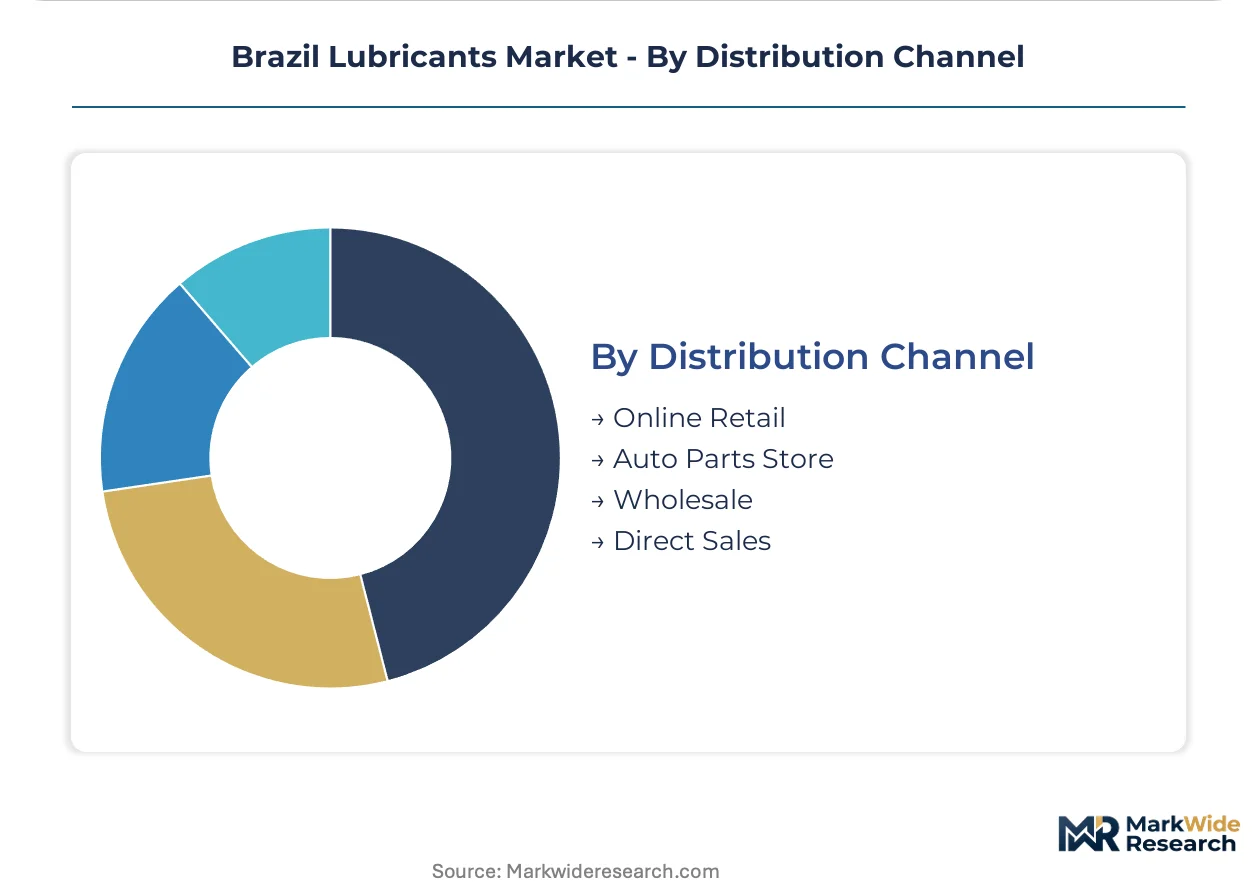
Brazil's lubricant segmentation reflects divergent channel economics. Fleet consolidation favors direct contracting in automotive, while industrial buyers split between technical distributors and mill-direct arrangements. Channel choice determines margin capture and formulation specification depth.
Product Type:
Channel-mix patterns vary sharply by product chemistry. Synthetic engine oils flow predominantly through direct fleet agreements, while mineral-based industrial fluids remain anchored to distributor networks with technical service attachments.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages meeting ANP Resolution 784 wear benchmarks. Demand concentrates in São Paulo's interstate trucking corridors where fuel-card-integrated purchasing has become standard practice among centralized fleet operators.
- Hydraulic Oil:Anti-wear formulations with viscosity index improvers and rust inhibitors engineered for high-pressure circulation systems. Sugar-ethanol machinery operators in São Paulo state and Goiás are driving specialized demand for fluids tolerant of high-moisture harvest conditions.
- Gear Oil:Extreme-pressure lubricants with sulfur-phosphorus additive chemistry for hypoid gear differentials.
- Grease:Thickener-stabilized lubricants delivering boundary lubrication in bearings and chassis points.
By volume, Engine Oil leads. By growth pace, Hydraulic Oil is climbing the fastest.
End User:
Cost-tier stratification separates premium synthetic formulations for automotive fleets from economy mineral grades serving aged industrial equipment.
- Automotive:Passenger vehicle and commercial fleet operators specifying SAE J300 viscosity grades with extended drain interval capabilities.
- Industrial:Manufacturing and processing facilities requiring ISO 3448-classified hydraulic and circulating oils with contamination resistance.
- Marine:Port logistics operators in Rio de Janeiro and coastal shipping corridors demanding high-base-number cylinder oils for residual fuel combustion.
- Aerospace:MRO facilities and general aviation operators sourcing MIL-PRF-specified synthetic turbine oils through specialized distribution.
Automotive generates the largest revenue pool. Industrial applications are expanding most quickly as Brazilian manufacturing capacity adds machinery.
Application:
Volume concentration tracks equipment density geography, with maintenance-intensive applications clustering in transport corridors and extractive zones.
- Automotive Maintenance:Scheduled service and preventive maintenance programs at fleet depots and quick-lube facilities.
- Machinery Operation:Continuous lubrication of manufacturing equipment, compressors, and pumps in industrial plants.
- Marine Engine:Crosshead and trunk piston engine lubrication for coastal and inland waterway vessels.
- Heavy Equipment:Mining, construction, and agricultural machinery operating in Minas Gerais mining belt and Cerrado farm zones.
Automotive Maintenance dominates current volume. Heavy Equipment is gaining share fastest on mining sector expansion.
Distribution Channel:
Customer-type fragmentation splits procurement between price-sensitive individual buyers and specification-driven institutional purchasers.
- Online Retail:E-commerce platforms capturing DIY consumer and small workshop demand with transparent pricing and rapid delivery.
- Auto Parts Store:Counter sales to independent mechanics and owner-operators with immediate availability requirements.
- Wholesale:Regional distributors stocking bulk inventory for resale to sub-distributors and service facilities.
- Direct Sales:Blender-to-fleet agreements bypassing intermediaries, concentrated in Rio de Janeiro port logistics and São Paulo manufacturing corridors.
Wholesale channels still handle the most volume. Direct Sales is expanding most quickly as fleet consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Santos-Paranaguá rail corridor and Rio de Janeiro port complex anchor Brazil's lubricant distribution infrastructure, channeling bulk formulations from coastal refineries into interior industrial zones.
São Paulo
Automotive fleet operators dominate lubricant procurement through fuel-card-integrated purchasing systems. ANP Resolution 784 mandates local wear-testing that domestic refiners shortcut via captive laboratory access. The Campinas-Sorocaba manufacturing belt concentrates industrial hydraulic fluid demand from automated assembly lines.
Minas Gerais
Iron ore mining operations in the Quadrilátero Ferrífero generate specialized grease demand for haul trucks and excavators. ANVISA workplace exposure limits push operators toward lower-toxicity synthetic alternatives. Belo Horizonte's machinery service depots form a secondary distribution node for heavy equipment lubricants.
Rio de Janeiro
Port logistics operators negotiate direct supply agreements with blenders, disintermediating wholesale channels. Petrobras maintains refinery capacity in the Baixada Fluminense that feeds captive distribution networks. The São Gonçalo-Niterói industrial corridor clusters marine cylinder oil demand from coastal shipping.
Rio Grande do Sul
Soybean processing facilities and meatpacking plants drive food-grade lubricant specifications for machinery safety. State environmental agencies enforce stricter discharge standards than federal baselines. Porto Alegre's equipment distributors stock specialized formulations for the Pampa agricultural machinery fleet.
Bahia
Petrochemical complexes in Camaçari generate captive base oil supply for regional formulators. The state's sugar-ethanol machinery operators demand hydraulic fluids tolerant of high-moisture harvest conditions. Salvador's port expansion projects are creating incremental marine lubricant consumption clusters.
Brazil Lubricants Market Competitive Environment
Listed leaders compete with private specialists across formulation technology and distribution reach. The market structures around three tiers: integrated refiners with captive base oil supply, international blenders with synthetic portfolios, and regional specialists serving machinery niches. Dominant competitive moves include direct fleet contracting that bypasses distributor networks and pre-certification of additive packages through ANP-affiliated testing channels.
Among integrated energy conglomerates, Petrobras anchors national supply through refinery-linked distribution. Shell plc and ExxonMobil Corporation exemplify international blenders competing on synthetic formulation ranges and extended drain interval capabilities. These three represent the primary competitive archetypes: captive supply integration, global technology licensing, and scale-driven procurement concentration.
| Leading Market Players |
|---|
| Petrobras |
| Shell plc |
| ExxonMobil Corporation |
| Iconic Lubrificantes |
| TotalEnergies |
| Cosan Lubrificantes |
| BP Plc (Castrol) |
| Petronas Lubricants International |
| FUCHS |
| Others |
Value Chain & Pricing Dynamics
Petrobras's refinery-linked captive base oil production anchors supply concentration in Brazil's lubricant sector, creating scale economies that simultaneously depress price floors for domestic formulators and elevate barriers for import-dependent competitors. This supply-side density compresses distributor margins while rewarding blenders with backward integration into Group II/III base stock production.
Pricing Analysis
Volume-discount tiering structures separate multinational fleet contracts from spot-market retail purchases, with synthetic formulations commanding premium positioning against mineral grades. Price differentiation rests on ANP Resolution 784 certification status and after-sales technical service bundling. Cost compression in the mineral-grade segment intensifies as centralized procurement aggregates demand. Individual vehicle owners and small workshops exhibit highest price sensitivity, while sugar-ethanol machinery operators prioritize contamination resistance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate São Paulo's manufacturing corridor, where automotive plants and sugar-ethanol processors minimize working capital tied to hydraulic fluid stocks. Geographic supply concentration draws from the United States, South Korea, and domestic Petrobras refineries for Group II/III base oils. Raw material dependencies center on polyalphaolefin synthetic base stocks, detergent-dispersant additive packages, and viscosity index improvers. Single-source vulnerability persists around specialized anti-wear chemistry imported from Asian suppliers. Distribution runs through Petrobras's captive network, Shell's technical service infrastructure, and regional wholesale distributors serving interior states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's lubricant sector functions as a defensive-moat market where ANP regulatory entrenchment and fleet switching costs protect incumbent positions. Established formulators benefit from captive laboratory access for mandatory wear-testing that importers cannot replicate.
For Market Incumbents: Secure ANP pre-certification pathways for additive packages to accelerate product launch timelines against import competitors. Deepen backward integration into bio-based ester chemistry to align formulation portfolios with Brazil's ethanol-blend mandates. Channel control through direct fleet contracting in Rio de Janeiro's port logistics zone repels distributor-dependent challengers.
For New Entrants and Emerging Players: Anchor in Minas Gerais mining belt distribution gaps where specialized grease demand outruns established supply infrastructure. Target sugar-ethanol machinery operators in Goiás with hydraulic fluids engineered for high-moisture harvest conditions. A technical service partnership model with Belo Horizonte equipment depots accelerates field validation and reference customer acquisition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-direct synthetic lubricant suppliers with multi-year service agreements. Long-term viability favors blenders with captive base oil access or bio-based formulation differentiation. Acquisition candidates should demonstrate ANP certification momentum and geographic expansion capability beyond São Paulo-Rio de Janeiro corridor dominance. Monitor biofuel blend mandate acceleration as inflection indicator for synthetic substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group II/III supply shields Petrobras and integrated formulators from currency-driven import cost volatility. |
| ANP Pre-Certification Investment | Local wear-testing access compresses product registration timelines versus import competitors facing INMETRO delays. |
| Direct Fleet Contracting Expansion | Bypassing wholesale channels captures volume commitments from Rio de Janeiro port logistics operators. |
| Bio-Based Additive Platform Development | Renewable ester chemistry compatibility with mandated ethanol blends opens formulation differentiation unavailable in fossil-dependent markets. |
| Minas Gerais Distribution Infrastructure Buildout | First-mover positioning in mining belt grease and hydraulic fluid supply exploits underdeveloped heavy equipment service networks. |
Study Parameters
Operator-level perspectives from fleet maintenance managers, sugar-ethanol machinery engineers, mining equipment service heads, and ANP regulatory affairs specialists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with downstream procurement decision-makers and technical validation sessions with lubricant formulators. Secondary sources included ANP Resolution 784 compliance filings, INMETRO certification databases, Brazilian customs trade records for base oil imports, and SEC disclosures from listed energy conglomerates. Bottom-up demand modeling triangulated against top-down refinery production capacity assessments.
Sensitivity analysis tested forecast robustness across ethanol-blend mandate acceleration scenarios and currency volatility assumptions. The analytical framework segmented volume and value projections by product chemistry, end-use equipment type, distribution channel architecture, and state-level industrial density. CAGRs derived from machinery fleet expansion rates, drain interval technology adoption curves, and manufacturing capacity addition pipelines. Industry-specific inputs incorporated sugar-ethanol harvest cycle patterns and mining sector equipment utilization benchmarks.
Decision-makers should treat outputs as directional under base assumptions of sustained ANP enforcement and biofuel blend mandate continuity; material deviation would warrant model refresh. Forecasts incorporate assumptions around fleet consolidation velocity and synthetic substitution elasticities. Revision becomes warranted when base oil import dependency ratios or workplace exposure regulatory thresholds cross material adjustment bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Germany Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Global Compressor Oil Market
Lubricants
Myanmar Lubricants Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Polyurea Greases Market
Lubricants
Contact Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Bio-Based Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Global Engineered Fluids Market