
 Rubber Testing Equipment Market | 2026-2036
Rubber Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Testing Equipment Market Outlook
Software-defined rheometer analytics is recalibrating what equipment vendors bundle with hardware sales. MonTech Rubber Testing Solutions leverages its European service network to sustain long-term calibration contracts. Alpha Technologies anchors its position through deep specialization in dynamic mechanical analysis for polymer research.
Rubber testing equipment comprises instruments that measure tensile strength, elasticity, hysteresis, and thermal degradation of elastomer compounds under controlled conditions, serving quality verification across tire manufacturing, industrial sealing, and consumer goods supply chains. Rheometers and dynamic mechanical analyzers capture the fastest-growing segment as compound complexity rises with silica-silane coupling and sustainable filler integration. Universal testing machines retain the largest installed base but face margin compression from standardized Chinese equipment imports.
ISO 23529 and ASTM D3182 govern sample preparation protocols that determine which instrument configurations qualify for supplier audits, while REACH substance restrictions and EU tire-labeling regulations expand the scope of mandatory batch testing. The US EPA and NHTSA maintain overlapping emission and safety standards that compounders must document through traceable measurement chains. Stakeholders should monitor how regulatory convergence between European and North American test protocols reshapes equipment specification requirements and service contract structures.
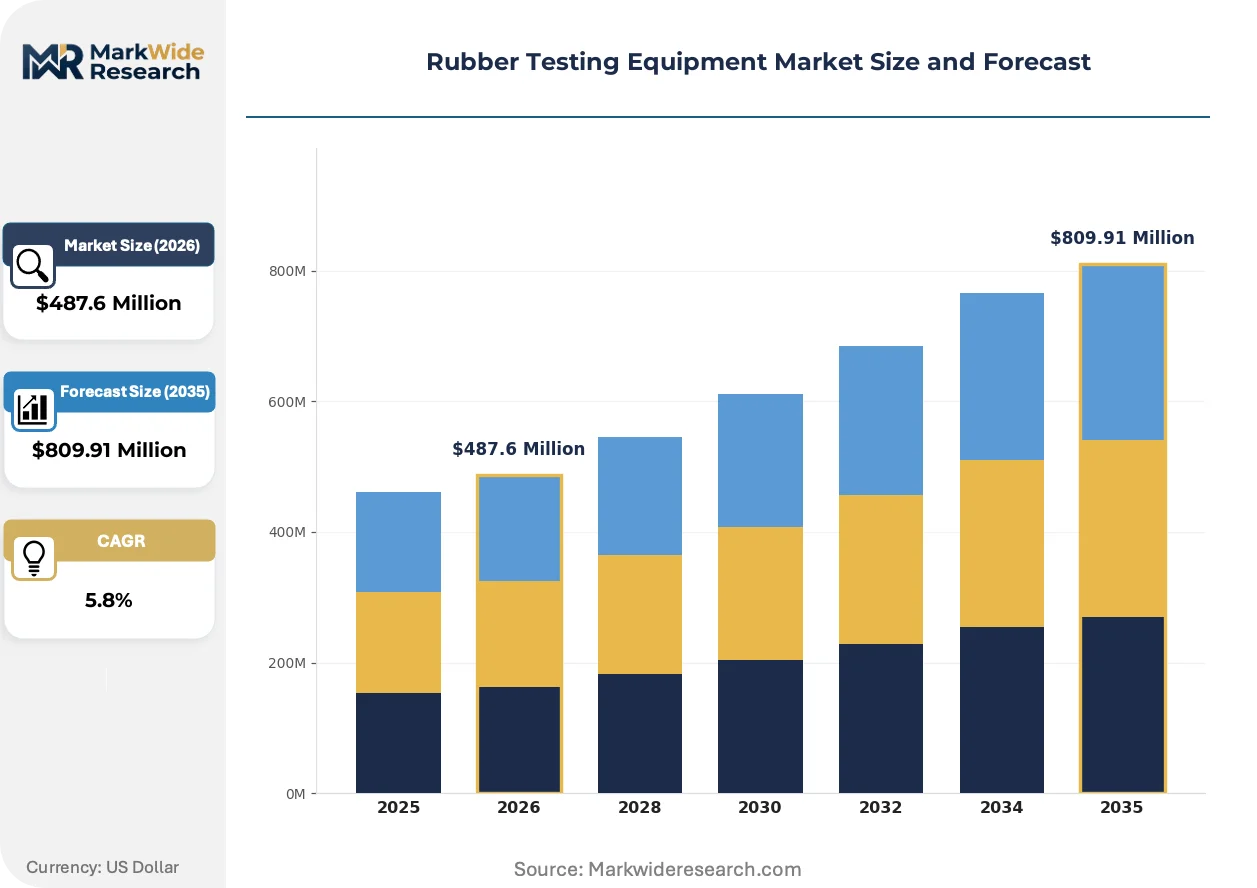
Market Dynamics
Tire OEM certification requirements in Vietnam and Indonesia are forcing compounders to upgrade laboratory infrastructure, while EU REACH substance restrictions mandate more frequent batch validation cycles across polymer supply chains.
Growth Catalysts
- REACH substance restrictions:European compounders must validate every batch for restricted chemicals, expanding testing frequency and equipment utilization rates.
- Silica-silane coupling integration:Sustainable tire formulations require rheometric characterization of filler dispersion, pulling demand for advanced dynamic mechanical analyzers.
- Vietnam tire production expansion:Regional manufacturing hubs are building captive testing laboratories to meet export certification standards.
Market Restraints
- Chinese equipment imports:Standardized universal testing machines from Shenzhen and Dongguan suppliers compress margins on legacy product lines.
- Calibration service concentration:European vendors dominate long-term service contracts, limiting aftermarket revenue capture for new entrants.
- Skilled polymer rheologist scarcity:Universities produce fewer specialists capable of interpreting complex viscoelastic data, constraining equipment utilization.
Strategic Opportunities
- Software-defined analytics:Cloud-based rheometer data platforms enable remote diagnostics and predictive maintenance contracts.
- Indonesian industrial rubber growth:Conveyor belt and sealing compound manufacturers lack sophisticated testing infrastructure.
- EU tire-labeling enforcement:Rolling resistance and wet grip verification mandates expand mandatory testing scope beyond tires to raw compound suppliers.
Industry Challenges
- ISO 23529 sample preparation compliance:Laboratories struggle to maintain traceable conditioning environments for supplier audit qualification.
- Legacy system integration:New rheometric software platforms must interface with decades-old laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Testing Equipment Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Testing Machines, Hardness Testers, Rheometers, Dynamic Mechanical Analyzers End User: Manufacturers, Quality Control Labs, Research Institutions, Automotive Industry Technology: Mechanical Testing, Thermal Analysis, Chemical Testing, Electrical Testing Application: Material Characterization, Quality Assurance, Process Optimization, Compliance Testing |
| Companies Covered | MonTech Rubber Testing Solutions, Elektron Technology, Alpha Technologies, Gibitre Instruments, BUZULUK, TA Instruments, Goettfert Inc, U-CAN DYNATEX INC, Qualitest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Testing Equipment Market Strategic Shifts
Digital instrumentation and predictive analytics are restructuring how testing equipment generates value, shifting vendor competition from hardware specifications to data service ecosystems.
Multi-frequency dynamic mechanical analysis is electrifying polymer characterization workflows. Tire manufacturers in Thailand and South Korea are adopting these systems to accelerate compound development cycles. The technology is electrifying traditional quality control departments into R&D-adjacent functions.
EU REACH Annex XVII updates on microplastic restrictions are forcing compounders to validate alternative filler systems. Industrial rubber producers must document biodegradation profiles through traceable measurement chains. Southeast Asian export-oriented facilities face the steepest compliance ramp as they serve European automotive OEMs.
After-sales service unbundling is fragmenting traditional equipment vendor relationships. Vietnamese tire manufacturers now procure calibration and maintenance from third-party metrology specialists rather than original equipment suppliers. This pattern is most visible in Ho Chi Minh City and Jakarta, where independent service laboratories compete on response time guarantees.
Rubber Testing Equipment Market Segmentation
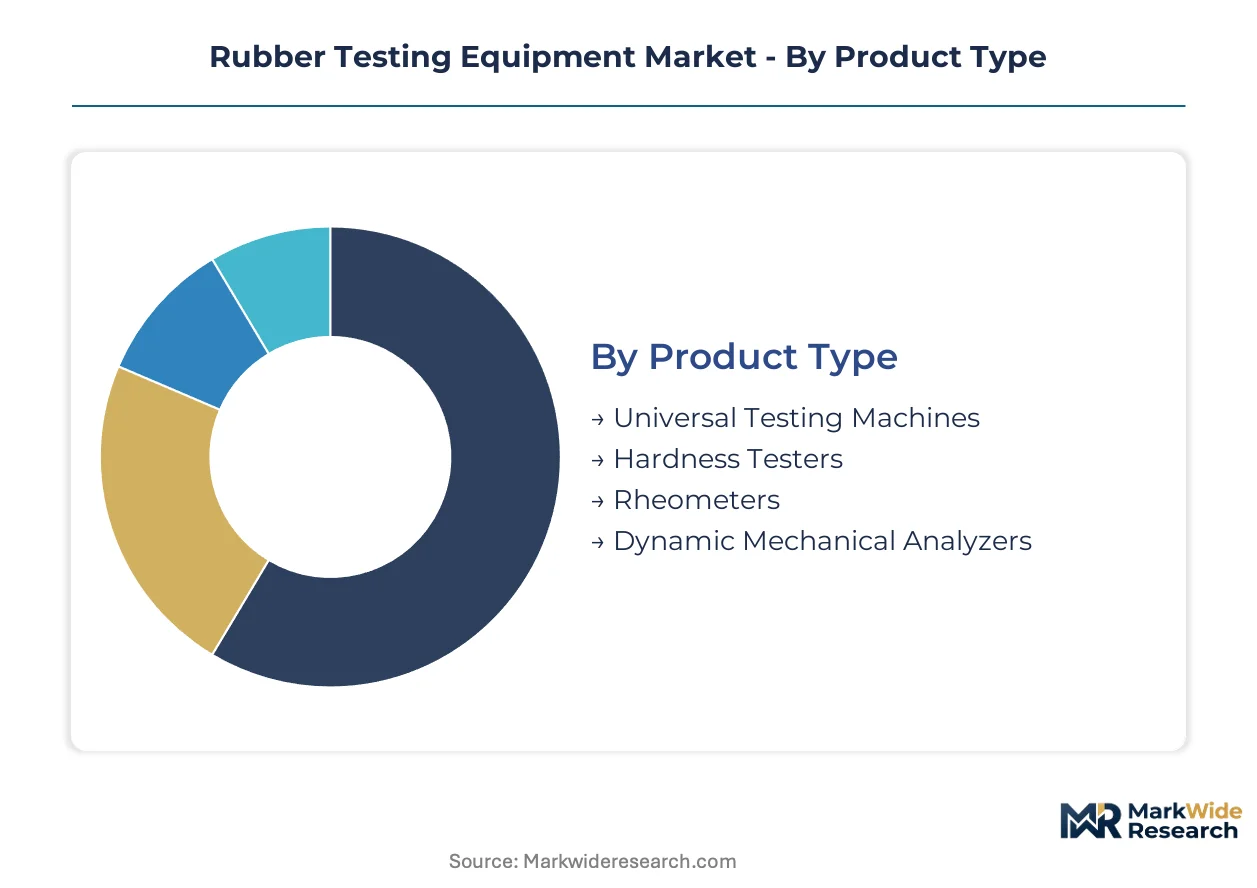
Rubber testing equipment vendors configure product portfolios around certification hierarchies that determine which instruments qualify for supplier audits. Segmentation choices directly affect compliance pathways under ISO 23529, ASTM D3182, and REACH batch validation requirements.
Product Type:
Certification burden varies sharply across instrument categories, with tire OEM audits demanding specific rheometer configurations while general manufacturing accepts broader testing protocols.
- Rheometers:These instruments measure viscoelastic properties of rubber compounds under shear deformation, capturing torque versus angle data to characterize curing behavior. Demand concentrates in Vietnam and Indonesia where tire manufacturers build captive laboratories to meet export certification standards, driven by silica-silane coupling integration in sustainable tire formulations.
- Dynamic Mechanical Analyzers:Systems applying oscillatory stress to measure storage modulus, loss modulus, and tan delta across temperature and frequency sweeps. Thai and South Korean tire producers are adopting multi-frequency variants to accelerate compound development cycles, pulled by EU tire-labeling mandates for rolling resistance documentation.
- Universal Testing Machines:Standardized tensile and compression testing equipment serving general rubber goods manufacturing.
- Hardness Testers:Shore and IRHD durometers for rapid elastomer hardness verification in quality control environments.
Leading the category by volume: Universal Testing Machines. Growing fastest: Dynamic Mechanical Analyzers.
End User:
Customer type determines pricing tolerance and service contract structure, with automotive OEMs demanding the most comprehensive calibration traceability.
- Automotive Industry:Tier-1 suppliers and OEM laboratories requiring full metrological traceability for PPAP submissions and supplier qualification. European automotive compounders face the steepest compliance ramp under REACH Annex XVII microplastic restrictions, validating alternative filler systems through documented measurement chains.
- Quality Control Labs:Independent and in-house laboratories performing batch release testing against customer specifications. Vietnamese tire manufacturers in Ho Chi Minh City increasingly procure calibration from third-party metrology specialists rather than original equipment vendors, fragmenting traditional service relationships.
- Manufacturers:Rubber goods producers conducting incoming raw material and finished product verification.
- Research Institutions:Universities and polymer research centers advancing elastomer science with less frequent but higher-specification instrumentation needs.
Dominating procurement spend: Automotive Industry. Expanding most quickly: Quality Control Labs.
Technology:
Technology platform selection governs which regulatory standards laboratories can credibly reference in supplier documentation.
- Mechanical Testing:Tensile, compression, tear, and fatigue testing of rubber specimens under standardized strain conditions. Indonesian conveyor belt and sealing compound manufacturers lack sophisticated infrastructure, creating openings for equipment vendors to upgrade legacy mechanical testing departments.
- Thermal Analysis:DSC, TGA, and DMA techniques characterizing filler dispersion, degradation temperatures, and glass transition behavior. EU REACH substance restrictions mandate thermal validation of every batch for restricted chemicals, expanding equipment utilization rates across European compounders.
- Chemical Testing:Chromatographic and spectroscopic methods for compound composition verification.
- Electrical Testing:Volume resistivity and dielectric characterization for specialty elastomer applications.
Highest installed base: Mechanical Testing. Steepest expansion trajectory: Thermal Analysis.
Application:
Application focus shapes software feature requirements and determines whether laboratories prioritize throughput or analytical depth.
- Compliance Testing:Mandatory verification against regulatory standards including EU tire-labeling, REACH batch restrictions, and US EPA emission documentation. Southeast Asian export-oriented facilities face the steepest compliance ramp as they serve European automotive OEMs, requiring traceable measurement chains for biodegradation profiles.
- Quality Assurance:Routine batch release testing ensuring consistency against customer specifications. Cloud-based rheometer data platforms enable remote diagnostics and predictive maintenance contracts, restructuring how quality departments generate value from testing infrastructure.
- Material Characterization:Fundamental property measurement supporting compound development and raw material qualification.
- Process Optimization:In-line and at-line testing to reduce scrap and accelerate manufacturing cycles.
Capturing largest revenue share: Quality Assurance. Gaining share fastest: Compliance Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City anchors Southeast Asian testing infrastructure expansion as Vietnamese tire manufacturers build captive laboratories to meet European OEM export certifications. German compounders face the steepest regulatory compliance burden under REACH Annex XVII microplastic restrictions. Chinese equipment imports compress margins across standardized mechanical testing segments.
Germany
Automotive OEM laboratories in Stuttgart and Munich demand full metrological traceability for PPAP submissions. ECHA REACH substance restrictions mandate thermal validation of every batch for restricted chemicals, expanding equipment utilization rates. The Rhine-Ruhr industrial corridor hosts concentrated polymer research institutions advancing elastomer science.
United States
Tier-1 suppliers serving Detroit automakers require dynamic mechanical analyzers for rolling resistance documentation under EPA emission standards. NHTSA safety standards compound documentation requirements through traceable measurement chains. The Southeast manufacturing belt attracts testing infrastructure investment from conveyor belt producers.
China
Shenzhen and Dongguan suppliers dominate standardized universal testing machine production, compressing global margins on legacy product lines. MIIT industrial standards govern domestic certification requirements for rubber goods manufacturers. The Yangtze River Delta concentrates tire production facilities building quality control capacity.
Vietnam
Tire manufacturers in Binh Duong province expand laboratory capacity to meet EU tire-labeling mandates for export markets. The country's national standards body aligns testing protocols with ISO 23529 sample preparation requirements. Ho Chi Minh City laboratories increasingly procure calibration from third-party metrology specialists rather than original equipment vendors.
Indonesia
Conveyor belt and sealing compound manufacturers in Java lack sophisticated thermal analysis infrastructure, creating upgrade openings for equipment vendors. The country's national industrial ministry promotes domestic rubber processing standards adoption. Batam island facilities serving Singapore-based multinationals face accelerating compliance documentation requirements.
Rubber Testing Equipment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across equipment fabrication and software analytics layers. The vendor base separates between European calibration service networks and Asian hardware fabricators. Three archetypes dominate: integrated rheometer specialists, universal testing machine commoditizers, and cloud analytics platform builders. Consolidation pressure concentrates among calibration service providers, while hardware fabrication fragments across Chinese industrial zones.
Within the European service-anchored tier, MonTech Rubber Testing Solutions and Alpha Technologies exemplify long-term calibration contract strategies. TA Instruments occupies a position among thermal analysis specialists serving polymer research institutions. Zhengzhou-based fabricators and Dongguan equipment builders represent the scale-driven hardware commoditization vector.
| Leading Market Players |
|---|
| MonTech Rubber Testing Solutions |
| Elektron Technology |
| Alpha Technologies |
| Gibitre Instruments |
| BUZULUK |
| TA Instruments |
| Goettfert Inc |
| U-CAN DYNATEX INC |
| Qualitest |
| Others |
Value Chain & Pricing Dynamics
Tier-1 automotive suppliers in Stuttgart and Munich concentrate procurement authority for metrologically traceable systems, anchoring value-based pricing around equipment uptime guarantees and predictive maintenance outcomes rather than hardware transaction costs.
Pricing Analysis
Uptime-linked service contracts determine value capture for European rheometer vendors, with pricing stratifying across ISO 17025 calibration tiers, silica-silane formulation complexity, and bundled software analytics depth. Chinese universal testing machine imports from Shenzhen compress margins on legacy mechanical testing lines. Vietnamese tire manufacturers exhibit highest price sensitivity, deferring to third-party calibration specialists to avoid OEM service premiums.
Supply Chain Analysis
Polymer rheologist scarcity in Germany and the United States constrains final assembly capacity for precision instrumentation, forcing vendors to draw from Czech and Hungarian technical labor pools. Precision load cells and torque transducers feed from Swiss and Japanese component specialists. Single-source vulnerability concentrates in high-frequency oscillatory drive systems. Distribution runs through direct sales teams for automotive OEMs and regional distributors for quality control laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where ECHA REACH substance restrictions erect capital barriers that favor incumbents with validated measurement chains and captive calibration infrastructure.
For Market Incumbents: To counter margin compression from Dongguan equipment imports, deepen backward integration into precision sensor manufacturing and expand captive calibration laboratory networks across Southeast Asian tire production clusters. Prioritize ISO 17025 accreditation investments that lock in long-term service contracts with automotive OEMs. For New Entrants and Emerging Players: EU tire-labeling enforcement in Vietnam and Indonesia opens a window for cloud-based rheometer analytics platforms that bypass capital-intensive hardware fabrication. Target conveyor belt and sealing compound manufacturers in Java lacking thermal analysis infrastructure. Lead with software-defined remote diagnostics to circumvent established European service networks. For Investors and Strategic Acquirers: The window for entry favors calibration service specialists with regional density in Southeast Asia over hardware fabricators facing Chinese commoditization. Monitor Indonesian national industrial ministry standards adoption as an inflection signal for mandatory testing infrastructure buildout. Long-term viability rests on recurring revenue capture from compliance-driven batch validation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Sensors | Secures supply of torque transducers from Swiss specialists for rheometer assembly. |
| Calibration Laboratory Network Expansion | Captures recurring revenue from REACH-mandated batch validation in Binh Duong province. |
| Cloud Analytics Platform Launch | Enables predictive maintenance contracts for Vietnamese tire manufacturers in Ho Chi Minh City. |
| ISO 17025 Accreditation Investment | Qualifies equipment for PPAP submissions to Stuttgart automotive OEM laboratories. |
| Joint Venture with Indonesian Distributor | Accesses conveyor belt manufacturers in Java lacking sophisticated thermal analysis infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving polymer rheologists, tire manufacturer laboratory managers, ECHA compliance officers, and aftermarket calibration service heads. ECHA substance restriction databases, ISO 23529 implementation records, and Vietnam customs import declarations provided triangulation points. Bottom-up equipment shipment tallies reconciled against top-down tire production capacity estimates.
Data-stream reconciliation across instrument category, end-user vertical, and technology platform dimensions shaped the analytical framework over the projection horizon. CAGRs derived from regression against tire OEM certification timelines and REACH enforcement intensity curves. Silica-silane adoption rates and cloud analytics penetration served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for software-defined rheometry would alter the outlook. Forecasts reflect assumptions regarding ECHA enforcement consistency and Southeast Asian tire export growth trajectories. Material deviation in REACH Annex XVII microplastic restriction timelines or Indonesian national standards adoption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Silica Analyzer Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Global Analytical Standards Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
Global Film Thickness Measurement Market