
 Engine Oil and Lubricant Market | 2026-2036
Engine Oil and Lubricant Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Oil and Lubricant Market Insights
API SP and ILSAC GF-6 specification upgrades is redrawing competitive positioning across the engine oil and lubricant market. Shell leverages its integrated gas-to-liquids base oil production to secure supply continuity for premium synthetics. ExxonMobil anchors its position through proprietary metallocene polyalphaolefin technology that extends drain intervals in severe-service applications.
Engine oils and lubricants are formulated blends of base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines and mechanical systems, with viscosity grades such as 0W-20 and 5W-30 defining cold-start flow and high-temperature film strength. Synthetic formulations command widening preference among OEM fill programs and fleet operators seeking extended drain intervals and fuel economy gains. Mineral oils retain volume dominance in emerging markets where price sensitivity shapes procurement patterns. Marine applications represent a specialized margin pool governed by IMO 2020 sulfur caps and cylinder oil alkalinity requirements.
EPA emissions standards, the EU F-Gas Regulation, and API certification protocols collectively dictate additive chemistry limits, volatility thresholds, and market access conditions for lubricant suppliers operating in North America and Europe. REACH compliance in the European Union restricts certain boron and phosphorus compounds, forcing additive houses to reformulate anti-wear packages. Stakeholders must monitor base oil Group II+ and Group III capacity expansions in Asia, as these supply additions will determine regional pricing power and blend economics through the forecast horizon.
Market Dynamics
Synthetic base oil capacity expansion in China and the Middle East is compressing traditional supply hierarchies, while API SP and ILSAC GF-6 specifications force additive package reformulations that favor integrated producers with captive base stock supply.
Growth Catalysts
- Commercial Fleet Electrification Readiness:Hybrid powertrain proliferation sustains demand for thermal-stable lubricants with electrical conductivity control, extending synthetic penetration in heavy-duty segments.
- EU F-Gas Regulation:Volatility limits on refrigerant-lubricant compatibility drive reformulation of compressor oils, creating specification premiums for low-VI-loss synthetics.
- Marine Cylinder Oil Alkalinity:IMO 2020 sulfur compliance sustains specialized high-BN lubricant demand in two-stroke engines, insulating marine blenders from automotive commoditization.
Market Restraints
- Group III Base Oil Concentration:Middle Eastern and South Korean refiners control 60% of high-viscosity-index capacity, exposing blenders to freight-driven cost volatility.
- REACH Boron Restrictions:ECHA limitations on boron-containing anti-wear additives force additive houses to rebuild boundary lubrication chemistry from phosphorus and sulfur compounds.
- Extended Drain Intervals:OEM fill programs specifying 15,000-mile synthetic service compresses lubricant volume per vehicle-mile by 40% versus conventional 3,000-mile mineral programs.
Strategic Opportunities
- India Two-Wheeler Synthetic Conversion:BS-VI emission standards and OEM fill mandates create first-mover advantage in a market still 70% mineral-dominant.
- Re-refined Base Oil Integration:Circular economy incentives under EU Green Deal funding position used-oil collection networks as captive feedstock sources for sustainable lubricant lines.
- Data Center Immersion Cooling:Dielectric fluid demand from hyperscale server farms represents a greenfield application with thermal management specifications distinct from automotive norms.
Industry Challenges
- Additive Chemist Talent Scarcity:Reformulation of anti-wear and dispersant packages for new base oil groups requires expertise in tribology and surface chemistry that outpaces university pipeline output.
- API Certification Timeline Compression:Sequence VI and Sequence VIII engine test availability constraints delay product launches by 18-24 months, freezing working capital in pre-certified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Oil and Lubricant Market |
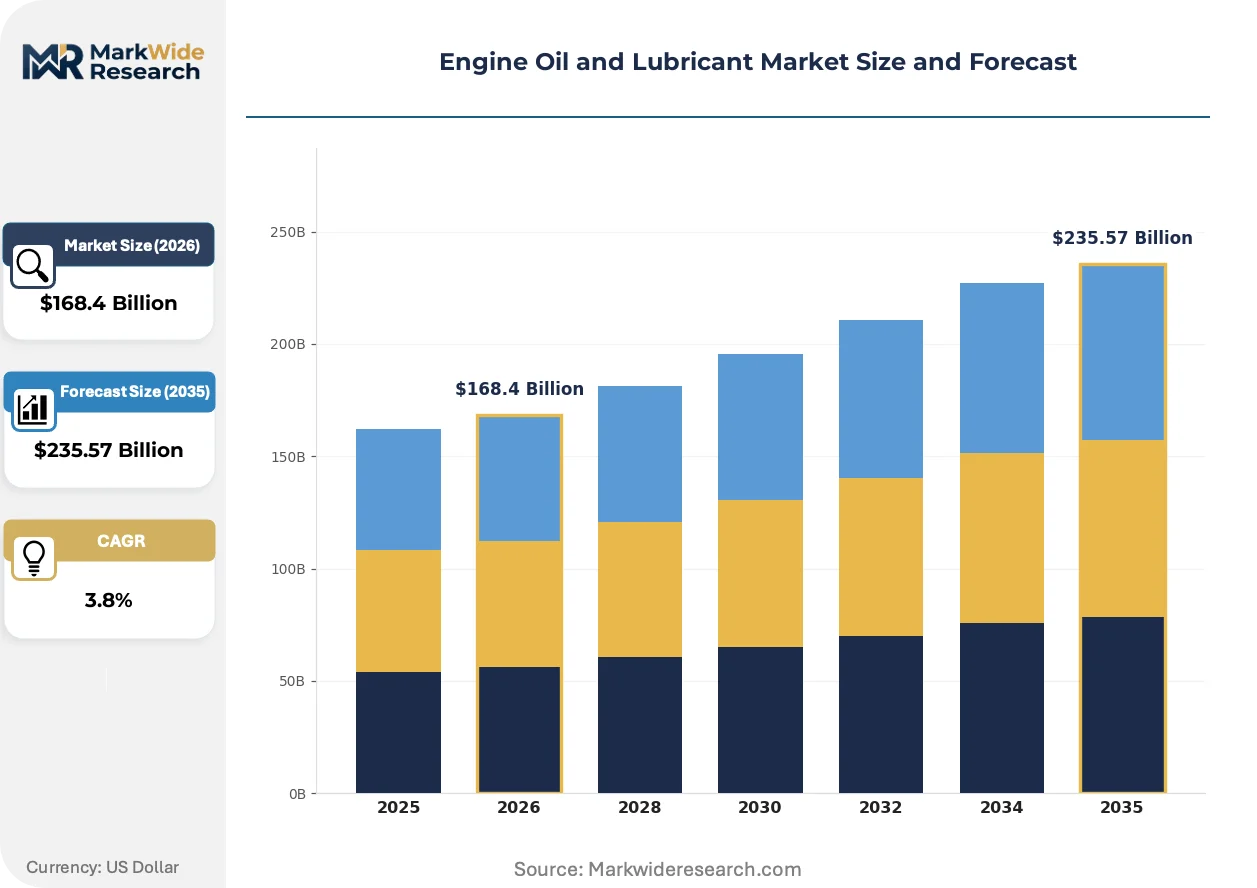
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $235.57 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based Application: Passenger Vehicles, Commercial Vehicles, Industrial Equipment, Marine Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Bottles, Drums, Pails, Bulk |
| Companies Covered | Shell, ExxonMobil, BP, Chevron, TotalEnergies, PetroChina, Sinopec, Fuchs Petrolub, Lukoil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Oil and Lubricant Market Trends and Innovations
Formulation science is pivoting from viscosity-grade competition to additive-package differentiation, with electrification compatibility and circular feedstock traceability emerging as the new axes of technical positioning.
Polyalkylene glycol (PAG) base stocks are fragmenting the compressor lubricant segment. HVAC and refrigeration OEMs specify PAGs for CO2 and HFO refrigerant compatibility under EU F-Gas phase-down schedules. The technology is fragmenting supplier relationships as traditional mineral-oil blenders lack PAG synthesis capability and must source from chemical specialists.
EPA Tier 3 and California LEV III emission standards tighten volatility limits on crankcase lubricants to protect gasoline particulate filters. The rules compress allowable Noack evaporation loss from 15% to 13%, forcing Group II+ and Group III base oil blends in applications previously served by Group I stocks. Passenger car motor oil producers in the US and Canada face reformulation costs or market exit.
Fleet maintenance departments are consolidating lubricant specifications across mixed-vehicle portfolios to reduce inventory SKUs and technician training burden. Bulk procurement agreements with national distributors displace jobber-supplied packaged goods in North American Class 8 trucking. The consolidation is most visible in US for-hire trucking, where megafleets specify single synthetic grade for diesel and gasoline powertrains alike.
Engine Oil and Lubricant Market Segmentation
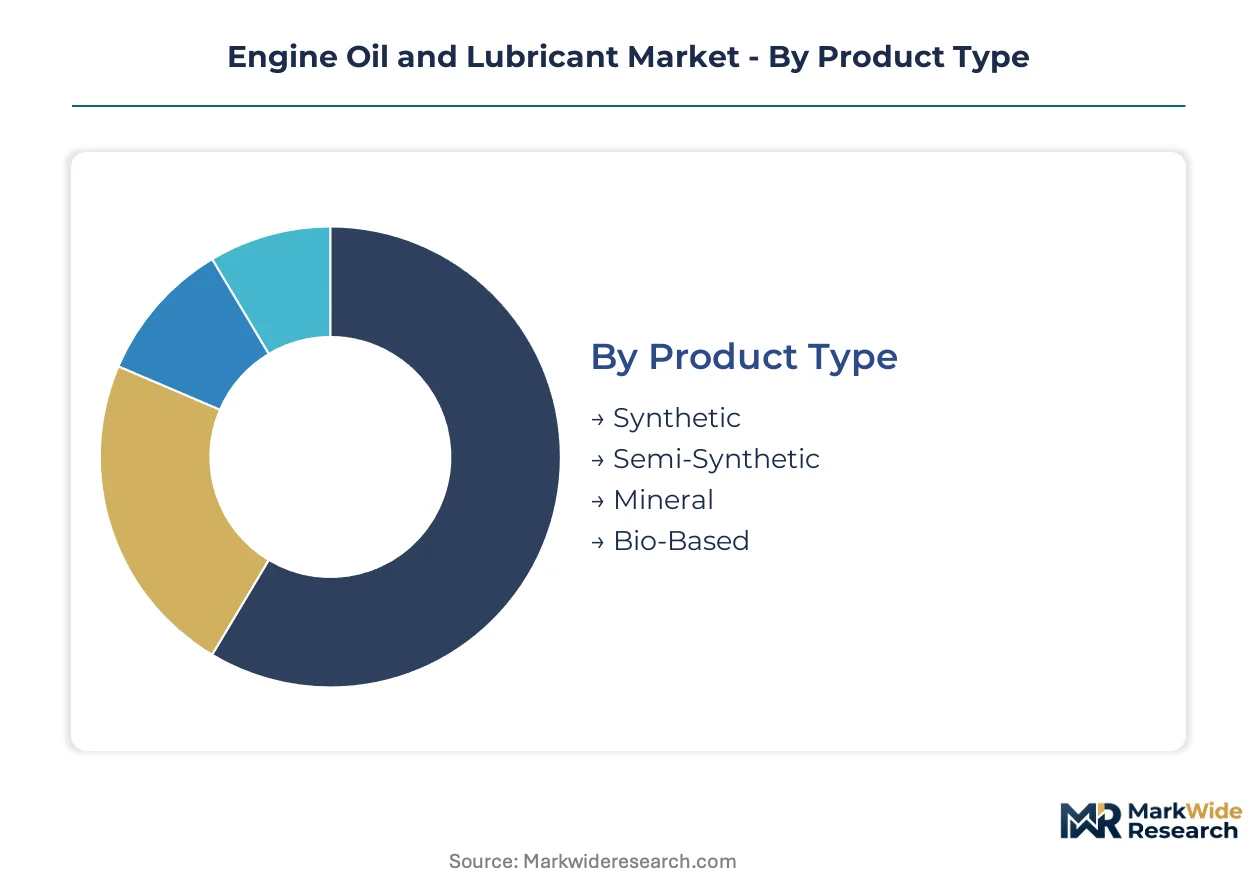
Segmentation in the engine oil and lubricant market determines formulation priorities, channel economics, and margin capture. Product type and viscosity grade dictate base oil sourcing and additive chemistry investment. Application verticals shape regulatory compliance requirements and service interval specifications.
Product Type:
Channel mix varies sharply by product type. Synthetic formulations flow predominantly through OEM fill programs and national fleet distributors. Mineral oils dominate jobber networks and aftermarket retail. Bio-based products concentrate in government procurement and sustainability-mandated corporate fleets.
- Synthetic:Formulated from Group III, Group IV (PAO), or Group V (ester/PAG) base stocks with precisely engineered additive packages for extended drain intervals and severe-service thermal stability. Demand concentrates in North American and European commercial fleet operators pursuing 15,000-mile service cycles under EPA and EU F-Gas volatility constraints.
- Semi-Synthetic:Blends mineral and synthetic base stocks, typically 30% synthetic content, balancing cost and performance for mid-tier passenger vehicle service. European independent workshops and quick-lube chains specify these grades for vehicles outside OEM warranty periods.
- Mineral:Refined petroleum base stocks with conventional additive treatment, serving price-sensitive markets and older equipment specifications.
- Bio-Based:Vegetable oil or synthetic ester formulations with biodegradability credentials for environmentally sensitive applications.
Mineral dominates installed base. Synthetic is where expansion concentrates.
Application:
Cost tier stratification separates application segments. Marine and industrial command premium pricing for specialized formulations. Passenger vehicles operate on thin margins with high volume velocity. Commercial vehicles sit at the intersection of price sensitivity and performance requirements.
- Passenger Vehicles:Light-duty gasoline and diesel engines requiring API SP or ILSAC GF-6 certified lubricants with gasoline particulate filter compatibility. OEM fill programs in Germany, Japan, and the United States specify 0W-20 and 5W-30 synthetics to meet EPA Tier 3 and California LEV III emission standards.
- Commercial Vehicles:Heavy-duty diesel engines operating under severe load cycles with extended drain interval requirements. Fleet consolidation in US for-hire trucking drives bulk procurement of single synthetic grades across mixed powertrain portfolios.
- Industrial Equipment:Hydraulic systems, compressors, and gearboxes requiring ISO viscosity grades and specialized additive packages for contamination tolerance.
- Marine:Two-stroke and four-stroke engines subject to IMO 2020 sulfur caps and cylinder oil alkalinity specifications.
Passenger vehicles generate highest volume throughput. Marine sustains the steepest expansion trajectory in margin per liter.
Viscosity Grade:
Geographic climate patterns determine viscosity grade distribution. Cold-start regions favor low winter ratings. High ambient temperature zones sustain multigrade demand with elevated high-temperature performance.
- 0W-20:Ultra-low viscosity formulation for modern gasoline direct injection engines with tight bearing clearances and fuel economy targets. Japanese and US OEM fill programs specify this grade for hybrid powertrains requiring thermal stability and electrical conductivity control.
- 5W-30:Versatile multigrade balancing cold-start pumpability and high-temperature film strength. European OEM specifications and North American quick-lube channels standardize on this grade for broad vehicle coverage.
- 10W-40:Higher viscosity reserve for older engines and high-temperature operating environments.
- 15W-50:Maximum film strength for performance engines and severe-service applications.
5W-30 dominates installed base. 0W-20 is where expansion concentrates.
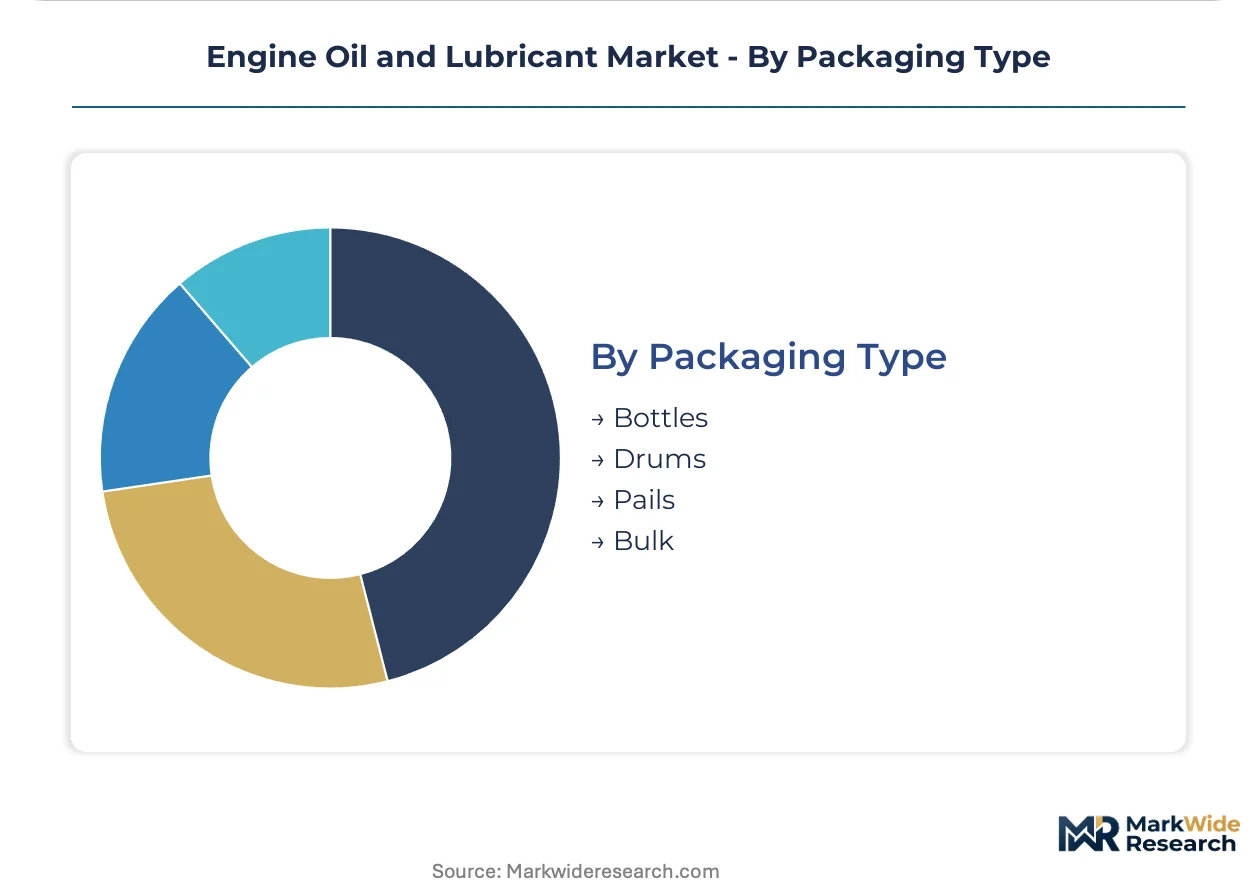
Packaging Type:
Customer type and procurement scale determine packaging mix. National fleets and industrial accounts bypass packaged goods entirely. Independent repair shops and retail consumers drive bottle and pail demand.
- Bottles:Retail consumer packaging in 1-quart and 5-quart configurations for DIY maintenance and top-off applications.
- Drums:55-gallon steel containers for fleet maintenance facilities and industrial lubricant dispensing systems.
- Pails:5-gallon plastic containers bridging retail and commercial volume requirements.
- Bulk:Tanker or tote delivery direct to fleet terminals and manufacturing plants with on-site storage and dispensing infrastructure.
Bulk dominates commercial volume. Bottles is where retail margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net trade positions diverge sharply across major lubricant economies. The United States and Germany maintain structural deficits in Group III and PAO base stocks, importing from Middle Eastern and South Korean refiners. China and India run surpluses in mineral oil blending while scrambling to build synthetic capacity.
United States
Class 8 trucking fleets in Texas and the Midwest drive synthetic diesel engine oil procurement through bulk terminal agreements. EPA Tier 3 volatility limits force reformulation of passenger car motor oils for gasoline particulate filter compatibility. Houston-Gulf Coast petrochemical complexes host additive blending operations serving North American OEM fill programs.
China
State-owned Sinopec and PetroChina expand Group III capacity at Zhejiang and Guangdong refineries to reduce import dependence. The country's dual carbon goals accelerate synthetic lubricant adoption in electric hybrid powertrains. Yangtze River Delta manufacturing clusters concentrate domestic blending capacity for regional automotive OEMs.
Germany
Industrial machinery exporters in Baden-Württemberg and Bavaria sustain premium hydraulic fluid demand with extended drain specifications. REACH boron restrictions force additive houses to reformulate anti-wear chemistry for boundary lubrication. KBA vehicle type-approval protocols mandate ILSAC GF-6 and ACEA C-series certification for OEM fill programs.
India
BS-VI emission standards and two-wheeler OEM fill mandates open synthetic conversion opportunities in a mineral-dominant market. The country's PLI scheme for automotive components indirectly supports lubricant specification upgrades. Maharashtra and Gujarat industrial corridors concentrate blending capacity for commercial vehicle and tractor applications.
South Korea
SK Innovation and GS Caltex control high-viscosity-index Group III exports to Asian and European blenders. Domestic automotive OEMs specify ultra-low viscosity grades for hybrid powertrain thermal management. Ulsan petrochemical complexes supply base stocks to lubricant formulators across Northeast Asia.
Engine Oil and Lubricant Market Competitive Landscape
Concentration sits with integrated oil majors possessing captive base stock production and global additive technology licensing. The market structure splits between full-spectrum suppliers running gas-to-liquids and metallocene PAO synthesis, regional refiners leveraging Group II+ capacity expansions, and specialized marine-industrial blenders. Three archetypes dominate: vertically integrated energy majors, Asian state-controlled refiners, and European technical specialists. Competitive moves center on synthetic base oil capacity additions in Asia and additive package reformulations for electrification compatibility.
Within the integrated major tier, Shell and ExxonMobil exemplify divergent synthetic supply strategies—Shell through Qatar-based gas-to-liquids integration, ExxonMobil through proprietary metallocene catalysis. BP and TotalEnergies occupy positions emphasizing low-carbon lubricant lines and re-refined base oil circularity. Among state-controlled Asian producers, PetroChina and Sinopec represent capacity-led expansion into Group III and domestic synthetic blending. Fuchs Petrolub anchors the European specialist archetype with technical service depth in industrial and automotive applications.
| Leading Market Players |
|---|
| Shell |
| ExxonMobil |
| BP |
| Chevron |
| TotalEnergies |
| PetroChina |
| Sinopec |
| Fuchs Petrolub |
| Lukoil |
| Others |
Pricing and Supply Chain Analysis
Sixty-day inventory cycles among European blenders signal supply-chain rigidity that amplifies pricing power for Middle Eastern Group III producers during freight volatility spikes. This lead-time compression concentrates procurement leverage with integrated majors possessing captive base stock synthesis.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scaled rebates and certification-grade premiums. Pricing stratifies across premium synthetic, standard semi-synthetic, and economy mineral tiers. Cost compression in the mineral segment intensifies because Asian state refiners flood Group II capacity into spot markets. Fleet operators show least price sensitivity due to total-cost-of-ownership calculations, while independent jobbers remain most exposed to margin erosion.
Supply Chain Analysis
Inventory cycles stretching past industry norms expose blenders to feedstock cost volatility between order placement and formulation. Supply concentrates in South Korea, the United Arab Emirates, and the United States for high-viscosity-index base stocks. Formulation chemistry draws from polyalphaolefin, metallocene catalyst systems, and sulfur-capped additive packages. Single-source vulnerability runs through Middle Eastern Group III export terminals. Distribution runs through national fleet distributors and OEM fill programs, bypassing traditional jobber networks for synthetic volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as synthetic penetration in commercial fleets and hybrid powertrains accelerates specification upgrades faster than volume commoditization.
For Market Incumbents: Shield formulation margins by securing captive Group III supply through Qatar or South Korean offtake agreements. Deepen technical service relationships with Class 8 fleet maintenance directors to lock out mineral-oil jobbers. The priority lever sits in additive package patents for electrification-compatible thermal management.
For New Entrants and Emerging Players: Differentiate on circular feedstock traceability and re-refined base oil certification under EU Green Deal procurement mandates. The most penetrable white space sits in Indian two-wheeler synthetic conversion where BS-VI compliance creates first-mover specification advantages. A direct technical sales force targeting OEM fill program engineers bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because additive chemistry talent scarcity and API certification bottlenecks favor scaled producers with R&D depth. Acquisition targets should display captive base stock supply or patented low-volatility formulation libraries. The signal to watch is Sequence VI and Sequence VIII engine test availability constraints extending product launch timelines.
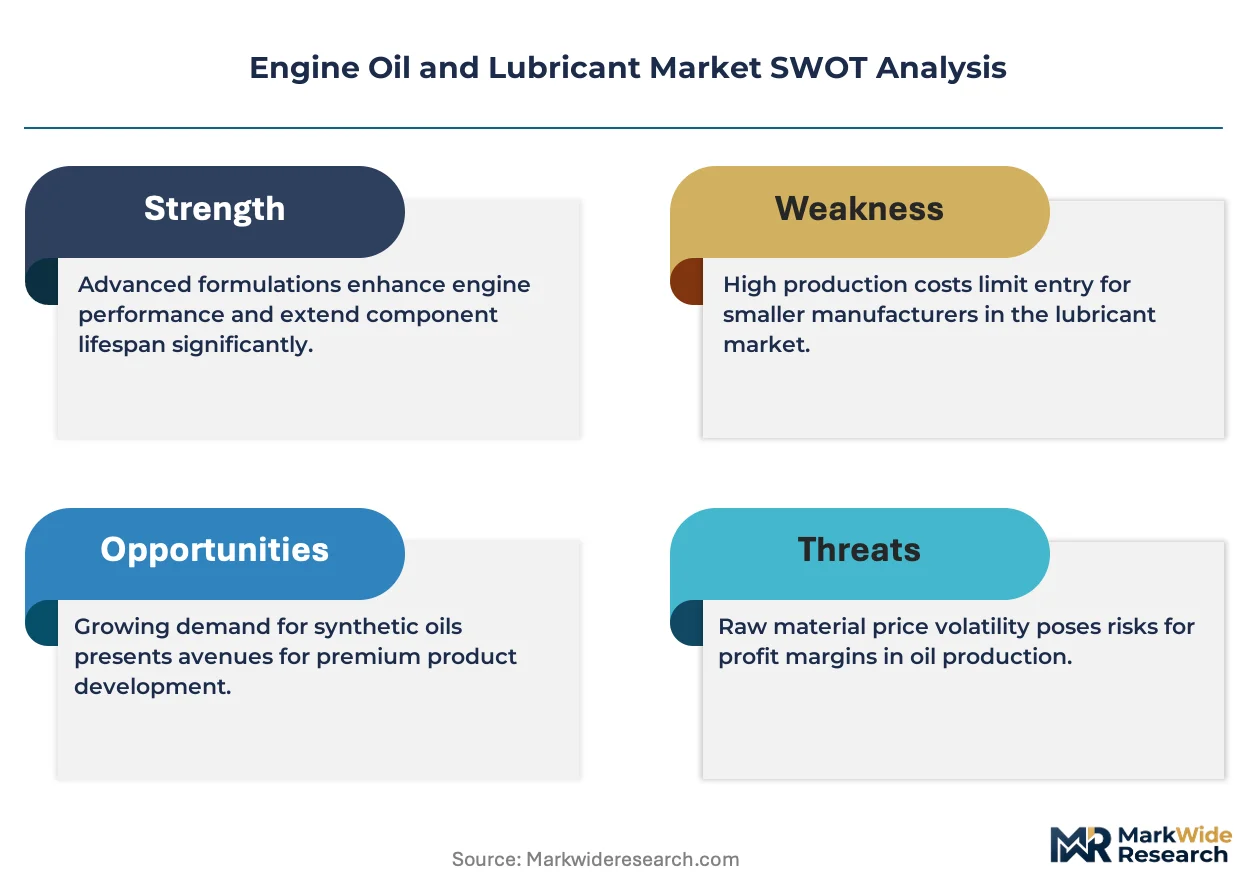
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Production | Captive supply from Qatar gas-to-liquids facilities secures formulation continuity against freight volatility. |
| API SP Certification Investment | Sequence VI and VIII test access unlocks OEM fill programs in EPA Tier 3 jurisdictions. |
| Re-refined Base Oil Supply Agreement | EU Green Deal funding positions circular feedstock networks as sustainable line differentiators. |
| Long-term Fleet Distribution Contract | Bulk terminal agreements with US for-hire trucking megafleets displace jobber-sourced packaged goods. |
| Joint Venture for PAG Synthesis Capability | HVAC OEM specifications for CO2 refrigerant compatibility fragment traditional mineral-oil supplier relationships. |
Research Methodology
Operator-level perspectives from lubricant plant managers, fleet procurement directors, additive house R&D leads, and OEM fill program engineers anchored the qualitative base. These interviews combined with customs trade data, API certification registries, SEC filings from integrated majors, and REACH compliance databases. Bottom-up volume triangulation against top-down refinery capacity assessments validated segment-level outputs.
Sensitivity analysis across base oil price scenarios and regulatory timing variations shaped the projection framework. The model segmented by product type, viscosity grade, application vertical, and regional production hub. CAGRs derived from elasticity-adjusted demand curves and capacity expansion schedules. Key inputs included OEM drain interval specifications and IMO marine sulfur compliance trajectories.
The analysis sits within stated boundaries; outcomes outside sustained synthetic adoption rates or accelerated electrification penetration would require recalibration. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock cost stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Argentina Lubricants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Germany Automotive Lubricants Market
Lubricants
High Performance Lubricants Market
Lubricants
Mexico Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Hydro Lubricants Market
Lubricants
Specialty Lubricants Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
India Lubricants Market