
 Canada Lubricants Market | 2026-2036
Canada Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Lubricants Market Outlook
Alberta is tilting toward expanded blending capacity to serve oil sands and mining demand. Petro-Canada Lubricants leverages its domestic refinery network to anchor supply security for western Canadian resource operations. Imperial Oil Canada Limited dominates retail and commercial channels through its Esso-branded service station footprint. Shell plc competes in the industrial segment with synthetic formulations tailored to cold-climate performance.
Lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically spanning ISO VG 32 through 680 for industrial applications and SAE 5W-30 through 15W-40 for automotive engines. Their primary purpose is extending equipment life and optimizing energy efficiency across machinery operating under variable temperature and load conditions. Engine oils command the largest product type share given Canada's substantial passenger vehicle and heavy-duty fleet population, while industrial oils generate premium margin pools in mining and steel processing. The aftermarket provider channel sustains higher volumes than OEM direct supply, though fleet operator contracts deliver more predictable offtake.
Health Canada and PMRA oversee chemical hazard assessment and environmental release standards for lubricant formulations, while Environment and Climate Change Canada administers the Clean Fuel Regulations and toxic substance tracking under CEPA. These frameworks compel suppliers to shift toward Group III and Group IV base stocks and document biodegradability profiles. Stakeholders must monitor pending amendments to federal carbon intensity requirements and provincial extended producer responsibility programs that could reshape collection and re-refining economics.
Market Dynamics
Canada's Clean Fuel Regulations are forcing reformulation across the lubricants value chain, compressing demand for conventional Group I base stocks while elevating bio-based and Group III alternatives in mining and transportation applications.
Growth Catalysts
- Alberta Oil Sands Fleet Renewal:Mining operators in Fort McMurray and Cold Lake are extending heavy-duty equipment cycles, driving consumption of high-performance hydraulic and engine oils formulated for extreme load conditions.
- Clean Fuel Regulations:Environment and Climate Change Canada's carbon intensity mandates are accelerating adoption of lower-viscosity lubricants that reduce engine friction and improve fuel economy in commercial transportation.
- Synthetic Base Oil Conversion:Group III and Group IV base stocks are penetrating the industrial segment as steel processors and automotive manufacturers prioritize thermal stability and extended drain intervals.
Market Restraints
- Base Oil Import Concentration:Eastern Canadian blenders depend on US Gulf Coast refineries for Group II and Group III feedstock, exposing margins to cross-border pipeline capacity constraints and currency volatility.
- Re-refining Infrastructure Gap:Collection networks for used lubricants remain underdeveloped outside Ontario and Quebec, limiting circular feedstock availability for domestic re-refiners.
- Extended Producer Responsibility Costs:Provincial packaging and product stewardship programs in British Columbia and Ontario are adding compliance overhead for smaller independent distributors without scale economies.
Strategic Opportunities
- Saskatchewan Mining Corridor:Potash and uranium operations around Saskatoon represent an underserved industrial lubricant segment with concentrated fleet purchasing power and limited local blending presence.
- Marine and Rail Convergence:Bio-based lubricants meeting Vessel General Permit standards are penetrating Great Lakes shipping and CN/CP rail maintenance yards as dual-certification products.
- EV Thermal Fluid Positioning:Battery electric commercial vehicles require dielectric coolants and specialized greases, creating formulation white space ahead of fleet electrification timelines.
Industry Challenges
- Additive Chemist Shortage:Formulation expertise in ashless dispersant and anti-wear chemistry is concentrating at multinational suppliers, constraining domestic independent blender R&D capacity.
- CEPA Compliance Timeline:Substance categorization and new toxicity assessment requirements under the Canadian Environmental Protection Act are extending product registration cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Lubricants Market |
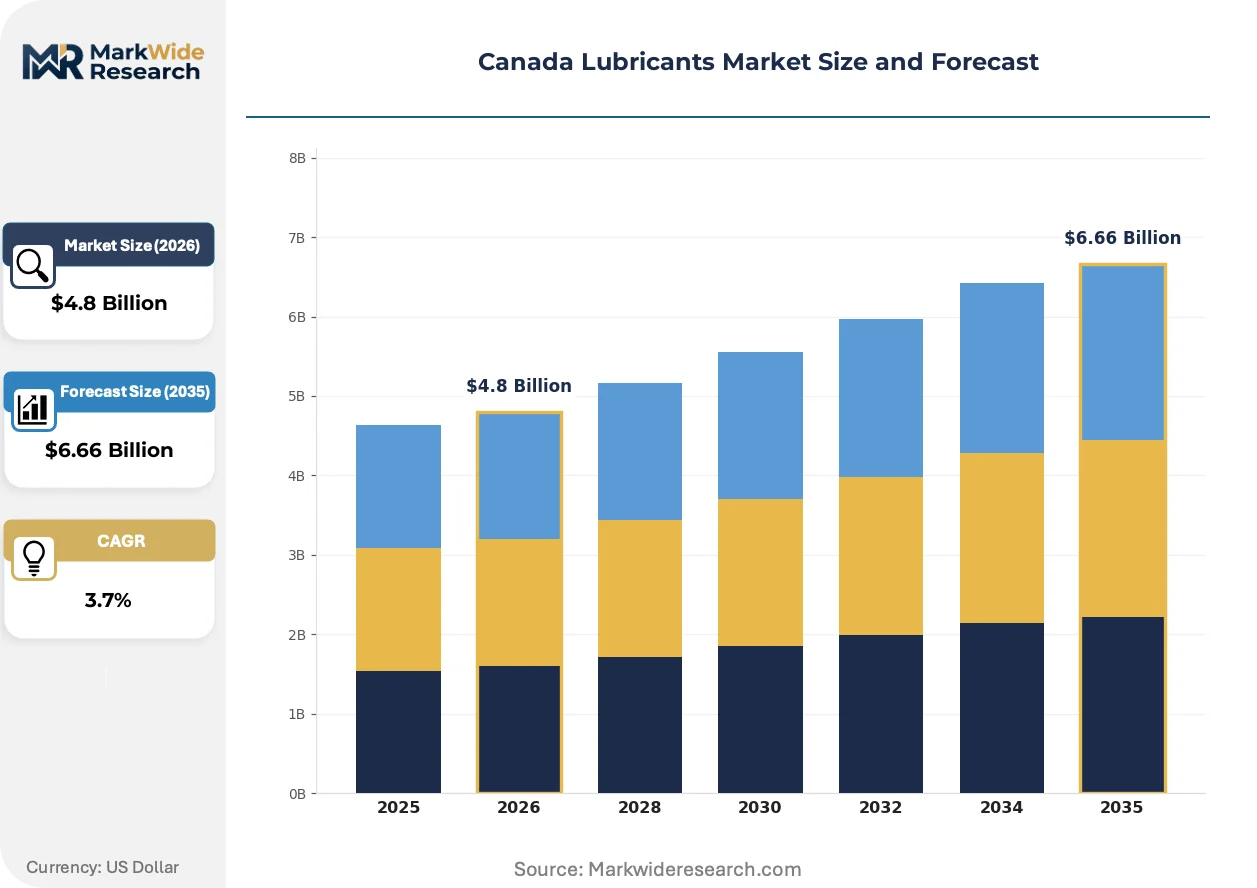
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Industrial Oils, Hydraulic Fluids, Greases Application: Automotive, Manufacturing, Marine, Aerospace End User: OEMs, Aftermarket Providers, Workshops, Fleet Operators Distribution Channel: Retail, Distributors, E-commerce, Direct Sales |
| Companies Covered | ExxonMobil Corporation, BP plc, Boss Lubricants, Valvoline Inc, TotalEnergies, Petro-Canada Lubricants, Shell plc, Imperial Oil Canada Limited, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Lubricants Market Strategic Shifts
Formulation science is converging with carbon accounting requirements, reshaping how base stock selection, additive chemistry, and end-use certification interlock in product development cycles.
Re-refined base oil technology is hybridizing with virgin Group III stocks to create certified sustainable lubricants that meet OEM warranty requirements while reducing Scope 3 emissions. Mining fleet operators in Alberta are piloting these blends for non-critical hydraulic systems. The hybridizing approach is compressing the price premium between circular and linear supply chains.
Health Canada and PMRA are tightening environmental release standards for lubricant formulations containing zinc dialkyldithiophosphate and other metal-based additives. Industrial oil suppliers must now submit expanded aquatic toxicity data for product registration renewals. The mining and steel processing segments are responding by accelerating trials of ashless anti-wear chemistries.
Fleet maintenance departments are consolidating lubricant purchasing through integrated supply contracts that bundle oil analysis, filtration services, and waste collection. Independent distributors in Ontario's manufacturing belt are losing share to direct manufacturer relationships. This concentration is most visible in Toronto-Hamilton corridor automotive parts plants and food processing facilities.
Canada Lubricants Market Segmentation
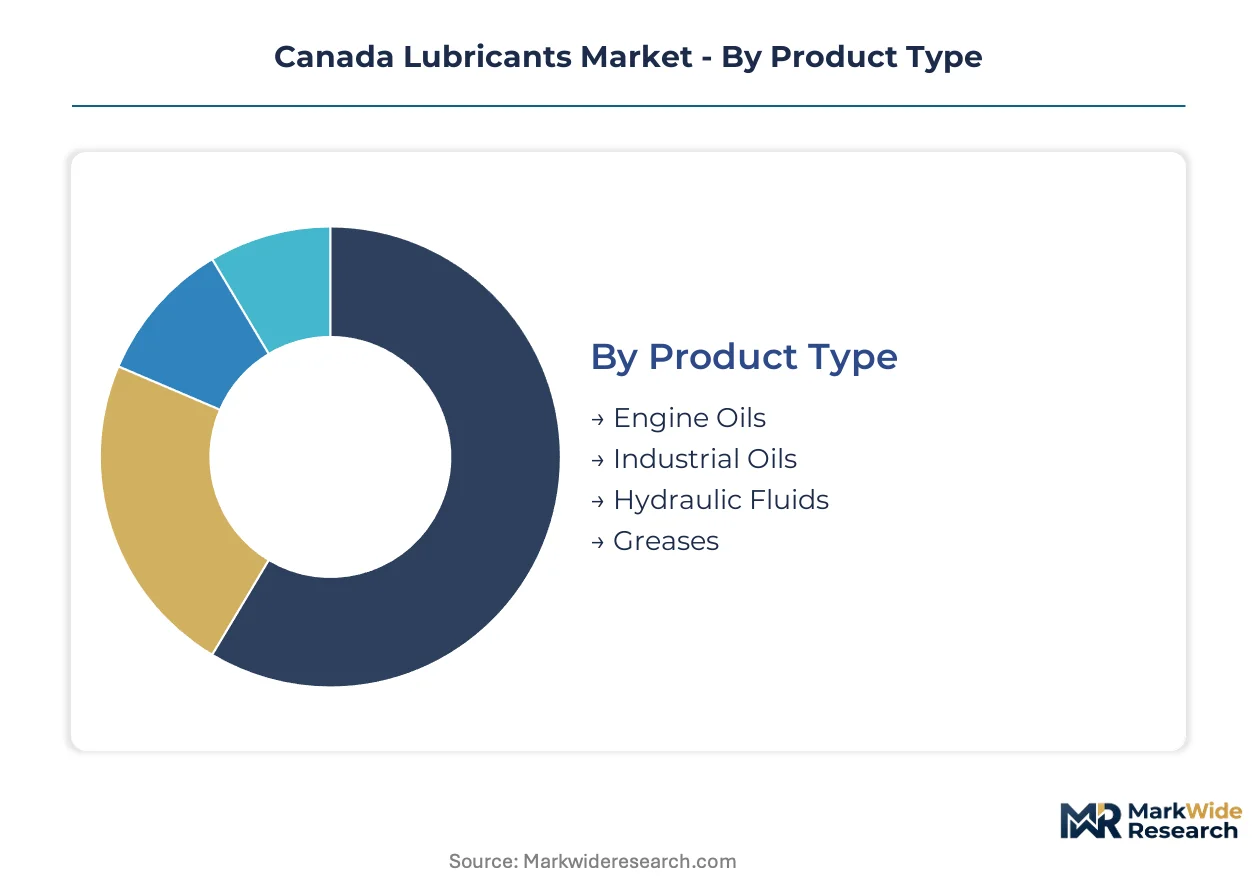
Segmentation in the Canada lubricants market reveals how formulation chemistry, procurement patterns, and regulatory compliance intersect differently across end-use environments. Understanding these divides clarifies where margin pools concentrate and where reformulation investments yield competitive defense.
Product Type:
The use-case spectrum spans combustion engine protection, industrial machinery longevity, power transmission efficiency, and friction reduction in sealed bearings.
- Engine Oils:Formulated from Group II through Group IV base stocks with viscosity modifiers and detergent packages meeting API SP and ILSAC GF-6 specifications. Demand concentrates in Alberta's oil sands haul truck fleets and Ontario's commercial transportation corridors, where extended drain intervals reduce maintenance downtime. Fleet operators in Fort McMurray negotiate bulk supply contracts tied to oil analysis programs.
- Industrial Oils:Circulating oils, compressor lubricants, and gear oils formulated for thermal stability under continuous load. Steel processors in Hamilton and Sault Ste. Marie specify synthetic formulations to withstand elevated operating temperatures. The segment commands premium pricing against mineral-based alternatives.
- Hydraulic Fluids:Anti-wear formulations with zinc-based or ashless additive chemistry for mobile and stationary equipment. Mining excavators and shovels in Saskatchewan potash operations consume high volumes with stringent cleanliness specifications.
- Greases:Thickened lubricants combining base oil with lithium, calcium, or polyurea soap structures for sealed bearing applications. Wind turbine maintenance in rural Ontario and rail wheel flange lubrication on CN/CP networks drive specialized demand.
Established volume favors Engine Oils; emerging adoption favors Industrial Oils as manufacturing electrification shifts thermal management requirements.
Application:
Cost tier differentiation separates commodity automotive volumes from specification-driven industrial premiums.
- Automotive:Passenger vehicle service fills and heavy-duty diesel engine oils dominate volume, with reformulation pressure from Clean Fuel Regulations driving lower-viscosity grades. Light-duty trucks in Quebec and British Columbia show accelerating 0W-20 and 5W-30 adoption.
- Manufacturing:Metalworking fluids, turbine oils, and compressor lubricants serving Ontario's automotive parts plants and food processing facilities. Toronto-Hamilton corridor manufacturers consolidate purchasing through integrated supply contracts bundling oil analysis and filtration services.
- Marine:Stern tube oils, two-stroke engine lubricants, and environmentally acceptable lubricants for Great Lakes shipping. Vessel General Permit compliance is pushing bio-based hydraulic fluid trials in St. Lawrence Seaway operations.
- Aerospace:Synthetic turbine oils and specialty greases for commercial aviation maintenance. Toronto Pearson and Vancouver International maintenance, repair, and overhaul facilities specify MIL-PRF-certified formulations with narrow supplier qualification.
Procurement concentration favors Manufacturing; specification complexity favors Aerospace.
End User:
Customer type determines contract structure, technical service intensity, and inventory risk allocation.
- OEMs:Factory-fill agreements with automotive and heavy equipment manufacturers specifying first-fill lubricants for warranty coverage. Engine and transmission plants in Ontario negotiate multi-year supply contracts with technical collaboration clauses.
- Aftermarket Providers:Independent distributors, jobbers, and retail chains serving fragmented vehicle and equipment owner bases. Volume concentration in Ontario and Quebec sustains national distribution network economics.
- Workshops:Quick-lube facilities and independent repair shops purchasing in bulk totes or drums. Alberta's mining service corridors and Vancouver's port maintenance clusters show workshop consolidation into franchise networks.
- Fleet Operators:Mining companies, trucking firms, and municipal vehicle pools with centralized procurement and used oil collection programs. Saskatchewan potash operators and Alberta oil sands haulers represent concentrated purchasing power with direct manufacturer relationships.
Margin stability favors Fleet Operators; volume scale favors Aftermarket Providers.
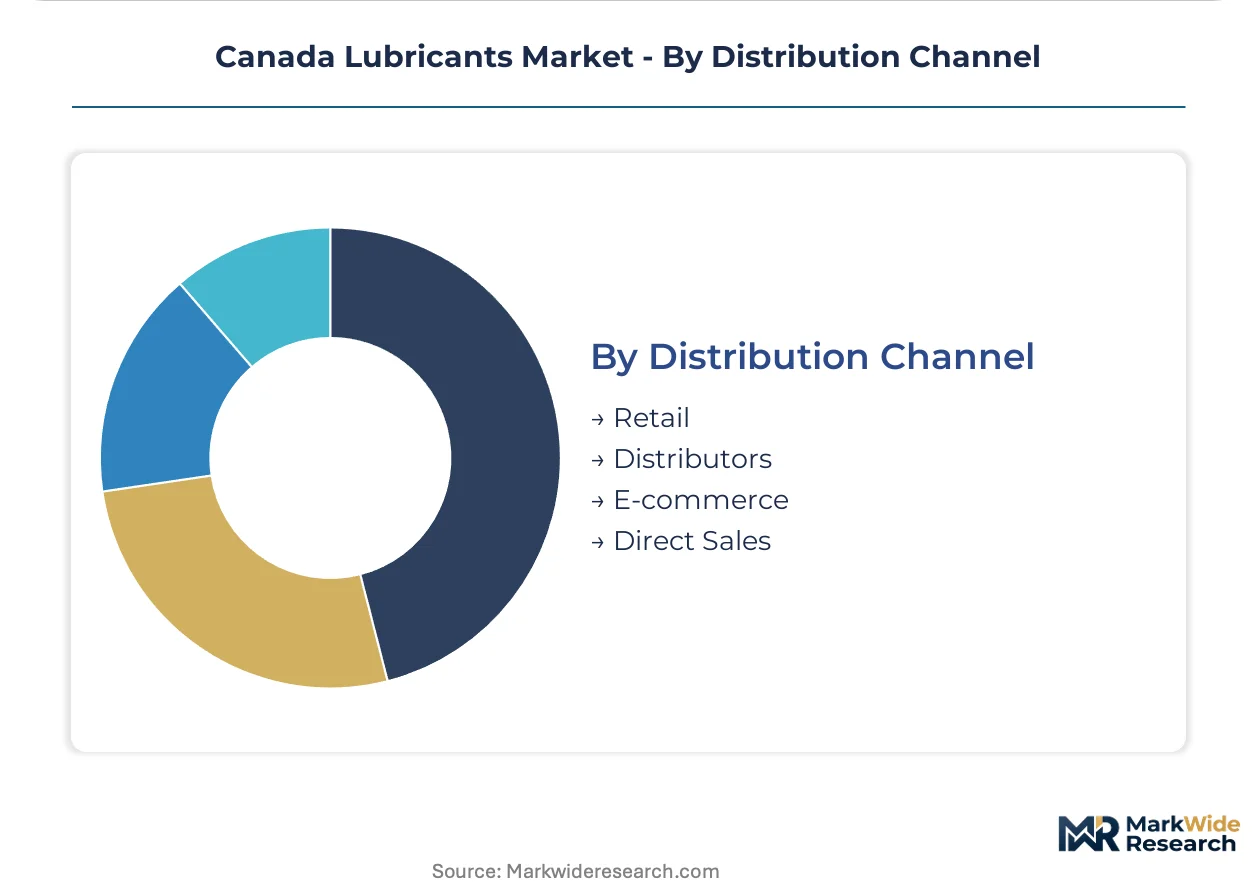
Distribution Channel:
Geography and customer density dictate channel economics, with urban concentration enabling scale and remote resource operations requiring direct logistics.
- Retail:Big-box automotive chains and farm supply stores serving DIY consumers and small commercial accounts. Ontario and Quebec population density supports national retail footprint economics.
- Distributors:Independent lubricant jobbers with blending, storage, and delivery capabilities serving industrial accounts. Western Canada distributor networks face margin pressure from direct manufacturer competition in mining segments.
- E-commerce:Direct-to-consumer and small commercial ordering with third-party logistics fulfillment. Growth concentrated in automotive DIY and specialty industrial formulations with low weight-to-value ratios.
- Direct Sales:Manufacturer field sales organizations serving large fleet and industrial accounts with technical service bundling. Alberta oil sands and Saskatchewan mining corridors show direct sales penetration above national averages.
Service intensity favors Direct Sales; reach efficiency favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans Mountain Pipeline expansion and CN/CP rail networks underwrite Canada's lubricant distribution architecture, linking Alberta base oil production to Ontario manufacturing clusters and Pacific Coast export terminals.
Ontario
Toronto-Hamilton corridor automotive parts plants and food processing facilities drive industrial oil consumption. Environment and Climate Change Canada's Clean Fuel Regulations enforce lower-viscosity formulations for commercial transportation fleets. Workshop consolidation into franchise networks is compressing independent distributor margins in the Golden Horseshoe.
Alberta
Oil sands haul truck fleets in Fort McMurray and Cold Lake consume high-performance hydraulic and engine oils for extreme load conditions. Health Canada and PMRA oversight of chemical hazard assessment shapes additive package selection for mining applications. Direct manufacturer relationships dominate procurement, bypassing traditional distributor channels in the Athabasca basin.
Quebec
Light-duty truck populations in Montreal and Quebec City show accelerating 0W-20 and 5W-30 adoption under carbon intensity mandates. The province's extended producer responsibility programs add compliance overhead for packaging and waste collection. Lubricant blending capacity concentrates around Montreal's petrochemical corridor.
British Columbia
Port maintenance clusters in Vancouver and Prince Rupert pilot bio-based hydraulic fluids meeting Vessel General Permit standards for marine applications. Provincial stewardship programs for used oil collection outpace Prairie infrastructure development. Mining equipment service yards in the interior support copper and coal operations with specialized grease formulations.
Saskatchewan
Potash and uranium operations around Saskatoon represent concentrated fleet purchasing power with limited local blending presence. The province's agricultural machinery base sustains seasonal demand spikes for tractor fluids and greases. Direct sales penetration runs above national averages as mining operators negotiate integrated supply contracts.
Canada Lubricants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry and base stock supply. The Canada lubricants market structures around three archetypes: integrated refinery-blenders with captive feedstock, multinational marketers with synthetic formulation portfolios, and independent distributors with regional logistics density. Consolidation pressure concentrates in the aftermarket channel as fleet operators bypass intermediaries. Strategic moves center on backward integration into base oil supply and forward integration into used oil collection networks.
Within the integrated refinery-blender tier, Petro-Canada Lubricants and Imperial Oil Canada Limited exemplify domestic supply security strategies. Shell plc occupies a multinational position with cold-climate synthetic portfolios. ExxonMobil Corporation anchors the global supermajor segment serving Canadian resource operations through direct technical service relationships.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| BP plc |
| Boss Lubricants |
| Valvoline Inc |
| TotalEnergies |
| Petro-Canada Lubricants |
| Shell plc |
| Imperial Oil Canada Limited |
| Chevron Corporation |
| Others |
Value Chain & Pricing Dynamics
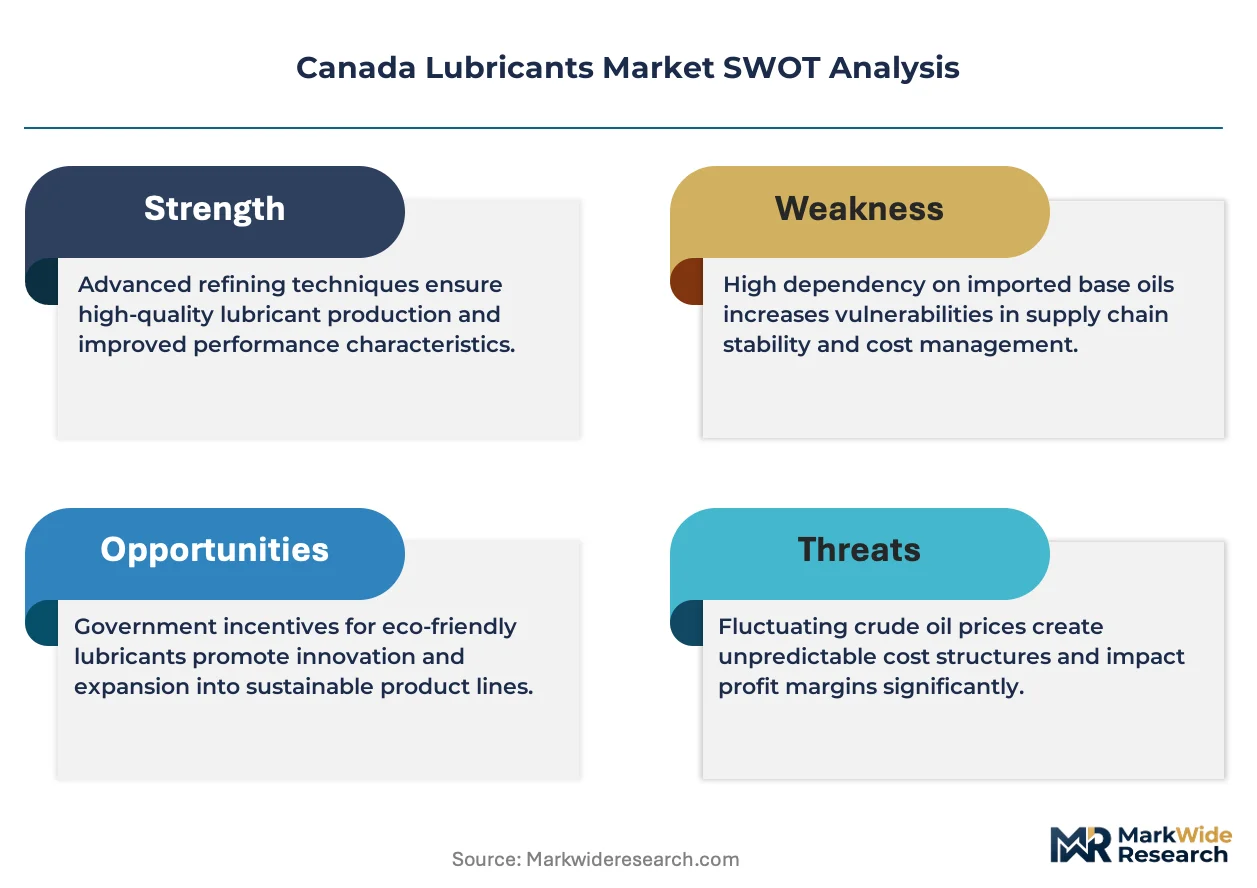
US Gulf Coast refinery concentration for Group II and Group III base stocks anchors cost structures for eastern Canadian blenders, pushing margin pools toward captive western supply and integrated direct-sales relationships with Alberta mining fleets.
Pricing Analysis
Environment and Climate Change Canada's Clean Fuel Regulations dictate the pricing tier structure across the Canada lubricants market. Three-tier pricing structure across premium synthetic, mid-tier Group III, and economy mineral formulations separates fleet operators seeking extended drain intervals from price-sensitive independent workshops. Cost compression in the standard tier is intensifying because currency volatility amplifies import feedstock exposure. Fleet operators in Alberta's oil sands corridor show least price sensitivity due to equipment downtime costs, while rural agricultural buyers in Saskatchewan exhibit highest elasticity.
Supply Chain Analysis
Export-control scrutiny on advanced additive chemistries limits cross-border flows of ashless dispersant packages and zinc-free anti-wear formulations. Feedstock draws from US Gulf Coast refineries, South Korean Group III producers, and domestic Alberta base oil output. Supply chain risk centers on single-source vulnerability for specialized hydraulic additives serving Saskatchewan potash operations. Distribution runs through direct manufacturer field sales for mining corridors, with independent distributors retaining Ontario-Quebec manufacturing belt coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation into integrated supply contracts has shifted bargaining power toward large-volume buyers, compressing intermediary margins and rewarding backward-integrated suppliers with captive base oil production.
For Market Incumbents: Harden defensible positions by securing captive Group III base oil supply through Alberta refinery network expansion and embedding oil analysis services into fleet maintenance contracts to lock out distributor competition. Threat from direct manufacturer relationships in mining segments demands technical service intensity as the counter-lever. Certification investment in bio-based formulations ahead of Vessel General Permit expansion protects premium positioning. For New Entrants and Emerging Players: Saskatchewan's potash and uranium mining corridor offers concentrated fleet purchasing power with limited local blending infrastructure, creating accessible white space for specialized hydraulic fluid suppliers. Marine bio-lubricant trials in British Columbia port clusters represent a specification-driven entry point with dual-certification potential for rail maintenance yards. Go-to-market through integrated supply contracts bundling waste collection addresses the re-refining infrastructure gap as differentiation. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale independent distributors with dense Ontario-Quebec logistics networks and established used oil collection relationships, positioned for consolidation into circular supply chains. Long-term viability hinges on re-refining infrastructure buildout and bio-based formulation capabilities over the coming decade. Watch for regulatory acceleration of extended producer responsibility programs as the inflection signal for collection network valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Alberta refinery output secures margin control against US Gulf Coast currency exposure for western Canadian mining demand. |
| Re-refining Infrastructure Expansion | Collection network buildout in Saskatchewan and Manitoba closes circular feedstock gaps for domestic sustainable lubricant production. |
| Bio-based Formulation Certification | Vessel General Permit compliance opens Great Lakes marine and CN/CP rail maintenance procurement to environmentally acceptable lubricant suppliers. |
| Direct Sales Force Expansion | Technical service bundling in Fort McMurray and Saskatoon mining corridors displaces traditional distributor relationships with integrated supply contracts. |
| Additive Chemistry R&D Partnership | Ashless anti-wear formulation collaboration addresses Health Canada tightening of zinc dialkyldithiophosphate environmental release standards. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, Environment and Climate Change Canada regulatory filings, and industry association production statistics. Primary interviews engaged lubricant formulation chemists, mining fleet procurement directors, industrial distributor operations managers, and aftermarket service network heads. Secondary validation drew from Canadian Energy Research Institute reports, base oil trade flow databases, and provincial extended producer responsibility program disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type and end-user segments.
Forecast inputs span equipment fleet renewal cycles in Alberta oil sands, Clean Fuel Regulations carbon intensity trajectory, synthetic base oil conversion rates in steel processing, and EV thermal fluid adoption timelines in commercial transportation. Segmentation dimensions modeled include product chemistry tier, end-use application intensity, procurement contract structure, and regional supply chain configuration. CAGRs derived from elasticity-adjusted demand projections and feedstock cost pass-through assumptions. Industry-specific inputs incorporate mining equipment utilization rates and automotive drain interval extension trends.
Macroeconomic conditions sit as an overlay; deviation in Canadian dollar exchange rates, US Gulf Coast refinery operating rates, or Prairie mining capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions on regulatory implementation timing and feedstock trade flow continuity. Material shifts in federal carbon intensity requirements or provincial stewardship program enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Construction Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Turkey Marine Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Global Grease Market
Lubricants
Mining Lubricants Market
Lubricants
Marine Grease Market
Lubricants
Firearm Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Kenya Lubricants Market