
 Mexico Commercial Vehicles Lubricants Market | 2026-2036
Mexico Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Commercial Vehicles Lubricants Market Foresight
Aftermarket service revenue is reshaping profit pools as fleet operators shift from transactional oil changes to contracted maintenance programs. ExxonMobil Corporation leverages its bulk supply infrastructure to anchor long-term fleet agreements across northern border states. Chevron Corporation competes through its distributor network density in central Mexico. Roshfrans sustains regional brand loyalty among independent transport operators through localized technical support.
Mexico commercial vehicles lubricants comprise formulated petroleum-based and synthetic fluids engineered to reduce friction, dissipate heat, and prevent wear in diesel and gasoline engines operating under high load cycles, with viscosity grades typically ranging from SAE 15W-40 to SAE 5W-30 for heavy-duty applications. Engine Oil commands the dominant product type position due to high consumption frequency in long-haul trucking, while Hydraulic Fluid captures expanding share from construction equipment attachments. Fleet Operators represent the most concentrated end user segment, with Logistics Providers driving fastest growth through e-commerce fulfillment networks requiring extended drain intervals.
SEMARNAT enforces environmental compliance on used oil collection and recycling, while NOM standards mandate minimum energy efficiency coefficients that favor synthetic and semi-synthetic formulations over conventional mineral oils. PROFECO monitors retail pricing transparency and product labeling accuracy across distribution channels. Stakeholders must evaluate formulation portfolios against impending emissions alignment with EPA-correlated standards for cross-border vehicle compatibility.
Market Dynamics
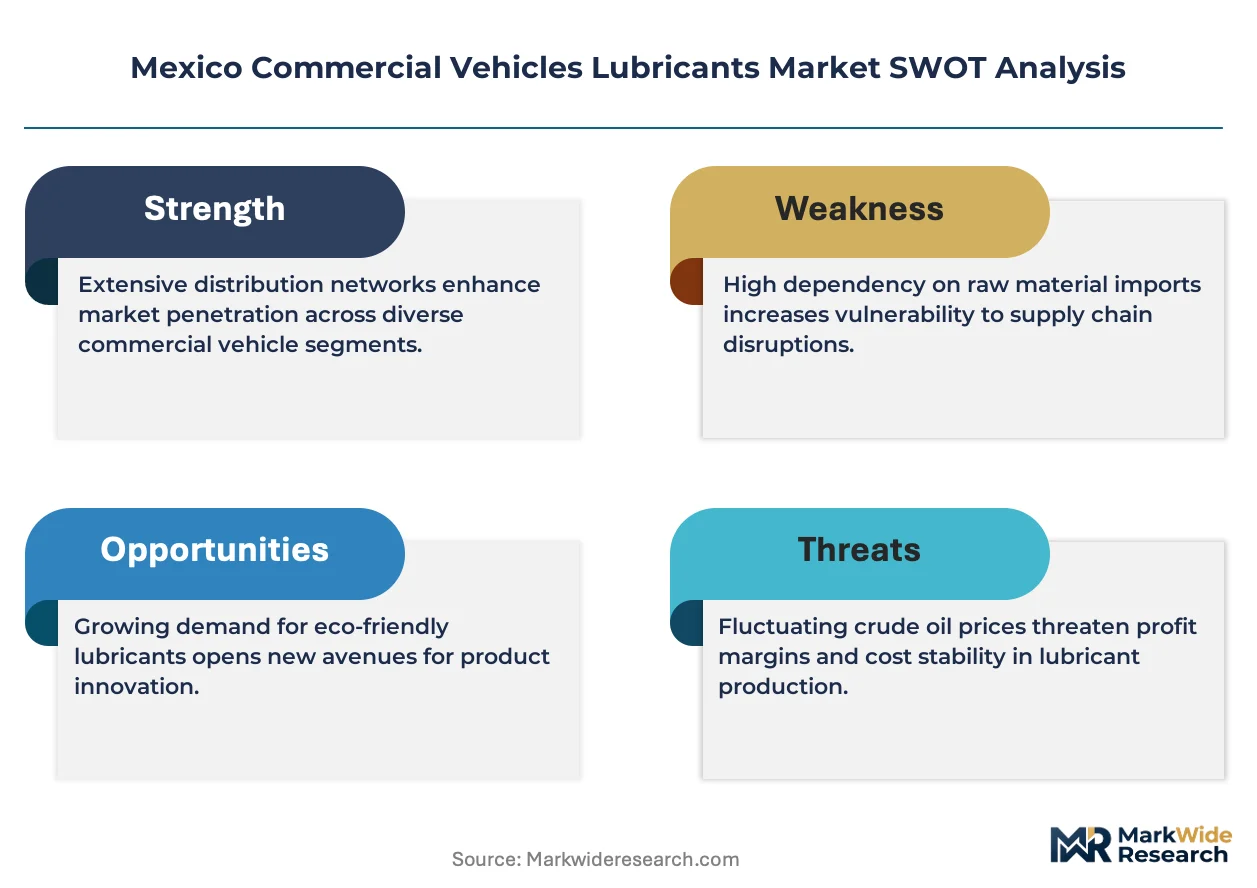
Fleet operators in Mexico's cross-border logistics corridors are consolidating procurement around extended-drain synthetic formulations as NOM energy efficiency standards tighten specifications and compress conventional mineral oil margins.
Growth Catalysts
- Nearshoring manufacturing expansion:Automotive OEMs relocating assembly capacity to Guanajuato and Querétaro are expanding captive fleet operations, creating concentrated demand nodes for bulk lubricant supply contracts.
- SEMARNAT enforcement protocols:Mandatory used oil collection and recycling quotas are forcing fleet operators toward higher-quality synthetics with longer service intervals to reduce waste volume compliance costs.
- Low-sulfur diesel transition:The nationwide shift to ULSD-compatible engine hardware is accelerating specification upgrades to API CK-4 and FA-4 categories that protect exhaust aftertreatment systems.
Market Restraints
- Base oil supply concentration:Mexico's Group II/III base oil production remains insufficient, forcing blenders to import from US Gulf Coast refiners and exposing margins to freight rate volatility.
- Additive package import dependency:Performance chemical formulations sourced from specialty chemical suppliers in Texas and Louisiana create working capital intensity and currency hedge requirements.
- Independent operator price sensitivity:Owner-operators running single-unit tractors in southern states resist premium synthetic pricing despite total-cost-of-ownership advantages, fragmenting volume concentration.
Strategic Opportunities
- Yucatán Peninsula logistics corridor:Port modernization at Progreso and expanding agro-export cold chain operations create greenfield fleet formation with no incumbent lubricant supplier relationships.
- Telematics-integrated oil analysis:Real-time viscosity and contamination monitoring via IoT sensors enables predictive drain interval optimization, shifting revenue from product sales to subscription diagnostics.
- NOM-052 alignment services:Technical consulting on energy efficiency coefficient documentation positions lubricant suppliers as compliance partners rather than commodity vendors.
Industry Challenges
- Used oil collection infrastructure gaps:SEMARNAT-certified recycling capacity concentrates in Mexico City and Monterrey, forcing fleet operators in Baja California and Chiapas to bear elevated logistics costs for compliance.
- Cross-border specification harmonization:EPA-correlated emissions standards for US-destined freight create dual-inventory complexity for bi-national fleet operators managing mixed engine generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Commercial Vehicles Lubricants Market |
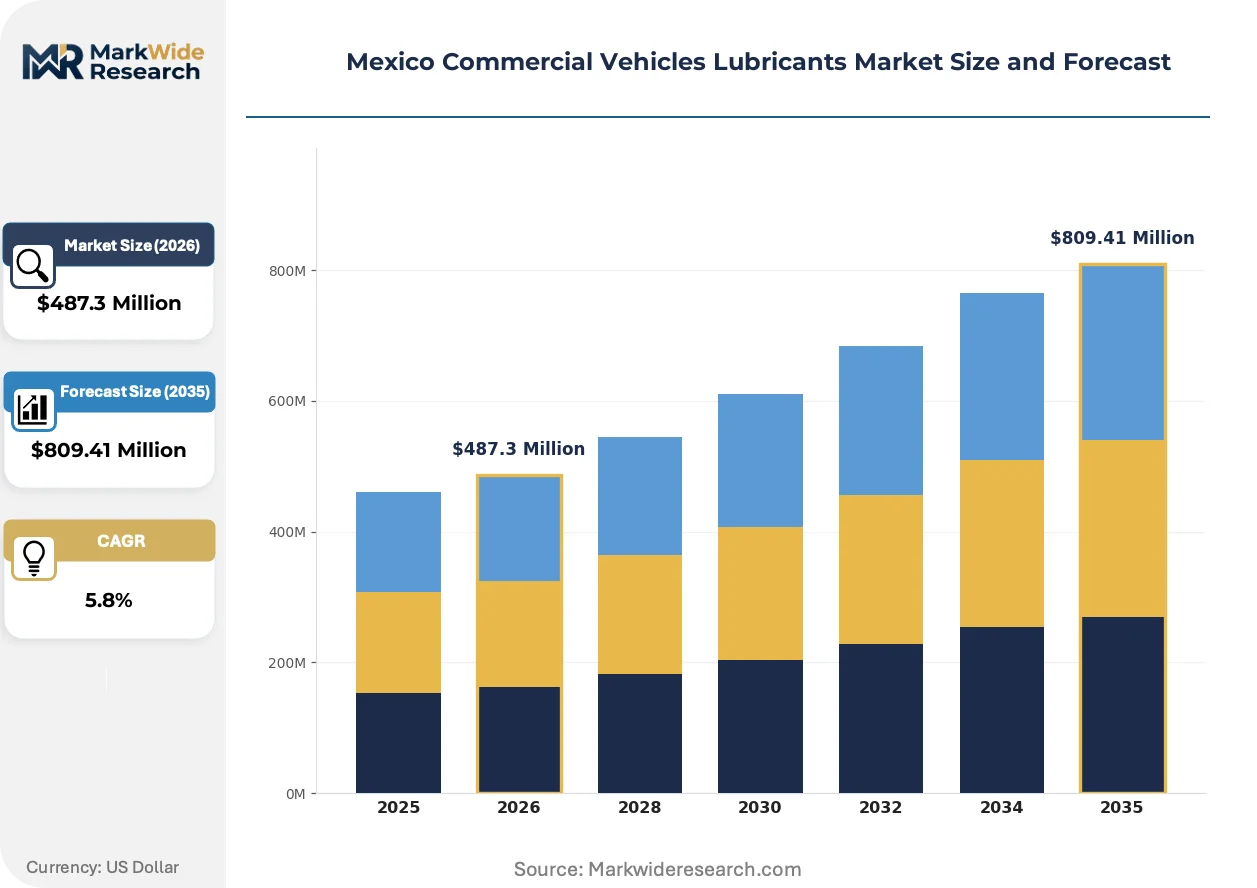
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Fluid Application: Trucks, Buses, Vans, Trailers End User: Fleet Operators, Logistics Providers, Public Transport, Construction Companies Distribution Channel: Retail Stores, Online Platforms, Distributors, Bulk Suppliers |
| Companies Covered | ExxonMobil Corporation, BP PLC (Castrol), Royal Dutch Shell Plc, TotalEnergies, Chevron Corporation, Valvoline Inc., Bardahl, Fuchs Petrolub SE, Roshfrans, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Commercial Vehicles Lubricants Market Shifts & Advancements
Synthetic formulation chemistry and digital fleet management tools are compressing traditional service intervals and rewiring how lubricant value is captured across Mexico's commercial vehicle base.
Low-viscosity multigrade engine oils are migrating from premium fleet segments to standard-duty applications as OEM drain interval recommendations extend past 50,000 kilometers for highway tractors. Logistics providers operating dedicated routes between Mexico City and Laredo are adopting SAE 5W-30 full synthetics to maximize uptime and minimize service bay congestion. This viscosity migration from conventional 15W-40 mineral stocks is compressing the addressable market for mid-tier semi-synthetic products and forcing reformulation investments.
PROFECO pricing transparency mandates combined with NOM energy efficiency labeling requirements are tightening retail channel compliance burdens. Retail distributors must now maintain auditable documentation linking shelf price to certified performance coefficients. Independent service stations in Jalisco and Nuevo León are responding by consolidating supplier relationships to reduce SKU complexity and audit preparation overhead.
Contracted maintenance programs are displacing transactional oil change revenue as fleet operators seek to cap operating cost volatility. Large transport operators running more than 500 power units are negotiating all-inclusive per-kilometer service agreements that bundle lubricant, filter, and labor. This model concentrates procurement authority at fleet headquarters in Querétaro and Monterrey, marginalizing traditional jobber networks that historically served dispersed owner-operators.
Mexico Commercial Vehicles Lubricants Market Segmentation
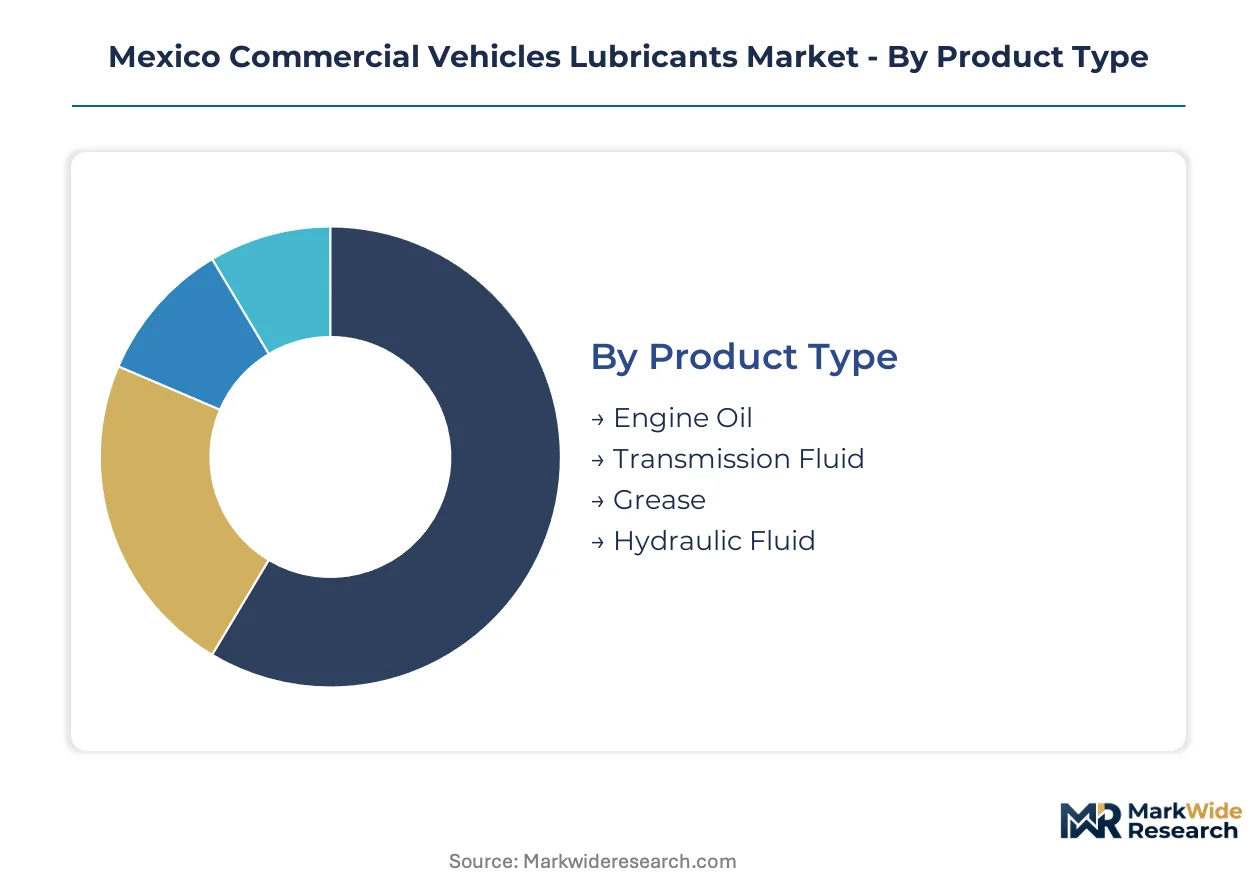
Segmentation in Mexico's commercial vehicles lubricants market reveals distinct consumption rhythms and procurement patterns. Fleet operators and logistics providers exhibit fundamentally different purchase frequencies, volume scales, and specification requirements that shape supplier strategy across product categories.
Product Type:
Engine Oil turns over fastest with drain intervals driving recurring demand, while Grease cycles slowest through chassis and bearing applications. Transmission Fluid and Hydraulic Fluid occupy intermediate replacement frequencies tied to equipment duty cycles.
- Engine Oil:Formulated petroleum-based and synthetic fluids ranging from SAE 15W-40 to SAE 5W-30 viscosity grades, engineered to reduce friction and dissipate heat in diesel and gasoline engines under high load cycles. Demand concentrates in long-haul trucking corridors between Mexico City and Laredo, where extended drain intervals above 50,000 kilometers favor full synthetic formulations despite premium pricing.
- Transmission Fluid:Specialized lubricants for manual and automated manual transmissions, formulated with friction modifiers and thermal stability additives. Adoption is accelerating in Guanajuato's automotive manufacturing corridor as captive fleet operations standardize on synthetic ATF for warranty compliance and fuel economy gains.
- Grease:Semi-solid lubricants for chassis points, wheel bearings, and fifth wheel plates, typically lithium-complex or calcium-sulfonate based. Construction equipment in Querétaro and Bajío industrial zones drives seasonal bulk purchasing tied to infrastructure project cycles.
- Hydraulic Fluid:Anti-wear formulations for construction equipment attachments and refuse truck lift mechanisms. Port modernization at Progreso and expanding agro-export cold chain operations in Yucatán are creating concentrated demand nodes for high-viscosity-index synthetics.
Engine Oil anchors the volume base while Hydraulic Fluid gains share at the steepest rate.
Application:
Cost tier differentiation separates premium synthetic adopters from conventional mineral oil users across vehicle categories. Heavy-duty applications command formulation investments that light-duty segments cannot economically justify.
- Trucks:Class 8 highway tractors and regional delivery vehicles consuming the highest lubricant volumes per unit. Fleet operators running cross-border routes through Nuevo León and Tamaulipas are consolidating procurement around API CK-4 and FA-4 specifications to protect exhaust aftertreatment systems under ULSD transition mandates.
- Buses:Urban transit and intercity coach applications with severe stop-and-go duty cycles. Mexico City and Monterrey public transport authorities are specifying low-ash synthetics to extend particulate filter service life in congested operating environments.
- Vans:Last-mile delivery and service vehicle segment dominated by independent operators. Southern states exhibit persistent price sensitivity toward conventional 15W-40 mineral stocks despite total-cost-of-ownership disadvantages.
- Trailers:Non-powered equipment with lubrication concentrated in landing gear, door hinges, and refrigeration unit compressors. Reefer trailer expansion along Pacific coast export corridors is driving specialized compressor oil demand.
Trucks generate the dominant revenue share while Buses exhibit the most rapid specification upgrade trajectory.
End User:
Customer type determines procurement authority concentration and contract structure preferences. Large consolidated fleets negotiate fundamentally different terms than fragmented owner-operator bases.
- Fleet Operators:Transport companies running 50-plus power units with centralized procurement functions. Querétaro and Monterrey headquarters locations are negotiating all-inclusive per-kilometer service agreements that bundle lubricant, filter, and labor into fixed operating cost structures.
- Logistics Providers:E-commerce fulfillment and dedicated contract carriage operators with uptime-critical operations. Real-time route optimization requirements are accelerating telematics-integrated oil analysis adoption for predictive maintenance scheduling.
- Public Transport:Municipal and state-level bus operators with regulatory compliance obligations. SEMARNAT used oil collection quotas are forcing specification upgrades to longer-interval synthetics that reduce waste volume compliance burdens.
- Construction Companies:Project-based equipment operators with seasonal demand patterns. Hydraulic fluid consumption tracks infrastructure spending cycles in central Mexico manufacturing corridors.
Fleet Operators command procurement volume concentration while Logistics Providers are expanding most quickly through e-commerce network buildouts.
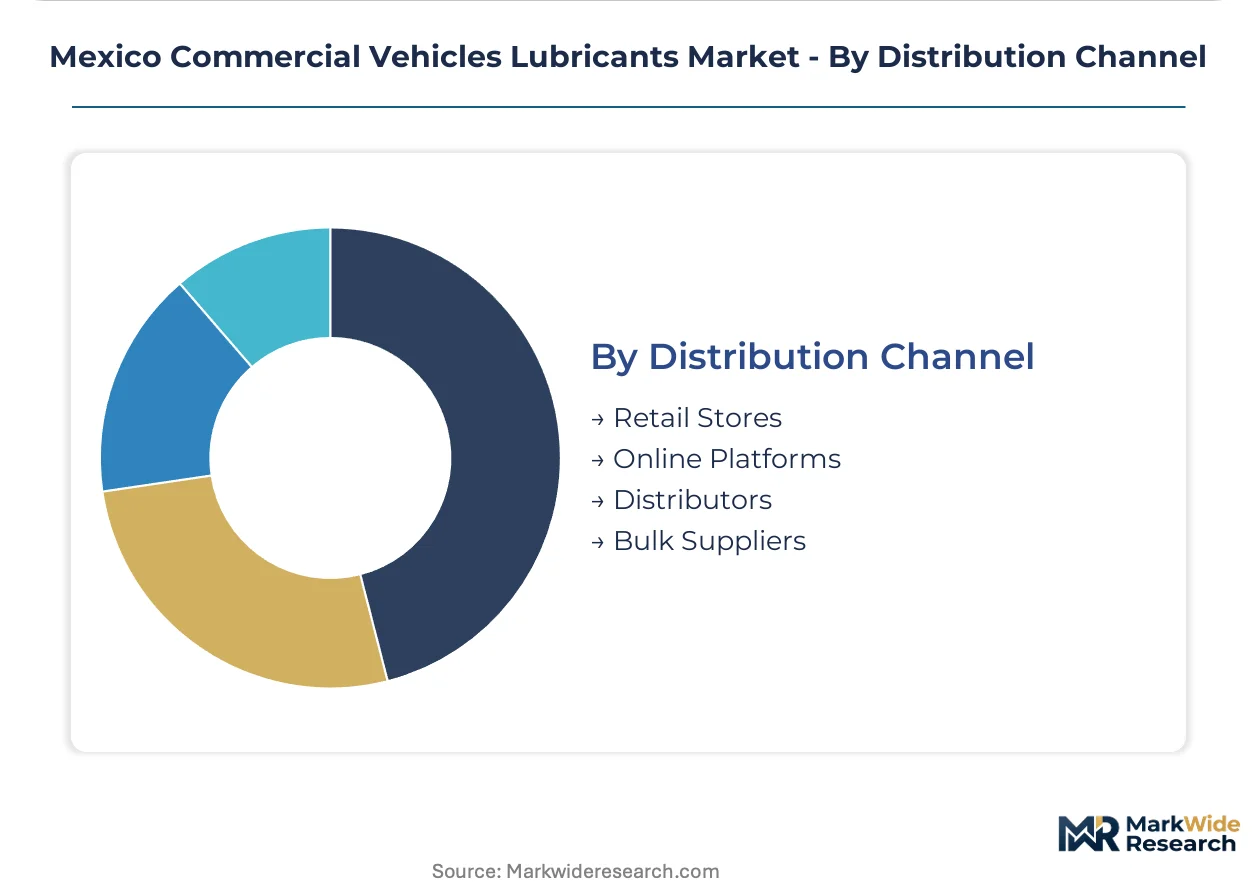
Distribution Channel:
Supply concentration varies dramatically by channel, with bulk infrastructure requirements creating natural barriers to entry that retail and online channels cannot replicate.
- Retail Stores:Independent service stations and automotive parts retailers serving owner-operators and small fleets. PROFECO pricing transparency mandates and NOM energy efficiency labeling requirements are consolidating supplier relationships to reduce SKU complexity and audit preparation overhead.
- Online Platforms:Emerging direct-to-fleet procurement channels with limited current penetration. Technical support requirements and bulk volume needs constrain adoption for heavy-duty applications.
- Distributors:Regional jobber networks with technical service capabilities and local inventory positioning. Chevron Corporation competes through network density in central Mexico, while independent distributors retain loyalty among southern state operators.
- Bulk Suppliers:Direct refinery-aligned supply infrastructure for large fleet accounts. ExxonMobil Corporation leverages Gulf Coast import terminals and northern Mexico storage assets to anchor long-term agreements across border states.
Bulk Suppliers capture the highest-value contracts while Distributors retain the broadest geographic coverage footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Mexican sub-regions. Northern border states favor bulk synthetic procurement for cross-border logistics, while central manufacturing corridors drive specification upgrades and southern markets retain price-sensitive conventional demand.
Northern Border States
Chihuahua, Coahuila, Nuevo León and Tamaulipas host dense Class 8 tractor concentrations serving US-Mexico freight corridors. SEMARNAT used oil collection quotas force fleet operators toward extended-drain synthetics that reduce compliance volume. ExxonMobil Corporation leverages Gulf Coast import terminals and regional storage assets to anchor long-term supply agreements.
Bajío Region
Guanajuato and Querétaro form Mexico's automotive manufacturing heartland with captive fleet operations expanding rapidly. NOM energy efficiency standards tighten lubricant specifications as OEM assembly plants relocate capacity from Asia. Heavy-duty truck density supports bulk lubricant offtake through direct refinery-aligned supply infrastructure.
Mexico City Metro
The capital's urban transit authorities specify low-ash synthetics to extend particulate filter service life in congested stop-and-go duty cycles. PROFECO monitors retail pricing transparency across distribution channels serving dispersed owner-operators. Public transport operators negotiate all-inclusive per-kilometer maintenance agreements.
Jalisco
Guadalajara anchors western Mexico logistics networks with independent service stations consolidating supplier relationships. NOM energy efficiency labeling requirements tighten retail channel compliance burdens. Chevron Corporation competes through distributor network density against regional jobber networks retaining loyalty among small fleet operators.
Yucatán Peninsula
Port modernization at Progreso and expanding agro-export cold chain operations create greenfield fleet formation. No incumbent lubricant supplier relationships exist in this emerging logistics corridor. Hydraulic fluid demand concentrates in high-viscosity-index synthetics for refrigerated trailer compressor systems.
Mexico Commercial Vehicles Lubricants Market Competitive Landscape
Capability concentration sits with multinational blenders possessing Gulf Coast import infrastructure; scale advantage sits with regional distributors maintaining local inventory positioning. The market structures around three tiers: global majors with bulk supply assets, national distributors with technical service networks, and regional specialists with localized brand equity. Consolidation pressure intensifies as fleet procurement centralizes. Two dominant competitive moves define current positioning: long-term service contract anchoring and distributor network density expansion.
Within the global major tier, ExxonMobil Corporation and Royal Dutch Shell Plc exemplify bulk infrastructure players leveraging import terminal access. Chevron Corporation occupies a position among network-density competitors. Roshfrans represents the regional specialist archetype sustaining loyalty through localized technical support rather than scale.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| TotalEnergies |
| Chevron Corporation |
| Valvoline Inc. |
| Bardahl |
| Fuchs Petrolub SE |
| Roshfrans |
| Others |
Supply & Pricing Matrix
US Gulf Coast refinery capacity dynamics directly shape downstream pricing power for Mexican blenders importing Group II/III base stocks. Fleet procurement consolidation around long-term service contracts compresses spot-market premiums while elevating volume-discount leverage for buyers with captive storage infrastructure.
Pricing Analysis
Long-term offtake agreements dominate fleet procurement, with per-kilometer service contracts bundling lubricant, filter, and labor into fixed operating cost structures. Three-tier pricing structure across premium synthetic, semi-synthetic, and conventional mineral tiers differentiates by drain interval performance and NOM energy efficiency certification. Cost compression in mid-tier semi-synthetics is intensifying because viscosity migration toward low-grade full synthetics erodes their value proposition. Owner-operators running single-unit tractors in southern states exhibit highest price sensitivity, while consolidated fleets with 500-plus power units capture steepest volume discounts through direct bulk supply relationships.
Supply Chain Analysis
Export-control regimes on specialty chemical additive packages from Texas and Louisiana refiners constrain formulation flexibility for Mexican blenders lacking backward integration. Supply concentration rests on US Gulf Coast base oil production, South Korean Group III synthetic feedstocks, and German additive technology imports. Working capital intensity spikes from currency hedge requirements on dollar-denominated additive purchases and freight rate volatility on cross-border tanker movements. Distribution runs through bulk terminal networks anchored in northern border states, with regional jobbers filling geographic gaps in central and southern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification trials and alternative powertrain adoption present substitution threats that lubricant incumbents must navigate through service model reinvention. Incumbents face compressed margins if they fail to capture value from predictive maintenance platforms and compliance consulting services.
For Market Incumbents: Insulate core fleet relationships by embedding telematics-integrated oil analysis into contracted maintenance programs, creating switching costs through predictive drain optimization subscriptions. Anchor long-term agreements with captive storage infrastructure investments in Querétaro and Monterrey logistics corridors. Battery-electric truck pilots threaten engine oil volume concentration; respond by diversifying into thermal management fluids and e-axle lubricants for hybrid architectures.
For New Entrants and Emerging Players: Build out technical service capabilities targeting the Yucatán Peninsula's greenfield fleet formation, where no incumbent lubricant supplier relationships exist and port modernization at Progreso creates concentrated demand nodes. Cold chain expansion for agro-exports drives hydraulic fluid consumption for refrigerated trailer compressors. Differentiate through NOM-052 energy efficiency coefficient documentation services that position suppliers as compliance partners rather than commodity vendors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors distributors with dense technical service networks and bulk infrastructure access over pure-play blenders exposed to base oil import volatility. Five-to-ten year viability hinges on synthetic formulation chemistry investments and digital fleet management tool integration. Acquisition targets should demonstrate established SEMARNAT-certified used oil collection partnerships and cross-border specification harmonization capabilities for bi-national fleet operators. Monitor EPA-correlated emissions standard alignment announcements as inflection indicators for specification upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive access to Group II/III feedstocks insulates margins from US Gulf Coast freight volatility and currency exposure. |
| Telematics-Integrated Oil Analysis Platform | Real-time viscosity monitoring shifts revenue from product sales to subscription diagnostics with higher retention. |
| SEMARNAT Compliance Partnership Program | Technical consulting on used oil collection quotas positions suppliers as regulatory allies rather than commodity vendors. |
| Yucatán Peninsula Distribution Expansion | Greenfield fleet formation at Progreso port creates first-mover advantage with no incumbent supplier relationships. |
| Synthetic Formulation R&D Investment | Low-viscosity multigrade chemistry captures extended-drain demand from logistics providers maximizing uptime. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement directors, lubricant blender operations managers, SEMARNAT compliance officers, and regional distributor principals and refined through secondary validation. Fleet maintenance records, customs import data on base oil and additive shipments, NOM energy efficiency certification databases, and PROFECO pricing transparency filings anchored quantitative triangulation. Bottom-up volume estimates from individual fleet operator consumption patterns were cross-checked against top-down market sizing from refinery-aligned bulk supplier throughput data.
Demand-supply-balance modeling across the projection horizon integrated fleet operator consolidation trends, nearshoring manufacturing expansion in Guanajuato and Querétaro, and ULSD-compatible engine hardware penetration. Segmentation dimensions included product viscosity grade, vehicle duty cycle intensity, end-user procurement centralization, and regional logistics corridor density. CAGRs were derived from segment-level volume trajectories weighted by specification upgrade elasticity and synthetic formulation adoption curves. Forecast inputs incorporated NOM regulatory amendment timelines and cross-border freight volume projections through Laredo and Nuevo Laredo corridors.
Stress conditions across base oil import cost volatility, fleet electrification adoption rates, and SEMARNAT enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on synthetic price parity achievement and distributor network consolidation velocity. Material shifts in EPA-correlated emissions standard alignment or nearshoring manufacturing relocation patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Drilling Lubricants Market
Lubricants
China Automotive Engine Oils Market
Lubricants
Marine Grease Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Polyurea-Based Greases Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
US Lubricants Market
Lubricants
Lubricity Improvers Market