
 Hydraulic Filters Market | 2026-2036
Hydraulic Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Filters Market Analysis
Filter-as-a-service maintenance contracts is broadening how hydraulic filtration gets monetized, shifting vendors from component sales to uptime guarantees. Pall Corporation leverages its aerospace heritage to dominate high-specification aviation applications. Donaldson Company Inc. sustains agricultural equipment channels through proprietary air-liquid filtration bundles. Eaton Corporation plc anchors its position in mobile hydraulics through integrated smart-monitoring filter housings.
Hydraulic filters are pressure-vessel elements engineered from woven metal mesh, synthetic fiber media, or multi-layer sintered composites, designed to remove particulate contamination from hydraulic circuits operating between 50 and 10,000 psi. Their primary purpose is protecting pumps, valves, and actuators from abrasive wear that degrades precision tolerances in fluid power systems. Inline filters command the largest installed base due to universal placement downstream of pumps, while return line filters represent the fastest replacement-cycle segment as low-pressure configurations permit higher dirt-loading capacity. Stainless steel media captures premium margin pools in aviation and offshore applications where corrosion resistance and fire safety override cost sensitivity.
The EPA enforces hydraulic fluid spill containment under Clean Water Act provisions, compelling construction and agriculture end users to specify filters with enhanced seal integrity and burst-pressure ratings. ISO 4406 cleanliness codes and the EU F-Gas Regulation together shape product design by mandating particle-count thresholds and restricting certain hydraulic fluid chemistries that interact with filter elastomers. Stakeholders must monitor how electrification of mobile equipment alters hydraulic system architectures and whether reduced reservoir volumes compress filter sizing conventions.
Market Dynamics
Predictive maintenance algorithms are compressing filter replacement cycles across construction equipment fleets, forcing suppliers to re-engineer media durability for extended service intervals while maintaining ISO 4406 cleanliness compliance.
Growth Catalysts
- EU F-Gas Regulation:Tightened hydraulic fluid cleanliness standards in European manufacturing are compelling upgrades to high-efficiency synthetic fiber media, particularly in German precision engineering supply chains.
- Construction equipment electrification:Hybrid hydraulic architectures in mobile machinery are creating demand for compact high-pressure filters that fit reduced reservoir volumes without sacrificing dirt-holding capacity.
- Aviation safety mandates:FAA corrosion-resistance requirements for hydraulic systems are accelerating adoption of stainless steel sintered media in commercial and defense aircraft maintenance programs.
Market Restraints
- Specialty steel price volatility:Nickel and chromium input cost swings compress margins on aviation-grade stainless steel filter production, forcing pass-through pricing that strains OEM relationships.
- German supply concentration:Precision manufacturing certification bodies and automotive OEM qualification protocols cluster filter validation in Bavaria and Baden-Württemberg, creating geographic chokepoints for market entry.
- Electro-hydraulic actuator substitution:Direct electric drive systems in precision motion control are displacing hydraulic circuits entirely in sub-50 horsepower mobile equipment segments.
Strategic Opportunities
- Filter-as-a-service contracts:Outcome-based uptime guarantees are displacing component sales in North American construction equipment fleets, locking in recurring revenue through predictive replacement scheduling.
- Offshore wind hydraulic systems:Corrosion-resistant filtration for turbine pitch control and yaw braking systems represents an underpenetrated application with 25-year service life requirements.
- Indian infrastructure buildout:Bureau of Indian Standards certification pathways for construction equipment filters are opening as the country's National Infrastructure Pipeline accelerates earthmoving machinery deployment.
Industry Challenges
- ISO 4406 certification timelines:Particle-count validation protocols for new media formulations require 18-24 month laboratory cycles, delaying product launches and freezing R&D capital.
- Multi-fluid compatibility engineering:Biodegradable ester-based hydraulic fluids mandated by EPA spill containment rules degrade conventional nitrile seals, forcing complete elastomer redesigns.
- Smart sensor integration:Pressure-differential monitoring electronics embedded in filter housings demand firmware expertise scarce among traditional metalworking suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Filters Market |
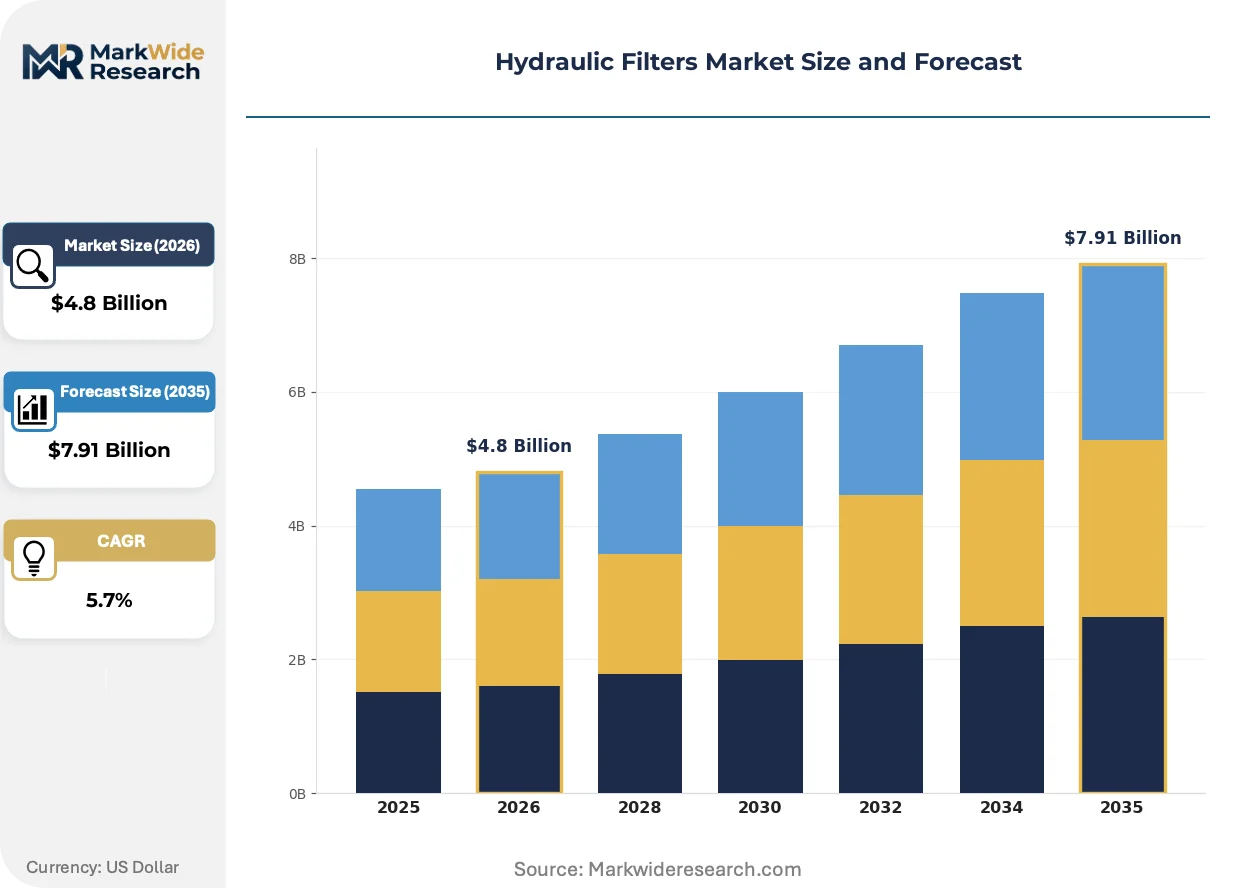
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Filters, Return Line Filters, Suction Filters, Pressure Filters Material: Stainless Steel, Nylon, Aluminum, Polyester End User: Agriculture, Construction, Automotive, Aviation Performance Rating: High Efficiency, Low Pressure Drop, High Dirt Holding, Standard |
| Companies Covered | Pall Corporation, Filtration Group Corporation, Caterpillar Inc., MAHLE GmbH, Donaldson Company Inc., Eaton Corporation plc, HYDAC Technology Limited, Bosch Rexroth AG, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Filters Market Emerging Trajectories
Real-time contamination monitoring and electrified hydraulic architectures are converging to redefine filter specification criteria, shifting design priorities from passive dirt-holding capacity toward active system intelligence.
Multi-layer sintered stainless steel mesh is electrifying aviation and offshore filtration specifications by delivering fire-safe corrosion resistance under 10,000 psi operating pressures. Boeing and Airbus maintenance programs are specifying these media for next-generation landing gear and flight control systems. The technology is electrifying supplier qualification requirements, compressing certification timelines from 36 months to 18 months for qualified entrants.
EPA Clean Water Act spill containment enforcement is compelling construction and agriculture end users to specify filters with enhanced seal integrity and burst-pressure ratings above 150% of maximum operating pressure. The regulation forces filter housing redesigns with redundant O-ring grooves and metal-to-metal backup sealing. Equipment operators in the US Gulf Coast and Great Lakes regions are responding fastest due to concentrated waterway proximity enforcement.
Equipment-as-a-service business models are unbundling filter replacement from machine purchase, concentrating procurement authority with fleet management platforms and compressing supplier relationships toward single-source national contracts. Caterpillar and Komatsu dealer networks are piloting all-inclusive maintenance subscriptions in the US Midwest agricultural belt. The shift is most visible in corn and soybean production regions where seasonal utilization patterns favor fixed-cost operational budgeting over capital expenditure cycles.
Hydraulic Filters Market Segmentation
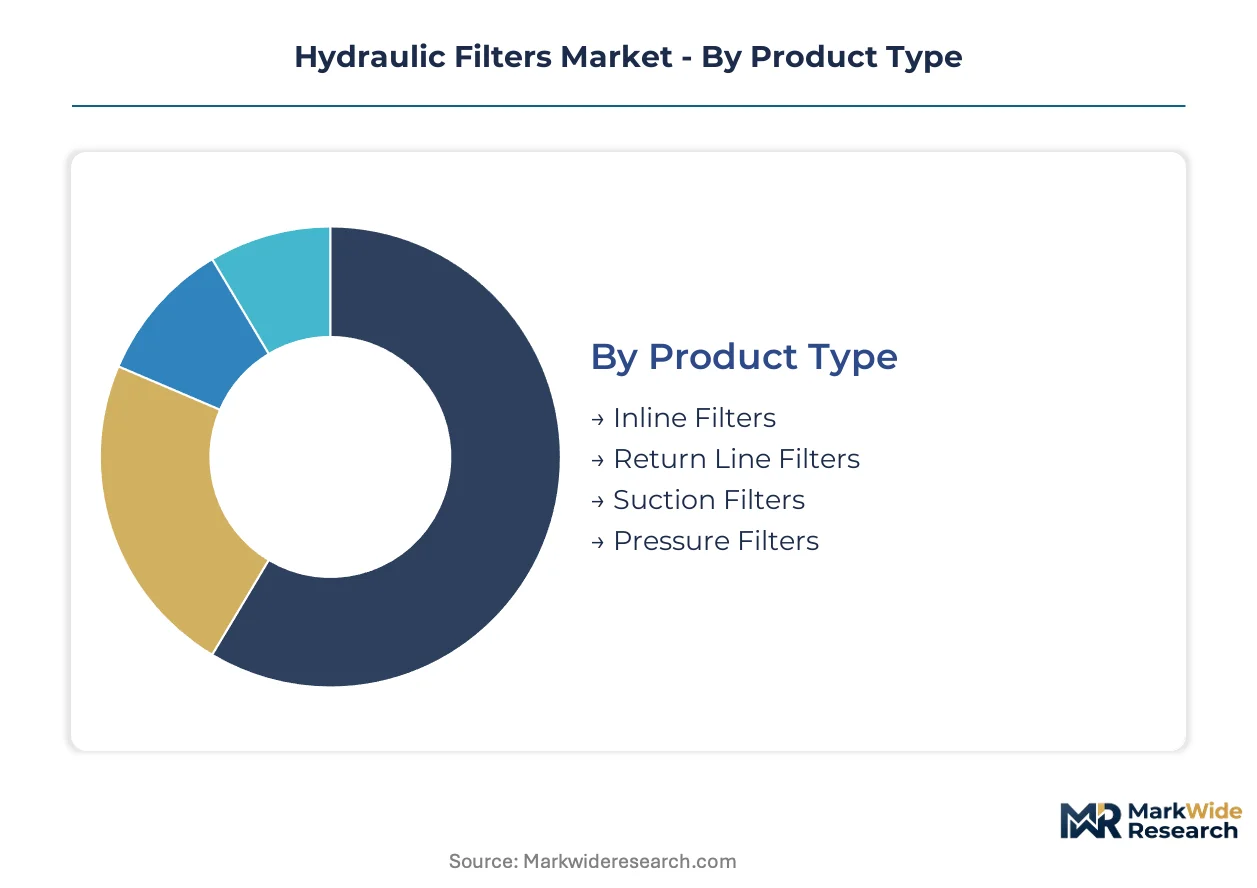
Hydraulic filter specification criteria fragment across four distinct dimensions, each governing procurement authority in different customer environments. Product architecture determines physical placement and pressure tolerance, while material selection locks in corrosion resistance and fire safety certifications. End-use concentration and performance tiering complete the segmentation matrix, dictating margin pools and replacement cycle economics.
Product Type:
Supply concentration for filter housings clusters around high-pressure inline configurations, with foundry capacity and machining expertise favoring established pressure-vessel manufacturers.
- Inline Filters:Positioned downstream of pumps at system pressure points between 1,000 and 6,000 psi, these elements use woven wire mesh or synthetic fiber media in cylindrical housings. German automotive OEM supply chains in Bavaria specify these for precision manufacturing lines where ISO 4406 cleanliness codes mandate continuous filtration. Inline configurations absorb the bulk of installed capacity due to universal placement requirements across mobile and industrial hydraulic architectures.
- Return Line Filters:Operating at tank-side pressures below 150 psi, these low-stress configurations permit higher dirt-loading capacity and extended service intervals. US construction equipment fleets in the Midwest are expanding predictive maintenance programs around return line replacement cycles, compressing supplier margins through volume contracting. Return line filters are expanding most quickly as fleet management platforms centralize procurement authority.
- Suction Filters:Located at pump inlets with coarse filtration ratings protecting against catastrophic debris ingestion. These elements see concentrated demand in Indian earthmoving machinery deployed through the National Infrastructure Pipeline.
- Pressure Filters:Specified for high-pressure circuits above 6,000 psi in aviation and offshore applications where burst-pressure ratings exceed 150% of maximum operating pressure. FAA corrosion-resistance requirements accelerate adoption in commercial aircraft maintenance programs.
Inline filters absorb the bulk of installed capacity; return line filters are expanding most quickly.
Material:
Cost tier differentiation separates corrosion-resistant specialty alloys from commodity synthetics, with aviation and offshore applications commanding premium multiples over agricultural equipment channels.
- Stainless Steel:Multi-layer sintered stainless steel mesh delivers fire-safe corrosion resistance under 10,000 psi operating pressures. Boeing and Airbus maintenance programs specify these media for landing gear and flight control systems, with supplier qualification timelines compressing from 36 months to 18 months for qualified entrants. Nickel and chromium input cost volatility compresses margins on aviation-grade production.
- Nylon:Injection-molded housings and structural components serve low-pressure agricultural equipment where cost sensitivity overrides corrosion concerns. These materials dominate corn and soybean production regions where seasonal utilization patterns favor fixed-cost operational budgeting.
- Aluminum:Lightweight housings for mobile hydraulic systems where weight reduction improves fuel efficiency in construction and earthmoving machinery.
- Polyester:Synthetic fiber media for standard-efficiency filtration in general industrial applications with moderate cleanliness requirements and extended replacement intervals.
Stainless steel commands the steepest price premiums; nylon captures the highest unit volumes in agricultural channels.
End User:
Application-specific certification requirements create distinct procurement ecosystems, with aviation and automotive segments demanding traceable validation while construction and agriculture prioritize total cost of ownership.
- Construction:Earthmoving machinery and mobile equipment fleets drive demand for compact high-pressure filters fitting reduced reservoir volumes in hybrid hydraulic architectures. EPA Clean Water Act spill containment enforcement compels enhanced seal integrity specifications in US Gulf Coast and Great Lakes regions.
- Agriculture:Seasonal equipment utilization in US Midwest corn and soybean belts favors fixed-cost maintenance subscriptions over capital expenditure cycles. Equipment-as-a-service models concentrate procurement authority with fleet management platforms.
- Automotive:Precision manufacturing supply chains in Germany require certified filtration systems meeting OEM qualification protocols clustered in Bavaria and Baden-Württemberg.
- Aviation:FAA corrosion-resistance requirements and fire safety mandates specify stainless steel sintered media for commercial and defense aircraft maintenance programs.
Construction absorbs the bulk of replacement volume; aviation delivers the highest margin per unit.
Performance Rating:
Customer type segmentation separates specification-grade buyers from price-sensitive volume purchasers, with certification requirements creating tiered market access barriers.
- High Efficiency:Synthetic fiber media achieving ISO 4406 cleanliness codes below 18/16/13 particle counts. EU F-Gas Regulation compliance in German precision engineering supply chains compels upgrades to these specifications.
- High Dirt Holding:Extended service interval designs for predictive maintenance programs in North American construction fleets, locking in recurring revenue through filter-as-a-service contracts.
- Low Pressure Drop:Optimized flow characteristics reducing energy consumption in continuous-operation industrial systems.
- Standard:Basic filtration meeting minimum equipment warranty requirements in price-sensitive emerging market applications.
High efficiency ratings dominate OEM specification sheets; high dirt holding configurations are climbing the fastest in aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision manufacturing certification and filter validation protocols, while the United States drives aftermarket volume through construction fleet electrification and predictive maintenance adoption. China and India expand earthmoving machinery deployment through infrastructure programs, with Japan maintaining aerospace-grade production standards.
Germany
Bavarian automotive OEM supply chains and Baden-Württemberg precision engineering clusters demand certified filtration systems meeting ISO 4406 cleanliness codes. The EU F-Gas Regulation compels upgrades to high-efficiency synthetic fiber media across German manufacturing lines. Stuttgart and Munich anchor supplier qualification protocols that compress certification timelines for qualified entrants.
United States
Midwest construction equipment fleets and Gulf Coast agriculture operators drive filter-as-a-service contract adoption through seasonal utilization patterns. EPA Clean Water Act spill containment enforcement mandates enhanced seal integrity specifications in waterway-proximate regions. Caterpillar and Komatsu dealer networks pilot predictive maintenance subscriptions across Illinois and Iowa corn belts.
China
National infrastructure stimulus and dual carbon goals accelerate hybrid hydraulic architecture deployment in earthmoving machinery. MIIT standards for mobile equipment cleanliness create compliance pathways for domestic filter manufacturers. Yangtze River Delta manufacturing clusters integrate compact high-pressure filters into reduced reservoir volume designs.
India
The National Infrastructure Pipeline accelerates earthmoving machinery deployment across state-level road and rail projects. Bureau of Indian Standards certification pathways open for construction equipment filters as domestic production scales. Maharashtra and Gujarat industrial corridors concentrate demand for suction filters protecting pump inlets in heavy-duty applications.
Japan
Commercial aircraft maintenance programs and defense aviation contracts sustain demand for stainless steel sintered media with fire-safe corrosion resistance. METI industrial standards align with FAA requirements for hydraulic system components in landing gear applications. Nagoya aerospace clusters and Osaka precision manufacturing districts anchor high-specification filter production.
Hydraulic Filters Market Vendor Landscape
Top-tier vendors anchor aviation and precision manufacturing certification tiers, while mid-scale specialists occupy construction and agriculture channels through volume contracting and regional distribution networks. The vendor base stratifies across aerospace-grade stainless steel media producers, mobile hydraulic integrated system suppliers, and agricultural equipment bundling specialists. Two dominant competitive moves define current positioning: predictive maintenance platform integration through smart-monitoring filter housings, and filter-as-a-service outcome-based contract structures that displace component sales.
Among diversified industrial conglomerates, Eaton Corporation plc and Parker Hannifin Corporation exemplify the integrated-systems archetype, embedding pressure-differential monitoring electronics directly into filter housings for mobile hydraulic applications. Pall Corporation occupies a position representing aerospace heritage specialization, with qualification protocols that compress certification timelines for commercial and defense aircraft maintenance programs. Donaldson Company Inc. anchors the agricultural bundling archetype, sustaining equipment channels through proprietary air-liquid filtration combinations in seasonal production regions.
| Leading Market Players |
|---|
| Pall Corporation |
| Filtration Group Corporation |
| Caterpillar Inc. |
| MAHLE GmbH |
| Donaldson Company Inc. |
| Eaton Corporation plc |
| HYDAC Technology Limited |
| Bosch Rexroth AG |
| Parker Hannifin Corporation |
| Others |
Supply Flow & Price Mechanics
Construction fleet procurement centralization through predictive maintenance platforms is forcing filter suppliers toward outcome-based contract structures, compressing component margins while rewarding integrated service capabilities. This demand-side consolidation reshapes how pricing power distributes across stainless steel media specialists versus synthetic fiber volume producers.
Pricing Analysis
Margin tightening in aviation-grade stainless steel filtration reflects nickel and chromium input cost volatility that suppliers cannot fully pass through to Boeing and Airbus maintenance programs. Three-tier pricing structure across aerospace-certified, industrial-performance, and agricultural-economy levels separates segments by ISO 4406 validation investment and fire-safety certification burden. Cost-down pressure on synthetic fiber media accelerates because German automotive OEMs demand high-efficiency formulations at contractually fixed rates. Agricultural equipment channels exhibit the highest price sensitivity, while aviation maintenance programs show the least due to non-negotiable FAA corrosion-resistance mandates.
Supply Chain Analysis
Specialty steel supply rests on German precision foundries, Japanese aerospace-grade metalworking clusters, and US Gulf Coast stainless distribution hubs. Raw material flows draw from Indonesian nickel mining, South African chromium extraction, and German synthetic fiber polymer production. Single-source vulnerability concentrates in Bavarian certification bodies that validate filter media for EU F-Gas Regulation compliance. Distribution runs through Caterpillar and Komatsu dealer networks in North American agricultural belts, with emerging direct-to-fleet platform sales compressing traditional channel margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 4406 certification timeline elongation and smart-sensor firmware capability scarcity are forcing sub-scale metalworking suppliers toward exit or acquisition, consolidating procurement authority among integrated system vendors.
For Market Incumbents: Anchor defensive positioning through backward integration into synthetic fiber media production, eliminating margin leakage to specialty polymer suppliers. Lock in fleet management platform partnerships before predictive maintenance algorithms commoditize filter replacement scheduling. Prioritize certification investment in Stuttgart and Munich validation protocols to maintain Bavarian automotive OEM access against emerging Asian competitors. For New Entrants and Emerging Players: Indian earthmoving machinery deployed through the National Infrastructure Pipeline represents the most penetrable buyer archetype, with Bureau of Indian Standards certification pathways newly opened and domestic production scaling. Target offshore wind turbine pitch control systems as an underpenetrated corrosion-resistant application with 25-year service life requirements. Pursue joint-venture structures with established German validation bodies to compress 18-month qualification timelines. For Investors and Strategic Acquirers: The window for entry favors vertically integrated filtration specialists with captive aerospace certification relationships and smart-monitoring firmware capabilities. Mid-cap targets with ISO 4406 laboratory infrastructure and existing FAA supplier status offer the strongest 5-10 year viability profile. Watch electrification rates in sub-50 horsepower mobile equipment as the inflection signal for hydraulic circuit displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Monitoring Filter Housing Development | Eaton and Parker Hannifin embed pressure-differential electronics to capture predictive maintenance platform revenue. |
| Filter-as-a-Service Contract Expansion | Caterpillar dealer networks pilot uptime guarantees that displace component sales in Illinois and Iowa corn belts. |
| Stainless Steel Sintered Media Scale-Up | Aviation maintenance programs specify fire-safe corrosion resistance for Boeing and Airbus landing gear systems. |
| Indian Bureau of Standards Certification | National Infrastructure Pipeline earthmoving deployment creates compliance pathways for domestic filter manufacturers. |
| Offshore Wind Hydraulic System Partnership | Turbine pitch control and yaw braking applications demand 25-year corrosion-resistant filtration specifications. |
Methodological Framework
Independent corroboration across maintenance directors at construction equipment fleets, procurement leads at German automotive OEMs, and aftermarket service heads at hydraulic system distributors underwrites the qualitative findings. Primary interviews with plant engineers specifying ISO 4406 cleanliness codes, regulatory affairs specialists tracking EPA Clean Water Act enforcement, and technical R&D directors developing multi-fluid compatible elastomers combined with secondary validation. Secondary sources include SEC 10-K filings from diversified industrial conglomerates, ECHA substance restriction databases, and customs trade data on nickel and chromium import flows. Bottom-up filter replacement volume estimates triangulated against top-down hydraulic system installed base calculations.
Comparable-period anchoring referenced historical construction equipment fleet expansion rates and aviation maintenance program spending patterns across the modeling period. Segmentation dimensions modeled include product architecture (inline, return line, suction, pressure), material grade (stainless steel, synthetic fiber, aluminum, nylon), end-use concentration (construction, agriculture, automotive, aviation), and performance tier (high efficiency, high dirt holding, low pressure drop, standard). CAGRs derived from regression analysis against equipment production forecasts and predictive maintenance adoption curves. Industry-specific inputs incorporated EPA spill containment enforcement intensity and EU F-Gas Regulation implementation pace.
Revisions become necessary when electrification penetration in mobile equipment accelerates beyond baseline assumptions, or when German certification body capacity constraints extend qualification timelines. Forecasts reflect documented assumptions on hybrid hydraulic architecture retention rates and stainless steel input cost stabilization. A small set of named triggers—electro-hydraulic actuator substitution rates, nickel price volatility spikes, and Indian infrastructure stimulus execution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Coolant Filtration Systems Market
Filters
Industrial Filter Paper Market
Filters
Global Lamella Clarifier Market
Filters
Round Plate Filter Press Market
Filters
Global Industrial Filters Market
Filters
Single-Use Filtration Assemblies Market
Filters
Compact Filters Market
Filters
Global Sterile Filtration Market
Filters
US Baghouse Filters Market
Filters
Filtration and Separation Market
Filters
United States Activated Carbon Market
Filters
Europe Activated Carbon Market
Filters
Intake Filter Media Market
Filters
Furnace Filters Market
Filters
Fabric Filter System Market
Filters
North America Gas Filtration Media Market