
 Asia-Pacific Automotive Lubricants Market | 2026-2036
Asia-Pacific Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Lubricants Market Outlook
Multi-source procurement for base oil supplies is pivoting toward contracted partnerships with regional refiners. Shell plc leverages its integrated supply chain from Singapore to secure feedstock continuity across Southeast Asian blending plants. Indian Oil Corporation Limited anchors its position through extensive depot networks penetrating tier-two and tier-three Indian cities. Idemitsu Kosan Co. Ltd specializes in high-viscosity index formulations serving Japanese OEM specifications across Thailand and Indonesia.
Asia-Pacific automotive lubricants are formulated hydrocarbon-based fluids engineered with additive packages containing detergents, dispersants, anti-wear agents, and viscosity modifiers, typically operating within temperature ranges from minus forty degrees Celsius to one hundred fifty degrees Celsius to reduce friction, dissipate heat, and prevent corrosion in powertrain assemblies. Engine oil commands the largest revenue pool due to high replacement frequency in passenger vehicle parc expansion, while transmission fluid represents the fastest-growing product category as CVT and DCT penetration rises in Korean and Chinese vehicle production. Two-wheeler end users sustain distinct formulation requirements with lower sump capacities and higher shear stability demands across Vietnam, India, and Indonesia.
Japan's METI enforces fuel economy standards that directly mandate lower viscosity grade lubricants, while China's MIIT implements corporate average fuel consumption rules pushing OEMs toward factory-fill synthetic products. India's BIS certification framework restricts market access for unapproved lubricant imports, compelling foreign suppliers to establish local blending operations. Stakeholders must monitor evolving OEM service-fill specifications and pre-position synthetic product portfolios ahead of regulatory tightening in ASEAN markets.
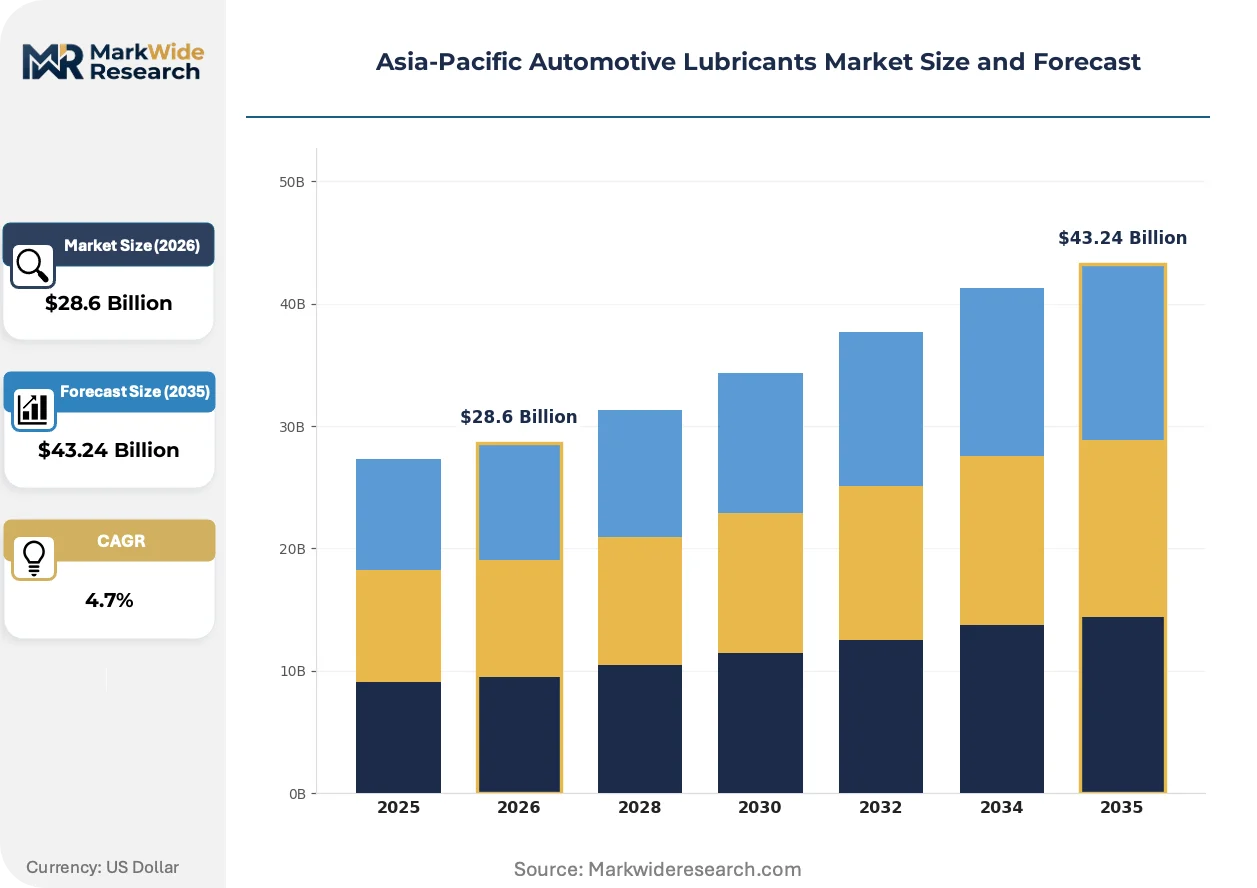
Market Dynamics
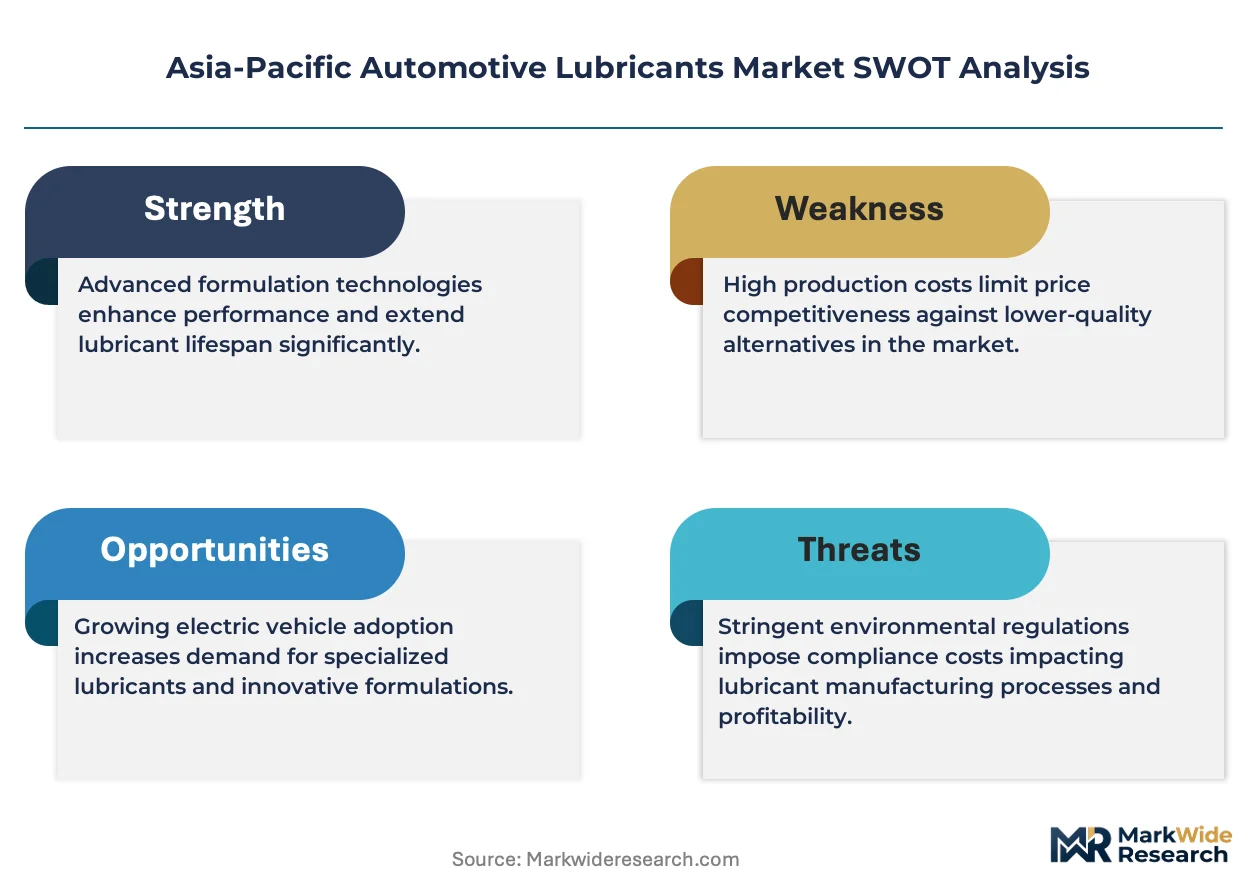
Japan's METI fuel economy mandates and China's MIIT corporate average fuel consumption rules are compressing viscosity grades across factory-fill specifications, forcing reformulation investments ahead of ASEAN regulatory harmonization.
Growth Catalysts
- Passenger vehicle parc expansion:Rising car ownership in India's industrial corridors around Pune and Chennai sustains high-frequency engine oil replacement cycles.
- MIIT dual carbon goals:China's corporate average fuel consumption regulations push OEMs toward synthetic lubricant factory-fill, accelerating premium product adoption.
- CVT and DCT penetration:Korean and Chinese vehicle production lines are expanding transmission fluid volumes as automated gearbox architectures multiply.
Market Restraints
- Group II/III base oil supply concentration:Singapore and South Korean refinery output constraints create feedstock bottlenecks for Southeast Asian blenders.
- BIS certification friction:India's tightening performance standards restrict unapproved imports, compelling foreign suppliers to establish local blending infrastructure.
- Electric powertrain substitution:Battery electric vehicle penetration in Chinese and Japanese fleets eliminates engine oil demand in new vehicle categories.
Strategic Opportunities
- Vietnam two-wheeler service expansion:Lower sump capacity formulations with enhanced shear stability address distinct mechanical stresses in high-density motorcycle markets.
- ASEAN regulatory pre-positioning:Synthetic portfolio development ahead of anticipated fuel economy standard tightening captures first-mover positioning.
- Tier-two Indian city depot networks:Penetration beyond Mumbai and Delhi into secondary urban centers unlocks replacement demand from aging vehicle stocks.
Industry Challenges
- Additive package formulation expertise:Detergent-dispersant-anti-wear balancing for high-temperature ASEAN operating conditions requires specialized tribology capabilities.
- Legacy mineral oil inventory transitions:Blending plant reconfiguration for synthetic throughput demands capital redeployment amid uncertain regional adoption curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Lubricants Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Grease End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Two-Wheelers Packaging Type: Bulk, Drums, Bottles, Pouches Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Specialty Stores |
| Companies Covered | China Petrochemical Corporation, Shell plc, ExxonMobil Corporation, TotalEnergies, BP p.l.c., China National Petroleum Corporation, ENEOS Corporation, Idemitsu Kosan Co. Ltd, Indian Oil Corporation Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Lubricants Market Strategic Shifts
Formulation chemistry and procurement architectures are converging around performance-tier stratification, with regulatory pressure and channel consolidation accelerating product-grade unification.
Low-viscosity synthetic base stocks are unifying factory-fill and service-fill specifications as OEMs consolidate lubricant portfolios. Japanese and Korean manufacturers are adopting 0W-16 and 0W-8 grades at accelerating pace across 2024-2025 model years. This viscosity compression is unifying previously separate product lines and compressing SKU proliferation in regional distribution networks.
China's MIIT implements corporate average fuel consumption rules that mandate lubricant contributions to fleet efficiency targets. OEMs now specify synthetic products with friction-modifier packages in factory-fill contracts. The passenger vehicle segment bears primary compliance burden, with joint-venture partners accelerating local synthetic blending capacity.
Fleet operators across Thailand and Indonesia are consolidating lubricant procurement through direct refinery partnerships, bypassing traditional distributor tiers. Commercial vehicle service providers negotiate annual volume contracts with guaranteed base oil supply. This channel restructuring concentrates buying power among large fleet aggregators in Jakarta and Bangkok metropolitan zones.
Asia-Pacific Automotive Lubricants Market Segmentation
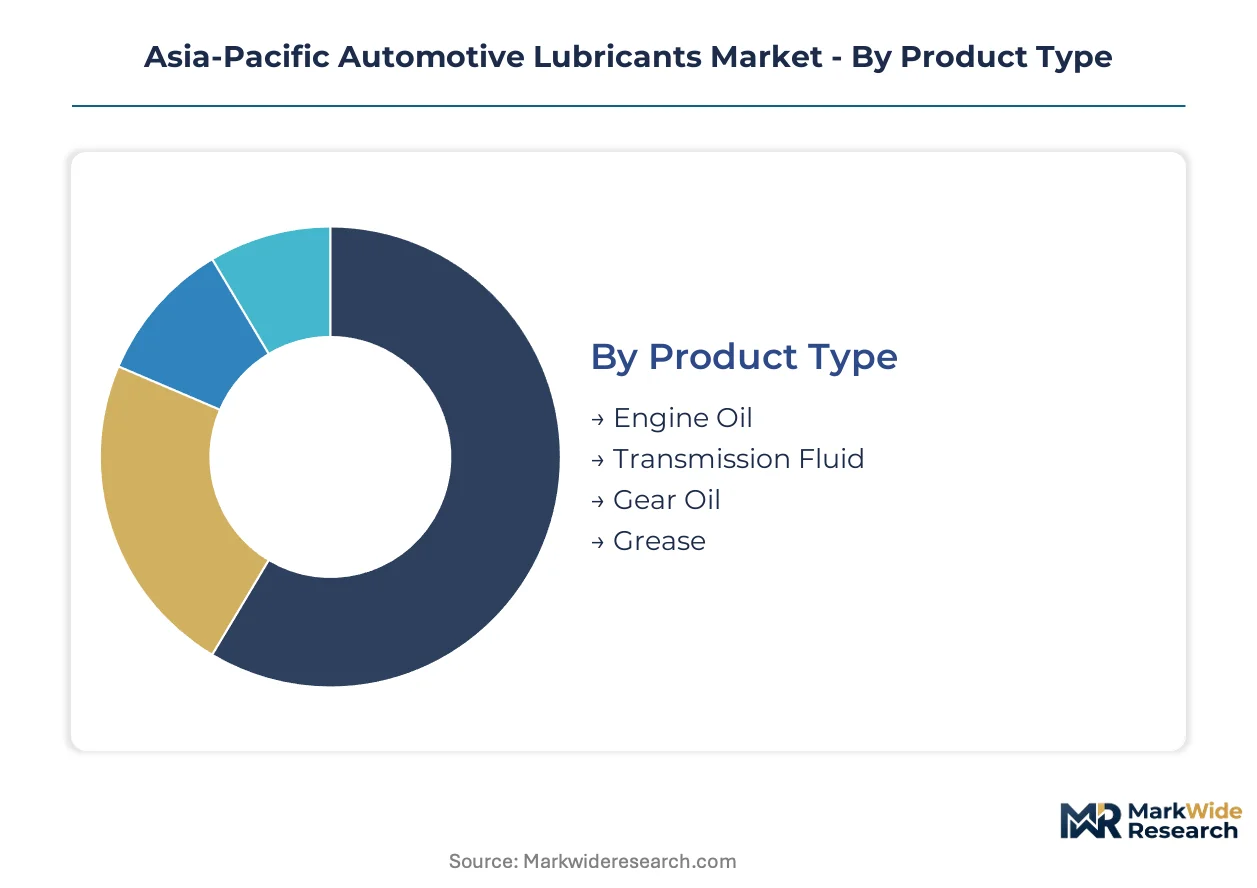
Segmentation in Asia-Pacific automotive lubricants reveals distinct capital requirements, formulation complexity, and channel economics. Product categories demand specialized blending infrastructure, while end-user segments dictate service interval patterns and viscosity specifications across regional markets.
Product Type:
Capital intensity varies sharply across product categories, with synthetic base stock storage and additive blending systems requiring differentiated investment levels.
- Engine Oil:Formulated hydrocarbon-based fluids with detergent-dispersant-anti-wear additive packages operating across minus forty to one hundred fifty degrees Celsius temperature ranges. Demand concentrates in India's industrial corridors around Pune and Chennai where passenger vehicle parc expansion sustains high-frequency replacement cycles.
- Transmission Fluid:Specialized formulations for CVT and DCT architectures with friction-modifier packages and shear stability requirements. Korean and Chinese vehicle production lines are expanding volumes as automated gearbox penetration rises, with formulations requiring precise viscosity index control.
- Gear Oil:High-viscosity lubricants for differential and axle assemblies with extreme pressure additives.
- Grease:Semi-solid lubricants with thickener systems for chassis and bearing applications.
Most installed capacity flows through Engine Oil. Expansion is steepest in Transmission Fluid.
End User:
Application-specific formulation requirements create divergent margin profiles, with factory-fill contracts and service-fill replacement markets operating on fundamentally different commercial terms.
- Passenger Vehicles:Light-duty engine oils and transmission fluids subject to MIIT corporate average fuel consumption regulations and METI fuel economy mandates. China's OEMs specify synthetic factory-fill products, while India's BIS certification requirements tighten performance standards for service-fill volumes.
- Two-Wheelers:Lower sump capacity formulations with enhanced shear stability for high-revving single-cylinder engines. Vietnam, India, and Indonesia sustain distinct mechanical stress profiles requiring specialized additive balancing.
- Commercial Vehicles:Extended drain interval formulations for fleet operators consolidating procurement through direct refinery partnerships.
- Heavy-Duty Vehicles:High-temperature stability formulations for mining and construction equipment operating across Southeast Asian climates.
Passenger Vehicles command the largest volume position. Two-Wheelers are climbing the fastest among end-user categories.
Packaging Type:
Packaging economics reflect channel infrastructure maturity, with bulk systems requiring dedicated logistics networks and retail formats demanding brand differentiation investments.
- Bulk:Tanker and flexitank deliveries for fleet operators and industrial blenders with dedicated storage infrastructure.
- Drums:Intermediate volume containers for commercial garages and regional distributors.
- Bottles:Consumer-facing retail formats with pour-spout designs for DIY replacement in auto parts stores.
- Pouches:Low-cost single-use packaging for two-wheeler roadside service points in Indonesian and Vietnamese rural markets.
Drums and bulk formats dominate commercial channel throughput. Pouch packaging is gaining share fastest in informal service networks.
Distribution Channel:
Channel restructuring is compressing intermediary tiers, with fleet procurement consolidation and digital platforms reshaping traditional distributor economics.
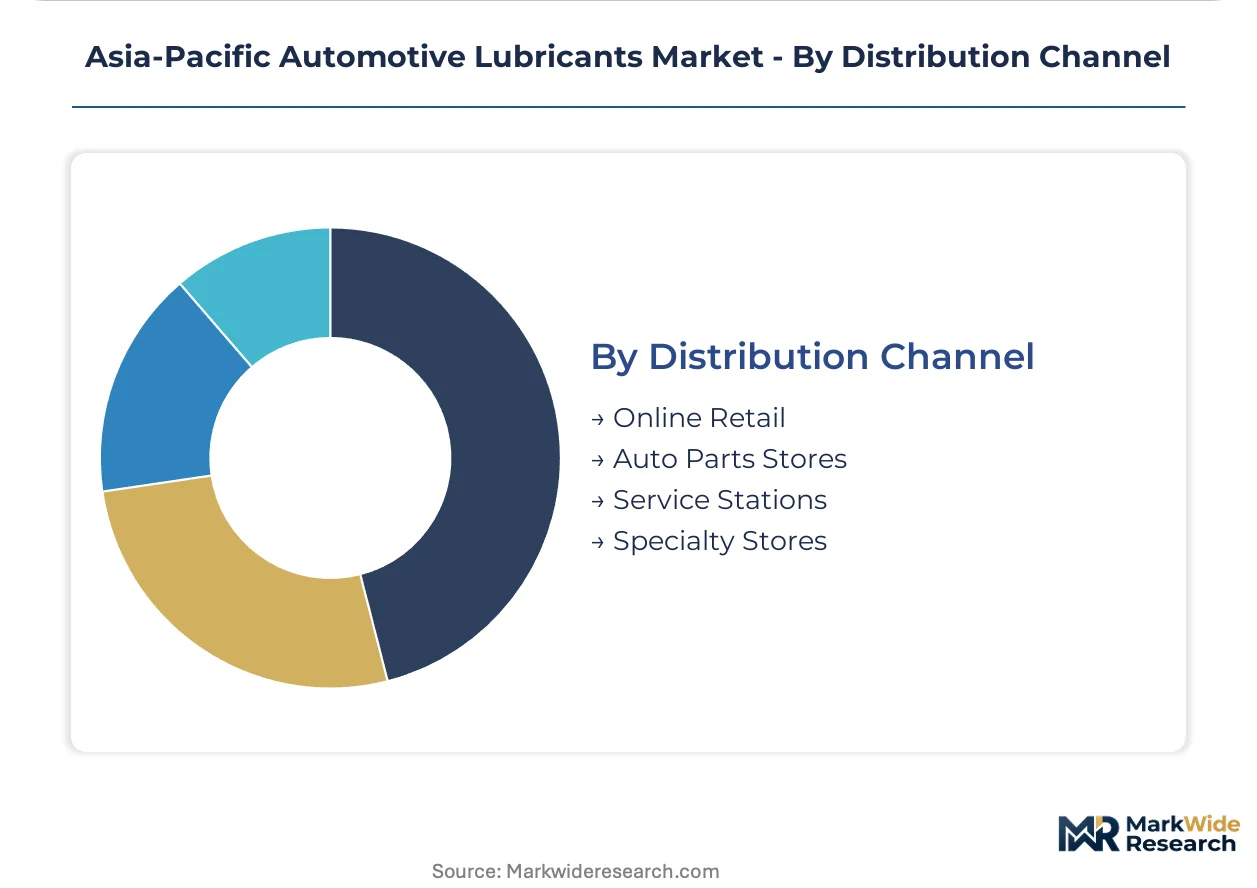
- Auto Parts Stores:Independent retail networks stocking multi-brand portfolios across tier-two and tier-three Indian cities.
- Service Stations:OEM-affiliated quick-lube operations with captive brand specifications in Japanese and Korean dealer networks.
- Online Retail:E-commerce platforms penetrating replacement demand in Chinese and Indian urban centers.
- Specialty Stores:Niche outlets serving performance vehicle segments with racing-specification formulations.
Auto parts stores retain the broadest geographic coverage. Online retail is expanding most quickly in metropolitan replacement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune and Chennai anchor Asia-Pacific lubricant demand through India's dense automotive manufacturing corridors. Fleet operators in these industrial zones compress service intervals to minimize commercial vehicle downtime. Japan's METI mandates and China's MIIT regulations cascade viscosity-grade compression across neighboring ASEAN markets.
China
MIIT corporate average fuel consumption rules force OEMs toward synthetic factory-fill specifications across joint-venture production lines. The dual carbon policy framework accelerates premium lubricant adoption in passenger vehicle assembly plants. Yangtze River Delta manufacturing clusters around Shanghai drive the steepest synthetic blending capacity expansion.
India
BIS certification requirements tighten performance standards for engine oil imports, compelling foreign suppliers to establish local blending infrastructure. Passenger vehicle parc expansion sustains high-frequency replacement cycles in tier-two and tier-three cities. Industrial corridors around Pune and Chennai concentrate demand from aging commercial vehicle stocks requiring extended drain formulations.
Japan
METI fuel economy standards mandate lower viscosity grades across 2024-2025 model year factory-fill contracts. OEMs specify 0W-16 and 0W-8 synthetic products with friction-modifier packages to meet fleet efficiency targets. Kanto manufacturing clusters around Tokyo supply formulation expertise to Thai and Indonesian assembly operations.
Thailand
Commercial vehicle fleet operators consolidate lubricant procurement through direct refinery partnerships, bypassing traditional distributor tiers. ASEAN regulatory harmonization pressures blenders to pre-position synthetic portfolios ahead of anticipated fuel economy standard tightening. Bangkok metropolitan zones concentrate buying power among large fleet aggregators negotiating annual volume contracts.
Vietnam
Two-wheeler end users sustain distinct formulation requirements with lower sump capacities and higher shear stability demands across high-density motorcycle markets. Roadside service points in rural areas drive pouch packaging adoption for single-use lubricant delivery. Ho Chi Minh City and Hanoi anchor replacement demand from informal maintenance networks.
Asia-Pacific Automotive Lubricants Market Competitive Environment
Global majors compete with regional champions across base oil procurement and blending infrastructure. The vendor base stratifies into three tiers: integrated energy conglomerates with captive refinery supply, national oil companies leveraging depot networks, and specialized formulators serving OEM specifications. Strategic moves concentrate on backward integration into regional base oil supply and synthetic portfolio expansion ahead of regulatory tightening.
Within the integrated multinational tier, Shell plc anchors positions through Singapore-to-Southeast Asia supply chain continuity. Indian Oil Corporation Limited exemplifies national oil company leverage through extensive depot networks penetrating secondary Indian urban centers. Idemitsu Kosan Co. Ltd occupies the specialized formulator position, serving Japanese OEM viscosity specifications across Thai and Indonesian markets. These three archetypes represent distinct competitive vectors: feedstock security, distribution density, and technical specification alignment.
| Leading Market Players |
|---|
| China Petrochemical Corporation |
| Shell plc |
| ExxonMobil Corporation |
| TotalEnergies |
| BP p.l.c. |
| China National Petroleum Corporation |
| ENEOS Corporation |
| Idemitsu Kosan Co. Ltd |
| Indian Oil Corporation Limited |
| Others |
Value Chain & Pricing Dynamics
Commercial vehicle fleet operators across Bangkok and Jakarta metropolitan zones concentrate annual volume purchasing power, locking in contract-based long-term offtake pricing with guaranteed base oil supply allocations from Singapore and South Korean refiners.
Pricing Analysis
Base oil cost pass-through from Group II/III feedstock suppliers dominates pricing structures across Southeast Asian blending plants. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral grades reflects BIS certification tiers and viscosity index specifications. Price differentiation hinges on factory-fill OEM approvals versus unbranded service-fill volumes. Cost compression in mineral oil tiers is intensifying because Indian and Indonesian aftermarket channels prioritize volume turnover over performance premiums. Fleet procurement managers exhibit lowest price sensitivity due to downtime cost calculus, while roadside two-wheeler service points in Vietnamese rural markets operate at highest elasticity.
Supply Chain Analysis
Used lubricant collection and re-refining flows are gaining structural importance as circular economy mandates tighten across ASEAN jurisdictions. Singapore, South Korea, and Japan anchor regional base oil supply through hydrocracking and catalytic dewaxing capacity. Blending operations draw from additive packages manufactured in the United States and Europe, with detergent-dispersant-anti-wear chemistries shipped in concentrated form. Single-source vulnerability concentrates in Singapore refinery output constraints affecting Southeast Asian blenders during turnaround seasons. Distribution runs through three parallel channels: direct refinery-to-fleet tanker deliveries, drum shipments to commercial garages, and packaged goods through auto parts retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific automotive lubricants function as a stable compounder underpinned by mandatory replacement cycles in internal combustion fleets, even as electric powertrain substitution advances at the margin.
For Market Incumbents: Hedge synthetic portfolio exposure by maintaining mineral oil blending flexibility for price-sensitive Indian and Indonesian aftermarket tiers. Battery electric vehicle penetration in Chinese and Japanese OEM fleets threatens factory-fill volume concentration. Backward integration into regional base oil supply through contracted offtake with Singapore and South Korean refiners secures feedstock continuity during supply shocks.
For New Entrants and Emerging Players: Begin with specialized high-viscosity index formulations for Japanese OEM service-fill specifications across Thai and Indonesian assembly operations. White-space concentration sits in tier-two Indian city depot networks where aging commercial vehicle stocks require extended drain interval products. Digital platform partnerships with e-commerce distributors unlock metropolitan replacement demand without legacy channel infrastructure investments.
For Investors and Strategic Acquirers: National oil companies with captive refinery supply and extensive depot networks are the most active acquirers in this space, consolidating regional blending capacity ahead of ASEAN regulatory harmonization. Five-to-ten year viability rests on synthetic formulation capabilities aligned with METI and MIIT viscosity grade compression mandates. Acquisition target archetype: specialized formulators with Japanese OEM technical approvals and Thai manufacturing presence. Monitor MIIT corporate average fuel consumption enforcement intensity as inflection indicator for premium product adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Contracted partnerships with Singapore refiners secure feedstock continuity for Southeast Asian blending plants. |
| Synthetic Portfolio Expansion | Pre-positioning 0W-16 and 0W-8 formulations captures METI and MIIT regulatory compliance premiums. |
| Tier-Two Indian Depot Network Penetration | Distribution density in Pune and Chennai corridors unlocks replacement demand from aging commercial vehicle stocks. |
| Direct Fleet Procurement Partnerships | Annual volume contracts with Bangkok and Jakarta fleet aggregators bypass traditional distributor margin layers. |
| Used Lubricant Re-Refining Capacity | Circular economy positioning addresses tightening ASEAN environmental regulations and feedstock cost volatility. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with lubricant blending plant managers, OEM platform engineers at Japanese and Korean manufacturers, aftermarket distributors in tier-two Indian cities, and fleet procurement officers in Bangkok and Jakarta informed demand segmentation. Secondary validation drew from BIS certification registries, MIIT corporate fuel consumption disclosures, METI fuel economy standard filings, and ASEAN trade customs records. Triangulation across these sources calibrated volume estimates against refinery output data and additive import flows.
Historical trendline analysis of engine oil replacement frequencies and transmission fluid content per vehicle established baseline growth parameters across the projection horizon. The analytical framework modeled segmentation across product type, end-user category, packaging format, and distribution channel, with additional dimensioning by OEM factory-fill versus aftermarket service-fill specifications. CAGRs were derived from elasticity-adjusted replacement cycle projections and synthetic penetration curves. Forecast inputs included CVT and DCT gearbox penetration rates in Korean and Chinese vehicle production and BIS certification timeline assumptions for imported lubricant formulations.
Several conditions sit outside the modeled scope, including abrupt battery electric vehicle adoption acceleration beyond current OEM platform roadmaps and unilateral ASEAN regulatory divergence from METI-MIIT viscosity grade harmonization. Forecasts reflect assumptions about synthetic blendstock availability and additive package supply chain stability. Practitioners should monitor Singapore refinery turnaround schedules and Indian BIS certification enforcement intensity for early signals of supply constraint or market access friction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Anti-Static Oil Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Biolubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Bangladesh Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Drilling Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
United States Automotive Lubricants Market
Lubricants
Global Grease Market
Lubricants
India Industrial Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market