
 Specialty Nitriles Market | 2026-2036
Specialty Nitriles Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Nitriles Market Outlook
Automotive sealing applications is consolidating as the dominant end-use vertical for specialty nitriles, displacing traditional general-purpose rubber demand in mature industrial segments. Ascend Performance Materials leverages its integrated adiponitrile-to-nylon chain to anchor high-purity nitrile supply for under-the-hood applications. Lanxess AG competes through specialized hydrogenated nitrile rubber grades that sustain temperature performance above standard NBR thresholds.
Specialty nitriles comprise nitrile-functional organic compounds and copolymers characterized by carbon-nitrile triple bond functionality, typically produced through ammoxidation of olefins or hydrocyanation processes yielding products with acrylonitrile content ranging from 18% to 50% by mass. These materials serve primarily as oil-resistant elastomers, chemical intermediates, and high-performance binders where hydrocarbon exposure would degrade conventional polymers. Acrylonitrile product types dominate current volume flows due to established butadiene copolymerization infrastructure, while ethylene nitrile grades represent the fastest-expanding structural pocket as producers target peroxide-curable formulations for aerospace hose specifications. Adhesives applications concentrate margin pools where electronics manufacturers specify ultra-low ionic content for semiconductor packaging films.
EPA industrial chemical reporting under TSCA Section 8 and REACH substance registration shape product standards by mandating full toxicological dossiers for nitrile monomers imported or manufactured above volume thresholds. China's SAMR enforces GB 31604 food-contact material limits that restrict residual acrylonitrile migration in coatings and sealants bound for consumer goods. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as specialty nitrile producers position hydrogenated grades as fluorocarbon replacements in sealing architectures without sacrificing chemical resistance profiles.
Market Dynamics
Automotive OEMs are consolidating gasket and hose specifications around hydrogenated nitrile rubber grades that withstand under-hood thermal stress above 150°C, compressing demand for conventional NBR formulations and rewiring supplier qualification timelines.
Growth Catalysts
- REACH substance registration:Full toxicological dossier requirements for acrylonitrile monomers above volume thresholds are filtering out marginal producers and concentrating supply among compliant manufacturers with established registration infrastructure.
- Fuel-resistant sealing architectures:Turbocharged direct-injection gasoline engines in passenger vehicles are specifying acrylonitrile-butadiene copolymers with elevated acrylonitrile content to resist aromatic hydrocarbon permeation.
- GB 31604 food-contact compliance:China's residual acrylonitrile migration limits for coatings and sealants are creating premium-grade demand from processors capable of sub-ppm purity certification.
Market Restraints
- Butadiene feedstock volatility:Steam cracker co-product supply swings tied to ethylene demand cycles inject margin instability into acrylonitrile-butadiene rubber production economics.
- Adiponitrile supply concentration:Integrated producers with captive hydrocyanation capacity control upstream nitrile intermediate flows, limiting merchant market access for non-integrated compounders.
- Fluorocarbon substitution ceiling:Hydrogenated nitrile grades face performance gaps against perfluoroelastomers above 180°C in aerospace fuel system seals, capping addressable market expansion.
Strategic Opportunities
- Semiconductor packaging films:Electronics manufacturers specifying ultra-low ionic content adhesives for die-attach applications represent an underpenetrated margin pool for high-purity specialty nitrile producers.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in stationary refrigeration are positioning hydrogenated nitrile seals as compliant alternatives in compressor gasket architectures.
- Ethylene-acrylonitrile peroxide cure:Convergence of metallocene polymerization with peroxide vulcanization chemistry enables aerospace hose specifications previously reserved for fluorocarbon elastomers.
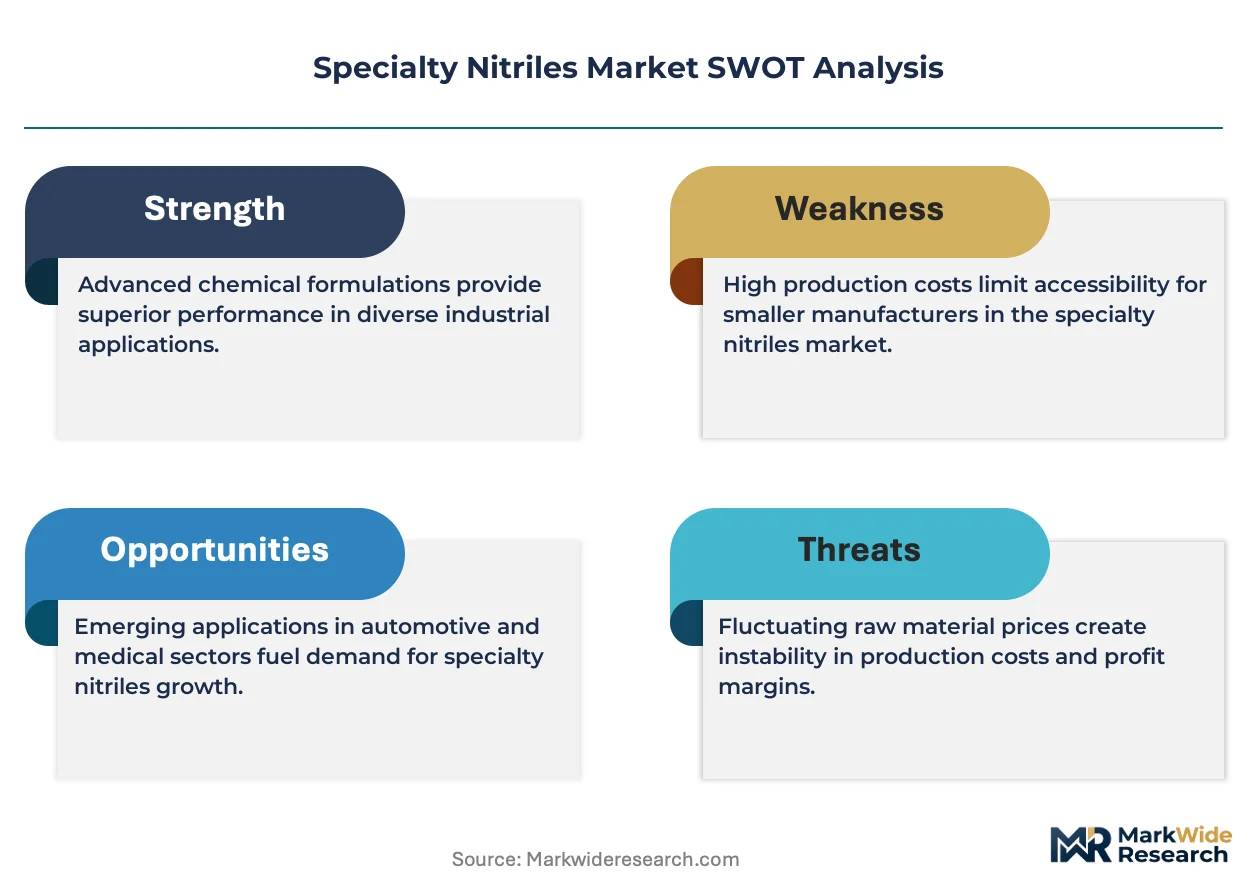
Industry Challenges
- Automotive qualification timelines:OEM validation protocols for under-hood sealing materials extend 36-48 months, compressing returns on R&D investment in next-generation nitrile grades.
- Legacy compounding asset integration:Batch-intensive NBR production lines require substantial retrofit capital to accommodate hydrogenated nitrile hydrogenation reactor infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Nitriles Market |
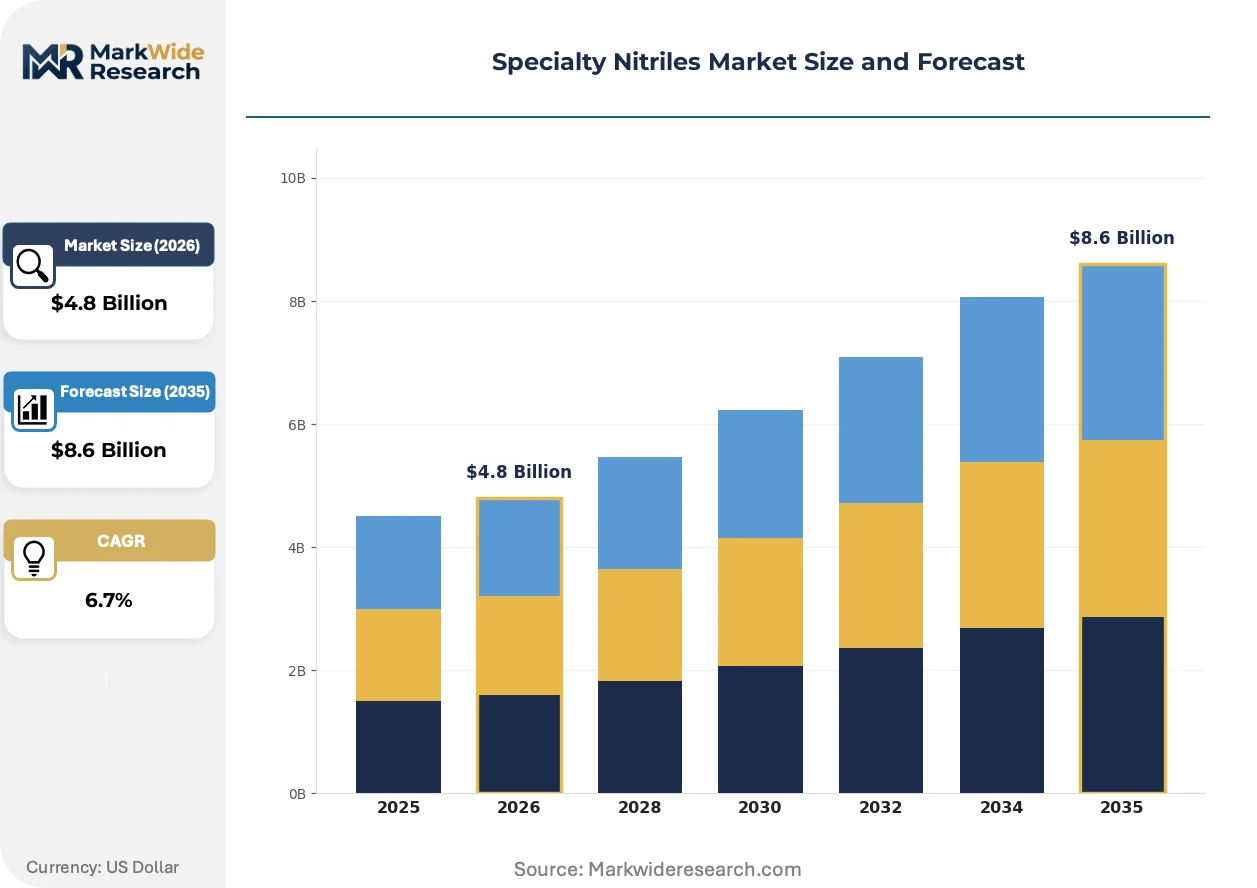
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyronitrile, Acrylonitrile, Ethylene Nitrile, Propionitrile End Use Industry: Aerospace, Automotive, Healthcare, Electronics Application: Adhesives, Coatings, Textiles, Sealants Form: Liquid, Powder, Granules, Gel |
| Companies Covered | Ascend Performance Materials, INEOS Group, AlzChem Group AG, Parchem fine & specialty chemicals, Zeon Chemicals L.P., LG Chemicals, Lanxess AG, Omnova Solutions, Emerald Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Nitriles Market Strategic Shifts
Continuous processing technology is displacing batch reactor dominance in nitrile rubber manufacturing, while regulatory chemistry restrictions and buyer consolidation are rewiring specification authority away from compounders toward OEM material engineering teams.
Metallocene-catalyzed ethylene-acrylonitrile copolymerization is decentralizing specialty nitrile supply chains by enabling smaller-scale production with tighter molecular weight distribution control. Regional compounders in Germany and Japan are adopting these systems to serve aerospace hose specifications without integrated adiponitrile feedstock positions. The technology is decentralizing volume concentration historically anchored by large-scale ammoxidation assets.
ECHA's restriction roadmap for per- and polyfluoroalkyl substances is accelerating hydrogenated nitrile substitution in European automotive and industrial sealing applications. Compounders are reformulating gasket architectures to meet PFAS-free declarations demanded by German tier-one suppliers. Hydrogenated nitrile grades with enhanced thermal stabilizer packages are capturing specification wins in transmission seal applications previously locked by fluoroelastomer incumbents.
Material engineering teams at automotive OEMs are consolidating approved supplier lists around vertically integrated nitrile producers with in-house hydrogenation and compounding capabilities. Direct sourcing agreements are displacing traditional distributor channels for high-performance grades. This concentration is most visible in Germany's automotive chemical corridor, where tier-one gasket manufacturers now qualify only producers with captive adiponitrile-to-compound supply chains.
Specialty Nitriles Market Segmentation
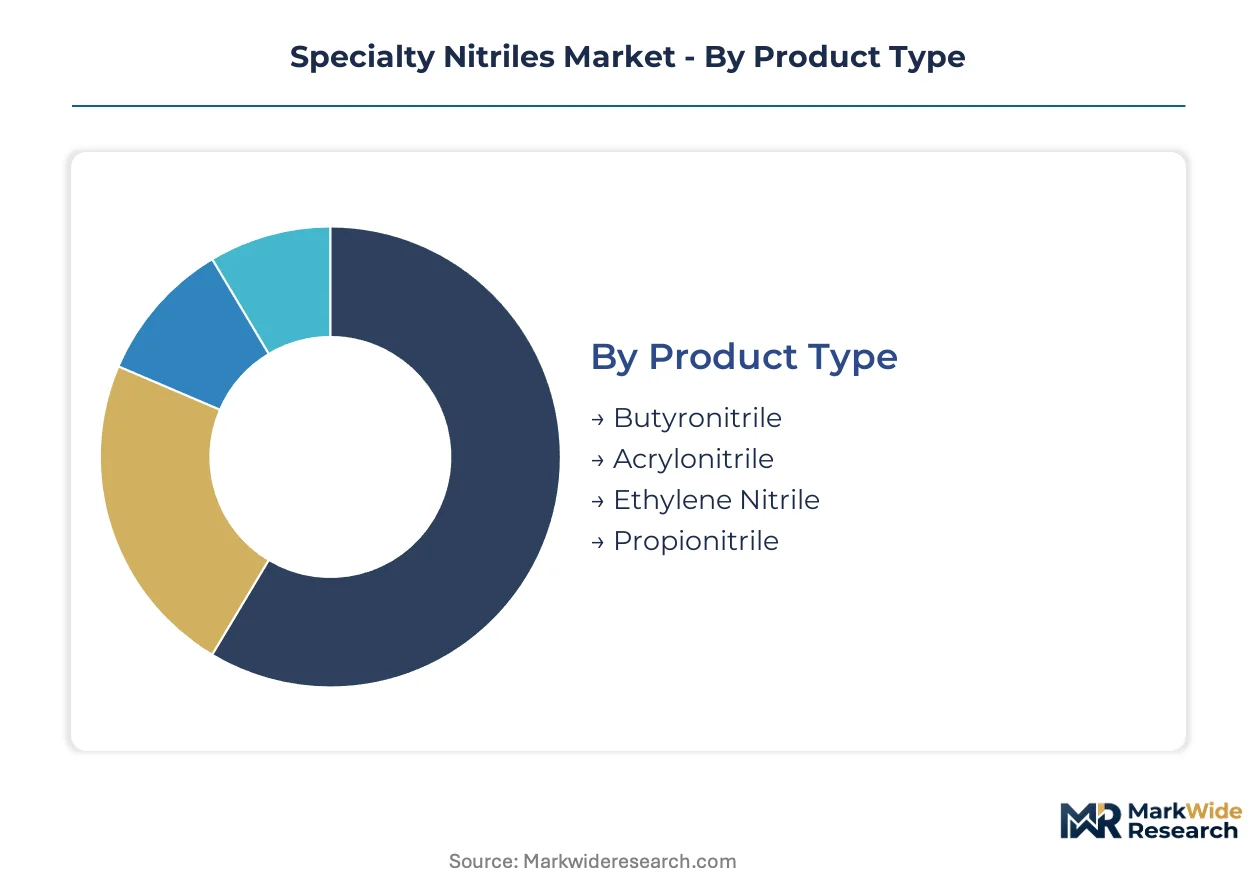
Specialty nitrile purchasing decisions pivot on performance specifications rather than commodity pricing, with buyers prioritizing acrylonitrile content thresholds, hydrogenation grades, and regulatory compliance certifications over per-kilogram costs. Segmentation reveals how material engineers at automotive OEMs and aerospace tier-one suppliers map technical requirements to specific nitrile formulations, creating distinct margin pools across product architectures.
Product Type:
Buyer specifications for fuel resistance, thermal stability, and cure chemistry determine which nitrile backbone enters formulation trials, with acrylonitrile content percentage and hydrogenation degree serving as the primary technical filters.
- Acrylonitrile:Carbon-nitrile triple bond functionality delivered through ammoxidation of propylene yields the dominant nitrile intermediate for butadiene copolymerization. Automotive under-hood sealing applications in Germany's chemical corridor specify elevated acrylonitrile content above 40% to resist aromatic hydrocarbon permeation from turbocharged gasoline direct-injection engines.
- Ethylene Nitrile:Metallocene-catalyzed copolymerization with ethylene enables peroxide-curable formulations that withstand sustained thermal stress above 150°C. Aerospace hose manufacturers in Japan and Germany are qualifying these grades for fuel system architectures previously reserved for fluorocarbon elastomers, climbing the fastest among structural categories.
- Butyronitrile:Four-carbon aliphatic nitrile serving as a chemical intermediate for pharmaceutical synthesis and specialty solvent applications.
- Propionitrile:Three-carbon nitrile compound utilized in extraction processes and as a precursor for agrochemical active ingredients.
Acrylonitrile leads on scale; ethylene nitrile leads on momentum.
End Use Industry:
Application-specific performance thresholds create divergent purity and certification requirements, with each vertical imposing distinct regulatory compliance burdens on suppliers.
- Automotive:OEM material engineering teams consolidate approved supplier lists around hydrogenated nitrile grades for transmission seals, fuel system gaskets, and turbocharger hoses. REACH substance registration and 36-48 month qualification timelines filter supply toward integrated producers with captive hydrogenation capacity.
- Aerospace:Peroxide-curable ethylene-acrylonitrile specifications for fuel system seals demand sub-ppm metallic contamination limits and full toxicological dossiers per EPA TSCA Section 8 reporting thresholds.
- Electronics:Semiconductor packaging film applications specify ultra-low ionic content adhesives for die-attach formulations, creating premium margin pools for high-purity specialty nitrile producers capable of sub-ppb ionic certification.
- Healthcare:Medical device seal and tubing applications require compliance with FDA biocompatibility testing protocols and extractables profiling for nitrile-containing polymers.
Automotive commands volume concentration; electronics offers the steepest expansion trajectory for purity-differentiated grades.
Application:
Functional performance requirements across bonding, surface protection, fiber treatment, and gap-filling roles determine formulation complexity and pricing differentiation.
- Sealants:Hydrogenated nitrile rubber compounds dominate under-hood and industrial sealing architectures where hydrocarbon exposure and thermal cycling degrade conventional elastomers. EU F-Gas Regulation phase-down is accelerating substitution for fluorinated seals in stationary refrigeration compressor gaskets.
- Adhesives:Electronics manufacturers drive specification authority toward ultra-low ionic content grades for semiconductor packaging films, with ionic contamination thresholds below 10 ppb separating qualified from marginal suppliers.
- Coatings:Residual acrylonitrile migration limits under China's GB 31604 food-contact material standards restrict coating formulations bound for consumer goods packaging.
- Textiles:Nitrile-functional binders and finishes provide oil and solvent resistance for technical textile applications in industrial protective equipment.
Sealants anchor revenue scale; adhesives in electronics represent the fastest-climbing application vertical.
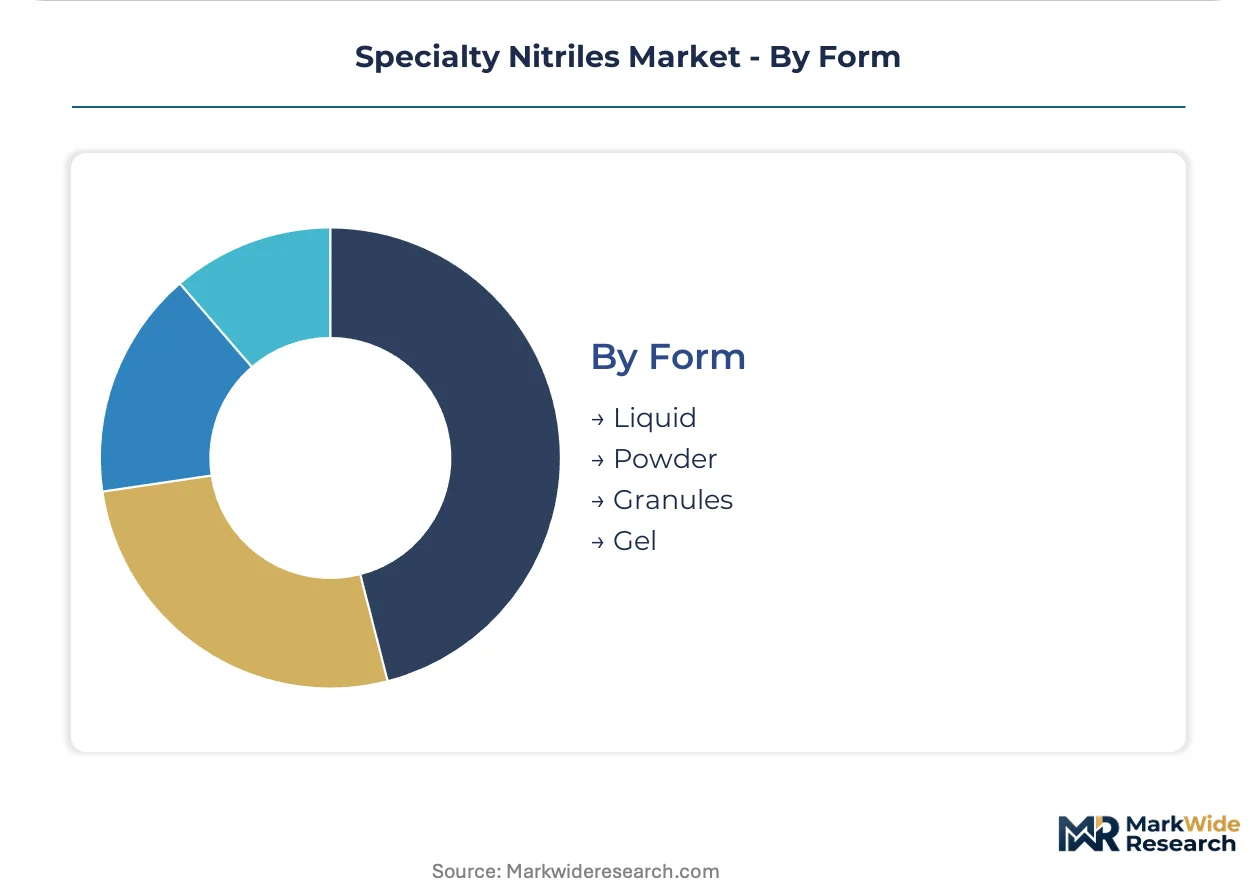
Form:
Processing method and end-use integration requirements determine physical state selection, with liquid and powder forms commanding distinct supply chain configurations.
- Liquid:Pumpable nitrile monomers and oligomers serve continuous polymerization processes and adhesive formulation lines where precise metering and rapid dispersion are required. Batch-intensive NBR production lines in Germany's automotive chemical corridor favor liquid feedstock for compounding efficiency.
- Powder:Free-flowing nitrile rubber powders enable dry blending with thermoplastics and thermoset resins for modified polymer compounds. Powder handling infrastructure at compounder facilities favors this form for inventory stability and precise dosing.
- Granules:Pelletized nitrile elastomers facilitate extrusion and injection molding operations in automotive gasket manufacturing.
- Gel:Partially cross-linked nitrile formulations serve specialized coating and sealant applications requiring thixotropic flow characteristics.
Liquid nitrile leads on processing throughput; powder leads on formulation flexibility momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward jurisdictions with streamlined chemical registration regimes is reshaping competitive positioning. REACH compliance costs in Europe and EPA reporting thresholds in the United States create arbitrage opportunities for producers in Asian manufacturing hubs with less burdensome toxicological dossier requirements.
Germany
Automotive OEMs in Stuttgart and Munich specify hydrogenated nitrile grades for transmission seals and turbocharger hoses. ECHA's PFAS restriction roadmap accelerates substitution away from fluorocarbon elastomers. The automotive chemical corridor around Ludwigshafen concentrates tier-one gasket manufacturers qualifying only integrated producers with captive adiponitrile supply chains.
United States
EPA TSCA Section 8 reporting mandates full toxicological dossiers for acrylonitrile monomers above volume thresholds. The Gulf Coast petrochemical complex leverages integrated steam cracker infrastructure to supply butadiene feedstock for NBR production. Houston-area compounders serve aerospace fuel system seal specifications with peroxide-curable ethylene-acrylonitrile formulations.
China
SAMR enforces GB 31604 food-contact material limits restricting residual acrylonitrile migration in coatings and sealants. The Yangtze River Delta hosts specialty chemical producers targeting electronics packaging film applications with ultra-low ionic content grades. Shanghai-based processors invest in metallocene polymerization systems to serve semiconductor die-attach adhesive specifications.
Japan
METI industrial standards govern nitrile rubber purity thresholds for automotive and electronics applications. The Nagoya industrial corridor supplies aerospace hose manufacturers qualifying ethylene-acrylonitrile grades for fuel system architectures. Osaka-area compounders develop peroxide-curable formulations to displace fluorocarbon elastomers in high-temperature sealing.
South Korea
MFDS pharmaceutical-grade certification requirements filter nitrile intermediate supply for medical device seal applications. The Ulsan petrochemical complex anchors acrylonitrile-butadiene rubber production for export to automotive OEMs in Germany and the United States. Seoul-based material engineering teams consolidate approved supplier lists around hydrogenated nitrile producers with in-house hydrogenation capabilities.
Specialty Nitriles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding premium-tier positioning in automotive sealing while regional compounders serve specification-driven aerospace and electronics niches. The market structure concentrates around adiponitrile-to-compound supply chains, filtering merchant market access for non-integrated players. Three archetypes dominate: vertically integrated petrochemical majors with captive hydrocyanation capacity, specialized hydrogenated nitrile rubber producers with dedicated hydrogenation infrastructure, and regional compounders leveraging metallocene polymerization for small-batch aerospace specifications. Competitive moves center on backward integration into adiponitrile intermediates and strategic partnerships with automotive OEM material engineering teams to compress 36-48 month qualification timelines.
Among integrated petrochemical majors, Ascend Performance Materials and INEOS Group exemplify the archetype of producers with captive adiponitrile-to-nylon chains anchoring high-purity nitrile supply. Lanxess AG occupies a position within the specialized hydrogenated nitrile tier, representing producers competing through enhanced thermal stabilizer packages for transmission seal applications.
| Leading Market Players |
|---|
| Ascend Performance Materials |
| INEOS Group |
| AlzChem Group AG |
| Parchem fine & specialty chemicals |
| Zeon Chemicals L.P. |
| LG Chemicals |
| Lanxess AG |
| Omnova Solutions |
| Emerald Performance Materials |
| Others |
Value Chain & Pricing Dynamics
Continuous processing technology is displacing batch reactor dominance in nitrile rubber manufacturing, simultaneously compressing unit production costs and concentrating supply among capital-intensive producers with hydrogenation infrastructure. This dual effect reshapes pricing power toward integrated adiponitrile-to-compound operators while marginalizing non-integrated compounders in Germany's automotive chemical corridor.
Pricing Analysis
Distributor margins on standard NBR grades have compressed as automotive OEMs consolidate direct sourcing agreements with integrated producers. Pricing stratifies across hydrogenated premium grades, REACH-compliant standard tiers, and economy NBR formulations. Cost compression in conventional NBR runs through butadiene feedstock volatility tied to steam cracker economics. Tier-one gasket manufacturers show least price sensitivity for hydrogenated grades with captive adiponitrile supply, while regional compounders remain most exposed to spot butadiene swings.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta and South Korea's Ulsan petrochemical complex are reshaping sourcing patterns for electronics and medical device applications. Supply concentrates in Germany, China, and the United States, with adiponitrile intermediates feeding from hydrocyanation assets in Ludwigshafen and the Gulf Coast. The chain draws from butadiene co-product streams, ammonia feedstock, and metallocene catalyst systems. Single-source vulnerability sits with integrated adiponitrile producers controlling upstream nitrile intermediate flows. Distribution runs through direct OEM supply agreements displacing traditional distributor channels for high-performance grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty nitriles function as a regulatory compounder where ECHA's PFAS restriction roadmap is accelerating hydrogenated nitrile substitution and rewiring supplier qualification criteria across European automotive sealing.
For Market Incumbents: Cement backward integration into adiponitrile intermediates to defend margin position against merchant market squeeze. Lock in 36-48 month automotive qualification timelines through strategic partnerships with Stuttgart and Munich OEM material engineering teams. Prioritize hydrogenation capacity expansion to capture specification wins in transmission seal applications displacing fluorocarbon elastomers.
For New Entrants and Emerging Players: Regional compounders in Japan and Germany represent the most penetrable channel partner type for aerospace hose specifications using metallocene polymerization systems. Target semiconductor packaging film adhesives where ultra-low ionic content requirements filter qualified suppliers. Pursue white-label compounding arrangements with tier-one gasket manufacturers seeking PFAS-free hydrogenated nitrile formulations.
For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated compounders with legacy NBR batch assets requiring hydrogenation retrofit capital. Long-term viability over the coming decade hinges on captive adiponitrile positions and automotive OEM direct sourcing relationships. Watch for EU F-Gas Regulation enforcement acceleration as the inflection signal for hydrogenated nitrile substitution velocity in stationary refrigeration compressor seals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Captive hydrocyanation capacity secures upstream nitrile intermediate supply for German automotive OEMs. |
| Hydrogenation Reactor Infrastructure | Enables qualification for 150°C-plus under-hood sealing specifications displacing conventional NBR. |
| Metallocene Polymerization Adoption | Decentralizes production scale for aerospace ethylene-acrylonitrile grades without integrated feedstock positions. |
| REACH Substance Registration | Full toxicological dossier compliance filters marginal producers and concentrates supply among registered operators. |
| Direct OEM Material Engineering Partnerships | Compresses 36-48 month qualification timelines and displaces distributor channels for premium grades. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at adiponitrile production facilities, procurement leads at tier-one automotive gasket manufacturers, technical R&D directors at hydrogenated nitrile compounders, and distribution channel partners in Germany's chemical corridor. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings from listed petrochemical majors, and EPA TSCA Section 8 substance registration databases. Bottom-up volume modeling and top-down value reconciliation anchored all segment outputs.
Segment-weighting across product type, end-use industry, application, and regional production hub dimensions structured the analytical framework across the analysis window. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity modeling for automotive sealing, aerospace hose, and electronics adhesive verticals. Key inputs included butadiene feedstock cost curves, automotive OEM platform production schedules, and regulatory compliance cost burdens for REACH and GB 31604 certification.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA PFAS restriction enforcement timing, steam cracker operating rate volatility affecting butadiene co-product availability, and metallocene catalyst technology diffusion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Potting Compound Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Propoxylates Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Europe Microencapsulation Market