
 US Plastics Market | 2026-2036
US Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
US Plastics Market Insights
Advanced mechanical recycling and chemical depolymerization is narrowing the performance gap between virgin and reprocessed resins in automotive structural applications. Dow Chemical Company leverages its Gulf Coast ethane cracker network to sustain cost-advantaged polyethylene supply for flexible packaging films. ExxonMobil Corporation anchors its position through proprietary metallocene catalyst technology that differentiates performance-grade polypropylene for medical and automotive tiers. LyondellBasell Industries competes on circular polymer output, operating mechanical recycling facilities that process post-consumer HDPE into food-contact compliant resins.
Plastics encompass synthetic or semi-synthetic organic polymers—primarily carbon, hydrogen, oxygen, nitrogen, sulfur, and chlorine backbones—formulated through addition or condensation reactions into thermoplastics, thermosets, or elastomers with melt flow indices ranging from 0.3 to 150 g/10min. These materials serve as lightweight, corrosion-resistant substitutes for metal, glass, and wood across industrial and consumer applications where design flexibility and cost efficiency predominate. Polyethylene leads product type volume due to its dominance in flexible packaging films and blow-molded containers, while polypropylene captures expanding automotive interior and under-hood component demand as OEMs pursue weight reduction targets. Injection molding technology occupies the largest processing share, though 3D printing represents the fastest-growing fabrication method for prototyping and short-run custom components in aerospace tooling and medical device fixtures.
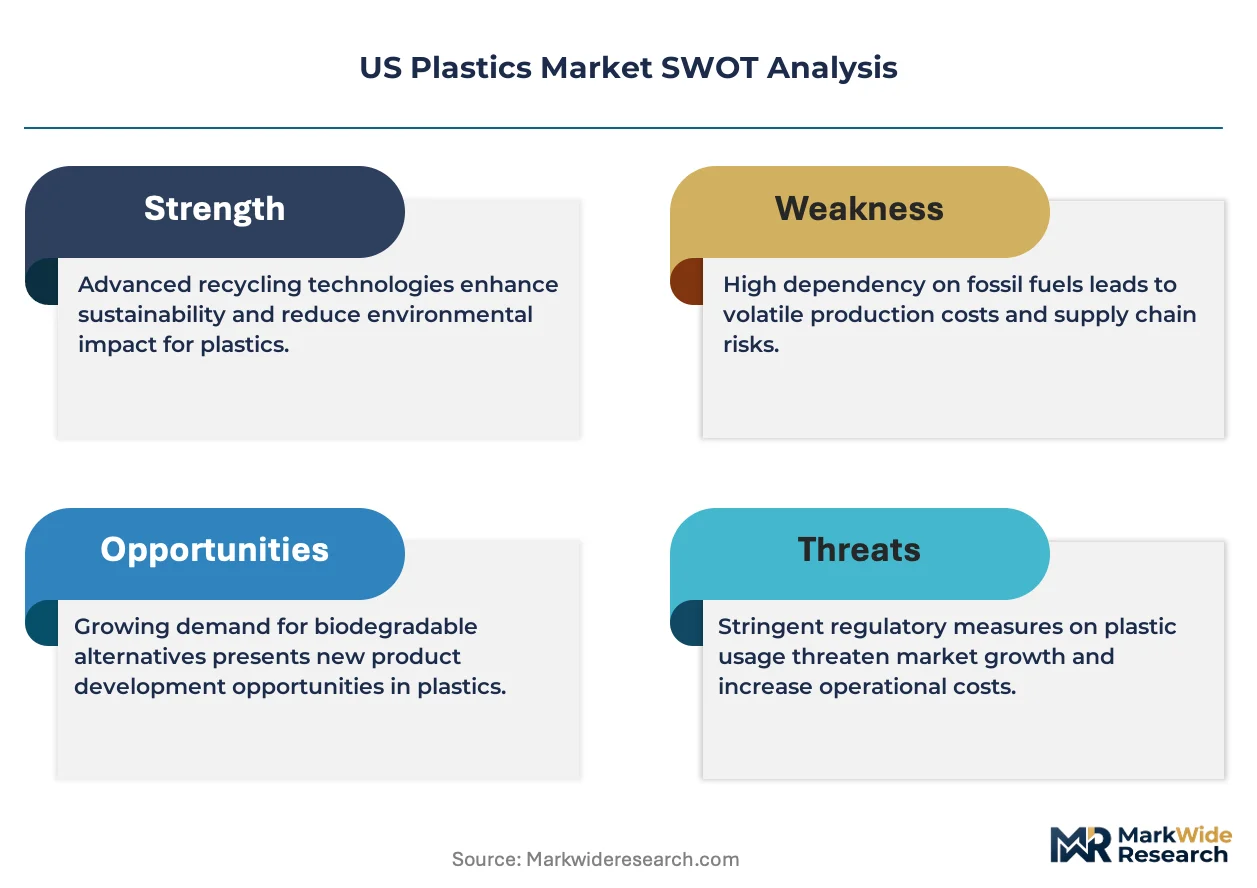
The EPA enforces Toxic Substances Control Act reporting requirements for novel polymer chemistries, while OSHA mandates permissible exposure limits for vinyl chloride monomer in PVC production facilities, collectively elevating compliance costs for chlorinated resin processors. State-level extended producer responsibility frameworks in California and Oregon reshape packaging design requirements, forcing brand owners to fund collection infrastructure or face material restrictions. Stakeholders must monitor how the FTC's evolving Green Guides interpret recycled content claims, as enforcement actions against unsubstantiated environmental marketing reshape procurement specifications and supplier qualification protocols.
Market Dynamics
EPA recycled content mandates under the National Recycling Strategy are redirecting virgin resin procurement toward post-consumer feedstock streams, compressing margins for conventional petrochemical-based supply chains while elevating circular polymer premiums.
Growth Catalysts
- Automotive Lightweighting:OEM weight reduction targets sustain polyethylene demand across Michigan and Ohio assembly corridors, with blow-molded fuel tanks and structural components displacing metal stampings.
- Chemical Depolymerization:Advanced pyrolysis and solvolysis processes narrow the performance gap between virgin and reprocessed resins for automotive structural applications.
- Great Lakes Packaging Cluster:Blow molding capacity concentrates around Chicago and Detroit logistics nodes, capturing inbound resin flows and outbound distribution efficiencies for flexible film and container markets.
Market Restraints
- Ethane Feedstock Volatility:Gulf Coast cracker economics tie polyethylene cost structures to natural gas liquid pricing swings, exposing margin compression during feedstock inflation cycles.
- Chlorinated Resin Compliance Burden:OSHA permissible exposure limits for vinyl chloride monomer elevate compliance costs for PVC processors, particularly in legacy production facilities.
- Mechanical Recycling Contamination:Post-consumer HDPE sortation limitations restrict food-contact resin yields, constraining circular supply scalability.
Strategic Opportunities
- California EPR Frameworks:Extended producer responsibility mandates force brand owners to fund collection infrastructure, creating service revenue pools for integrated recycler-processor hybrids.
- Medical-Grade Polypropylene:Metallocene catalyst differentiation opens high-margin tiers for sterilizable device housings and diagnostic consumables.
- 3D Printing Tooling:Aerospace and medical fixture prototyping represents an underpenetrated channel for short-run custom component fabrication.
Industry Challenges
- Polymer Chemist Talent Scarcity:Novel resin formulation expertise concentrates among aging workforce cohorts, constraining R&D velocity for next-generation circular materials.
- FTC Green Guide Enforcement:Unsubstantiated recycled content claims trigger procurement specification revisions and supplier qualification protocol disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Plastics Market |
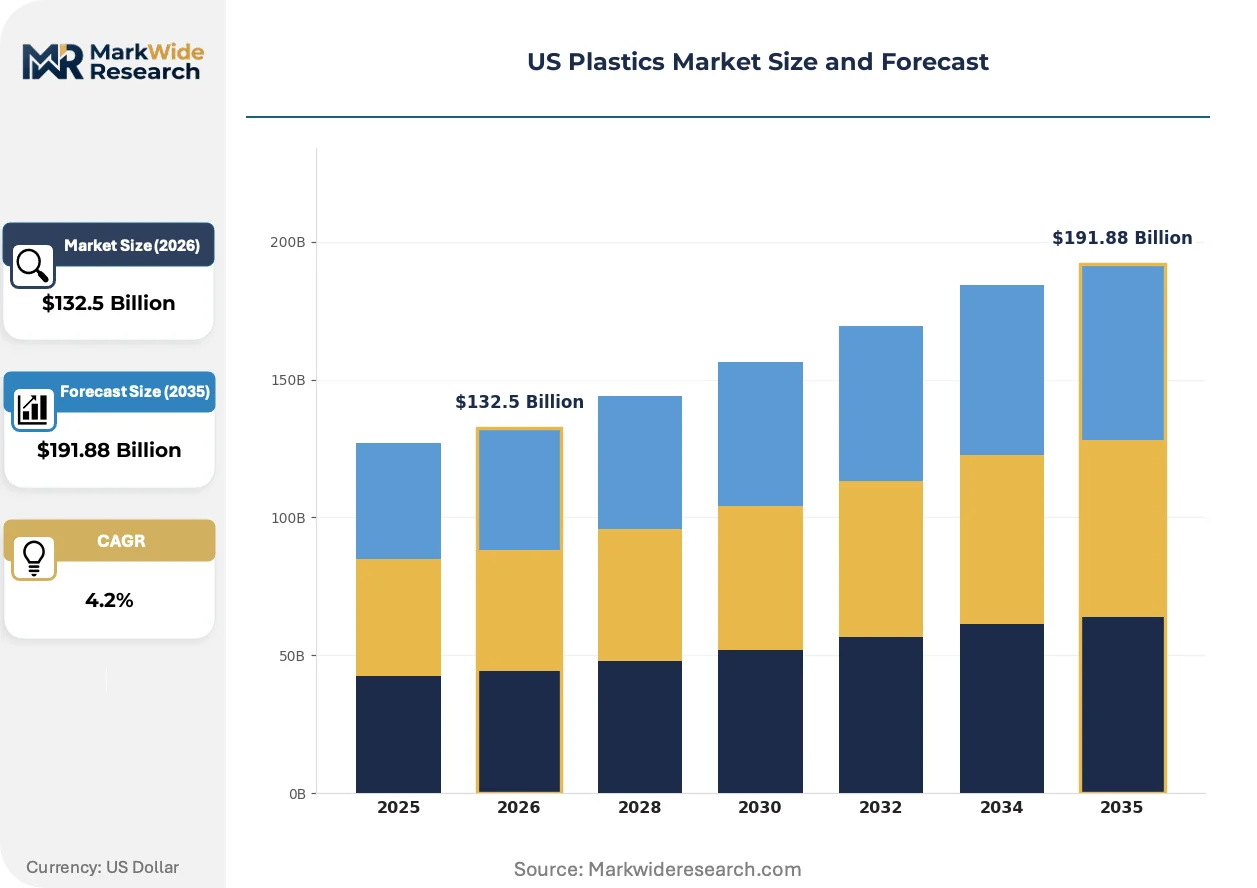
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $191.88 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, PVC End User: Packaging, Automotive, Consumer Goods, Construction Technology: Injection Molding, Blow Molding, Extrusion, 3D Printing Application: Containers, Films, Pipes, Components |
| Companies Covered | Dow Chemical Company, ExxonMobil Corporation, LyondellBasell Industries, BASF SE, DuPont, Formosa Plastics Corporation, Huntsman Corporation, SABIC, Borealis AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Plastics Market Trends and Innovations
Mechanical and chemical recycling convergence is collapsing the virgin-reprocessed resin quality differential, while regulatory pressure on embodied carbon intensifies process innovation across the value chain.
Pyrolysis-based chemical recycling is rendering obsolete the technical limitations that previously confined post-consumer plastics to downcycled applications. Automotive Tier 1 suppliers are qualifying pyrolysis-derived naphtha for under-hood components at accelerated timelines. This technology is rendering obsolete the historical trade-off between sustainability credentials and performance specifications in structural applications.
EPA's advancing recycled content mandates under the National Recycling Strategy are forcing packaging redesign cycles and feedstock contract restructuring. Brand owners face material restrictions or infrastructure funding obligations under state-level extended producer responsibility frameworks in California and Oregon. Flexible packaging converters in the Great Lakes industrial belt are responding by securing long-term offtake agreements with mechanical recycling facilities.
Buyer concentration among national retail chains is compressing supplier negotiation cycles and unbundling after-sales technical service from resin supply contracts. Procurement teams at large CPG brands now mandate third-party certified recycled content verification, displacing traditional supplier quality assurances. This concentration is most visible in the Chicago-Detroit logistics corridor, where blow molding capacity serves consolidated retail distribution networks.
US Plastics Market Segmentation
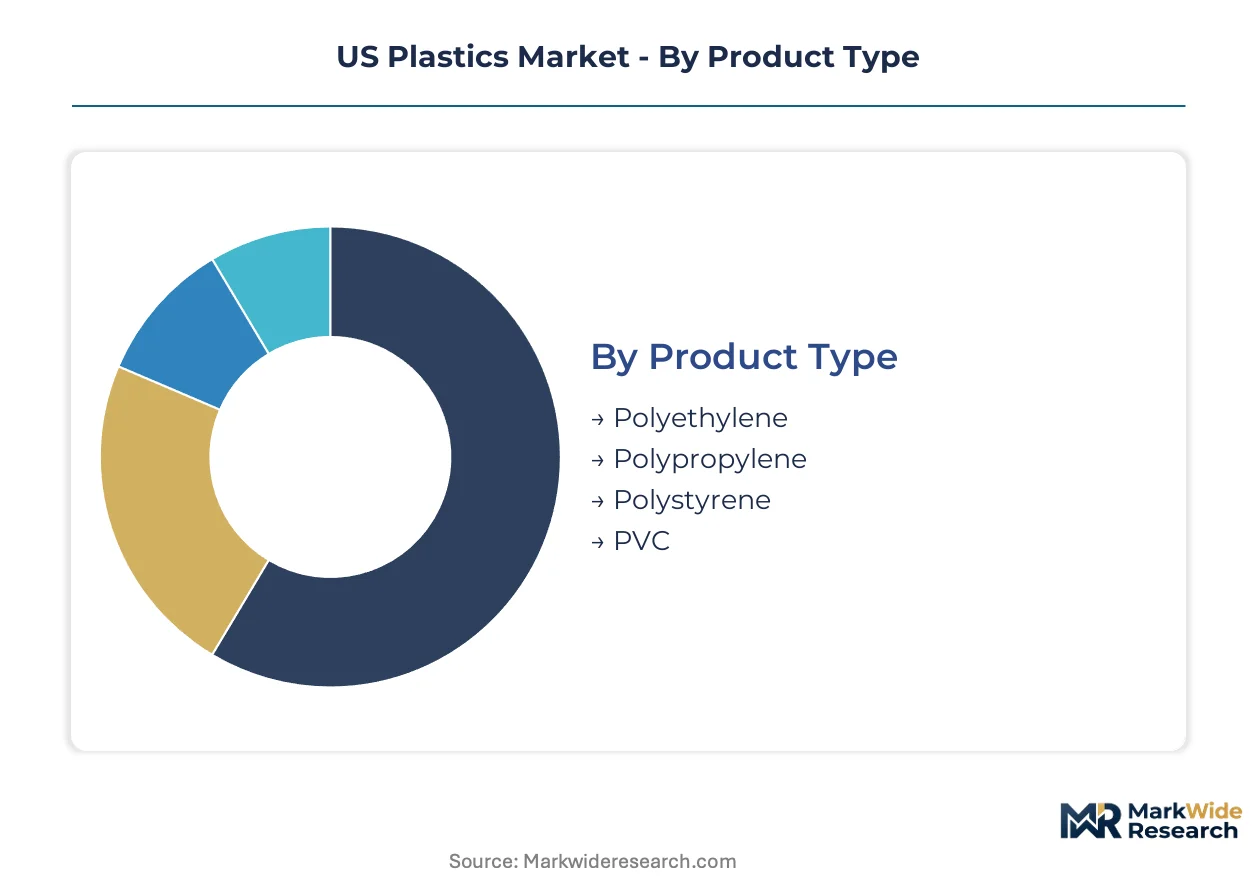
Segmentation reveals how resin chemistry, fabrication technology, and end-use specifications create distinct competitive arenas within the US plastics value chain. Each dimension carries unique margin profiles and regulatory exposure that reshape procurement priorities.
Product Type:
Cost tier differentiation separates commodity thermoplastics from performance-engineered grades, with feedstock economics and catalyst technology determining competitive positioning.
- Polyethylene:Linear low-density and high-density variants dominate flexible packaging films and blow-molded containers. Michigan and Ohio automotive corridors sustain demand for fuel tank and structural component applications as OEMs pursue weight reduction targets.
- Polypropylene:Metallocene-catalyzed grades deliver sterilizable medical device housings and under-hood automotive components. The material captures expanding interior trim demand across Detroit-area assembly plants where heat resistance specifications exceed polyethylene capabilities.
- Polystyrene:Expandable grades serve food service disposables and protective packaging. California EPR mandates compress single-use applications.
- PVC:Chlorinated backbone formulations face OSHA vinyl chloride monomer exposure limits that elevate compliance costs for Gulf Coast processors.
Polyethylene commands the established base. The steepest expansion runs through polypropylene.
End User:
Application maturity varies sharply across customer industries, with regulatory intensity and circular economy readiness reshaping contract structures.
- Packaging:Flexible films and rigid containers absorb the majority of polyethylene volume. Chicago-Detroit logistics nodes concentrate blow molding capacity to serve consolidated retail distribution networks.
- Automotive:Structural components and interior systems drive polypropylene qualification programs. EPA recycled content mandates redirect Tier 1 supplier procurement toward post-consumer feedstock streams.
- Consumer Goods:Durable housewares and appliances utilize engineering-grade formulations. FTC Green Guide enforcement pressures brand owners toward third-party certified recycled content verification.
- Construction:Pipe extrusion and siding applications rely on PVC and HDPE durability specifications. OSHA compliance burdens weigh heavily on chlorinated resin processors serving infrastructure markets.
Packaging captures the volume anchor position. Automotive demonstrates the most rapid specification evolution.
Technology:
Process selection determines cycle economics, design flexibility, and scrap rates across fabrication operations.
- Injection Molding:High-volume precision molding dominates automotive interior components and medical device housings. Michigan tooling corridors maintain specialized expertise for multi-cavity mold design.
- Blow Molding:Extrusion and injection blow processes serve fluid container markets. Great Lakes industrial belt capacity clusters around resin inbound flows and finished goods distribution.
- Extrusion:Film, sheet, and pipe production lines scale efficiently for construction and packaging applications. Post-consumer HDPE contamination limits constrain food-contact film yields.
- 3D Printing:Fused deposition modeling and selective laser sintering enable aerospace tooling and medical fixture prototyping. The technology gains traction for short-run custom components where traditional mold costs prove prohibitive.
Injection molding holds the installed capacity base. 3D printing climbs the fastest as a fabrication alternative.
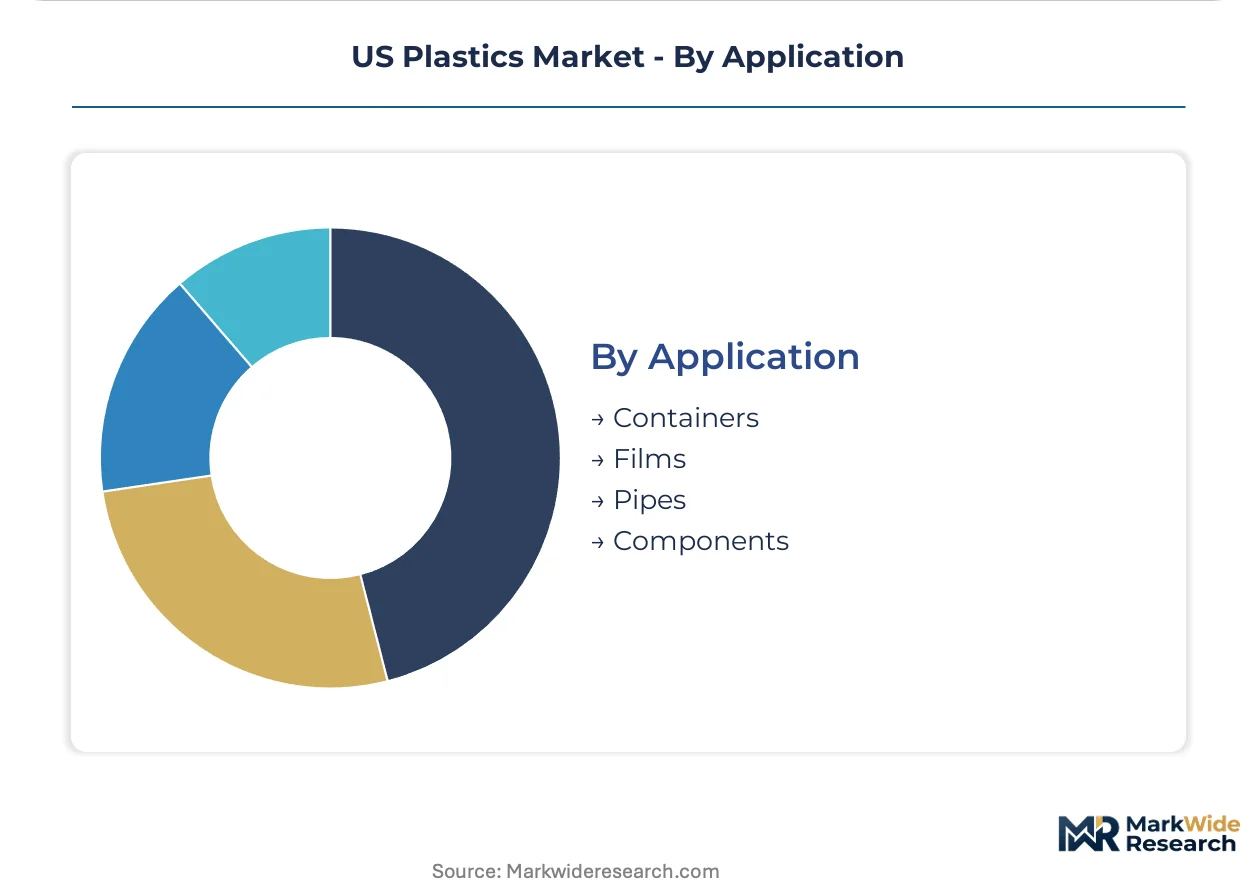
Application:
Functional requirements dictate resin selection, with barrier properties, mechanical load tolerance, and regulatory compliance defining specification boundaries.
- Containers:Blow-molded HDPE and PET bottles serve beverage and household chemical markets. California and Oregon EPR frameworks force brand owners to fund collection infrastructure or face material restrictions.
- Films:Multilayer flexible packaging structures demand precise barrier layer engineering. Mechanical recycling contamination challenges limit post-consumer content ratios in food-contact applications.
- Pipes:Pressure-rated PVC and HDPE formulations serve water infrastructure and natural gas distribution. Gulf Coast ethane cracker economics influence polyethylene cost structures for municipal procurement.
- Components:Injection-molded automotive and electrical parts require dimensional stability under thermal cycling. Chemical depolymerization processes narrow the quality differential for recycled-content structural grades.
Containers represent the mature demand core. Components gain share fastest through automotive lightweighting programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US plastics trade flows reflect a net export position in polyethylene resins balanced against substantial imports of specialized engineering grades from European and Asian suppliers. Regional production clusters concentrate near Gulf Coast feedstock supplies and Great Lakes manufacturing demand centers.
Gulf Coast Texas-Louisiana
Ethane cracker complexes along the Houston Ship Channel and Lake Charles corridor generate cost-advantaged polyethylene feedstock for domestic flexible packaging markets. EPA Clean Air Act enforcement shapes emissions compliance investments for chlorinated resin processors operating along this petrochemical belt. Port Houston handles bulk resin exports to Latin American converters while receiving specialty additive imports from German chemical suppliers.
Great Lakes Industrial Belt
Chicago and Detroit logistics nodes concentrate blow molding capacity for beverage containers and automotive fuel tank applications. Michigan and Ohio assembly corridors sustain polypropylene demand for interior trim and under-hood components as OEMs pursue weight reduction targets. OSHA vinyl chloride monomer exposure limits elevate compliance costs for PVC processors serving regional construction markets.
California
Extended producer responsibility frameworks under SB 54 force brand owners to fund collection infrastructure or face material restrictions on single-use packaging. CalRecycle enforcement actions reshape procurement specifications for food-contact compliant resins. Los Angeles and San Francisco Bay Area converters secure long-term offtake agreements with mechanical recycling facilities to meet recycled content mandates.
Southeast Atlantic
Georgia and South Carolina automotive assembly plants drive polypropylene qualification programs for interior systems and structural components. EPA recycled content mandates redirect Tier 1 supplier procurement toward post-consumer feedstock streams. Charleston and Savannah ports facilitate resin imports from Middle Eastern producers serving regional packaging converters.
Pacific Northwest
Oregon's EPR legislation mirrors California frameworks, compressing single-use polystyrene applications and redirecting investment toward circular polymer infrastructure. Seattle-area converters specialize in medical-grade polypropylene for sterilizable device housings and diagnostic consumables. Columbia River logistics corridors support barge-based resin distribution to inland packaging markets.
US Plastics Market Competitive Landscape
On the supply side, the industry is consolidated around integrated petrochemical majors with captive ethane feedstock positions and specialized recyclers building circular polymer capabilities. Three strategic archetypes dominate competitive positioning: Gulf Coast ethane crackers leveraging cost-advantaged natural gas liquids, European-headquartered multinationals with metallocene catalyst differentiation, and mechanical recycling specialists securing food-contact compliant resin certifications. Dominant competitive moves include backward integration into post-consumer collection infrastructure and technology licensing agreements for pyrolysis-based chemical recycling.
Within the integrated petrochemical tier, Dow Chemical Company, ExxonMobil Corporation, and LyondellBasell Industries exemplify scale-driven positioning anchored to Gulf Coast feedstock economics. These entities represent the cost-leadership archetype through ethane cracker networks, while simultaneously building circular polymer capabilities to capture recycled content premiums under EPA mandates. Their market presence reflects the structural tension between virgin resin scale advantages and regulatory pressure toward post-consumer feedstock adoption.
| Leading Market Players |
|---|
| Dow Chemical Company |
| ExxonMobil Corporation |
| LyondellBasell Industries |
| BASF SE |
| DuPont |
| Formosa Plastics Corporation |
| Huntsman Corporation |
| SABIC |
| Borealis AG |
| Others |
Pricing and Supply Chain Analysis
The Chicago-Detroit logistics corridor freight economics compress polyethylene margins for Great Lakes converters while amplifying pricing power for Gulf Coast ethane crackers serving flexible packaging markets. Resin procurement costs diverge sharply between automotive Tier 1 suppliers locked into long-term offtake contracts and spot-market buyers exposed to natural gas liquid volatility cycles.
Pricing Analysis
Virgin-to-recycled resin pricing gaps separate current-generation mechanical recycling outputs from next-generation chemical depolymerization grades and legacy virgin polyethylene benchmarks. Contract-based long-term offtake structures dominate automotive and packaging procurement, with price differentiation driven by FDA food-contact certification tiers and volume scale commitments. Cost compression in commodity polyethylene intensifies as Gulf Coast cracker expansions elevate domestic supply availability. National retail chains demonstrate acute price sensitivity through consolidated procurement mandates, while medical device manufacturers absorb premiums for metallocene-catalyzed polypropylene sterilization grades.
Supply Chain Analysis
Tariff exposure between US and Chinese specialty additive suppliers elevates formulation cost uncertainty for compounding operations serving automotive and medical tiers. Geographic supply concentration centers on US Gulf Coast ethane cracker complexes, Canadian natural gas liquid feedstocks, and German catalyst technology imports. Raw material dependencies rest on ethane purity specifications, metallocene catalyst proprietary supply, and post-consumer bale quality for mechanical recycling feedstock. Single-source vulnerability concentrates in specialized medical-grade resin certifications. Distribution runs through bulk rail terminals, barge networks along the Mississippi River system, and just-in-time truck delivery to Chicago-Detroit blow molding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US plastics market fragmentation creates acquisition targets as EPA recycled content mandates splinter unified procurement specifications into grade-specific compliance tiers. Brand owner redesign cycles fragment formerly standardized resin contracts into customized circular feedstock agreements.
For Market Incumbents: Harden circular polymer capabilities through backward integration into post-consumer collection infrastructure across California and Oregon EPR zones. Consolidate mechanical recycling assets serving food-contact compliant resin demand as FTC Green Guide enforcement elevates third-party certification requirements. Capacity expansion in pyrolysis-based chemical recycling preserves margin position against virgin resin commoditization pressures. For New Entrants and Emerging Players: Build out medical-grade polypropylene compounding operations targeting Seattle-area sterilizable device housing demand. Aerospace and medical fixture prototyping via 3D printing represents the most penetrable white-space channel where traditional mold economics deter incumbents. Secure FDA master file status as the primary go-to-market angle for premium resin qualification programs. For Investors and Strategic Acquirers: Regional mechanical recycling specialists with CalRecycle food-contact certifications command scarcity premiums as California SB 54 compliance deadlines accelerate. Long-term viability across the analysis window hinges on circular infrastructure deployment velocity outpacing virgin resin cost curves. Monitor EPA National Recycling Strategy enforcement intensity as the inflection signal for recycled content premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Captures post-consumer feedstock streams under California and Oregon EPR mandates. |
| Pyrolysis Capacity Buildout | Qualifies automotive Tier 1 suppliers for structural component recycled content specifications. |
| FDA Food-Contact Certification Investment | Unlocks premium pricing tiers for mechanical recycling facilities serving flexible packaging converters. |
| Metallocene Catalyst Licensing Agreement | Differentiates polypropylene grades for sterilizable medical device housing applications. |
| Long-term Supply Agreement with Retail Chains | Locks in volume commitments as buyer concentration compresses negotiation cycles. |
Research Methodology
Desk research of trade association resin shipment data, SEC petrochemical segment disclosures, and EPA enforcement action records preceded structured interviews with plant managers at Gulf Coast ethane crackers, procurement leads at Detroit-area automotive Tier 1 suppliers, mechanical recycling facility operators, and FDA regulatory affairs specialists. Bottom-up volume estimates from individual production facility capacities were triangulated against top-down demand calculations derived from end-use industry consumption patterns.
Assumptions held fixed across the modeling period include EPA recycled content mandate enforcement timelines and natural gas liquid feedstock cost structures, while variables tested included chemical recycling technology adoption rates and California EPR framework expansion to additional states. Segmentation dimensions modeled encompass resin chemistry grade, fabrication technology, end-use industry, and regional production hub clustering. CAGRs were computed from normalized baseline values through iterative convergence against industry stakeholder growth expectations. Forecast inputs incorporated automotive lightweighting program targets and flexible packaging converter capacity expansion plans.
Stress conditions across ethane price volatility bands, mechanical recycling contamination rate scenarios, and FTC Green Guide enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
BPA Free Plastic Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
United States Non-Ferrous Scrap Recycling Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Modified Polypropylene Market