
 United Kingdom Commercial Vehicles Lubricants Market | 2026-2036
United Kingdom Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Commercial Vehicles Lubricants Market Analytics
Modular service bundling is consolidating buyer choice around combined fluid-change and inspection packages rather than standalone lubricant purchases. BP PLC (Castrol) leverages its nationwide garage network to anchor fleet contracts across England and Scotland. Royal Dutch Shell Plc competes through integrated telematics-linked fluid monitoring systems that reduce unscheduled downtime. ExxonMobil Corporation differentiates via high-performance synthetic formulations engineered for extended drain intervals in stop-start urban delivery cycles.
Commercial vehicles lubricants encompass formulated oils, greases, and functional fluids designed to reduce friction, dissipate heat, and prevent wear in powertrain and auxiliary systems of trucks, buses, and off-highway equipment, with viscosity grades typically spanning SAE 15W-40 to 5W-30 for heavy-duty diesel engines and additive packages containing detergents, dispersants, and anti-wear compounds such as zinc dialkyldithiophosphate. Engine oil commands the largest volume share given mandatory replacement intervals tied to OEM warranty terms, while synthetic transmission fluid represents the fastest-expanding margin pool as automated manual transmissions proliferate in Euro VI-compliant tractor units. Hydraulic oil demand tracks construction and agricultural application cycles, with off-road segments showing greater price elasticity than on-road fleet accounts.
The UK's Vehicle Certification Agency enforces EU-derived CO2 performance standards for heavy-duty vehicles, compelling fleet operators to specify lower-viscosity lubricants that improve fuel economy test results. The Health and Safety Executive mandates waste oil handling protocols that shape collection infrastructure and re-refining economics across Britain. Stakeholders must monitor how the UK's post-EU regulatory divergence affects lubricant specification alignment with continental OEM requirements and whether DEFRA's emerging industrial emissions framework extends carbon accounting to aftermarket consumables.
Market Dynamics
Fleet operators across Britain's logistics corridors are consolidating procurement around bundled fluid-change and inspection packages, compressing standalone lubricant margins while elevating service-contract stickiness among national garage networks.
Growth Catalysts
- Euro VI CO2 standards:The UK's Vehicle Certification Agency enforces EU-derived emissions benchmarks that compel heavy goods vehicle operators to specify lower-viscosity lubricants, directly expanding demand for synthetic formulations engineered for fuel economy testing protocols.
- Automated manual transmission proliferation:Euro VI-compliant tractor units are accelerating adoption of synthetic transmission fluids, creating margin expansion in functional fluids as drain intervals extend and fluid performance specifications tighten.
- Midlands manufacturing density:England's central industrial belt concentrates commercial vehicle service infrastructure with fleet operator headquarters, generating localized demand pull for preventive maintenance programs and bulk lubricant distribution.
Market Restraints
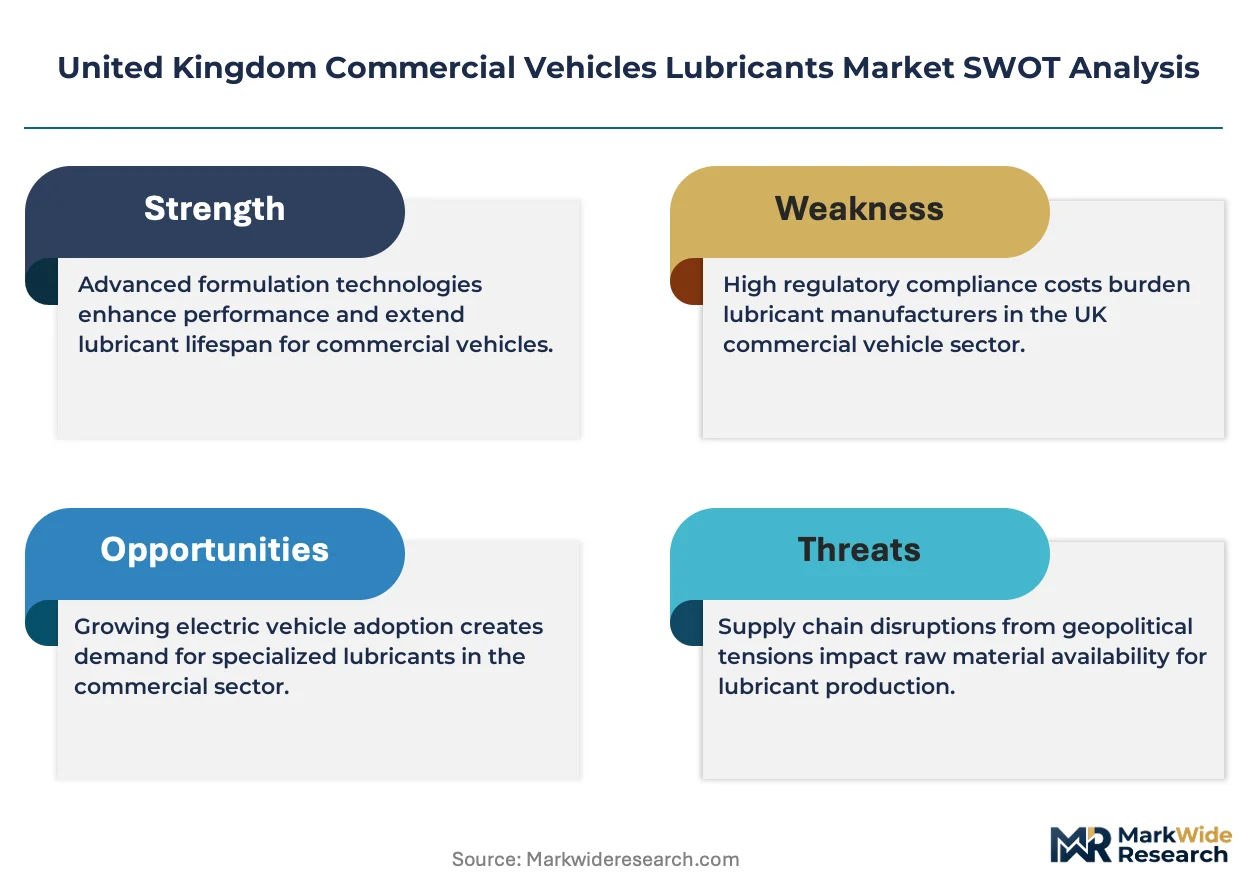
- Base oil price volatility:Group II and Group III base stock costs fluctuate with crude oil benchmarks, squeezing blender margins when feedstock spikes occur without corresponding contract price adjustment clauses in fleet agreements.
- Re-refining infrastructure concentration:Waste oil collection and re-refining capacity clusters in England's industrial corridors, leaving Scotland and Wales with higher logistics costs for compliant used lubricant disposal under Health and Safety Executive protocols.
- Electric powertrain substitution:Battery-electric truck pilots in urban delivery segments threaten long-term engine oil volume as drivetrain architectures eliminate crankcase lubrication requirements entirely from certain duty cycles.
Strategic Opportunities
- Telematics-integrated fluid monitoring:Sensor-enabled oil condition tracking allows predictive drain scheduling, creating subscription revenue streams for lubricant suppliers while reducing unscheduled downtime for fleet operators managing just-in-time delivery contracts.
- Scottish Highlands logistics expansion:Renewable energy construction and remote freight corridors are opening service territory where preventive maintenance penetration remains below English Midlands benchmarks, offering first-mover positioning for garage network expansion.
- DEFRA industrial emissions framework:Emerging carbon accounting protocols for aftermarket consumables may create preferential procurement status for lubricants with verified lifecycle emissions data, rewarding early certification investment.
Industry Challenges
- Synthetic formulation chemistry expertise:Extended drain interval specifications require additive package engineering capabilities that outstrip traditional mineral oil blending skill bases, creating recruitment pressure for tribology specialists and lubricant chemists.
- OEM warranty alignment complexity:Post-EU regulatory divergence risks misalignment between UK fleet specifications and continental European manufacturer requirements, forcing dual inventory strategies or specification negotiation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Commercial Vehicles Lubricants Market |
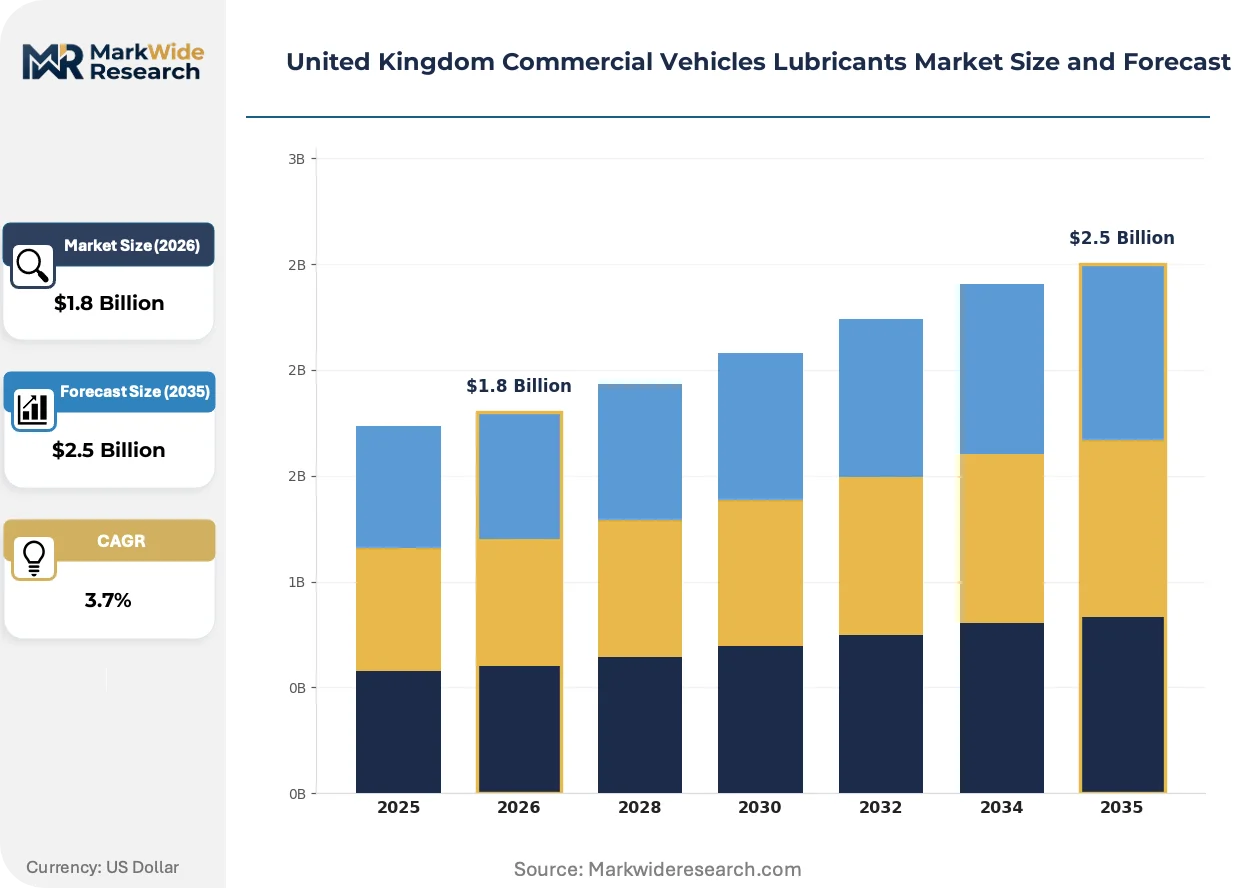
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Grease Application: On-Road, Off-Road, Construction, Agricultural End User: Fleet Operators, Transportation Companies, Logistics Providers, Vehicle Assemblers Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | BP PLC (Castrol), Royal Dutch Shell Plc, ExxonMobil Corporation, FUCHS, TotalEnergies, Chevron Corporation, Exol Lubricants Limited, Morris Lubricants, Q8Oils, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Commercial Vehicles Lubricants Market Evolving Landscape
Synthetic formulation chemistry is converging with digital monitoring infrastructure to reshape how lubricant value is captured, moving product-centric sales toward performance-guaranteed service architectures.
Low-viscosity heavy-duty engine oils are converging with automated manual transmission fluids to create unified powertrain lubrication strategies. Major fleet operators in England's grocery and parcel delivery segments are adopting these formulations simultaneously across tractor units. This convergence is compressing the supplier base toward blenders capable of certifying multi-system fluid compatibility under single contract frameworks.
The Vehicle Certification Agency's enforcement of EU-derived CO2 performance standards for heavy-duty vehicles is tightening lubricant specification requirements. Fleet operators must now document fuel economy contributions from consumables to meet compliance thresholds. Engine oil viscosity selection has become a regulated design parameter rather than a maintenance discretion, with SAE 5W-30 displacing 15W-40 in new vehicle specifications.
Maintenance bundling is displacing standalone lubricant procurement across Britain's national supermarket and express delivery fleets. National garage networks are capturing fluid purchasing decisions within multi-year service contracts that specify supplier exclusivity. This pattern is most visible in England's Midlands corridor where fleet density supports centralized maintenance depots with captive lubricant inventory.
United Kingdom Commercial Vehicles Lubricants Market Segmentation
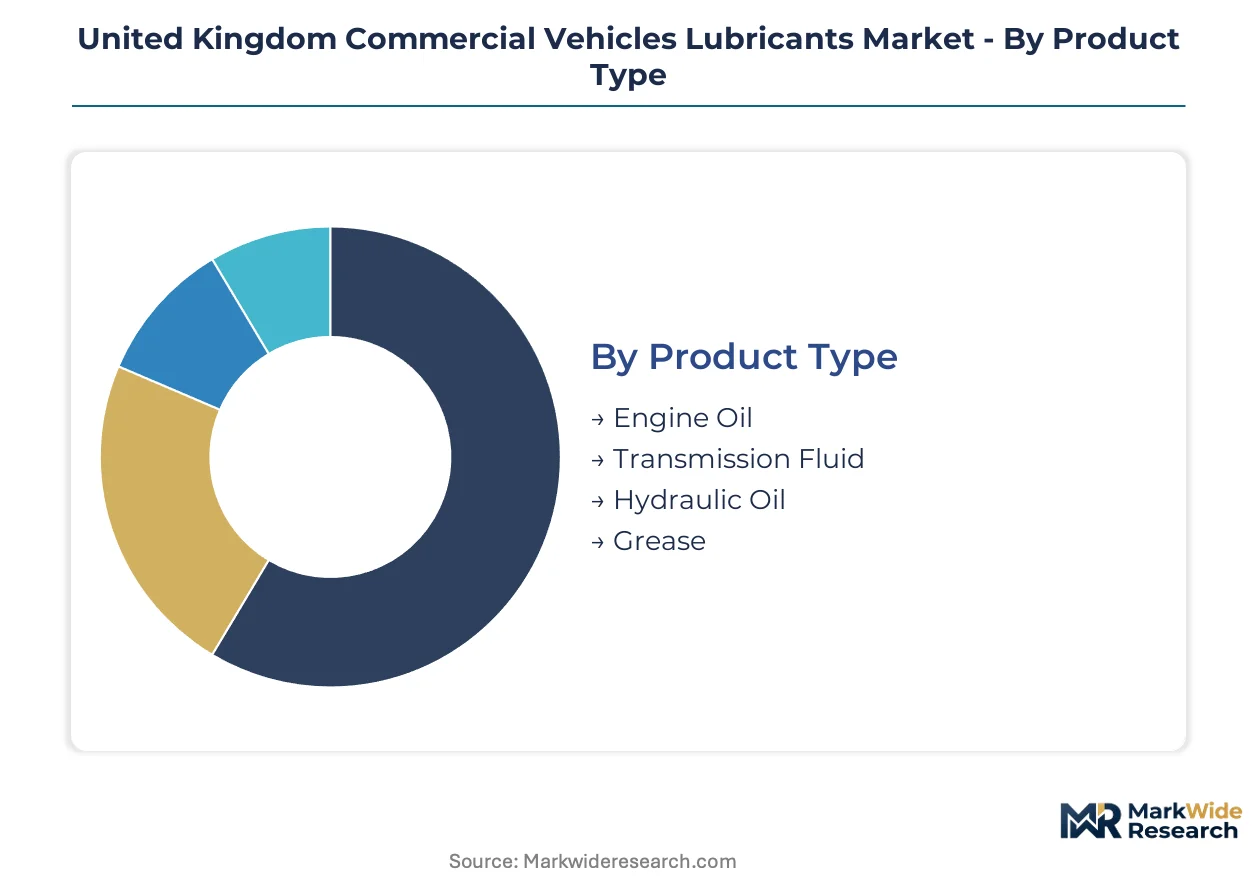
Commercial vehicle lubricant purchasing in Britain fragments across technical specifications, duty cycles, and procurement hierarchies. Fleet operators specify products differently for warranty-compliant tractor units versus off-highway equipment with flexible drain intervals. Understanding these segment boundaries reveals where formulation investment translates to contract capture and where price competition dominates.
Product Type:
Supply concentration among synthetic blenders tilts competitive advantage toward segments demanding advanced additive chemistry and OEM certification overhead.
- Engine Oil:Formulated lubricants for heavy-duty diesel powertrains span SAE 15W-40 through 5W-30 viscosity grades with zinc dialkyldithiophosphate anti-wear packages. England's Midlands fleet corridors concentrate demand where Euro VI CO2 compliance mandates lower-viscosity specifications tied to fuel economy testing protocols.
- Transmission Fluid:Synthetic formulations for automated manual transmissions deliver extended drain intervals and friction stability under stop-start urban cycles. Scotland's grocery delivery networks and England's parcel hubs are standardizing on unified powertrain fluid strategies that bundle engine and transmission specifications under single supplier contracts.
- Hydraulic Oil:Anti-wear and rust-inhibited grades serve construction and agricultural auxiliary systems across Britain's off-road equipment base.
- Grease:Lithium-complex and calcium-sulfonate thickened lubricants protect chassis, wheel bearings, and fifth-wheel couplings in high-load duty cycles.
Today's leader: Engine Oil. Tomorrow's challenger: Transmission Fluid.
Application:
Cost tier differentiation separates premium synthetic formulations for regulated on-road fleets from commodity mineral grades serving seasonal off-road operators.
- On-Road:Highway tractor units and rigid trucks operating under Euro VI emissions frameworks require OEM-approved synthetic engine oils with documented fuel economy contributions. Fleet operators across England's M6 and M1 logistics corridors specify these products to maintain warranty coverage and CO2 compliance thresholds.
- Off-Road:Quarry, mining, and materials handling equipment operates outside emissions testing regimes, permitting longer drain intervals and lower-specification mineral oils. Wales and Scotland's extractive sites show greater price elasticity as maintenance schedules follow utilization hours rather than regulatory mandates.
- Construction:Excavators, loaders, and mobile cranes demand hydraulic oils with anti-wear additives and thermal stability across variable ambient temperatures.
- Agricultural:Tractors and harvesters combine engine, transmission, and hydraulic systems with overlapping fluid requirements in seasonal use patterns.
On-Road commands premium pricing power; Construction offers volume scale for bulk distributors.
End User:
Customer type determines procurement sophistication, with national fleet operators consolidating specifications while independent operators retain fragmented purchasing patterns.
- Fleet Operators:National logistics and express delivery companies with centralized maintenance depots negotiate multi-year lubricant supply contracts tied to service bundling. These buyers specify synthetic formulations across their England-based tractor unit fleets and demand telematics-integrated fluid monitoring to optimize drain scheduling.
- Transportation Companies:Regional bus and coach operators balance municipal contract requirements with aftermarket maintenance economics.
- Logistics Providers:Third-party fulfillment and warehousing specialists lubricate material handling equipment and shunt vehicles in distribution center environments.
- Vehicle Assemblers:UK-based truck and bus manufacturers specify factory-fill lubricants and aftermarket service products for warranty networks.
Fleet Operators dominate contract value; Vehicle Assemblers control specification authority for new equipment.
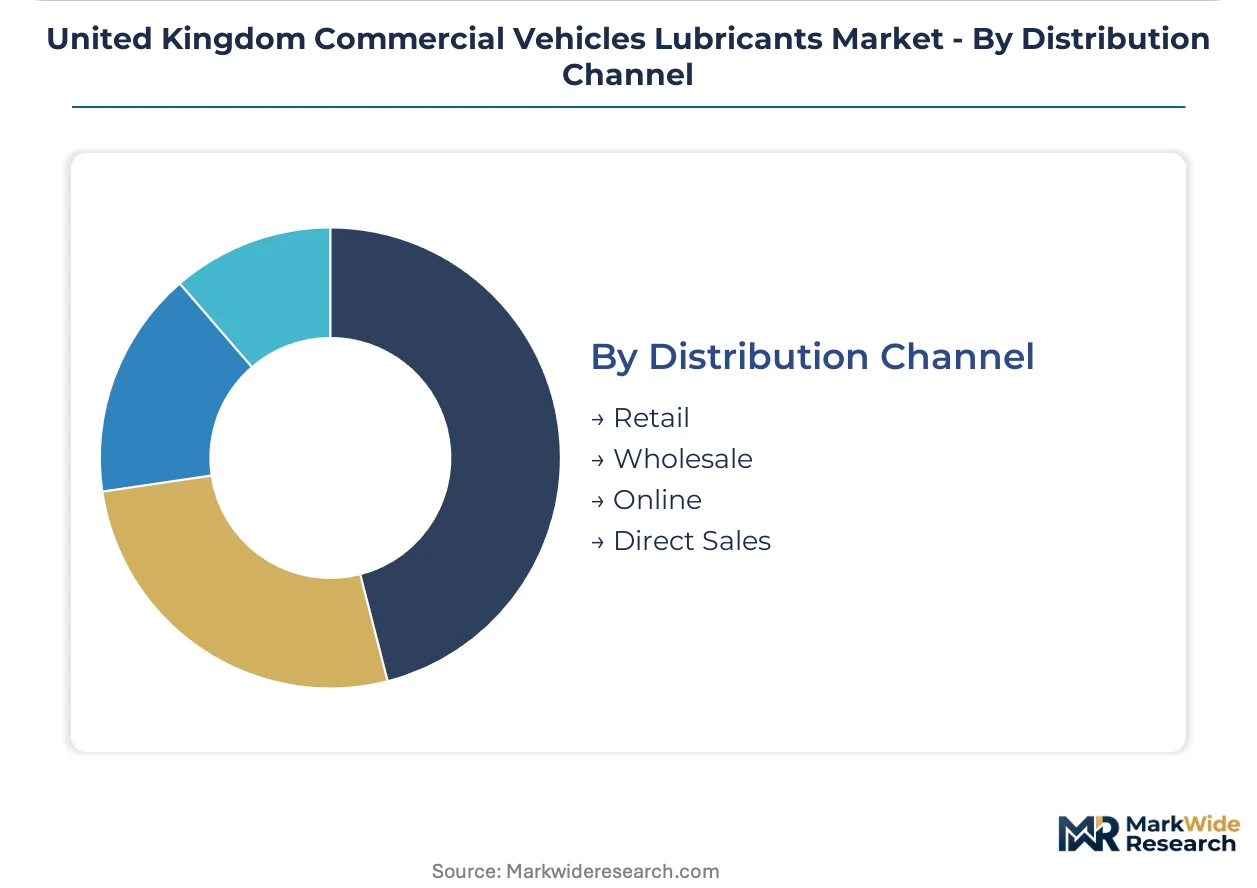
Distribution Channel:
Volume concentration through national garage networks is marginalizing standalone retail and fragmenting direct sales into service-integrated contracts.
- Retail:Independent motor factors and automotive parts chains serve owner-operators and small fleet maintenance. These outlets stock mineral-based engine oils and generic greases for price-sensitive buyers outside England's centralized fleet corridors.
- Wholesale:Regional lubricant distributors supply garage networks and independent workshops with bulk deliveries and inventory management programs. Scotland and Wales depend more heavily on wholesale intermediaries due to geographic dispersion of service points.
- Online:E-commerce platforms capture specification-conscious buyers seeking technical documentation and competitive pricing for synthetic formulations.
- Direct Sales:Blender-to-fleet contracts eliminate intermediaries for national operators with captive maintenance infrastructure and volume commitments.
Wholesale retains geographic coverage advantage; Direct Sales is gaining share fastest among national account consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom's commercial vehicle lubricants industry traces its modern scale to post-war industrial corridor development, when Midlands manufacturing concentration and North Sea oil refining established integrated supply chains that persist today.
England Midlands
England's central industrial belt hosts the densest concentration of fleet operator headquarters and national garage networks. The Vehicle Certification Agency enforces Euro VI CO2 compliance thresholds that mandate lower-viscosity lubricant specifications. Birmingham and Coventry anchor preventive maintenance depots where bundled service contracts capture bulk lubricant procurement decisions.
Scotland
Scotland's grocery delivery networks and renewable energy construction projects are accelerating synthetic transmission fluid adoption. Health and Safety Executive waste oil protocols impose higher logistics costs due to re-refining infrastructure concentration in England. Glasgow and Edinburgh distribution hubs standardize on unified powertrain fluid strategies under single-supplier frameworks.
Wales
Wales's extractive and materials handling sectors operate outside emissions testing regimes, permitting greater price elasticity in mineral oil procurement. The country's national environmental regulator shapes waste lubricant handling requirements that affect collection economics. South Wales quarry clusters maintain flexible drain intervals that contrast with England's regulatory-driven maintenance schedules.
North England
North England's logistics corridors along the M6 and M1 motorways concentrate highway tractor unit operations under strict Euro VI warranty terms. Fleet operators in Manchester and Leeds specify OEM-approved synthetic engine oils with documented fuel economy contributions. Centralized maintenance depots here pioneered telematics-integrated fluid monitoring for predictive drain scheduling.
London and Southeast
London's urban delivery segments drive demand for stop-start cycle formulations as battery-electric truck pilots threaten long-term engine oil volume. The capital's express delivery fleets were first to adopt maintenance bundling within multi-year garage network contracts. Dartford and Thurrock distribution centers anchor captive lubricant inventory systems for just-in-time logistics operations.
United Kingdom Commercial Vehicles Lubricants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation certification and service integration capabilities. The vendor base organizes into three tiers: multinational blenders with OEM approval networks, national distributors with garage chain partnerships, and regional specialists serving price-sensitive independent operators. Dominant competitive moves include telematics-enabled service bundling and synthetic formulation chemistry investments that extend drain intervals.
Within the multinational blender tier, BP PLC (Castrol), Royal Dutch Shell Plc, and ExxonMobil Corporation exemplify archetypes of national garage network anchoring, integrated fluid monitoring systems, and high-performance synthetic engineering respectively. These London- and US-based entities occupy positions where specification authority for new equipment intersects with aftermarket service contract capture. Their collective presence shapes how fleet procurement consolidates around combined fluid-change and inspection packages rather than standalone product sales.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| FUCHS |
| TotalEnergies |
| Chevron Corporation |
| Exol Lubricants Limited |
| Morris Lubricants |
| Q8Oils |
| Others |
Value Network & Pricing Analysis
Fleet consolidation around bundled service contracts is forcing blenders to absorb fluid-change labor costs into lubricant pricing, compressing standalone product margins while elevating multi-year contract values. The Vehicle Certification Agency's Euro VI CO2 enforcement has transformed viscosity specification from maintenance discretion into regulated compliance cost, embedding fuel-economy testing premiums into synthetic formulation pricing.
Pricing Analysis
Three-tier pricing structure across premium synthetic, approved mineral, and unbranded economy levels organizes the market around certification authority and drain-interval performance. Price differentiation hinges on OEM approval status and volume commitment scale, with national fleet contracts commanding 15-25 point discounts against spot wholesale. Cost compression in mineral grades is intensifying because independent motor factors compete on shelf-price visibility for owner-operators. Small fleet maintenance shops in Wales and Scotland show greatest price sensitivity; England's Midlands national accounts least.
Supply Chain Analysis
Single-source vulnerability sits with Group II and Group III base oil imports from the Netherlands, Belgium, and South Korea, where refinery capacity concentrates. Formulation chemistry draws from polyalphaolefin synthetic stocks, zinc dialkyldithiophosphate additive packages, and viscosity modifier polymers. Tariff exposure from post-EU regulatory divergence threatens specification alignment costs. Distribution runs through England's Midlands bulk terminals to captive fleet depots and national garage networks, with Scotland and Wales served by wholesale intermediaries facing higher logistics overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom commercial vehicle lubricants market represents a late-cycle quality story as Euro VI CO2 compliance forces fleet operators toward synthetic formulations with documented fuel economy contributions. Premium specification demand is displacing commodity mineral procurement across England's centralized maintenance corridors.
For Market Incumbents: Acquire tribology engineering capabilities and additive package formulation assets to defend against synthetic chemistry expertise gaps. Backward integration into base oil refining secures margin control when feedstock volatility spikes. Cement exclusive garage network partnerships before telematics-integrated service bundling locks in competitor contracts.
For New Entrants and Emerging Players: Capture Scotland's Highland renewable energy construction corridors where preventive maintenance penetration trails English benchmarks and national garage networks lack density. Target Wales's extractive sector with flexible mineral oil supply contracts unburdened by Euro VI warranty compliance overhead. Lead with wholesale distribution partnerships rather than direct fleet sales to overcome incumbent specification authority.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap blenders possessing OEM approval networks but underutilized capacity in automated manual transmission fluids. Five-to-ten year viability rests on electric powertrain substitution pace and synthetic formulation chemistry moats. Monitor battery-electric truck pilot scale-up in London urban delivery as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Formulation Chemistry Investment | Extended drain interval specifications require additive engineering capabilities beyond mineral blending skill bases. |
| Telematics-Integrated Fluid Monitoring Deployment | Sensor-enabled oil condition tracking creates subscription revenue streams while reducing fleet unscheduled downtime. |
| Scottish Highlands Garage Network Expansion | Renewable energy construction and remote freight corridors offer first-mover positioning below English penetration benchmarks. |
| DEFRA Carbon Certification Early Investment | Lifecycle emissions verification creates preferential procurement status under emerging aftermarket consumables accounting. |
| Base Oil Refining Backward Integration | Captive Group II and Group III supply insulates blender margins from crude-linked feedstock volatility. |
Research Methodology
Bottom-up fleet operator procurement modeling reconciled against top-down blender capacity tracking forms the analytical core of this study. Primary interviews with fleet maintenance directors, national garage network procurement managers, lubricant distributor operations heads, and OEM warranty compliance officers combined with secondary validation against Vehicle Certification Agency filings, Health and Safety Executive waste oil protocol records, and SEC disclosures from multinational blender parents. Trade data from HM Revenue and Customs and industry association production surveys provided triangulation anchors.
Historical trendline analysis of lubricant volume by viscosity grade and formulation type established baseline growth patterns across the analysis window. Segmentation modeling captured product type, application duty cycle, end-user procurement sophistication, and distribution channel structure. CAGRs derived from regression-weighted projection of fleet operator synthetic adoption curves and Euro VI compliance phase-in schedules. Forecast inputs incorporated automated manual transmission penetration rates and electric powertrain substitution scenarios for urban delivery segments.
Base oil price volatility, regulatory divergence from continental OEM specifications, and electric vehicle adoption acceleration are the dominant revision risks to projection assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Automotive Engine Oils Market
Lubricants
India Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Biolubricants Market
Lubricants
Japan Lubricants Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Lubrication Equipment Market
Lubricants
Hydro Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Indonesia Lubricants Market
Lubricants
Canada Automotive Lubricants Market