
 Poland Industrial Lubricants Market | 2026-2036
Poland Industrial Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Industrial Lubricants Market Outlook
REACH compliance is shifting the cost-of-entry calculus for smaller blenders importing base stocks into Poland. PKN ORLEN leverages its Gdańsk refinery complex to sustain captive supply advantages across the Baltic corridor. FUCHS differentiates through specialized metalworking fluid portfolios tailored to Polish machinery exporters. ExxonMobil anchors premium positioning among power generation operators modernizing turbine fleets.
Industrial lubricants comprise formulated fluids and semi-solid greases engineered from Group I–III mineral bases, polyalphaolefin synthetics, or ester-derived biolubricants, with viscosity grades typically spanning ISO VG 32 to 680 and additive packages incorporating anti-wear zinc dialkyldithiophosphate, detergents, and friction modifiers to reduce mechanical wear, dissipate heat, and extend equipment life in continuous-duty operations. The oils category dominates volume flows into Polish machinery and metalworking applications, where multi-year service intervals and extreme-pressure performance command margin premiums, while greases face faster growth in automated lubrication systems deployed across mining and energy infrastructure. Additives represent a concentrated profit pool as reformulation cycles accelerate under EU regulatory pressure.
Poland's industrial lubricant sector operates under the overlapping jurisdictions of the EU's ECHA REACH framework, the F-Gas Regulation restricting fluorinated lubricant chemistries, and national BIS-aligned product safety standards administered through the Polish Committee for Standardization. These frameworks compel domestic blenders to migrate toward lower-sulfur, higher-biodegradability formulations while tightening documentation burdens on importers. Stakeholders must monitor how the EU AI Act's predictive maintenance mandates reshape lubricant sensor integration requirements and service-model economics.
Market Dynamics
Poland's industrial lubricant sector is compressing around EU Green Deal decarbonization mandates, forcing blenders to reformulate mineral-based stocks into synthetic and bio-based alternatives while navigating REACH documentation burdens and F-Gas phase-down schedules.
Growth Catalysts
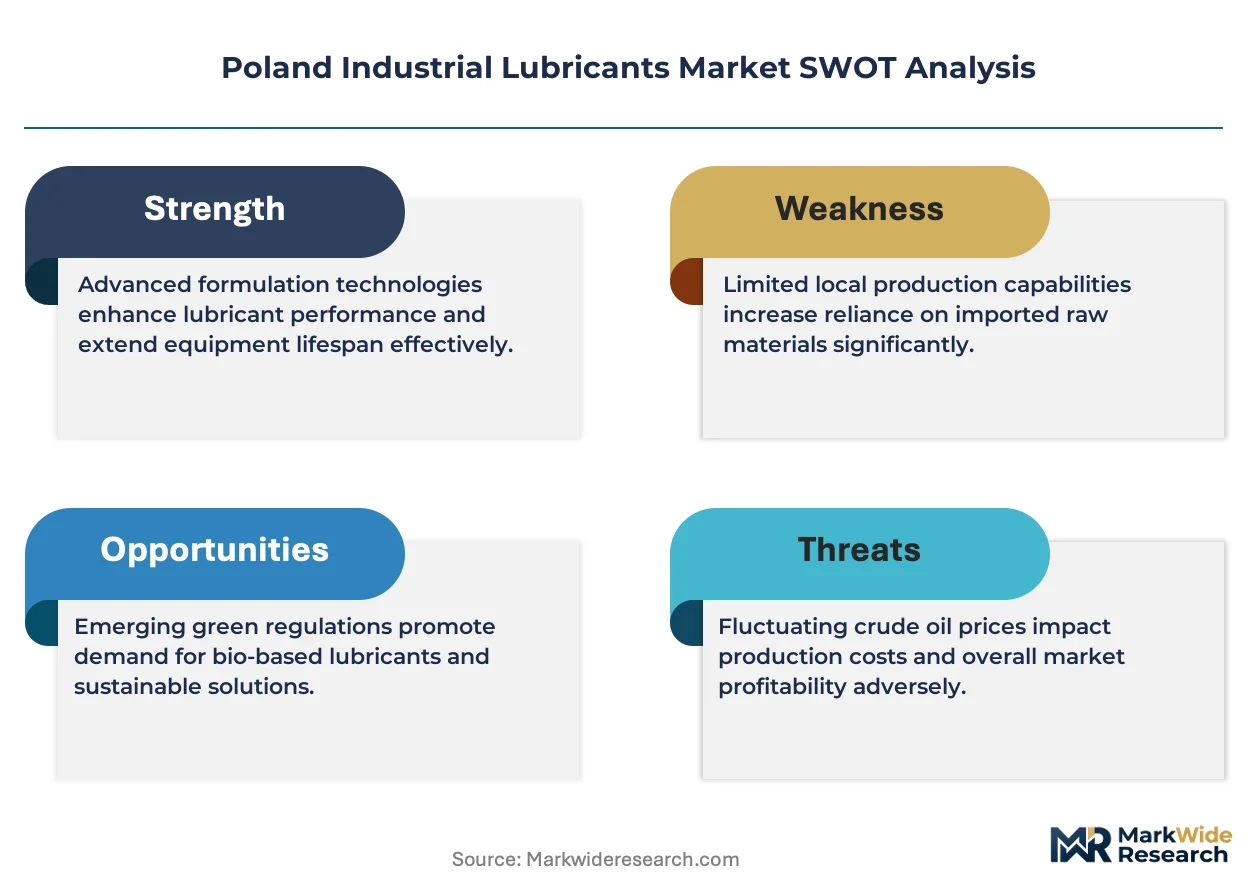
- EU Green Deal alignment:Poland's national climate targets accelerate demand for biodegradable hydraulic fluids in metalworking clusters across Silesia and Greater Poland.
- Automotive OEM supply chain density:Machinery exporters concentrated around Bielsko-Biała and Tychy require extreme-pressure metalworking fluids with extended service intervals.
- F-Gas Regulation phase-down:Restrictions on fluorinated lubricant chemistries are pulling reformulation investment toward polyalphaolefin synthetic bases.
Market Restraints
- Base stock import concentration:Smaller blenders face elevated cost-of-entry from REACH compliance burdens on Group II-III mineral oil imports.
- Captive refinery dominance:PKN ORLEN's Gdańsk complex controls Baltic corridor supply, limiting third-party sourcing flexibility for independent formulators.
- Reformulation capex intensity:Migration to ester-derived biolubricants demands new blending infrastructure and additive package redevelopment.
Strategic Opportunities
- Automated lubrication systems:Mining and energy infrastructure operators in Lower Silesia are retrofitting centralized grease delivery systems.
- EU AI Act predictive maintenance:Sensor-integrated lubricant monitoring creates service-model economics for turbine fleet operators.
- Greater Poland manufacturing expansion:Underpenetrated food-grade lubricant demand from packaging machinery producers offers white-space growth.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise in zinc dialkyldithiophosphate alternatives and friction modifier synthesis remains concentrated among legacy technical staff.
- REACH documentation timelines:Extended safety data sheet preparation and substance registration cycles delay product launches for importers.
- Legacy equipment compatibility:Synthetic fluid retrofits into decades-old Polish machinery require seal material upgrades and filtration system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Industrial Lubricants Market |
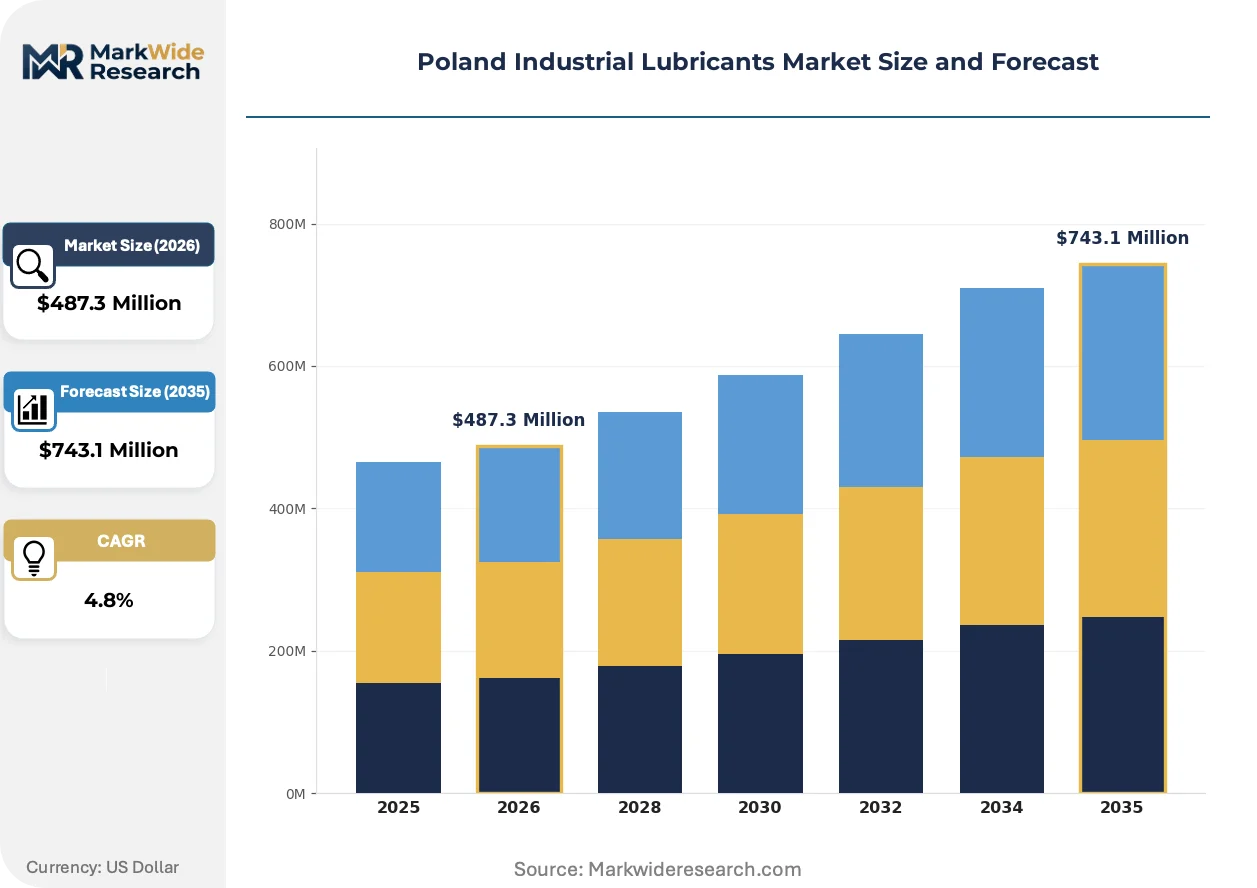
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greases, Oils, Additives, Cleaners Application: Machinery, Automotive, Metalworking, Power Generation End User: Manufacturing, Automotive OEMs, Mining, Energy Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Shell plc, ExxonMobil Corporation, PKN ORLEN, Modex Oil, BP Plc (Castrol), LOTOS OIL, TotalEnergies, Eurol, FUCHS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Industrial Lubricants Market Strategic Shifts
Reformulation chemistry, predictive maintenance integration, and procurement restructuring are converging to reshape how lubricant value migrates from product sales to performance guarantees and sensor-enabled service contracts.
Polyalphaolefin synthetic base stocks are absorbing volume share from Group I mineral oils in high-temperature hydraulic applications. Metalworking plants serving automotive tier-one suppliers adopt these formulations aggressively to meet multi-year service interval specifications. The technology is absorbing margin compression from mineral oil commodity cycles while commanding premium positioning in continuous-duty operations.
ECHA REACH framework amendments tighten documentation burdens on imported additive packages and base stock formulations. Polish blenders must now submit expanded chemical safety assessments for anti-wear compounds and detergent systems. Metalworking fluid portfolios face the steepest compliance cost escalation as reformulation cycles accelerate.
Power generation operators unbundle lubricant supply from turbine maintenance contracts, shifting toward specification-driven procurement with independent fluid analysis requirements. This disintermediation pressures traditional integrated service providers and elevates third-party laboratory testing demand. The pattern concentrates most visibly in modernizing coal and gas turbine fleets across southern Poland.
Poland Industrial Lubricants Market Segmentation
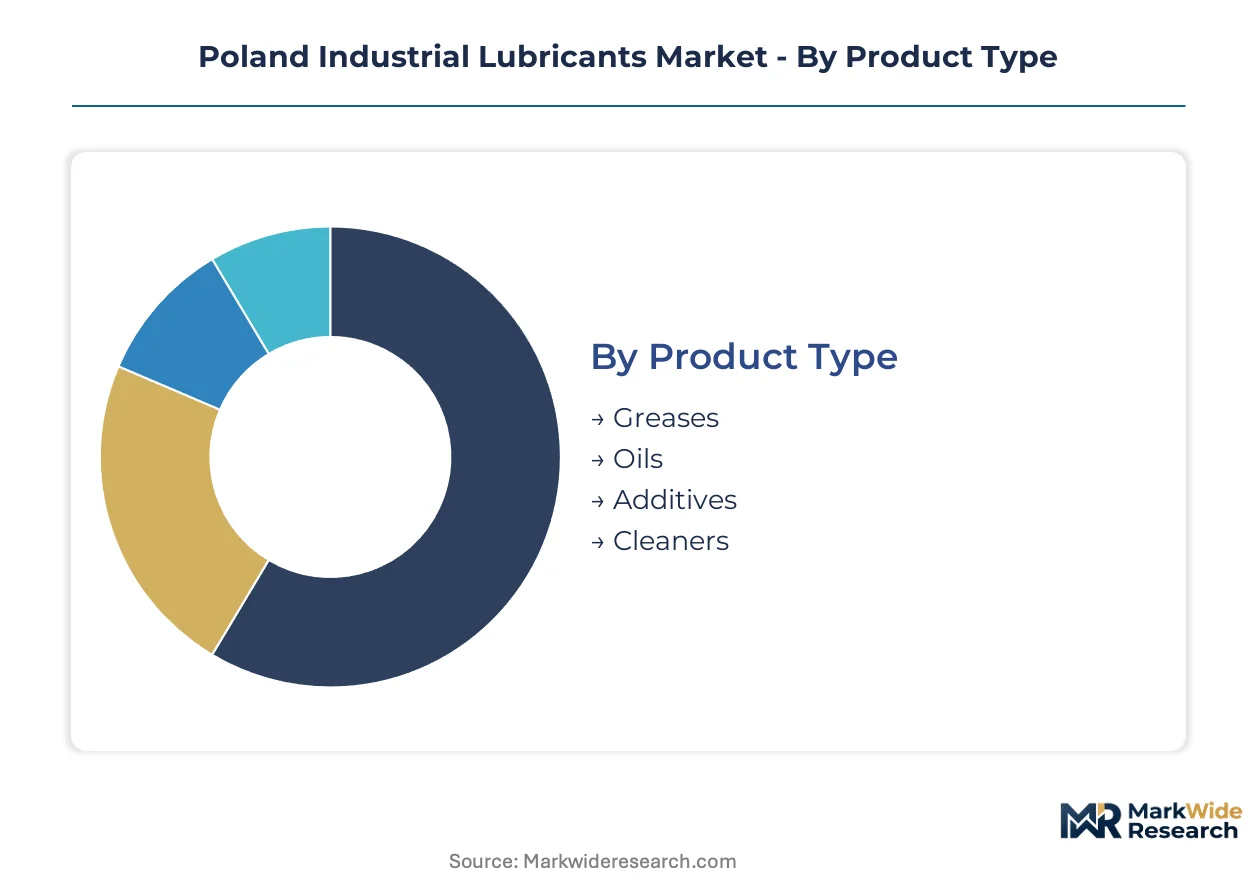
Segmentation in Poland's industrial lubricants market reveals how reformulation pressures and supply chain concentration reshape procurement priorities across buyer categories. Understanding these divisions exposes where margin pools concentrate and where regulatory compliance creates defensive moats.
Product Type:
Buyers prioritize performance specifications over base chemistry when selecting lubricant formulations, with service interval guarantees and biodegradability credentials driving contract terms.
- Oils:Formulated fluids spanning ISO VG 32 to 680 grades, incorporating zinc dialkyldithiophosphate anti-wear packages and friction modifiers for continuous-duty machinery. Demand concentrates heaviest in Silesian metalworking plants serving automotive tier-one suppliers, where multi-year service intervals command premium positioning against mineral oil commodity cycles.
- Additives:Concentrated chemical packages including detergents, dispersants, and viscosity index improvers that define finished lubricant performance. Polish blenders face ECHA REACH documentation burdens on imported additive systems, creating cost-of-entry barriers that favor captive formulators with in-house chemist teams.
- Greases:Semi-solid lubricants with thickener systems for sealed-for-life applications. Mining operators in Lower Silesia deploy these in automated lubrication retrofits.
- Cleaners:Degreasing and flushing formulations for equipment maintenance cycles. Food-grade variants from Greater Poland packaging machinery producers show underpenetrated white-space potential.
Oils lead on scale; additives lead on margin compression resistance.
Application:
Equipment duty cycles and operating temperature regimes determine lubricant selection more than industry vertical alone.
- Metalworking:Extreme-pressure fluids for cutting, grinding, and forming operations requiring thermal stability and chip flushing. Plants clustered around Bielsko-Biała and Tychy absorb synthetic formulations aggressively to meet automotive OEM supply chain specifications.
- Machinery:General industrial lubrication for gearboxes, bearings, and hydraulics across factory automation. Greater Poland manufacturing expansion pulls biodegradable hydraulic fluid demand under EU Green Deal alignment.
- Power Generation:Turbine oils and compressor lubricants for continuous-duty thermal plants. Southern Polish coal and gas fleet modernization drives specification-driven procurement with independent fluid analysis requirements.
- Automotive:Assembly line lubrication and component finishing fluids. Dense OEM supply chain concentration creates volume pull with tight formulation tolerances.
Metalworking captures the deepest value per liter; machinery offers the broadest addressable base.
End User:
Procurement sophistication varies sharply by sector, with energy and automotive OEMs running centralized technical specifications while mining and general manufacturing delegate to maintenance departments.
- Automotive OEMs:Tier-one suppliers and final assembly operations with specification-locked supply agreements. Bielsko-Biała and Tychy clusters demand extreme-pressure metalworking fluids with documented REACH compliance and batch traceability.
- Energy:Power generation operators unbundling lubricant supply from turbine maintenance contracts. Sensor-integrated monitoring under EU AI Act predictive maintenance mandates creates service-model economics for fluid analysis providers.
- Manufacturing:General industrial users across packaging, textiles, and consumer goods. Greater Poland food-grade lubricant demand from packaging machinery producers shows expansion potential.
- Mining:Extraction and processing operations in Lower Silesia retrofitting centralized grease delivery systems for automated lubrication.
Automotive OEMs lead on specification intensity; energy leads on contract restructuring velocity.
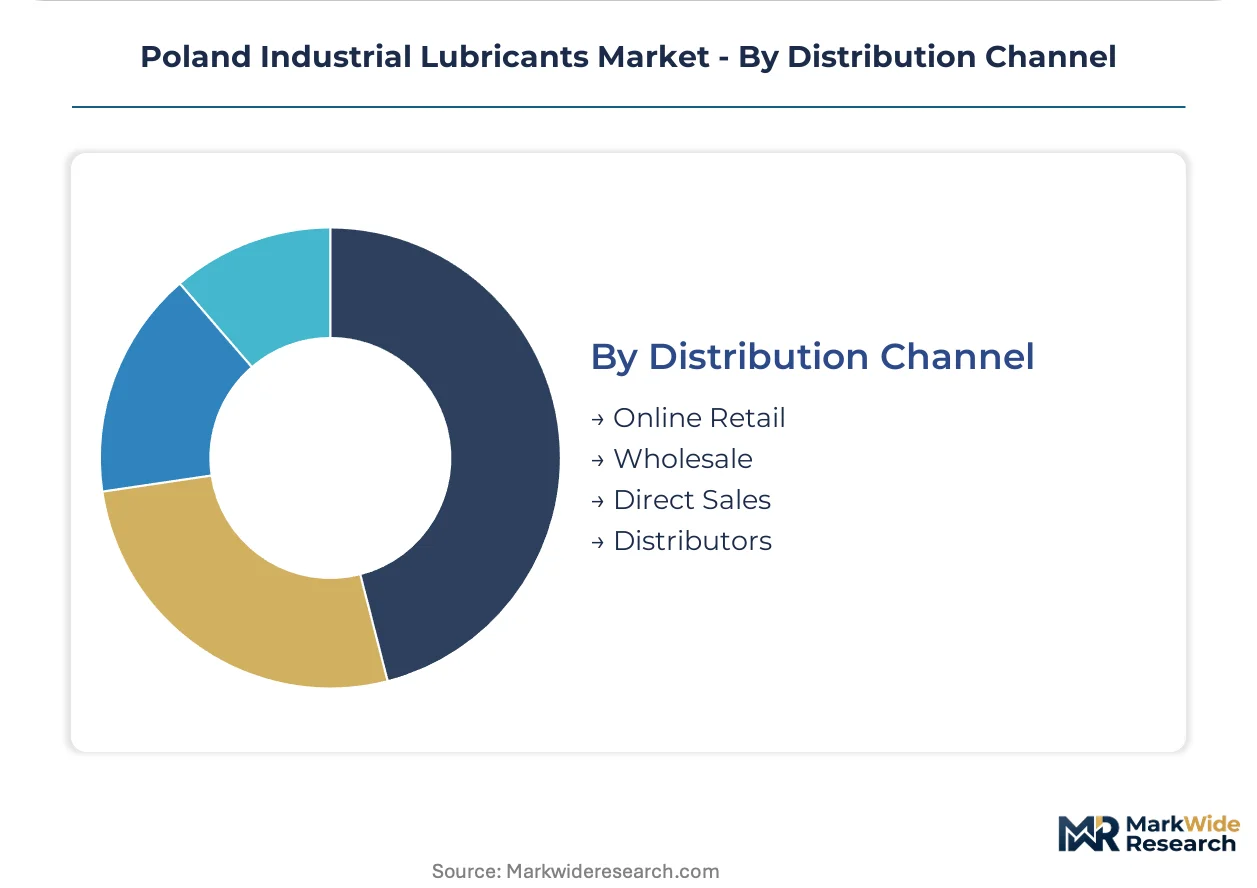
Distribution Channel:
Channel selection reflects order size predictability and technical service requirements, with large volume accounts disintermediating traditional distributors.
- Direct Sales:Manufacturer-to-end-user relationships for high-volume accounts with technical service demands. PKN ORLEN leverages Gdańsk refinery captive supply to anchor direct contracts across the Baltic corridor.
- Distributors:Independent stocking intermediaries serving fragmented manufacturing base. Smaller blenders rely on this channel to bypass PKN ORLEN supply dominance.
- Wholesale:Bulk volume transactions for large industrial accounts with predictable consumption patterns. REACH documentation burdens concentrate here for imported base stock formulations.
- Online Retail:Digital procurement platforms for maintenance-repair-operations supplies. Limited penetration in industrial lubricants due to technical specification complexity.
Direct sales leads on margin retention; distributors lead on geographic coverage breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's industrial lubricant sector traces its modern scale to post-1989 manufacturing expansion and EU accession integration, with Silesian coal mining and automotive assembly anchoring early demand clusters that now drive reformulation toward synthetic and bio-based alternatives.
Silesia
Coal extraction and metallurgical processing sustain heavy consumption of extreme-pressure greases and hydraulic fluids. ECHA REACH documentation burdens concentrate here as legacy mining equipment retrofits require seal-compatible synthetic formulations. Katowice-Gliwice-Zabrze triangle hosts the densest automated lubrication system deployments in Polish mining.
Greater Poland
Food packaging machinery and agricultural equipment manufacturing pull biodegradable hydraulic fluid demand under EU Green Deal alignment. F-Gas Regulation phase-down schedules accelerate polyalphaolefin adoption in cold-storage compressor applications. Poznań-Konin corridor clusters dominate white-space growth for food-grade lubricant formulations.
Lesser Poland
Steel production and heavy machinery fabrication at Nowa Huta legacy complexes sustain mineral oil volume despite synthetic migration pressure. Poland's national climate targets force blast furnace operators toward lower-sulfur hydraulic stocks. Kraków-Tarnów industrial belt exhibits slowest reformulation velocity due to capital equipment age.
Pomerania
PKN ORLEN's Gdańsk refinery complex anchors captive supply advantages across the Baltic corridor. Wind turbine manufacturing at Łeba and Ustka pulls synthetic gear oil demand for offshore drivetrain applications. Gdynia port logistics sustain bulk lubricant storage and distribution infrastructure serving Nordic markets.
Subcarpathia
Aircraft component manufacturing at Rzeszów-Łańcut aviation cluster demands aerospace-certified synthetic lubricants with batch traceability. EU AI Act predictive maintenance mandates reshape procurement specifications for precision machining centers. The region shows fastest growth in sensor-integrated fluid monitoring service contracts.
Poland Industrial Lubricants Market Competitive Environment
The competitive structure tilts toward refinery-integrated national champions and specialized metalworking formulators. PKN ORLEN's Gdańsk captive supply dominance compresses margins for independent blenders importing Group II-III base stocks. Two archetypes define positioning: vertically integrated petrochemical majors leveraging Baltic corridor logistics, and application-specific specialists commanding premium tiers through formulation expertise. Competitive moves concentrate on REACH compliance infrastructure investment and direct sales channel expansion toward automotive OEM supply chains.
Among refinery-integrated operators, PKN ORLEN anchors the national champion archetype through Gdańsk complex supply control. Shell plc and ExxonMobil Corporation occupy positions as multinational majors with premium turbine oil and power generation portfolios. FUCHS exemplifies the specialist tier through metalworking fluid concentration. These three represent distinct competitive vectors: captive supply security, global specification authority, and application-specific formulation depth.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| PKN ORLEN |
| Modex Oil |
| BP Plc (Castrol) |
| LOTOS OIL |
| TotalEnergies |
| Eurol |
| FUCHS |
| Others |
Value Chain & Pricing Dynamics
Refinery-integrated national champions anchored by PKN ORLEN's Gdańsk complex exercise asymmetric pricing power over independent blenders importing Group II-III base stocks. This ownership pattern compresses margins for smaller formulators while sustaining premium capture for synthetic and bio-based formulations serving EU Green Deal compliance mandates.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume procurement among automotive OEMs and power generation operators, with pricing stratifying across premium synthetic, standard mineral, and economy re-refined tiers. Price differentiation hinges on REACH certification grade and volume scale commitments. Cost compression in standard mineral tiers intensifies because PKN ORLEN's captive supply floods the Baltic corridor. Mining operators in Lower Silesia show highest price sensitivity due to commodity-driven cost pressures, while aerospace-certified synthetic buyers in Subcarpathia absorb premiums with minimal negotiation leverage.
Supply Chain Analysis
Group II-III mineral base stock supply rests on integrated refinery output from Poland, Germany, and the Netherlands, with polyalphaolefin synthetics drawing from Belgian and German specialty chemical producers. Critical dependencies include zinc dialkyldithiophosphate anti-wear additives from German suppliers, ester biolubricant feedstocks from French and Italian oleochemical plants, and viscosity index improvers from Benelux polymer specialists. Single-source vulnerability concentrates in REACH-compliant additive packages where ECHA documentation burdens delay qualification of alternative suppliers. Distribution runs through PKN ORLEN's direct sales channel for high-volume accounts, with independent distributors serving fragmented manufacturing across Greater Poland and Lesser Poland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's industrial lubricant sector functions as a geographic-arbitrage play where EU regulatory stringency exceeds neighboring Eastern European markets, creating cost-advantaged export positioning for compliant domestic blenders.
For Market Incumbents: Cement captive supply security through backward integration into Gdańsk corridor logistics infrastructure. Lock in multi-year direct sales contracts with Bielsko-Biała automotive tier-one suppliers before F-Gas Regulation phase-down accelerates synthetic formulation switching costs. Prioritize additive chemist retention programs to defend against talent scarcity threatening reformulation timelines.
For New Entrants and Emerging Players: Begin with food-grade lubricant white-space in Greater Poland packaging machinery clusters where incumbent penetration remains thin. Target automated lubrication system retrofits in Lower Silesia mining operations through grease formulation specialization. Pursue sensor-integrated fluid monitoring service contracts as EU AI Act predictive maintenance mandates reshape procurement specifications.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent blenders with stranded mineral oil capacity facing REACH compliance cost escalation. Long-term viability centers on synthetic and bio-based formulation capabilities aligned with EU Green Deal decarbonization trajectories. Watch for ECHA REACH framework amendments tightening additive documentation burdens as inflection indicator for consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Supply | PKN ORLEN's Gdańsk refinery complex anchors captive cost advantages across Baltic corridor distribution. |
| Green Manufacturing Transition | Ester-derived biolubricant capacity expansion aligns with EU Green Deal biodegradable hydraulic fluid mandates. |
| Long-term Supply Agreement | Automotive OEM specification-locked contracts around Bielsko-Biała secure multi-year synthetic formulation volume. |
| Joint Venture | Sensor-integrated lubricant monitoring partnerships capture EU AI Act predictive maintenance service economics. |
| Capacity Expansion | Greater Poland food-grade lubricant production addresses underpenetrated packaging machinery demand clusters. |
Study Parameters
Direct dialogue with lubricant plant managers, automotive OEM procurement leads, mining maintenance directors, and additive package technical directors grounded the qualitative foundation. Secondary validation drew from ECHA REACH substance registration databases, Polish Central Statistical Office industrial production indices, customs trade flow records, and EU F-Gas Regulation implementation reports. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity models.
Segment-level projections across product type, application, end user, and distribution channel dimensions were generated through the analytical framework. CAGRs were derived from elasticity-adjusted consumption models incorporating base stock price trajectories and regulatory compliance cost curves. Forecast inputs included automotive production forecasts for Bielsko-Biała and Tychy clusters, coal fleet retirement schedules affecting turbine oil demand, and EU AI Act implementation timelines for predictive maintenance mandates.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Baltic corridor logistics, abrupt ECHA REACH framework amendments, and technological substitution by solid-state lubrication systems. Forecasts assume continued EU Green Deal policy continuity and stable base stock import flows from German and Benelux suppliers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Hydropower Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Canada Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Global Grease Market