
 Bio-Based Lubricants Market | 2026-2036
Bio-Based Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Lubricants Market Intelligence
The shift towards performance-based service contracts for industrial equipment is rewriting market access rules for lubricant suppliers. This model favors suppliers with deep application expertise. Fuchs Petrolub SE leverages its specialization in industrial lubricants to secure these contracts. Klüber Lubrication also differentiates through its high-performance, tailored solutions, while integrated majors like Shell plc compete by bundling lubricants with broader energy and service packages.
Bio-based lubricants are fluids derived from renewable feedstocks like vegetable oils, replacing petroleum-based products. Their primary function is to reduce friction in machinery, with key parameters being high biodegradability and low ecotoxicity. Vegetable oils form the core of the product type segment, but synthetic esters command higher value in demanding industrial machinery applications. The automotive application segment requires complex formulations to meet OEM performance standards, representing a high-barrier, high-reward area.
Regulations like the US EPA's Vessel General Permit and the EU Ecolabel create mandatory markets for environmentally acceptable lubricants in marine and other sensitive applications. Concurrently, ISO 14001 standards encourage industrial facilities in countries like Japan and Germany to adopt greener operational inputs. The central challenge for producers remains balancing feedstock cost, performance characteristics, and certified sustainability claims to capture value.
Market Dynamics
The central tension in the bio-based lubricants market is the conflict between regulatory pressure for biodegradability, exemplified by the EU Ecolabel, and the high-performance requirements of industrial machinery, creating a constant trade-off for formulators.
Growth Catalysts
- Regulatory Mandates:The US EPA's Vessel General Permit creates a mandatory market for environmentally acceptable lubricants in marine applications.
- Corporate Sustainability Goals:Industrial facilities in Germany and Japan pursuing ISO 14001 certification specify bio-lubricants to reduce their environmental footprint.
- Automotive OEM Requirements:Car manufacturers are demanding greener supply chains, creating a high-value segment for bio-lubricants that meet stringent performance standards.
Market Restraints
- Feedstock Price Volatility:Vegetable oils face direct price competition from the food industry, creating cost instability for lubricant producers.
- Technical Performance Gaps:Many bio-based products exhibit lower thermal stability than petroleum synthetics, limiting use in high-temperature industrial applications.
- Concentrated Agricultural Supply:The supply of key feedstocks like rapeseed oil is concentrated in specific agricultural regions, creating supply chain risks.
Strategic Opportunities
- Advanced Feedstock Development:Research into non-food biomass like algae promises a new generation of high-performance esters with a more stable cost base.
- High-Value Niche Applications:Untapped demand exists in specialized segments like food-grade lubricants and dielectric fluids for electric vehicles.
- Expansion into New Regulatory Zones:Targeting industrial economies in Southeast Asia as they begin to implement environmental regulations modeled on EU standards.
Industry Challenges
- Certification Burdens:Obtaining credentials like the EU Ecolabel is a costly and lengthy process, requiring extensive testing that can be a barrier for smaller producers.
- Formulation Talent Scarcity:A shortage of chemical engineers with dual expertise in advanced lubricant formulation and the unique chemistry of bio-based feedstocks hinders product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Lubricants Market |
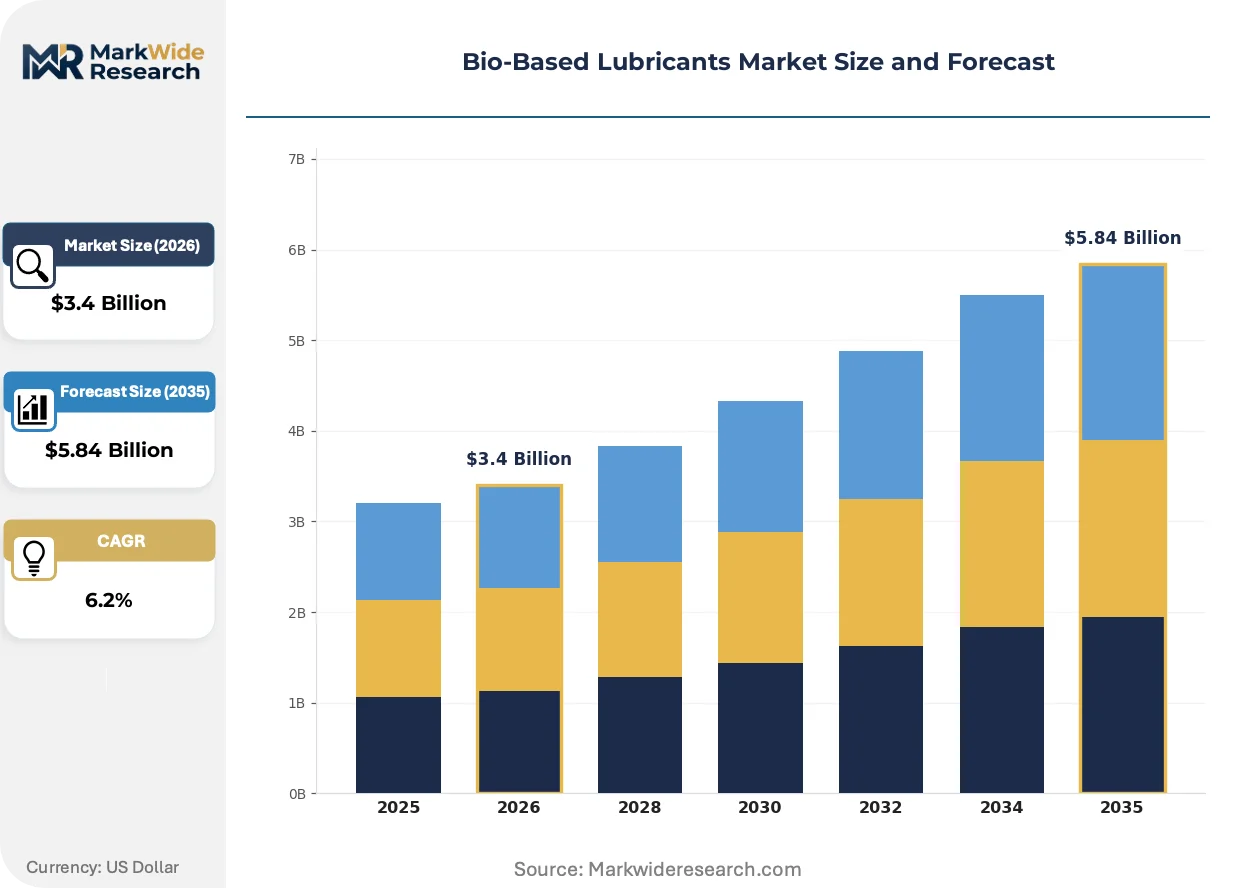
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oils, Animal Fats, Synthetic Esters, Bio-Based Polyalkylene Glycols Application: Automotive, Industrial Machinery, Marine, Biofuels End User: Automakers, Manufacturing Sector, Aerospace, Renewable Energy Formulation: Chemical Additives, Pure Lubricants, Blends, Biodegradable Solutions |
| Companies Covered | Shell plc, ExxonMobil Corporation, TotalEnergies SE, BP p.l.c., Fuchs Petrolub SE, Emery Oleochemicals, Chevron Corporation, Klüber Lubrication, Panolin AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Lubricants Market Strategic Shifts & Innovations
Material science advancements and new service models are fundamentally altering how bio-based lubricants are specified, sold, and monitored. This evolution is moving the industry beyond simple product substitution toward integrated performance solutions.
Genetically modified high-oleic oils from sources like soybeans provide superior thermal stability and oxidative resistance. Industrial and automotive formulators are rapidly adopting these advanced feedstocks for more demanding applications. The traditional performance gap between bio-based and conventional petroleum lubricants is collapsing, enabling market entry into previously inaccessible high-temperature processes.
The European Union’s Corporate Sustainability Reporting Directive (CSRD) is a significant policy driver. It compels large enterprises to disclose detailed information on their supply chain's environmental impact, including lubricant use. Consequently, industrial equipment operators in countries like Germany and France are increasingly specifying certified bio-lubricants to improve their reported metrics.
Performance-based service contracts are gaining traction over traditional transactional lubricant sales. This model disrupts legacy distributor channels by fostering direct relationships between equipment owners and lubricant suppliers with deep application knowledge. The shift is most visible within capital-intensive sectors such as wind energy and heavy manufacturing in Northern Europe.
Bio-Based Lubricants Market Segmentation
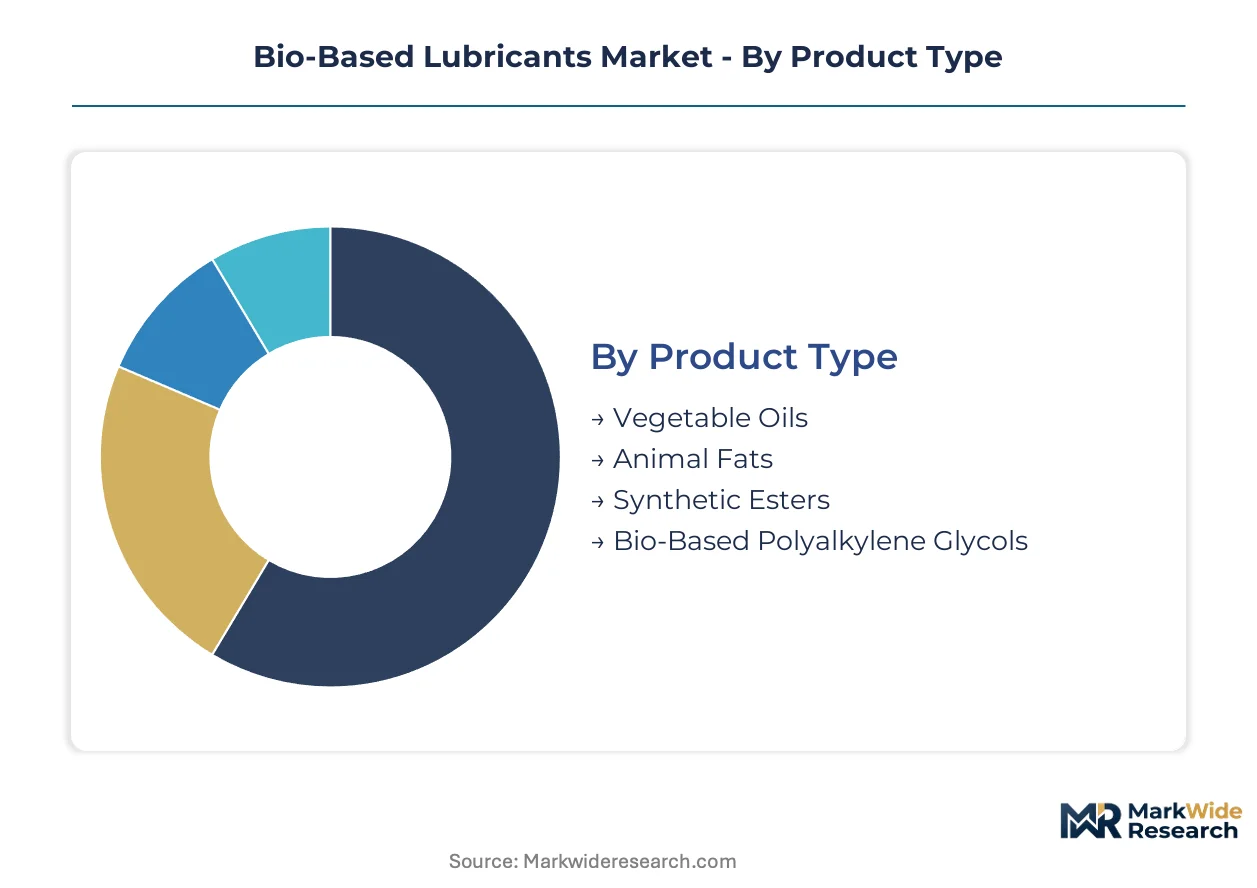
Understanding the varied applications and chemical compositions of bio-based lubricants is crucial for market participants. This segmentation highlights the diverse demands across industrial and automotive sectors, influencing product development and market penetration strategies for suppliers.
Product Type:
The chemical composition of bio-based lubricants dictates their performance characteristics and suitability for specific applications.
- Synthetic Esters:These engineered lubricants offer superior thermal stability and oxidative resistance, making them ideal for demanding industrial machinery applications. Their higher value is recognized in specialized uses requiring robust performance.
- Vegetable Oils:Derived from renewable feedstocks, vegetable oils form the foundational product type, prized for their inherent biodegradability and low ecotoxicity. They are widely adopted in environmentally sensitive applications and less extreme operating conditions.
- Animal Fats:These bio-based feedstocks provide an alternative source for lubricant production, often used in formulations where cost-effectiveness and specific lubricity properties are prioritized.
- Bio-Based Polyalkylene Glycols:These synthetic bio-lubricants offer good shear stability and low pour points, suitable for specific industrial gear oils and compressor lubricants.
Vegetable Oils commands the established base. The steepest expansion runs through Synthetic Esters.
Application:
The end-use function for bio-based lubricants varies significantly, driven by performance requirements and environmental mandates.
- Industrial Machinery:This segment represents a primary demand driver, with performance-based service contracts favoring suppliers with deep application expertise. Lubricants for heavy manufacturing and wind energy systems are critical.
- Automotive:Bio-lubricants in this segment require complex formulations to meet stringent OEM performance standards for engines, transmissions, and other vehicle components. Car manufacturers increasingly demand greener supply chains.
- Marine:This application is significantly influenced by regulatory frameworks like the US EPA's Vessel General Permit, which mandates environmentally acceptable lubricants for sensitive marine environments.
- Biofuels:While not a direct lubricant application, this segment represents a competing demand for certain bio-based feedstocks, impacting price stability for lubricant producers.
Demand in the Industrial Machinery segment is consistently high. The Automotive application is climbing the fastest due to OEM requirements.
End User:
The type of customer directly influences the specification and procurement of bio-based lubricants, reflecting diverse operational needs and sustainability goals.
- Manufacturing Sector:Industrial facilities, particularly in Germany and Japan, specify bio-lubricants to support ISO 14001 certification and broader corporate sustainability goals. This sector relies on consistent performance for heavy machinery.
- Automakers:These major industrial consumers drive demand for bio-lubricants that comply with their stringent performance standards and contribute to greener supply chains. Their requirements often involve complex testing and certification.
- Aerospace:This sector requires lubricants with extreme performance characteristics, including high thermal stability and low-temperature fluidity, for aircraft engines and hydraulic systems.
- Renewable Energy:Wind turbines and other renewable energy infrastructure utilize specialized bio-lubricants for gearboxes and hydraulic systems, often in challenging environmental conditions.
The Manufacturing Sector represents a large, established consumer base. Automakers are gaining share fastest due to sustainability mandates.
Formulation:
The specific blend of components within a bio-based lubricant determines its final performance characteristics and suitability for demanding environments.
- Chemical Additives:These components are crucial for enhancing the performance of bio-based lubricants, providing properties like anti-wear, anti-corrosion, and improved thermal stability. They bridge performance gaps with petroleum-based alternatives.
- Blends:Lubricant blends combine different base oils and additives to achieve a specific balance of performance, cost, and environmental attributes. This approach allows for customization across various industrial and automotive needs.
- Pure Lubricants:These formulations consist primarily of a single bio-based fluid, often vegetable oils, used in applications where high biodegradability is paramount and performance demands are moderate.
- Biodegradable Solutions:This category emphasizes lubricants specifically designed to break down naturally in the environment, meeting strict regulatory requirements for sensitive applications like marine or forestry.
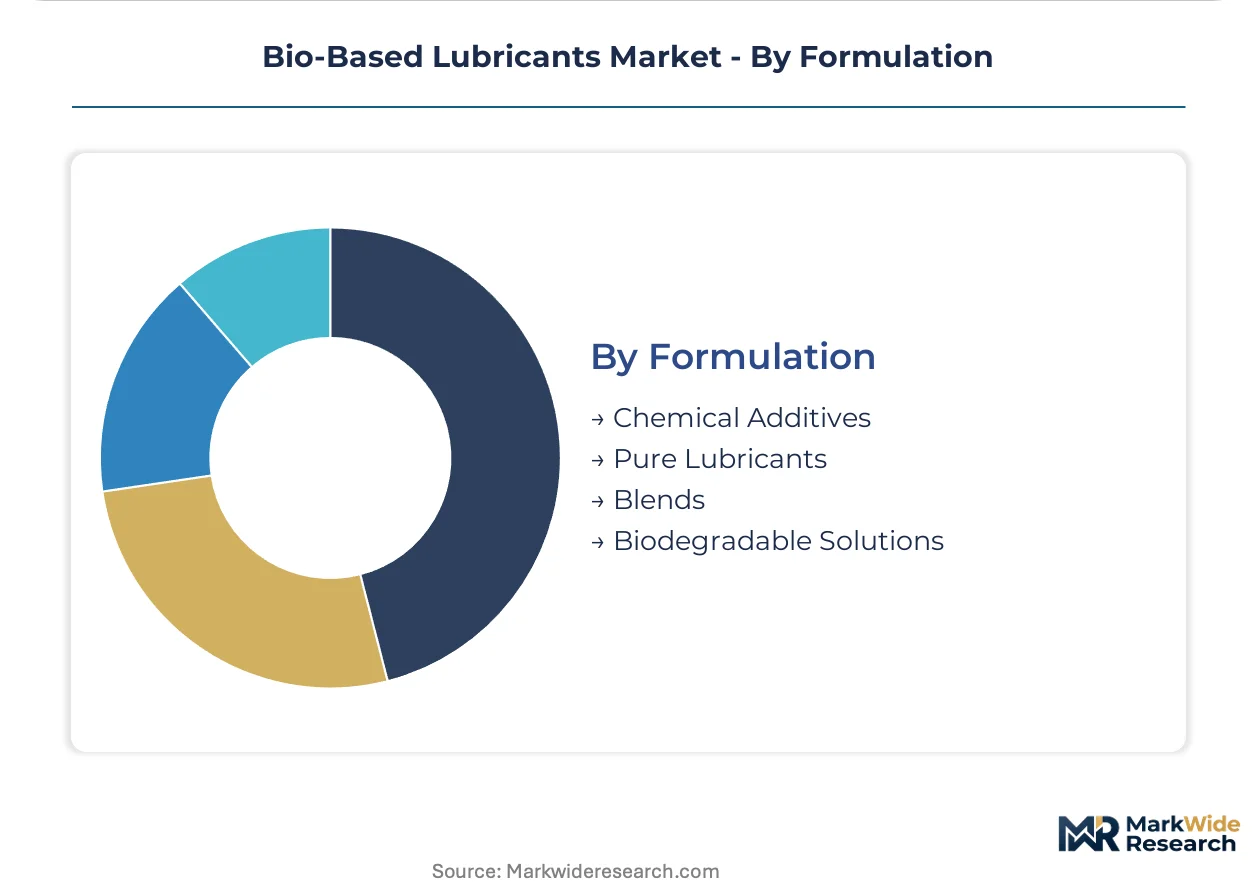
Pure Lubricants provide a foundational offering. The market for Chemical Additives is expanding most quickly, driven by performance demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bio-based lubricants market exhibits a complex interplay of regional demand and supply dynamics, often influenced by local feedstock availability and stringent environmental standards. Export-import balances vary significantly, with Europe leading in regulatory-driven demand while Asia-Pacific rapidly expands its industrial consumption base. This market structure reflects diverse industrialization stages and sustainability priorities worldwide.
Germany
Demand from the manufacturing sector and corporate sustainability goals drives the market in Germany. The EU Ecolabel and the Corporate Sustainability Reporting Directive (CSRD) compel industrial facilities to adopt greener operational inputs. The Ruhr region, a historical hub for heavy industry, actively integrates bio-lubricants into its advanced manufacturing processes.
United States
Industrial machinery and marine applications represent significant demand drivers across the United States. The US EPA's Vessel General Permit mandates environmentally acceptable lubricants for marine vessels operating in sensitive waters. The Gulf Coast, with its extensive shipping and petrochemical industries, is a key area for marine and industrial bio-lubricant adoption.
Japan
Japanese industrial facilities and automotive OEMs are increasingly specifying bio-lubricants to meet their environmental objectives. ISO 14001 standards encourage the adoption of sustainable inputs across various industries. The Kansai region, home to major manufacturing and automotive plants, shows strong uptake for high-performance bio-lubricants.
China
China's rapid industrialization and growing environmental awareness are accelerating the demand for bio-based lubricants. The country's dual carbon goals promote the use of sustainable materials across its vast manufacturing base. The Yangtze River Delta, a powerhouse of industrial production, is a critical region for market expansion.
India
India's expanding manufacturing sector and infrastructure development are creating new opportunities for bio-based lubricants. Government initiatives like the Production Linked Incentive (PLI) scheme encourage domestic manufacturing, indirectly boosting demand for sustainable industrial inputs. Gujarat, with its chemical and automotive manufacturing clusters, is a focal point for bio-lubricant adoption.
Bio-Based Lubricants Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on material science and formulation. The bio-based lubricants market exhibits a tiered structure, with integrated energy majors alongside specialized chemical producers. Key strategic archetypes include diversified energy conglomerates, niche performance lubricant providers, and feedstock innovators. Dominant competitive moves involve strategic partnerships for advanced feedstock development and portfolio diversification into high-value niche applications.
Integrated energy majors like Shell plc represent a broad approach, bundling bio-lubricants with extensive energy and service packages to industrial clients. Fuchs Petrolub SE exemplifies specialized industrial lubricant providers, leveraging deep application expertise to secure performance-based service contracts. Klüber Lubrication occupies a position as a high-performance, tailored solutions specialist, differentiating through sophisticated formulations for demanding industrial machinery applications.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| TotalEnergies SE |
| BP p.l.c. |
| Fuchs Petrolub SE |
| Emery Oleochemicals |
| Chevron Corporation |
| Klüber Lubrication |
| Panolin AG |
| Others |
Cost & Logistics Intelligence
Under-utilization of advanced feedstock processing capacity in Europe currently drives supplier behavior toward optimizing existing assets, impacting pricing posture for high-performance bio-lubricants. This scenario creates opportunities for strategic investments in specialized production technologies.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing structures for bio-based lubricants, particularly for complex formulations meeting stringent performance standards. Price differentiation stems from certified sustainability claims like the EU Ecolabel and specific thermal stability characteristics required for demanding applications. Pricing softness reflects the intense competition from petroleum-based alternatives in less regulated segments. Automotive OEMs exhibit lower price sensitivity due to compliance needs and performance demands, while smaller industrial facilities are more sensitive to cost.
Supply Chain Analysis
Upstream feedstock sourcing for bio-based lubricants primarily draws from agricultural regions, with rapeseed oil concentrated in Europe and soybean oil largely from the United States and South America. The market depends heavily on vegetable oils as base stocks and specialized chemical additives for performance enhancement. Commodity price volatility in agricultural markets, driven by competition from the food industry, represents a significant structural risk. Downstream distribution often runs through direct sales channels for performance-based contracts and specialized industrial distributors for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-based lubricants market currently stands at a platform-economics inflection, driven by the expanding ecosystem of performance-based service contracts integrating equipment OEMs and lubricant suppliers.
For Market Incumbents:
Insulate core industrial lubricant revenues by deepening application expertise and leveraging existing client relationships for performance-based service contracts. Invest strategically in advanced feedstock research, particularly genetically modified high-oleic oils, to bridge technical performance gaps with petroleum synthetics. Expand certification efforts for products like the EU Ecolabel to mitigate the threat of new regulatory mandates impacting market access.
For New Entrants and Emerging Players:
Pursue high-value niche applications such as food-grade lubricants and dielectric fluids for electric vehicles, where performance and sustainability premiums are higher. Target industrial economies in Southeast Asia as they begin implementing environmental regulations modeled on EU standards, representing a penetrable geography. A focused go-to-market angle should emphasize tailored, high-performance ester formulations that address specific industrial machinery challenges.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upward across advanced feedstock development and specialized formulation segments, signaling a maturation of the market. Long-term viability favors entities with intellectual property in synthetic esters derived from non-food biomass or with established certification pathways. The uptake of genetically modified high-oleic oils by major formulators serves as a key signal to watch for accelerated market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Esters | This initiative ensures supply stability for high-performance bio-lubricants in demanding industrial applications. |
| Joint Venture for Non-Food Biomass Development | Partnerships accelerate research into sustainable, cost-stable feedstocks, reducing reliance on food crops. |
| Green Manufacturing Process Certification | Achieving certified sustainable production enhances brand reputation and meets stringent corporate sustainability goals. |
| Long-term Feedstock Supply Agreements | Securing stable raw material input mitigates price volatility and ensures consistent product availability. |
| Product Launch in EV Dielectric Fluids | Diversifying into electric vehicle applications captures demand from a rapidly expanding, high-value segment. |
Research Approach
A spread of perspectives from lubricant formulators, industrial equipment engineers, environmental regulators, and feedstock suppliers converged on the working assumptions that underpin this analysis. This approach combined in-depth primary interviews with rigorous secondary validation using EU Ecolabel reports, US EPA publications, ISO 14001 certification databases, and corporate sustainability reports. Bottom-up and top-down triangulation ensured data consistency and comprehensive market coverage.
The demand-supply-balance framing guided the analytical framework across the analysis window, modeling market dynamics without specific year references. Segmentation dimensions included product type, application, end user, formulation, and regional regulatory stringency. Compound annual growth rates were derived from historical data trends and projected market drivers, with feedstock availability and regulatory implementation timelines serving as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global commodity prices or geopolitical disruptions affecting agricultural supply would shift the trajectory. Forecasts reflect assumptions documented through extensive research and cross-checked against industry benchmarks. Cross-checking against external market reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Hydraulic Oil Additives Market
Lubricants
Iraq Lubricants Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Europe Marine Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
Lubricity Improvers Market
Lubricants
High Performance Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Marine Lubricants Market