
 Global Hydraulic Fluid Market | 2026-2036
Global Hydraulic Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Fluid Market Foresight
Base oil refinery investment in the Middle East is shifting trade flows for hydraulic fluid feedstocks. Shell plc leverages integrated upstream chemical production to sustain margin control across synthetic grades. Exxon Mobil Corporation anchors North American distribution through captive blending capacity and direct OEM supply contracts. FUCHS specializes in high-performance formulations for metalworking equipment, competing on technical service density rather than volume pricing.
Hydraulic fluid is a non-compressible liquid medium formulated with base stocks and additive packages to transmit force in enclosed mechanical systems, typically operating at pressures from 3,000 to 6,000 psi in industrial settings. Its primary purpose is power transmission, lubrication of moving parts, heat transfer, and corrosion protection within hydraulic machinery. Mineral oil formulations still occupy the largest volume share across construction equipment applications, though synthetic oil grades command premium positioning in aerospace systems and extreme-temperature mining operations. Bio-based fluid demand is accelerating among European energy producers facing supply chain audits under CSRD disclosure rules.
The EPA administers used oil management standards under RCRA that shape collection and re-refining economics in the United States, while REACH compliance in Europe restricts certain anti-wear additive chemistries and forces reformulation cycles. China's SAMR enforces GB standard conformity for hydraulic fluids sold into domestic heavy equipment channels, creating a dual-track certification burden for multinational suppliers. Stakeholders must monitor regulatory divergence between biodegradability mandates and performance specifications when allocating R&D budgets across regional formulation portfolios.
Market Dynamics
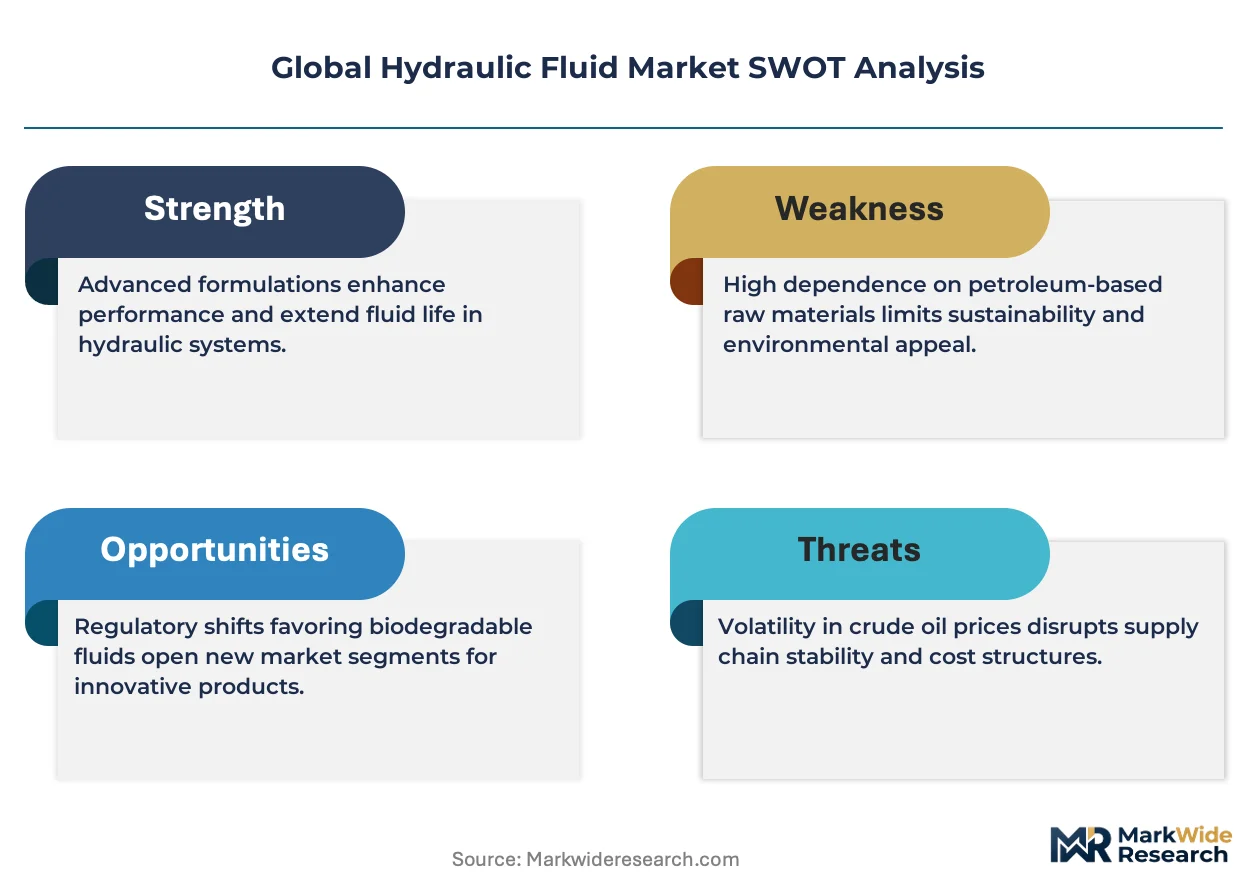
China's MIIT lubricant standards and the EU F-Gas Regulation are forcing simultaneous reformulation across mineral, synthetic, and bio-based grades, compressing product development cycles while OEMs tighten emission specifications for construction and mining equipment.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated gas emissions are accelerating demand for low-GWP synthetic hydraulic fluids in German automotive supplier corridors.
- Construction equipment procurement:Operators across emerging industrial clusters in India and Vietnam are expanding fluid volumes as infrastructure investment concentrates in East Asian manufacturing corridors.
- CSRD disclosure rules:European energy producers face supply chain audits that accelerate bio-based fluid adoption for carbon accounting transparency.
Market Restraints
- Base oil feedstock volatility:Middle East refinery investment shifts are creating price instability for Group II and III base stocks essential to synthetic formulations.
- REACH additive restrictions:ECHA limitations on zinc dialkyldithiophosphate (ZDDP) anti-wear chemistries force costly reformulation cycles without performance guarantees.
- Mineral oil lock-in:Construction equipment fleets in price-sensitive markets resist premium synthetic upgrades despite OEM pressure for extended drain intervals.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for heavy machinery manufacturing create localized blending demand in Gujarat and Tamil Nadu industrial zones.
- Digital fluid monitoring:IoT sensor integration with hydraulic systems enables predictive maintenance contracts and recurring revenue streams for technical service providers.
- Re-refining infrastructure:RCRA economics in the United States favor used oil collection network expansion, creating circular supply advantages for integrated operators.
Industry Challenges
- Dual certification burden:China's SAMR enforces GB standard conformity alongside ISO specifications, extending product registration timelines for multinational suppliers.
- Additive package complexity:Biodegradability mandates from EU Ecolabel conflict with extreme-pressure performance requirements in mining applications, forcing portfolio segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Fluid Market |
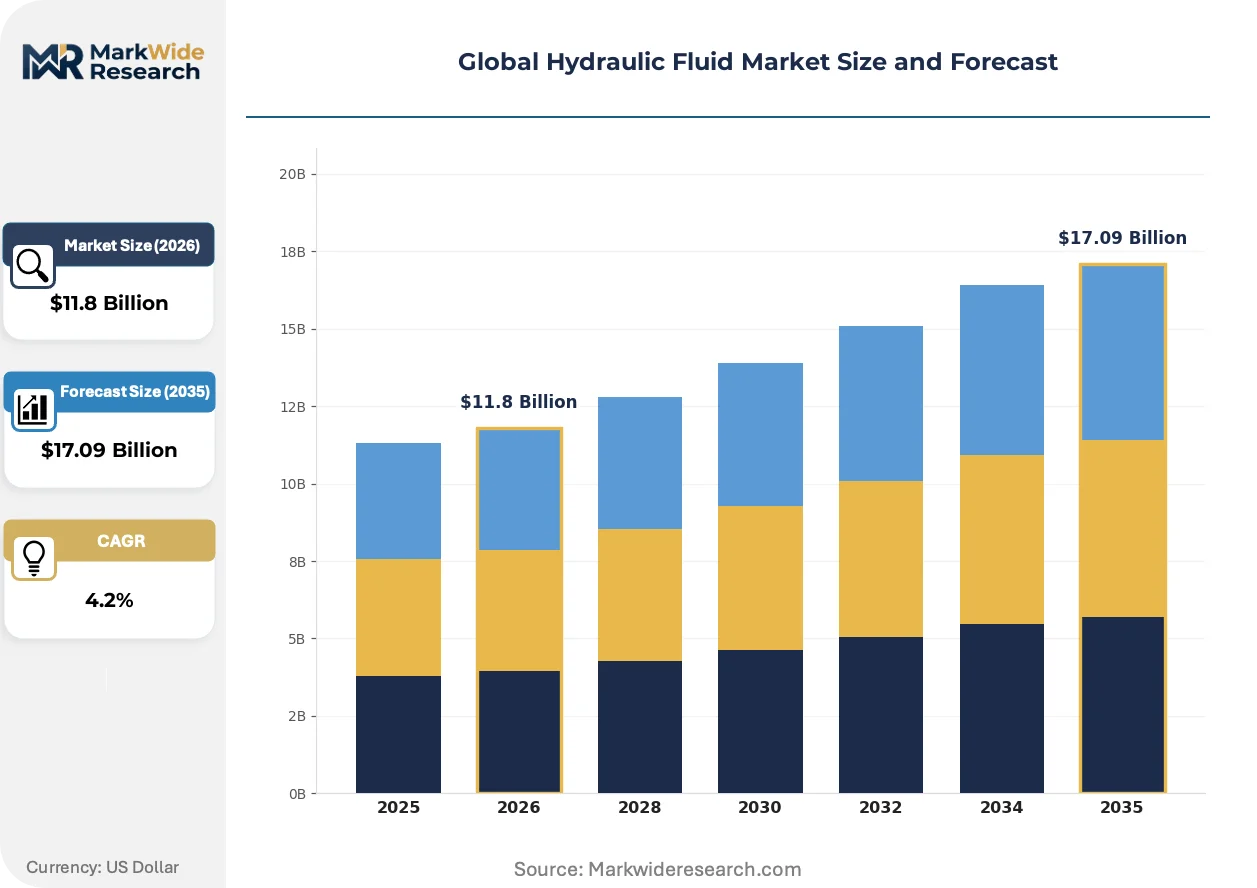
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.09 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fluid Type: Mineral Oil, Synthetic Oil, Water-Based Fluid, Bio-Based Fluid, Phosphate Ester Application: Construction Equipment, Agricultural Machinery, Metalworking Equipment, Marine Vessels, Aerospace Systems End User: Manufacturing Plants, Mining Operations, Transportation Companies, Energy Producers, Heavy Equipment Operators Packaging Type: Drums, Totes, Barrels, Bottles, Bulk Containers |
| Companies Covered | Shell plc, Exxon Mobil Corporation, Chevron Corporation, BP p.l.c., TotalEnergies, FUCHS, PetroChina Company Limited, China Petroleum & Chemical Corporation, Valvoline Global Operations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Fluid Market Shifts & Advancements
Real-time fluid condition monitoring and predictive analytics are automating maintenance scheduling, while regulatory divergence between biodegradability and performance specifications splits formulation strategies across regional portfolios.
Smart sensor integration into hydraulic reservoirs is automating viscosity, moisture, and particulate detection for fleet operators. Mining companies in Western Australia and Chilean copper belts are deploying these systems at scale. The technology is automating technician dispatch decisions and compressing unplanned downtime intervals.
REACH authorization procedures for anti-wear additive chemistries are restricting formulation flexibility across European metalworking and mobile equipment segments. ECHA substance evaluation timelines extend 18-24 months, forcing advance R&D commitments. German automotive hydraulic component suppliers are responding with accelerated synthetic base stock qualification programs.
Buyer consolidation among rental equipment fleets is compressing supplier negotiation cycles and unbundling technical service from fluid procurement. United Rentals and Ashtead Group specifications now drive North American blending priorities. This concentration is most visible in Texas and Florida construction corridors where fleet standardization reduces SKU complexity.
Global Hydraulic Fluid Market Segmentation
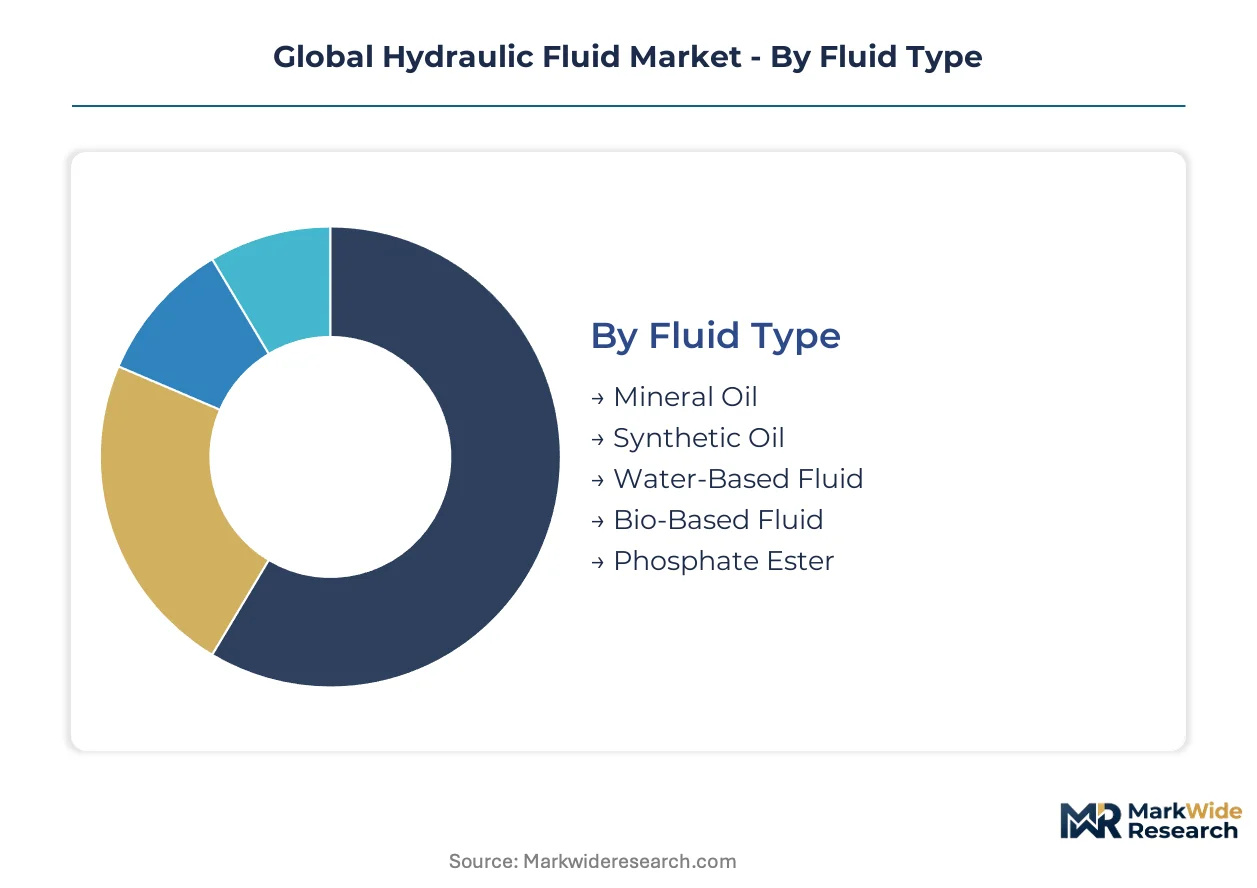
Fluid specification tiers, application pressure requirements, and procurement volume scales create distinct profit pools across the hydraulic fluid value chain. Buyers prioritize thermal stability, biodegradability credentials, or cost-per-liter depending on equipment criticality and regulatory exposure.
Fluid Type:
Cost tier determines procurement behavior across fleet operators and maintenance contractors.
- Mineral Oil:Refined petroleum base stocks dominate construction equipment fleets due to established supply chains and price accessibility. Demand concentrates in Indian and Vietnamese infrastructure corridors where total cost of ownership drives specification decisions.
- Synthetic Oil:Polyalphaolefin and ester formulations deliver extreme-temperature performance for aerospace systems and underground mining equipment. German automotive supplier zones and Western Australian iron ore operations absorb premium volumes as OEM drain intervals extend.
- Water-Based Fluid:Fire-resistant glycols and water-glycol emulsions serve steel mills and foundries with ignition risk exposure. Metalworking plants in China's Hebei province specify these for blast furnace proximity.
- Bio-Based Fluid:Vegetable oil esters and synthetic esters from renewable feedstocks satisfy EU Ecolabel criteria. European energy producers facing CSRD disclosure mandates are accelerating adoption for carbon accounting transparency.
- Phosphate Ester:Aviation-grade fire resistance supports aircraft hydraulic systems and power generation turbines. Aerospace OEMs in Toulouse and Seattle anchor specification development.
Mineral oil leads on scale; bio-based fluid leads on momentum.
Application:
Operating pressure regimes and duty cycles fragment demand across equipment categories.
- Construction Equipment:Excavators, loaders, and cranes operate at 3,000–5,000 psi with high contamination exposure. Fleet operators in Texas and Florida construction corridors standardize specifications to reduce SKU complexity.
- Agricultural Machinery:Tractors and harvesters face seasonal use patterns with wide temperature swings. Brazilian soybean belt and Ukrainian grain regions drive procurement timing.
- Metalworking Equipment:Press brakes, stamping presses, and CNC machines require precision viscosity control. German automotive component plants and Japanese machine tool builders set formulation benchmarks.
- Marine Vessels:Deck machinery and steering systems operate in salt-laden environments with biodegradability requirements. Rotterdam and Singapore port authorities enforce discharge standards.
- Aerospace Systems:Flight control hydraulics demand fire resistance and thermal stability across altitude ranges. Boeing and Airbus supply chains in Wichita and Hamburg anchor qualification protocols.
Construction equipment commands volume concentration; aerospace systems command margin premiums.
End User:
Technical service integration and inventory management sophistication separate buyer segments.
- Manufacturing Plants:Automotive and electronics assembly lines require predictive maintenance integration. German OEM supplier parks in Bavaria and Baden-Württemberg specify fluid monitoring systems.
- Mining Operations:Open-pit and underground extraction equipment faces extreme contamination and temperature cycles. Chilean copper belts and Western Australian iron ore regions absorb high-viscosity synthetic grades.
- Transportation Companies:Rail and trucking fleets prioritize extended drain intervals and nationwide distribution networks. Union Pacific and Deutsche Bahn maintenance contracts drive blending priorities.
- Energy Producers:Wind turbine hydraulics and gas turbine control systems demand low-temperature flow properties. North Sea offshore platforms and Texas wind farms specify cold-climate formulations.
- Heavy Equipment Operators:Rental fleets and contractor equipment pools balance acquisition cost against downtime risk. United Rentals and Ashtead Group procurement specifications compress supplier negotiation cycles.
Manufacturing plants lead on technical service density; mining operations lead on per-site volume intensity.
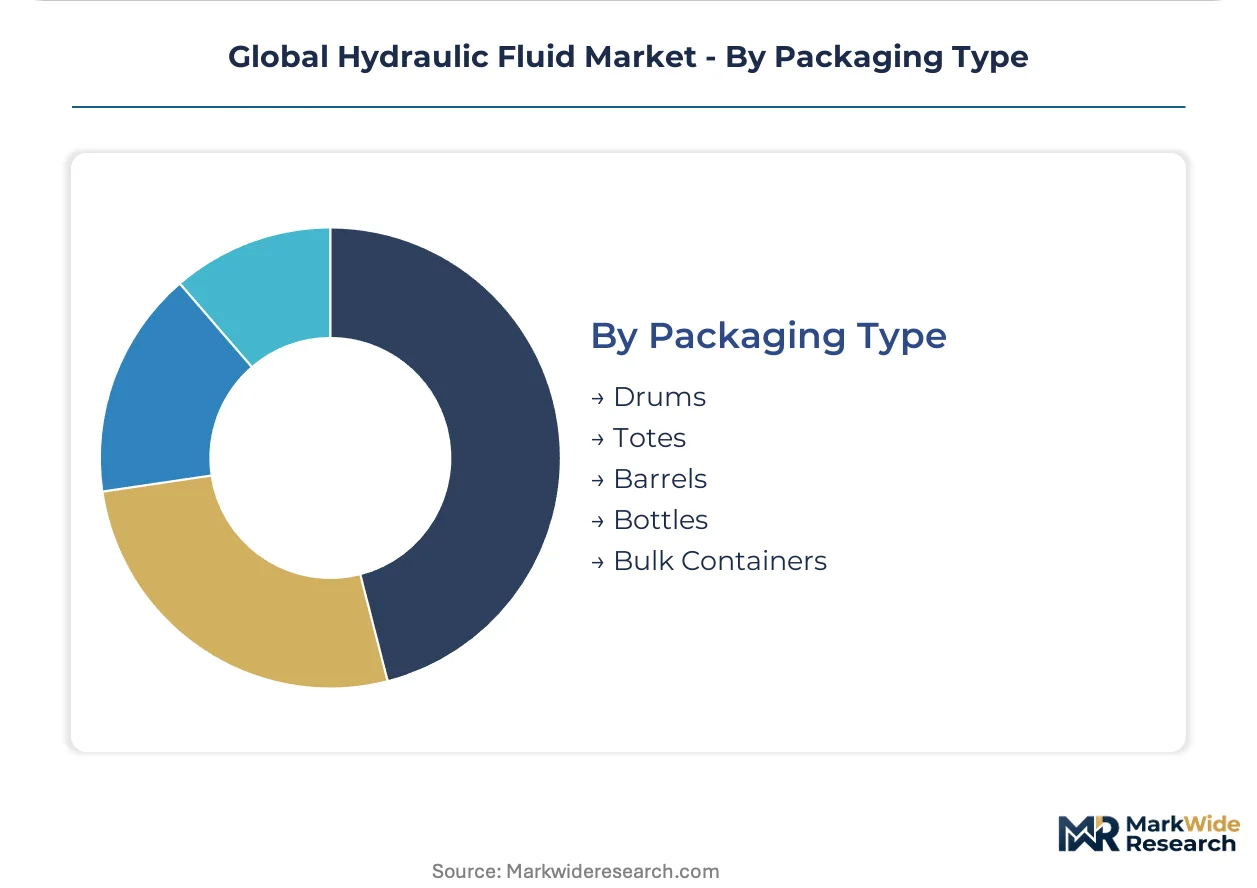
Packaging Type:
Logistics infrastructure and consumption velocity determine format selection.
- Drums:55-gallon steel containers serve mid-size maintenance shops with limited storage. Independent repair facilities across the US Midwest rely on drum delivery networks.
- Totes:Intermediate bulk containers reduce handling costs for high-volume consumers. Fleet maintenance depots in Gujarat industrial zones specify totes for localized blending operations.
- Barrels:Wooden and fiber containers support specialty fluid exports with customs documentation requirements. European re-refiners ship reclaimed base stocks in barrel formats.
- Bottles:Quart and gallon containers address top-off demand and small equipment service. Retail automotive channels and agricultural cooperatives stock bottle formats.
- Bulk Containers:Tank trucks and railcars feed captive blending facilities and direct OEM supply contracts. ExxonMobil's Baytown refinery and Shell's Pernis complex distribute via bulk infrastructure.
Bulk containers lead on throughput efficiency; totes lead on flexibility for emerging market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between REACH compliance costs in Europe and MIIT standardization in China is shifting formulation investment toward jurisdictions with clearer certification pathways. Suppliers now arbitrage between Germany's additive restrictions and China's dual-track GB standard enforcement.
United States
Construction equipment rental fleets in Texas and Florida drive bulk procurement volumes as United Rentals and Ashtead Group consolidate specifications. EPA RCRA administration of used oil collection networks shapes re-refining economics. Shell's Baytown refinery and ExxonMobil's captive blending capacity anchor Gulf Coast supply corridors.
Germany
Automotive supplier zones in Bavaria and Baden-Württemberg absorb premium synthetic grades under EU F-Gas Regulation mandates for low-GWP formulations. ECHA restrictions on ZDDP anti-wear chemistries force reformulation cycles. Stuttgart and Wolfsburg OEM parks set qualification protocols for hydraulic component suppliers.
China
Heavy equipment manufacturing clusters in Guangdong and Jiangsu provinces expand fluid procurement as SAMR enforces GB standard conformity alongside ISO specifications. MIIT lubricant standards reshape formulation requirements. Sinopec and PetroChina blending facilities in Shanghai and Ningbo industrial zones serve domestic OEM channels.
India
Production-linked incentives for heavy machinery under the PLI scheme concentrate blending demand in Gujarat and Tamil Nadu industrial corridors. BIS standards govern domestic specification compliance. Construction equipment operators in Mumbai-Pune and Chennai manufacturing belts expand procurement volumes.
Japan
Machine tool builders in Nagoya and Osaka prefectures set precision viscosity benchmarks for metalworking fluid formulations. METI industrial standards coordinate with JIS specifications. Japanese automotive hydraulic component suppliers in Aichi prefecture anchor synthetic base stock qualification programs.
Global Hydraulic Fluid Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and digital fluid monitoring services. The market structures around three tiers: integrated oil majors with captive base stock supply, regional blenders with technical service density, and specialty formulators targeting aerospace or mining extremes. Competitive moves concentrate on backward integration into base oil refining and strategic partnerships for re-refining network access.
Within the integrated major tier, Shell plc and Exxon Mobil Corporation exemplify upstream-downstream coordination. Shell's Pernis complex and ExxonMobil's Baytown refinery represent captive supply advantages. FUCHS occupies a position emphasizing technical service density over volume pricing. These three anchors illustrate the strategic divergence between scale-driven feedstock control and specialization-driven margin capture.
| Leading Market Players |
|---|
| Shell plc |
| Exxon Mobil Corporation |
| Chevron Corporation |
| BP p.l.c. |
| TotalEnergies |
| FUCHS |
| PetroChina Company Limited |
| China Petroleum & Chemical Corporation |
| Valvoline Global Operations |
| Others |
Supply & Pricing Matrix
Synthetic base stock qualification programs across German automotive supplier zones are compressing formulation development timelines while simultaneously concentrating procurement leverage among integrated refiners with captive chemical production. This dual squeeze on cost structures and supply access is reshaping margin distribution between mineral oil blenders and premium synthetic formulators.
Pricing Analysis
Distributor margins on mineral oil grades compress under fleet standardization mandates from United Rentals and Ashtead Group, while direct-to-OEM contracts for synthetic formulations retain pricing power through extended drain interval guarantees. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified synthetics from construction equipment mineral oils and emerging bio-based alternatives. Cost compression in standard mineral grades intensifies because buyer consolidation favors volume discounts over technical service bundling. Rental fleet operators exhibit highest price sensitivity; aerospace OEM qualification programs show least.
Supply Chain Analysis
Re-refining network expansion under EPA RCRA economics is creating circular supply advantages for operators with collection infrastructure, though feedstock quality variability limits output grade flexibility. Base oil production concentrates in the United States, China, and the Netherlands, with Group II and III stocks drawing from Middle East refinery investment shifts. Additive packages rest on zinc dialkyldithiophosphate chemistries facing REACH restrictions, plus polyalphaolefin base stocks tethered to ethylene cracking economics. Single-source vulnerability runs through German automotive supplier corridors for qualified synthetic grades. Distribution runs through bulk tank terminals feeding captive blending facilities and direct OEM supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium synthetic grade penetration as OEM drain interval specifications extend and bio-based certification commands carbon accounting premiums.
For Market Incumbents: Deepen backward integration into Group II and III base oil refining to secure feedstock margin control against Middle East supply volatility. Expand re-refining collection networks under RCRA economics to capture circular supply advantages. Defend against specialty formulator encroachment by accelerating synthetic qualification programs with Stuttgart and Wolfsburg OEM parks. For New Entrants and Emerging Players: The price-point gap between premium aerospace synthetics and economy mineral oils offers white-space targeting for mid-tier bio-based formulations with EU Ecolabel certification. Gujarat and Tamil Nadu industrial zones under India's PLI scheme present the most penetrable geography for localized blending operations. Pursue digital fluid monitoring service bundling as differentiated go-to-market positioning against established technical service networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders with technical service density but lacking captive base stock supply. Long-term viability favors operators with backward integration into refining or forward integration into re-refining networks. Monitor ECHA substance evaluation timelines for ZDDP anti-wear chemistries as inflection signal for reformulation cycle intensity and R&D commitment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Captive supply of Group II and III stocks secures margin control against Middle East price volatility for integrated majors. |
| Re-Refining Network Expansion | RCRA-compliant used oil collection infrastructure creates circular supply advantages and feedstock cost hedging. |
| Synthetic Base Stock Qualification Programs | German automotive supplier zones demand extended drain interval formulations that command premium positioning. |
| Digital Fluid Monitoring Service Launch | IoT sensor integration enables predictive maintenance contracts with recurring revenue streams for technical service providers. |
| Bio-Based Formulation Certification | EU Ecolabel compliance satisfies CSRD disclosure mandates from European energy producers accelerating adoption. |
Research Methodology
Multiple input streams — primary interviews with maintenance directors at mining operations and construction fleet operators, technical consultations with plant engineers at German automotive supplier parks, and structured exchanges with OEM procurement teams at hydraulic component manufacturers — were reconciled against secondary validation from customs and trade flow data, SEC 10-K filings of integrated oil majors, and MIIT lubricant standard documentation. Bottom-up volume modeling across fluid type, application pressure regime, and end-user procurement sophistication triangulated with top-down market sizing from refinery capacity disclosures and blending facility throughput estimates.
Historical volume trajectories were cross-referenced against panel input from industry participants to derive expansion rates across the analysis window. Segmentation dimensions modeled include fluid specification tier, operating pressure requirement, end-user technical service integration level, and regional regulatory compliance burden. CAGRs were computed from reconciled base-year consumption estimates and projected demand curves incorporating OEM specification evolution and fleet replacement cycles. Forecast inputs incorporated REACH additive restriction timelines and China's SAMR dual-track certification enforcement patterns.
Caveats apply where ECHA authorization delays for anti-wear chemistries or abrupt shifts in Middle East refinery export economics could materially shift the outlook. Practitioners should monitor MIIT lubricant standard revision schedules and EU F-Gas Regulation implementation intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Open Gear Lubricants Market
Lubricants
Norway Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Singapore Commercial Vehicles Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Polyurea Greases Market
Lubricants
Japan Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Philippines Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Lubricated Tracks Market
Lubricants
Drilling Lubricants Market