
 US Industrial Boiler Market | 2026-2036
US Industrial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Boiler Market Analysis
Buyer concentration across US food processing and pharmaceutical campuses is rebalancing as multi-site operators consolidate procurement under single-vendor agreements. Cleaver-Brooks leverages its national service network to anchor long-term maintenance contracts with these consolidated buyers. Miura America differentiates through compact modular steam systems that compete for footprint-constrained urban facilities. Clayton Industries specializes in rapid-start once-through designs that sustain replacement demand among chemical processors seeking thermal efficiency gains.
Industrial boilers are closed vessels designed to heat water or generate steam above 15 psig for process or power applications, with pressure ratings, burner configurations, and heat exchange surface materials determining operational suitability. Fire-tube units dominate the installed base across smaller manufacturing plants due to lower capital outlays and simpler maintenance protocols. Water-tube designs occupy the fastest-expanding segment among power generation and large process heating users where superheated steam at elevated pressures is required. Electric and biomass categories are gaining share as natural gas price volatility and federal clean energy incentives reshape fuel type selection across the application spectrum.
EPA New Source Performance Standards, OSHA Process Safety Management rules, and state-level emissions trading programs collectively tighten compliance thresholds for boiler operators, elevating capital requirements for upgrades and replacements. The Department of Energy's efficiency standards for commercial and industrial equipment further constrain product design choices available to manufacturers. Stakeholders must monitor evolving state renewable portfolio standards and carbon pricing mechanisms to anticipate fuel switching timelines and retrofit investment cycles.
Market Dynamics
EPA New Source Performance Standards and state carbon mandates are forcing capital-intensive fuel conversions across the installed base, compressing replacement cycles and elevating procurement authority to corporate engineering headquarters.
Growth Catalysts
- USDA Sanitation Standards:Food processing facilities in the Midwest are expanding steam generation capacity to meet stricter federal hygiene requirements, driving boiler capacity additions across dairy and meat processing corridors.
- Natural Gas Infrastructure:Pipeline network expansions in Texas and Ohio industrial corridors are enabling fuel-switching investments that displace aging coal and residual oil-fired units.
- Biomass Feedstock Availability:Agricultural residue supply chains in California's Central Valley are anchoring renewable thermal installations for processors seeking compliance with state renewable portfolio standards.
Market Restraints
- Steel and Alloy Input Volatility:Pressure vessel-grade stainless steel and specialty alloy pricing swings compress manufacturer margins and extend quotation validity periods.
- Specialized Fabrication Concentration:ASME-certified pressure vessel fabrication capacity clusters in Gulf Coast and Great Lakes manufacturing zones, creating geographic supply bottlenecks.
- Emissions Control Retrofit Complexity:Selective catalytic reduction and baghouse integration with legacy fire-tube designs faces physical space constraints in footprint-limited facilities.
Strategic Opportunities
- Modular Steam Systems:Compact once-through designs are penetrating urban pharmaceutical and food campuses where land constraints block conventional boiler house construction.
- Hydrogen-Ready Burner Platforms:Dual-fuel combustion systems capable of 30% hydrogen blending are capturing early-mover utility incentives in California and New York decarbonization programs.
- Predictive Maintenance Analytics:IoT-enabled tube leak detection and efficiency monitoring are opening recurring revenue streams through performance-guaranteed service contracts.
Industry Challenges
- Boilermaker Craft Shortage:Welding certification programs and ASME code expertise pipelines are failing to replace retiring skilled trades, extending installation timelines.
- Permitting Coordination:Air quality pre-construction permits in non-attainment zones require 12-18 month approval windows that misalign with capital budget cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Boiler Market |
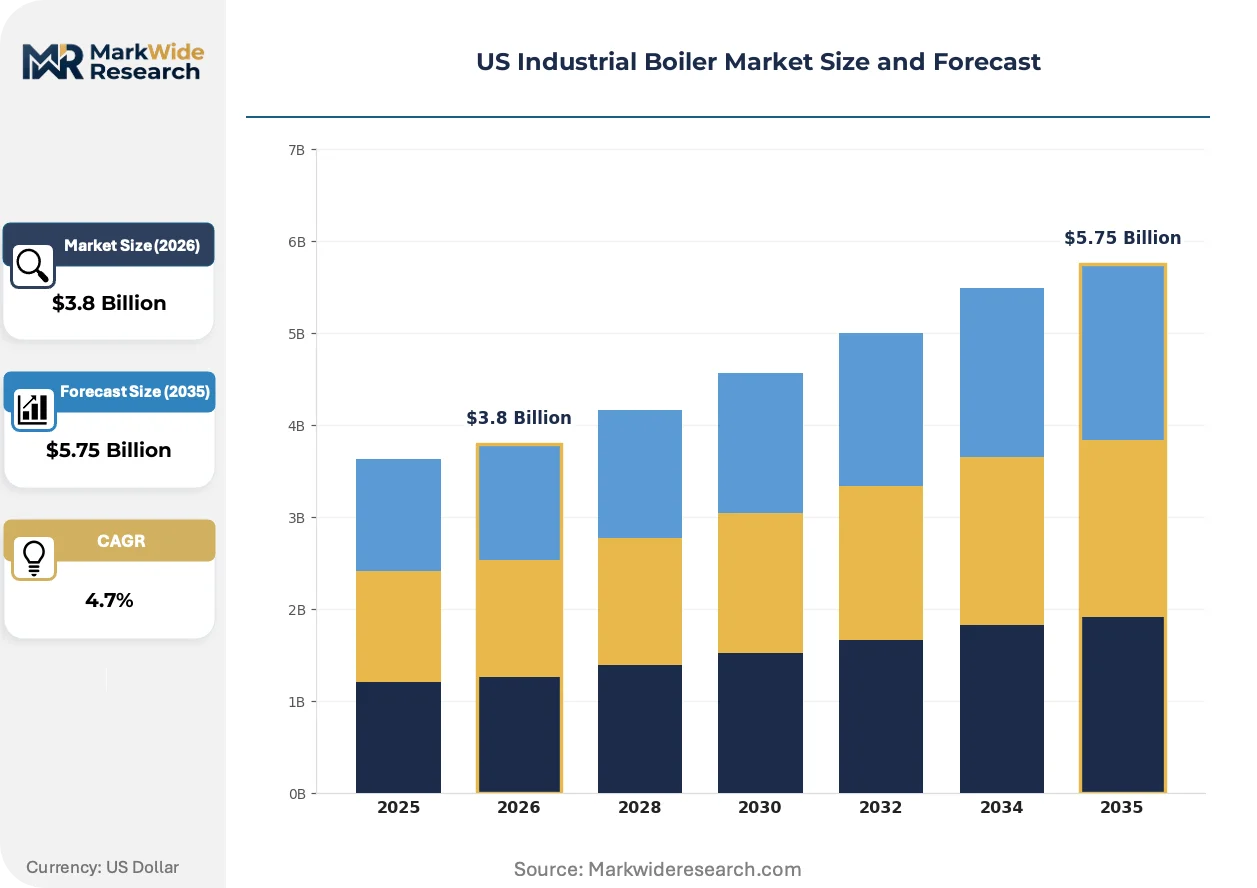
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Electric, Biomass End User: Manufacturing, Power Generation, Food Processing, Pharmaceutical Fuel Type: Natural Gas, Oil, Coal, Renewable Application: Heating, Steam Generation, Process Heating, Hot Water Production |
| Companies Covered | Clayton Industries, Unilux Advanced Manufacturing, Cleaver-Brooks, Hurst Boiler & Welding, Fulton Companies, Babcock & Wilcox Enterprises, Velocity Boiler Works, ECR International, Miura America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Boiler Market Emerging Trajectories
Digital combustion optimization and low-NOx burner architectures are compressing the performance gap between legacy fire-tube workhorses and advanced water-tube systems, while modular deployment models are redrawing site logistics and procurement patterns.
Modular once-through steam generators are decentralizing thermal infrastructure across pharmaceutical and food processing campuses. Facilities in Philadelphia and Boston metropolitan areas are adopting skid-mounted 200-600 horsepower units to bypass central plant construction. This distributed architecture is decentralizing capital deployment from single large installations to phased capacity additions that track production volume ramps.
The EPA's updated Maximum Achievable Control Technology standards for industrial boilers are mandating particulate matter and mercury emissions reductions. Operators in Texas petrochemical corridors face retrofit deadlines that compress project execution windows. Chemical processors are responding by accelerating natural gas conversions ahead of compliance dates to avoid continuous emissions monitoring system installations.
Consolidated procurement under multi-site master service agreements is displacing facility-level vendor selection across food and pharmaceutical operators. Corporate engineering teams in Chicago and Minneapolis headquarters are centralizing specifications and negotiating enterprise pricing. This concentration is most visible in Midwest dairy processing networks where three operators control 40% of regional steam capacity.
US Industrial Boiler Market Segmentation
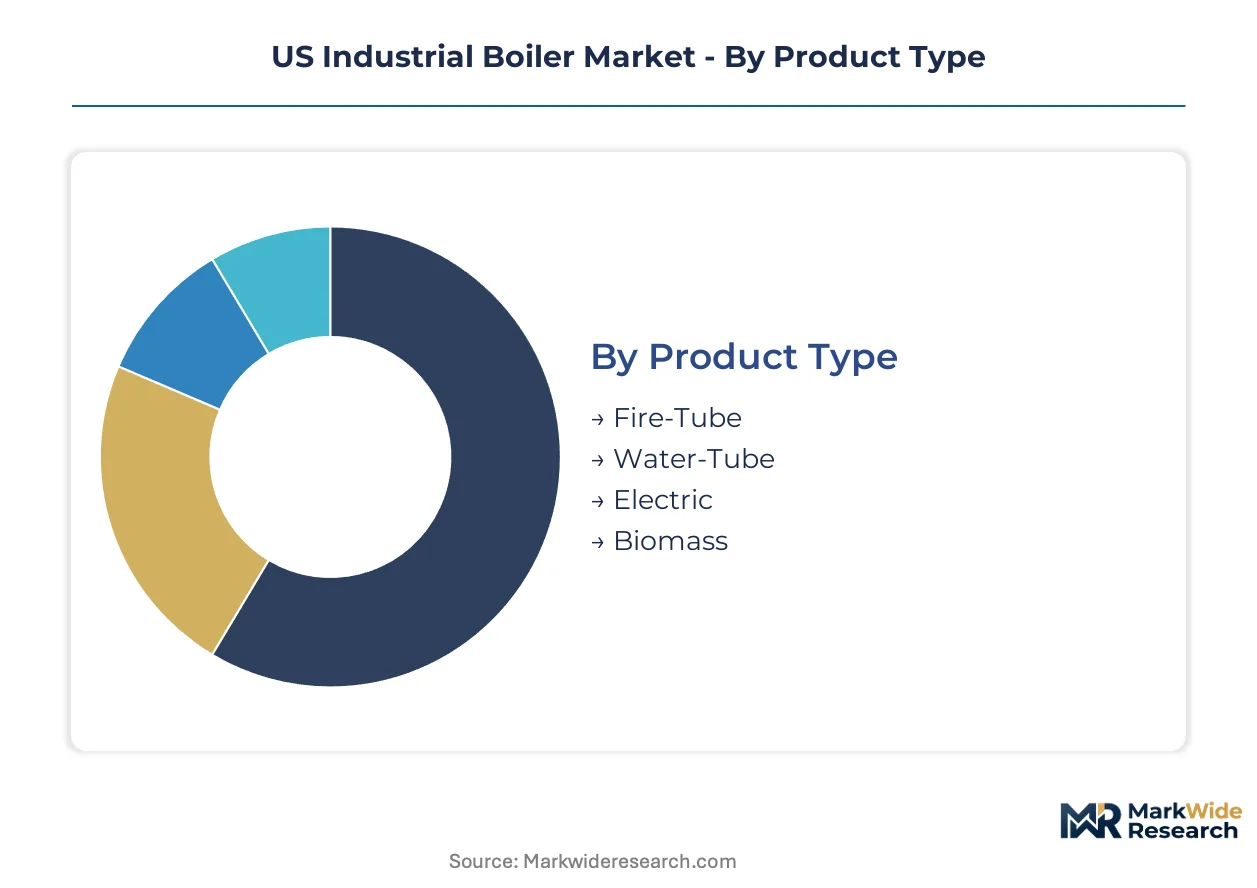
Boiler procurement decisions in the US industrial base are fragmenting across fuel conversion timelines, pressure specifications, and site-specific emissions constraints. Segment-level demand patterns reveal divergent replacement cycles between legacy manufacturing corridors and clean energy transition zones.
Product Type:
Upgrade cycles across the installed base vary sharply by pressure vessel architecture and burner compatibility with emerging fuel blends.
- Fire-Tube:Cylindrical pressure vessels route combustion gases through submerged tubes to heat surrounding water, with pressure ratings typically capped at 350 psig. Meatpacking plants in Nebraska and Kansas continue specifying these units for sanitation steam where capital budgets constrain upfront investment.
- Water-Tube:Water circulates through tubes exposed to combustion heat, enabling superheated steam delivery above 1,000 psig for turbine applications. Texas petrochemical complexes are accelerating replacements of aging fire-tube clusters with these systems to meet EPA Maximum Achievable Control Technology deadlines.
- Electric:Resistance or electrode elements generate steam without combustion emissions, eliminating stack permitting requirements. California pharmaceutical campuses in South San Francisco are deploying these units where air quality non-attainment status blocks new gas-fired permits.
- Biomass:Fluidized bed or stoker-fired designs combust agricultural residues, wood chips, or energy crops. Central Valley food processors are installing these systems to capture state renewable thermal incentives and hedge natural gas price volatility.
Volume placements concentrate in Fire-Tube units across legacy manufacturing; the faster expansion belongs to Biomass installations in California and Pacific Northwest decarbonization corridors.
End User:
Procurement authority is centralizing under corporate engineering headquarters as multi-site operators consolidate vendor relationships and standardize specifications.
- Manufacturing:General industrial plants spanning automotive stamping, textile finishing, and metal fabrication. Ohio and Michigan automotive suppliers are replacing residual oil-fired units with natural gas systems as pipeline infrastructure reaches secondary industrial parks.
- Power Generation:Cogeneration facilities and utility-scale industrial power producers. Texas Gulf Coast chemical complexes are expanding captive power capacity to isolate operations from grid reliability concerns.
- Food Processing:Dairy pasteurization, meat rendering, and beverage sterilization operations. Wisconsin cheese processors are adding redundant steam capacity to meet USDA Hazard Analysis Critical Control Point sanitation mandates.
- Pharmaceutical:Active pharmaceutical ingredient synthesis and sterile formulation facilities. New Jersey and Massachusetts biotech corridors are specifying clean steam generators with pure steam validation protocols.
Procurement volume clusters in Food Processing networks; Pharmaceutical campuses are gaining share fastest as biologics manufacturing expands.
Fuel Type:
Emissions compliance deadlines and infrastructure availability are forcing fuel-switching investments that compress replacement cycles.
- Natural Gas:Cleanest fossil combustion profile with established pipeline distribution networks. Appalachian shale proximity is accelerating conversions across Pennsylvania and Ohio manufacturing zones ahead of state carbon pricing implementation.
- Oil:Residual fuel oil and distillate backups retained for interruptible gas rate structures. Northeast heating oil infrastructure sustains dual-fuel capability in legacy institutional and industrial installations.
- Coal:Declining share confined to captive mine-mouth power generation and select chemical processes with process-specific ash requirements. Remaining units face accelerated retirement under EPA Mercury and Air Toxics Standards.
- Renewable:Biogas from anaerobic digesters, landfill gas, and synthetic renewable natural gas. Iowa and Minnesota ethanol producers are capturing biogas from stillage processing to offset thermal energy purchases.
Natural Gas dominates current placements; Renewable fuel integration is climbing fastest as biogas infrastructure matures.
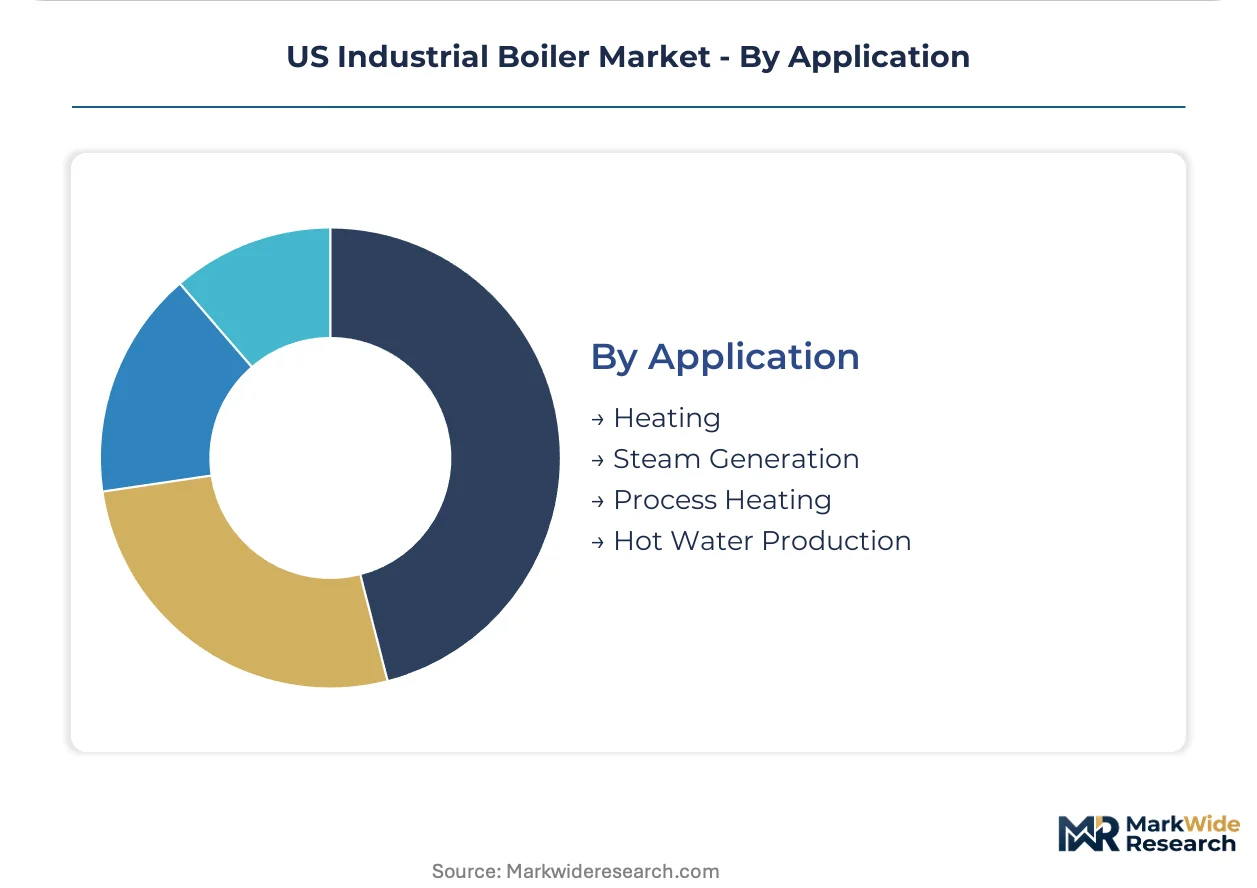
Application:
Process thermal requirements and steam quality specifications determine pressure vessel selection and auxiliary equipment scope.
- Heating:Space heating and comfort conditioning for industrial facilities. Michigan and Illinois automotive assembly plants are upgrading heating systems during facility modernization programs.
- Steam Generation:Process steam for sterilization, humidification, and mechanical drive applications. Louisiana chemical processors require saturated steam at precise pressure tolerances for reactor temperature control.
- Process Heating:Direct thermal energy transfer to reactors, distillation columns, and drying equipment. Texas refinery expansion projects are specifying high-temperature thermal fluid systems for crude preheating.
- Hot Water Production:Low-pressure hot water for washdown, CIP systems, and building services. Food safety regulations are driving temperature monitoring upgrades across dairy processing hot water loops.
Steam Generation commands the largest installed base; Process Heating applications are expanding most quickly with petrochemical capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in three industrial corridors where fuel infrastructure, emissions policy, and processing capacity intersect. Texas petrochemical complexes, Ohio manufacturing zones, and California food processing clusters anchor replacement cycles and new capacity additions.
Texas
Gulf Coast chemical processors are expanding captive steam capacity to isolate operations from grid instability. EPA Maximum Achievable Control Technology deadlines are accelerating natural gas conversions ahead of retrofit mandates. Houston and Beaumont refining corridors are specifying high-pressure water-tube systems for crude preheating and reactor temperature control.
Ohio
Appalachian shale proximity is enabling pipeline-fed natural gas conversions across residual oil-fired manufacturing plants. State carbon pricing implementation timelines are compressing investment decisions for industrial operators. Cleveland and Toledo automotive supplier parks are replacing aging fire-tube clusters during facility modernization programs.
California
Central Valley food processors are installing biomass-fired systems to capture state renewable thermal incentives. Air quality non-attainment status in South San Francisco is blocking new gas-fired permits and driving electric steam generator deployments. Sacramento Valley dairy operations are adding redundant capacity to meet USDA Hazard Analysis Critical Control Point sanitation mandates.
Illinois
Chicago-area pharmaceutical headquarters are centralizing procurement specifications under multi-site master service agreements. Midwest dairy processing networks are consolidating vendor relationships as three operators control substantial regional steam capacity. Rockford and Peoria manufacturing zones are upgrading heating systems during assembly plant modernization.
Pennsylvania
Marcellus shale infrastructure is accelerating fuel-switching investments across legacy coal and oil-fired installations. Pittsburgh and Philadelphia metropolitan pharmaceutical campuses are adopting modular skid-mounted units to bypass central plant construction. State emissions trading programs are elevating capital requirements for boiler upgrades and replacements.
US Industrial Boiler Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular and hydrogen-ready platforms to capture decarbonization incentives. The vendor base spans integrated manufacturers with national service networks and specialized fabricators focused on pressure vessel design. Three archetypes dominate: full-service providers anchoring long-term maintenance contracts, compact system specialists targeting footprint-constrained urban facilities, and rapid-start designers serving chemical processors seeking thermal efficiency gains. Consolidation through enterprise procurement agreements and geographic expansion of ASME-certified fabrication capacity represent the dominant competitive moves.
Among the named fabricators, Clayton Industries, Cleaver-Brooks, and Miura America exemplify distinct positioning within this structure. Clayton Industries represents the rapid-start specialization archetype for chemical processing applications. Cleaver-Brooks occupies a position as a full-service provider leveraging national coverage for maintenance contract anchoring. Miura America exemplifies the compact modular system approach targeting urban pharmaceutical and food campuses where land constraints block conventional boiler house construction.
| Leading Market Players |
|---|
| Clayton Industries |
| Unilux Advanced Manufacturing |
| Cleaver-Brooks |
| Hurst Boiler & Welding |
| Fulton Companies |
| Babcock & Wilcox Enterprises |
| Velocity Boiler Works |
| ECR International |
| Miura America |
| Others |
Supply Flow & Price Mechanics
Modular once-through steam generator adoption simultaneously compresses installed cost economics and concentrates fabrication demand among ASME-certified pressure vessel shops with rapid-turnaround capability. This technology transition elevates pricing power for qualified fabricators while squeezing margins on conventional fire-tube commoditized units.
Pricing Analysis
Volume placements concentrate in standard fire-tube configurations where price competition intensifies among established fabricators; margin expansion accrues to compact modular and hydrogen-ready platforms commanding certification premiums. Price differentiation separates UL-listed rapid-start systems from conventional units across dairy and pharmaceutical procurement specifications. Pricing pressure stems from steel and specialty alloy input volatility compressing manufacturer quotations. Food processing networks exhibit highest price sensitivity through consolidated master service agreements; pharmaceutical campuses show lowest sensitivity where pure steam validation protocols override capital cost considerations.
Supply Chain Analysis
Refurbishment flows for pressure vessel components and burner retrofits extend asset life cycles while anchoring aftermarket revenue streams for national service networks. Manufacturing concentration clusters in the United States Gulf Coast and Great Lakes zones where ASME-certified fabrication capacity draws from regional steel mill supply chains. Raw material dependencies center on pressure vessel-grade stainless steel, nickel alloys for high-temperature tubing, and specialized burner control systems. Single-source vulnerability concentrates in ASME code welding certification pipelines failing to replace retiring skilled trades. Distribution runs through manufacturer-direct sales for large installations and regional distributor networks for standard unit replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME-certified boilermaker craft shortages prop pricing power for qualified fabricators capable of meeting compressed EPA compliance deadlines. Capacity bottlenecks in code-certified welding expertise sustain margin premiums across the analysis window.
For Market Incumbents: Lock in long-term maintenance contracts with multi-site food and pharmaceutical operators before modular specialists capture urban footprint-constrained opportunities. Anchor procurement relationships through predictive analytics service bundles that create switching costs. Defend against Miura America and Clayton Industries by expanding rapid-response field service density in Midwest dairy corridors where USDA sanitation mandates drive replacement urgency.
For New Entrants and Emerging Players: Footprint-constrained pharmaceutical campuses in Boston and Philadelphia metropolitan areas represent the most penetrable buyer archetype for skid-mounted modular deployment. Target California Central Valley food processors seeking biomass thermal solutions under state renewable portfolio standards. Capture early-mover positioning through hydrogen-ready burner platforms qualifying for California and New York decarbonization incentives.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated manufacturers seeking ASME-certified fabrication capacity and regional service network expansion. Long-term viability favors fabricators with backward integration into burner control systems and IoT-enabled predictive maintenance platforms. Watch EPA Maximum Achievable Control Technology deadline acceleration as inflection indicator for replacement cycle compression and consolidation momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| ASME-Certified Fabrication Capacity Expansion | Addresses boilermaker craft shortages compressing project timelines in Gulf Coast and Great Lakes zones. |
| Hydrogen-Ready Burner Platform Development | Captures California and New York utility incentives for 30% hydrogen blending capability. |
| Predictive Maintenance Analytics Integration | Opens recurring revenue streams through IoT-enabled tube leak detection and efficiency monitoring contracts. |
| Biomass Feedstock Supply Agreement | Secures agricultural residue chains for Central Valley renewable thermal installations under state incentives. |
| Multi-Site Master Service Agreement Consolidation | Centralizes procurement authority with corporate engineering headquarters across Midwest dairy networks. |
Methodological Framework
Independent corroboration across plant engineer interviews, OEM procurement team consultations, and aftermarket service head discussions underwrites the qualitative findings. Primary fieldwork engaged maintenance directors, facility engineering managers, and ASME code welding program administrators across Texas, Ohio, and California industrial corridors. Secondary validation drew from EPA enforcement and compliance databases, EIA industrial energy consumption surveys, and state renewable portfolio standard filings. Bottom-up unit placement tracking triangulates against top-down capacity expansion announcements from petrochemical and food processing operators.
Rate-of-change decomposition separates replacement cycle compression from new capacity additions across fuel type, pressure vessel architecture, and end-use application dimensions. The analytical framework models segment-level growth over the projection horizon through pressure rating tier, burner configuration, and emissions control technology stratification. CAGRs derive from installed base age profiling correlated with regulatory compliance deadline clustering. Forecast inputs incorporate pipeline infrastructure expansion timelines and state carbon pricing implementation schedules.
Revisions become necessary when EPA enforcement intensity shifts, natural gas price volatility exceeds historical bands, or ASME certification program throughput materially changes. Forecasts reflect documented assumptions regarding regulatory timeline adherence and infrastructure buildout pacing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Global Marine Boilers Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Advanced Utility Boilers Market
Boilers
Field Erected Boiler Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Gas Fired Boilers Market
Boilers
Germany Combined Heat and Power Market
Boilers
Combi Boiler Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Residential Boiler Market
Boilers
Commercial Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Industrial Boiler MRO Market