
 Asia-Pacific Power Plant Boiler Market | 2026-2036
Asia-Pacific Power Plant Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Power Plant Boiler Market Outlook
ASME Boiler and Pressure Vessel Code certification is redrawing competitive boundaries across the Asia-Pacific Power Plant Boiler Market. Bharat Heavy Electricals Limited leverages its captive forging and fabrication infrastructure to dominate domestic Indian tenders. Mitsubishi Heavy Industries anchors its position through advanced ultra-supercritical steam cycle technology leadership. Dongfang Electric Corporation sustains cost competitiveness via integrated boiler-turbine-generator manufacturing scale.
A power plant boiler is a closed vessel engineered to convert water into high-pressure steam through controlled combustion, operating at temperatures exceeding 540°C and pressures above 24 MPa in supercritical configurations to drive turbine-generators for electricity production. Water-tube designs command the largest installed base across utility-scale plants due to superior thermal efficiency and higher pressure tolerance, while supercritical units represent the fastest-growing technology tier as operators pursue heat-rate improvements and emission reductions. Pulverized fuel systems retain dominance in coal-dependent geographies, though natural gas-fired boilers are gaining share where pipeline infrastructure and carbon pricing alter fuel economics.
China's MEE enforces progressively tighter NOx and SOx emission limits that force boiler retrofits or replacements, while India's CEA mandates minimum efficiency standards under national electricity plans that reshape procurement specifications for utilities. Japan's METI promotes hydrogen cofiring roadmaps that will alter burner design requirements and material specifications for next-generation installations. Stakeholders must monitor which national regulators accelerate decarbonization timelines versus those prioritizing energy security through coal fleet extensions, as this divergence will determine regional technology mix and supplier competitive advantage.
Market Dynamics
Ultra-supercritical steam cycle technology is fragmenting procurement specifications across Southeast Asian utilities as operators balance efficiency mandates against capital constraints and fuel diversification pressures.
Growth Catalysts
- India's CEA Efficiency Mandates:Minimum boiler efficiency standards under national electricity plans force utility procurement toward advanced supercritical units, accelerating replacement cycles for aging subcritical installations.
- Coal-to-Gas Switching:Pipeline infrastructure expansion in Indonesia and Vietnam enables natural gas-fired boiler deployments that reduce carbon intensity while maintaining baseload reliability.
- China's Dual Carbon Goals:MEE emission limits tighten NOx and SOx thresholds, compelling retrofits and technology upgrades across provincial power generation fleets.
Market Restraints
- Specialized Alloy Supply Concentration:High-grade nickel-based superalloys for ultra-supercritical pressure components concentrate among limited forging suppliers, creating input bottlenecks and price volatility.
- Extended Certification Timelines:ASME Boiler and Pressure Vessel Code compliance requires 18-24 month qualification periods that delay project commissioning and strain working capital.
- Renewable Baseload Substitution:Grid-scale battery storage and pumped hydro projects in Australia and South Korea erode coal and gas boiler economics for mid-merit generation roles.
Strategic Opportunities
- Hydrogen Cofiring Infrastructure:Japan's METI hydrogen roadmap creates burner redesign demand and material specification shifts for next-generation installations capable of 30% hydrogen blending.
- Philippines Archipelago Electrification:Distributed power investments across island grids favor modular circulating fluidized bed boilers that accommodate variable coal quality and reduce transmission losses.
- Digital Twin Integration:AI-driven predictive maintenance platforms converge with boiler control systems to enable performance optimization contracts that shift revenue models toward outcomes.
Industry Challenges
- Welding Specialist Scarcity:Qualified technicians for thick-section pressure vessel fabrication remain concentrated in China and Japan, constraining localized manufacturing scale-up in Vietnam and Indonesia.
- Legacy Control System Integration:DCS retrofits for 1990s-era installations face protocol incompatibility with modern IIoT architectures, extending outage windows and commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Power Plant Boiler Market |
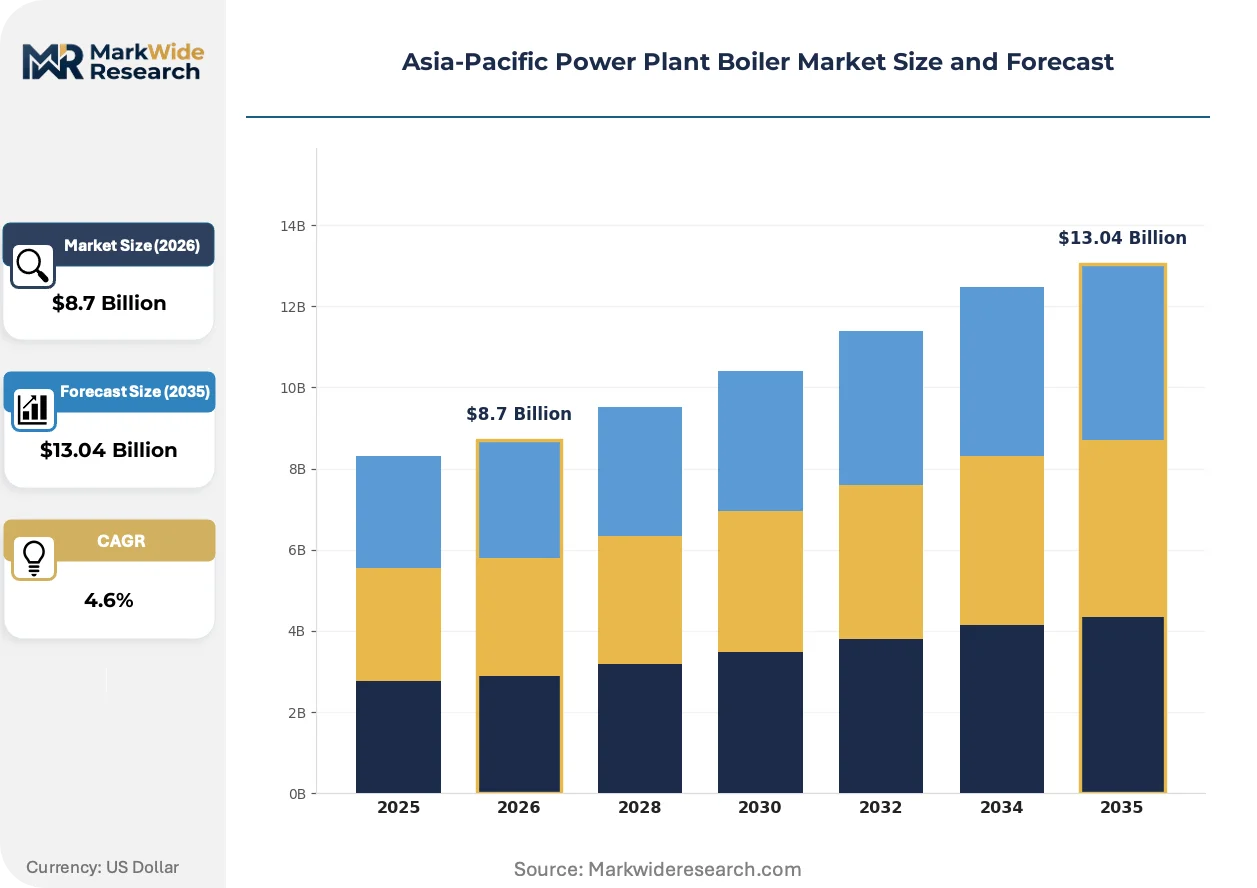
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boiler Type: Fire-Tube, Water-Tube, Supercritical, PulVerified Fuel Source: Coal, Natural Gas, Biomass, Oil Application: Power Generation, Industrial Usage, District Heating, Cogeneration End User: Utilities, Manufacturing, Petrochemicals, Others |
| Companies Covered | Bharat Heavy Electricals Limited, Mitsubishi Heavy Industries, Dongfang Electric Corporation, Siemens Energy, IHI Corporation, Harbin Electric Corporation, Doosan Heavy Industries & Construction, General Electric, Shanghai Electric, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Power Plant Boiler Market Strategic Shifts
Technology trajectories across the Asia-Pacific Power Plant Boiler Market center on thermal efficiency maximization, emission containment, and operational flexibility to accommodate variable renewable integration.
Advanced ultra-supercritical designs operating above 620°C and 31 MPa are fragmenting technology tiers as Chinese utilities pursue record heat rates while Southeast Asian operators prioritize cost-calibrated supercritical configurations. Indian power developers adopt these systems selectively based on coal quality and grid dispatch requirements. The technology divergence is compressing supplier R&D spreads and forcing regional product line specialization.
China's MEE progressively tightens particulate and mercury emission limits that mandate selective catalytic reduction retrofits and activated carbon injection systems for existing coal-fired units. Boiler OEMs must now bundle emission control packages with core steam generator sales. Indonesian and Vietnamese utilities face similar compliance trajectories as bilateral climate financing attaches environmental conditionality to project loans.
Long-term service agreements are displacing transactional spare parts procurement as Chinese IPPs and Indian state gencos seek guaranteed availability contracts. Dongfang Electric and Shanghai Electric anchor aftermarket revenue through 15-year operation and maintenance commitments. This behavioral shift concentrates supplier-customer relationships and raises switching costs for competing technology providers.
Asia-Pacific Power Plant Boiler Market Segmentation
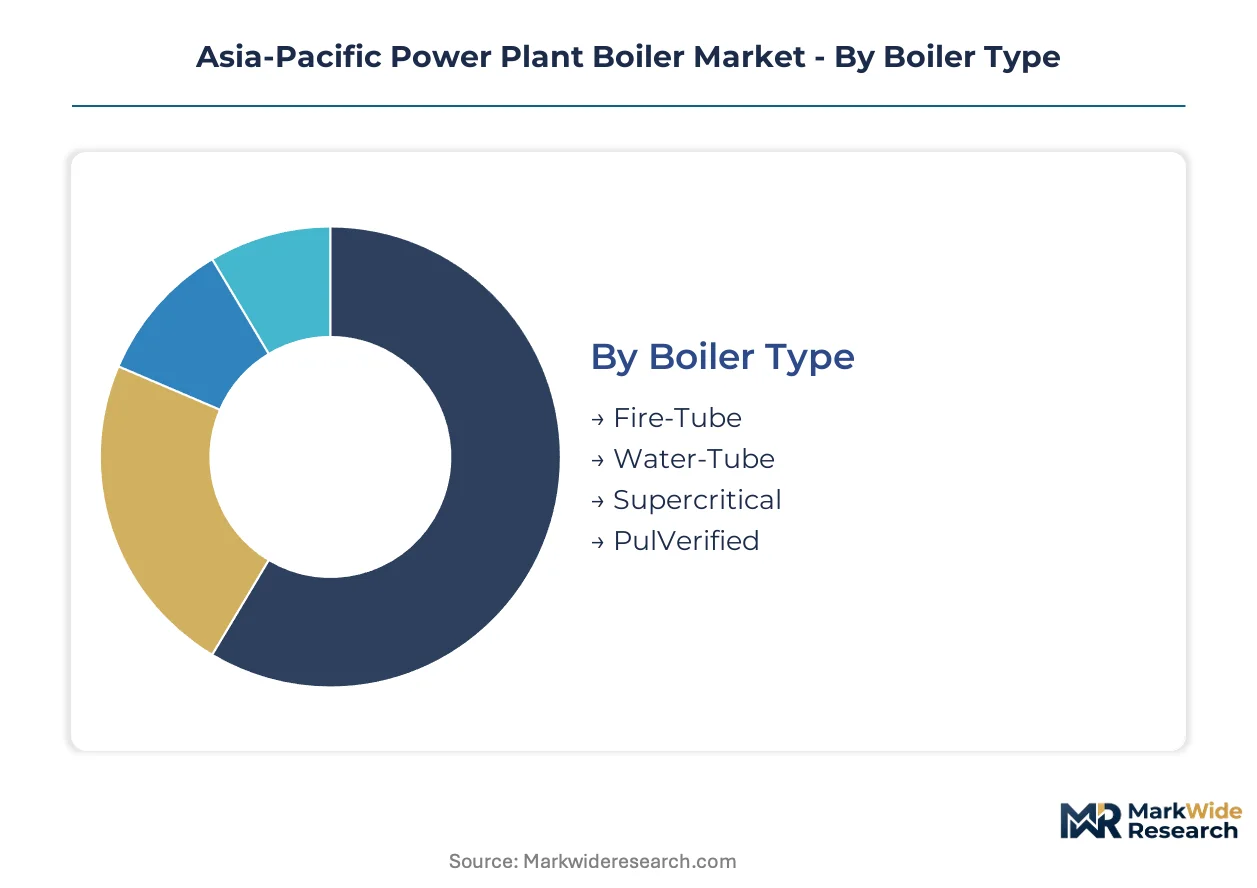
Technology differentiation across boiler configurations and fuel systems determines procurement specifications, capital intensity, and regulatory compliance pathways for power developers across the Asia-Pacific region. Segmentation reveals where efficiency mandates, fuel switching economics, and emission controls concentrate investment flows.
Boiler Type:
Water-tube designs face intensifying substitution pressure from supercritical units as utilities prioritize heat-rate improvements over conventional pressure vessel economics.
- Fire-Tube:Smaller-scale industrial installations employ these shell-and-tube configurations where steam demand remains below 20 bar pressure. Philippine island electrification projects specify compact fire-tube units for distributed baseload.
- Water-Tube:These configurations circulate water through heated tubes arranged in furnace walls, enabling operating pressures exceeding 160 bar for utility-scale generation. Indian state gencos dominate procurement for 500MW+ installations requiring rapid steam generation response.
- Supercritical:Operating above 22.1 MPa critical pressure eliminates phase separation, achieving thermal efficiencies above 42% through single-phase heat transfer. China's provincial utilities anchor regional demand as MEE emission limits force fleet upgrades.
- Pulverized Fuel:Coal grinding mills feed combustion chambers with micronized fuel for complete burnout and reduced unburned carbon. Indonesian mine-mouth plants specify these systems for low-rank coal combustion.
Water-tube configurations retain volume leadership across utility procurement; supercritical technology holds the steepest expansion curve as efficiency mandates tighten.
Fuel Source:
Cost tier stratification separates premium low-emission systems from baseline coal configurations as carbon pricing mechanisms penetrate regional energy markets.
- Coal:Sub-bituminous and bituminous firing systems retain installed base dominance across India, Indonesia, and Vietnam where domestic reserves anchor energy security strategies. CEA efficiency mandates force upgrades to supercritical pulverized coal units.
- Natural Gas:Combined-cycle configurations achieve sub-50% carbon intensity versus coal baselines where pipeline infrastructure reaches power plant sites. Vietnam's LNG terminal expansions enable gas-fired boiler deployments in the Mekong Delta.
- Biomass:Agricultural residue and energy crop combustion systems qualify for renewable energy certificates under Japan's feed-in tariff mechanisms. Thai sugar mill cogeneration facilities anchor regional demand for bagasse-fired units.
- Oil:Distillate and residual fuel oil systems provide peaking capacity and grid stabilization services where gas infrastructure remains undeveloped. Bangladesh grid operators specify dual-fuel oil-gas boilers for operational flexibility.
Coal retains procurement volume leadership across baseload capacity additions; natural gas climbs fastest as pipeline networks extend and emission pricing intensifies.
Application:
Customer type concentration varies sharply between centralized utilities seeking scale economies and industrial operators prioritizing thermal integration.
- Power Generation:Utility-scale installations exceeding 300MW dominate capital deployment across national grid interconnections. Chinese IPPs anchor regional investment through ultra-supercritical coal and gas-fired baseload units.
- Industrial Usage:Process steam supply for cement, steel, and paper manufacturing requires pressure configurations calibrated to thermal process requirements. Indian textile clusters in Gujarat specify medium-pressure boilers for dyeing operations.
- District Heating:Combined heat and power distribution networks serve urban heating loads in northern China and South Korean metropolitan areas. Seoul's district heating authority procures natural gas-fired boilers for seasonal peak shaving.
- Cogeneration:Simultaneous electricity and useful heat production achieves 80% system efficiency through backpressure and extraction turbine configurations. Thai industrial estates anchor regional demand for biomass cogeneration systems.
Power generation commands procurement volume leadership; cogeneration gains share fastest as industrial energy efficiency regulations tighten.
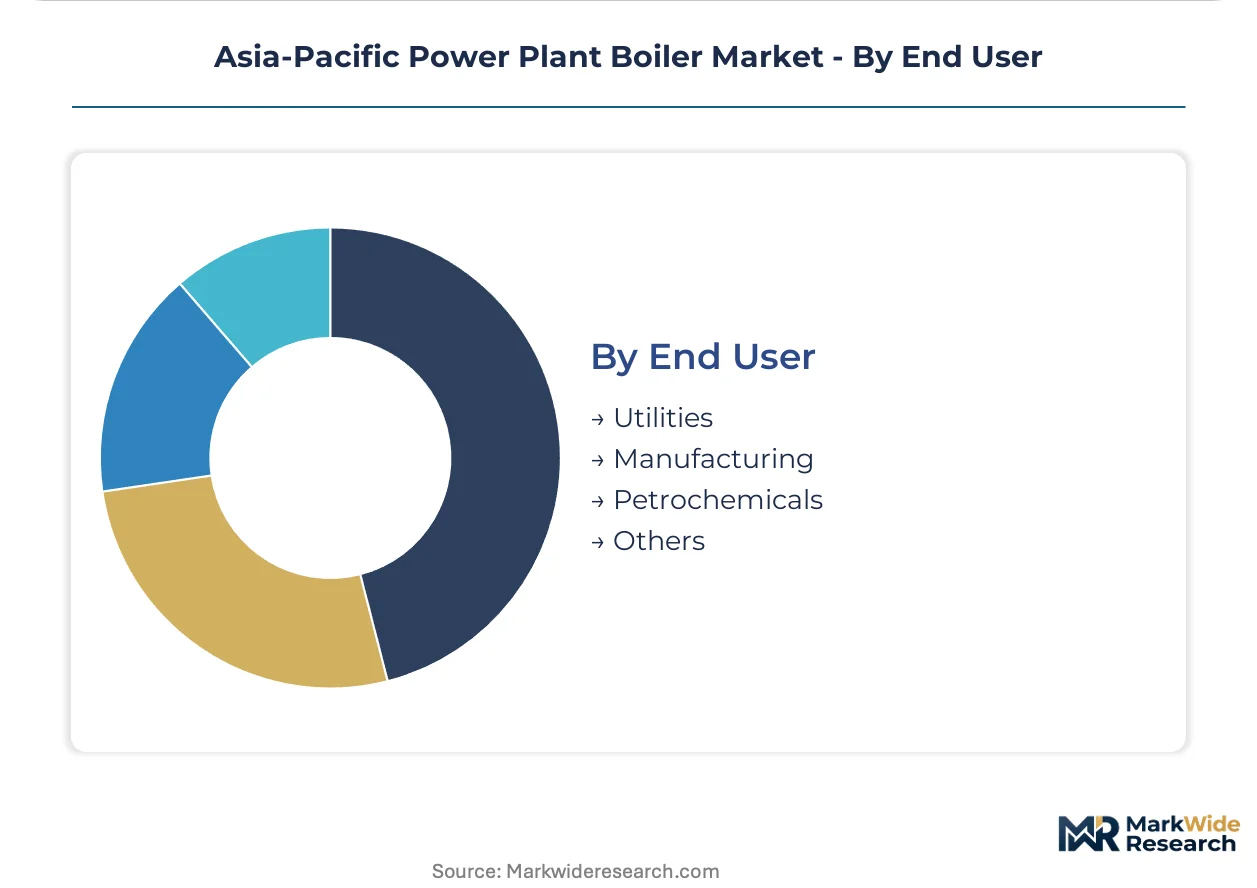
End User:
Supply concentration among forged pressure component suppliers creates tiered availability constraints across customer categories with diverging technical specifications.
- Utilities:State gencos and independent power producers operate grid-connected baseload and mid-merit capacity under regulatory cost-plus or competitive tariff frameworks. NTPC and China Huaneng Group anchor regional procurement volumes through multi-unit tenders.
- Manufacturing:Captive power plants supply process steam and electricity to industrial facilities with reliability requirements exceeding grid availability. Indonesian nickel smelters specify high-pressure boilers for ore processing thermal demands.
- Petrochemicals:Ethylene crackers and refinery complexes require superheated steam for fractionation and catalytic processes. Singapore's Jurong Island petrochemical cluster procures gas-fired boilers for process integration.
- Others:Commercial district cooling, desalination facilities, and agricultural processing operations specify smaller-scale configurations outside utility procurement frameworks. Philippine palm oil mills anchor demand for biomass-fired process steam systems.
Utilities retain volume leadership in boiler procurement; manufacturing sector demand expands most quickly as industrial electrification and captive power investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State gencos and independent power producers dominate procurement across Asia-Pacific, with procurement concentrated among utilities in China, India, and Indonesia seeking baseload capacity additions.
China
Provincial utilities anchor regional demand through ultra-supercritical coal and gas-fired baseload units. MEE emission limits tighten NOx and SOx thresholds, compelling retrofits and technology upgrades across provincial power generation fleets. The Yangtze River Delta concentrates manufacturing scale for pressure component forging and boiler-turbine-generator integration.
India
NTPC and state gencos drive procurement volumes through multi-unit tenders for 500MW+ installations. CEA mandates minimum boiler efficiency standards under national electricity plans, forcing utility procurement toward advanced supercritical units. Gujarat's industrial clusters specify medium-pressure boilers for captive textile processing operations.
Indonesia
Mine-mouth plants specify pulverized fuel systems for low-rank coal combustion across the archipelago. Pipeline infrastructure expansion enables natural gas-fired boiler deployments that reduce carbon intensity while maintaining baseload reliability. Nickel smelters in Sulawesi and Maluku specify high-pressure boilers for ore processing thermal demands.
Japan
METI promotes hydrogen cofiring roadmaps that alter burner design requirements and material specifications for next-generation installations. Combined heat and power distribution networks serve urban heating loads in metropolitan areas. Seoul's district heating authority procures natural gas-fired boilers for seasonal peak shaving.
Vietnam
LNG terminal expansions enable gas-fired boiler deployments in the Mekong Delta where pipeline infrastructure reaches power plant sites. Bilateral climate financing attaches environmental conditionality to project loans, mandating emission control packages. Distributed power investments across island grids favor modular circulating fluidized bed boilers.
Asia-Pacific Power Plant Boiler Market Competitive Environment
Player mix skews toward integrated boiler-turbine-generator manufacturers and specialized pressure component fabricators. Market structure concentrates around state-affiliated heavy electrical equipment producers with captive forging infrastructure and multinational industrial conglomerates with advanced ultra-supercritical technology portfolios. Three archetypes dominate: integrated domestic champions leveraging scale economies, technology-licensing joint ventures with regional engineering capabilities, and aftermarket service specialists anchoring long-term operation and maintenance contracts. Competitive moves center on backward integration into high-grade alloy forging and strategic partnerships for hydrogen cofiring burner development.
Among Asia-Pacific-based integrated manufacturers, Bharat Heavy Electricals Limited, Mitsubishi Heavy Industries, and Dongfang Electric Corporation exemplify the dominant competitive archetypes. Bharat Heavy Electricals Limited represents the state-affiliated domestic champion model with captive fabrication infrastructure. Mitsubishi Heavy Industries occupies a position as the technology leadership anchor through advanced steam cycle specialization. Dongfang Electric Corporation sits within the scale-driven tier via integrated boiler-turbine-generator manufacturing. These three entities collectively illustrate how geographic origin and corporate structure shape competitive positioning across procurement tender outcomes.
| Leading Market Players |
|---|
| Bharat Heavy Electricals Limited |
| Mitsubishi Heavy Industries |
| Dongfang Electric Corporation |
| Siemens Energy |
| IHI Corporation |
| Harbin Electric Corporation |
| Doosan Heavy Industries & Construction |
| General Electric |
| Shanghai Electric |
| Others |
Value Chain & Pricing Dynamics
ASME Boiler and Pressure Vessel Code certification gates both supply qualification and price differentiation simultaneously, creating tiered market access where uncertified fabricators compete on cost while certified suppliers capture premium utility contracts. This regulatory barrier concentrates pricing power among incumbent forge shops with existing code stamps while forcing new entrants into extended qualification timelines that compress their margins.
Pricing Analysis
Cost-plus contracts with nickel alloy indexation dominate utility procurement, insulating suppliers from raw material volatility while exposing them to efficiency penalties. Price differentiation rests on ASME certification tier and captive forging capability, with integrated manufacturers commanding premiums over pure fabricators. Cost compression in standard water-tube configurations is intensifying because Chinese OEMs are exporting excess capacity into Southeast Asian tenders. State gencos in India exhibit highest price sensitivity due to tariff-regulated procurement frameworks, while Japanese IPPs prioritize availability guarantees over unit cost.
Supply Chain Analysis
China and Japan anchor high-grade pressure component forging, with South Korean specialists supplying supercritical turbine rotors and India scaling welded fabrication for domestic content requirements. The supply chain draws from nickel-based superalloy ingots, heavy plate steel, and precision control system electronics. Single-source vulnerability concentrates in aerospace-grade alloy suppliers qualified for ultra-supercritical temperatures. Distribution runs through EPC contractors and utility direct procurement with long-lead scheduling tied to project financing milestones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive advantage through ASME certification barriers and decade-long customer relationships.
For Market Incumbents: Consolidate through backward integration into nickel alloy forging to secure input supply and capture margin pools currently leaking to specialty metal suppliers. Acquire welding specialist training programs in Vietnam and Indonesia to preempt emerging local fabrication capacity. Hydrogen cofiring burner development represents the critical R&D lever for next-generation contract retention. For New Entrants and Emerging Players: Differentiate on modular circulating fluidized bed designs for Philippine island electrification projects where logistics complexity disadvantages integrated OEMs. Target Indonesian nickel smelter captive power as the most penetrable segment, leveraging simpler pressure specifications than utility supercritical units. Partner with established forging houses for pressure component supply rather than replicating capital-intensive infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European boiler service specialists seeking Asia-Pacific platform expansion. Long-term viability hinges on hydrogen transition readiness and aftermarket service contract duration. Watch Japan's METI hydrogen blending timeline acceleration as the inflection signal for burner technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Captive supply of nickel-based superalloys insulates margins from commodity volatility and supplier concentration. |
| Hydrogen Cofiring Burner Development | Japan's METI roadmap mandates 30% hydrogen blending, requiring material specification shifts and redesign investment. |
| Long-Term Service Agreement Expansion | Chinese IPPs and Indian state gencos seek guaranteed availability contracts, concentrating supplier-customer relationships. |
| Modular CFB Product Line Investment | Philippine archipelago electrification favors distributed configurations accommodating variable coal quality. |
| Welding Specialist Training Programs | Qualified technicians for thick-section pressure vessels remain concentrated in China and Japan, constraining localized scale-up. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, EPC contractors, boiler OEM procurement teams, and aftermarket service heads; and secondary validation through IEA power generation databases, EIA international energy outlooks, FERC filings on technology imports, and national regulator emission standard publications. Bottom-up unit deployment tracking across the analysis window triangulated against top-down capacity investment forecasts from multilateral development bank project pipelines.
Across the projection horizon, the analytical framework modeled segmentation dimensions including boiler type, fuel source, application, and end-user category with regional regulatory framework overlays. CAGRs were derived from installed capacity retirement schedules superimposed on efficiency mandate compliance deadlines and fuel switching economics. Forecast inputs incorporated MEE emission limit trajectories, CEA boiler efficiency standards, and METI hydrogen roadmap milestones without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained coal fleet utilization or accelerated renewable substitution would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement consistency, alloy supply availability, and project financing access for baseload capacity additions. Recalibration cycles align with material shifts in national decarbonization timelines and bilateral climate financing conditionality.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Field Erected Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
North America Commercial Boiler Market
Boilers
Biomass Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
Superheater Market
Boilers
Watertube Boilers Market
Boilers
US Boiler Market
Boilers
Power Plant Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Utility Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
Advanced Utility Boilers Market
Boilers
Electric Boiler Market