
 Global Marine Boilers Market | 2026-2036
Global Marine Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marine Boilers Market Outlook
The OEM-to-fleet-direct channel is narrowing as shipyards consolidate procurement under long-term service agreements. Alfa Laval leverages its exhaust gas heat recovery portfolio to anchor retrofit demand across container fleets. SAACKE GmbH sustains burner system specialization in LNG-ready boiler architectures. Wärtsilä competes through integrated power-plant packages that bundle boilers with auxiliary engines.
Marine boilers are pressurized steam generators engineered to operate at temperatures exceeding 300°C and pressures above 60 bar, using fire-tube, water-tube, or composite configurations to convert fuel combustion into thermal energy for propulsion, power generation, and auxiliary heating aboard vessels. Water-tube designs dominate newbuild contracts above 50 MW thermal output due to higher pressure tolerance and faster steam ramp rates. Exhaust gas boilers represent the fastest-expanding product category as shipowners prioritize waste heat recovery to meet IMO efficiency mandates. By fuel type, LNG-fired systems command premium positioning amid sulfur cap compliance, while heavy fuel oil retains residual share in retrofit-constrained deep-sea tankers.
The International Maritime Organization enforces Energy Efficiency Existing Ship Index and Carbon Intensity Indicator standards that mandate boiler efficiency upgrades or vessel retirement for non-compliant fleets. ISO 8861 ventilation standards and classification society rules from Lloyd's Register and DNV govern boiler room safety and emissions certification. Stakeholders must weigh retrofit economics against newbuild LNG boiler commitments as regulatory thresholds tighten without grandfathering relief.
Market Dynamics
IMO 2023 carbon intensity regulations are forcing a binary choice between boiler retrofits and vessel retirement across aging commercial fleets, compressing decision timelines from years to months.
Growth Catalysts
- Energy Efficiency Existing Ship Index mandates:The IMO's EEXI standards require boiler efficiency upgrades for continued commercial operation, creating immediate replacement demand across container and tanker segments.
- LNG bunkering infrastructure expansion:Port facilities in Singapore, Rotterdam, and South Korea are scaling LNG availability, enabling dual-fuel boiler adoption without range anxiety.
- Water-tube boiler thermal output thresholds:Designs exceeding 50 MW now dominate newbuild contracts due to faster steam ramp rates and higher pressure tolerance for large vessels.
Market Restraints
- Specialized alloy input costs:Nickel and molybdenum price volatility directly impacts water-tube boiler fabrication economics, squeezing margins on fixed-price shipyard contracts.
- South Korean shipbuilding cluster concentration:Ulsan and Geoje districts control disproportionate newbuild boiler procurement, creating geographic supply risk from single-region dependency.
- Heavy fuel oil boiler residual lock-in:Deep-sea tankers face retrofit constraints from engine room spatial limitations, delaying LNG-ready conversions despite regulatory pressure.
Strategic Opportunities
- Brazilian offshore support vessel fleet:Pre-salt oil field expansion is driving demand for high-pressure auxiliary boilers in platform supply and crew transfer vessels.
- Exhaust gas heat recovery convergence:Integration of economizers with scrubber systems creates bundled efficiency solutions for IMO compliance without separate capital outlays.
- Long-term service agreement channel shift:Shipyard consolidation is opening direct fleet procurement relationships, bypassing traditional OEM distribution layers.
Industry Challenges
- Marine boiler welder certification scarcity:ASME Section IX qualified pressure vessel welders are in short supply across European and Asian repair yards, extending dry-dock timelines.
- Legacy control system integration:Digital boiler management platforms must interface with 1990s-era vessel automation architectures, requiring costly custom protocol bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marine Boilers Market |
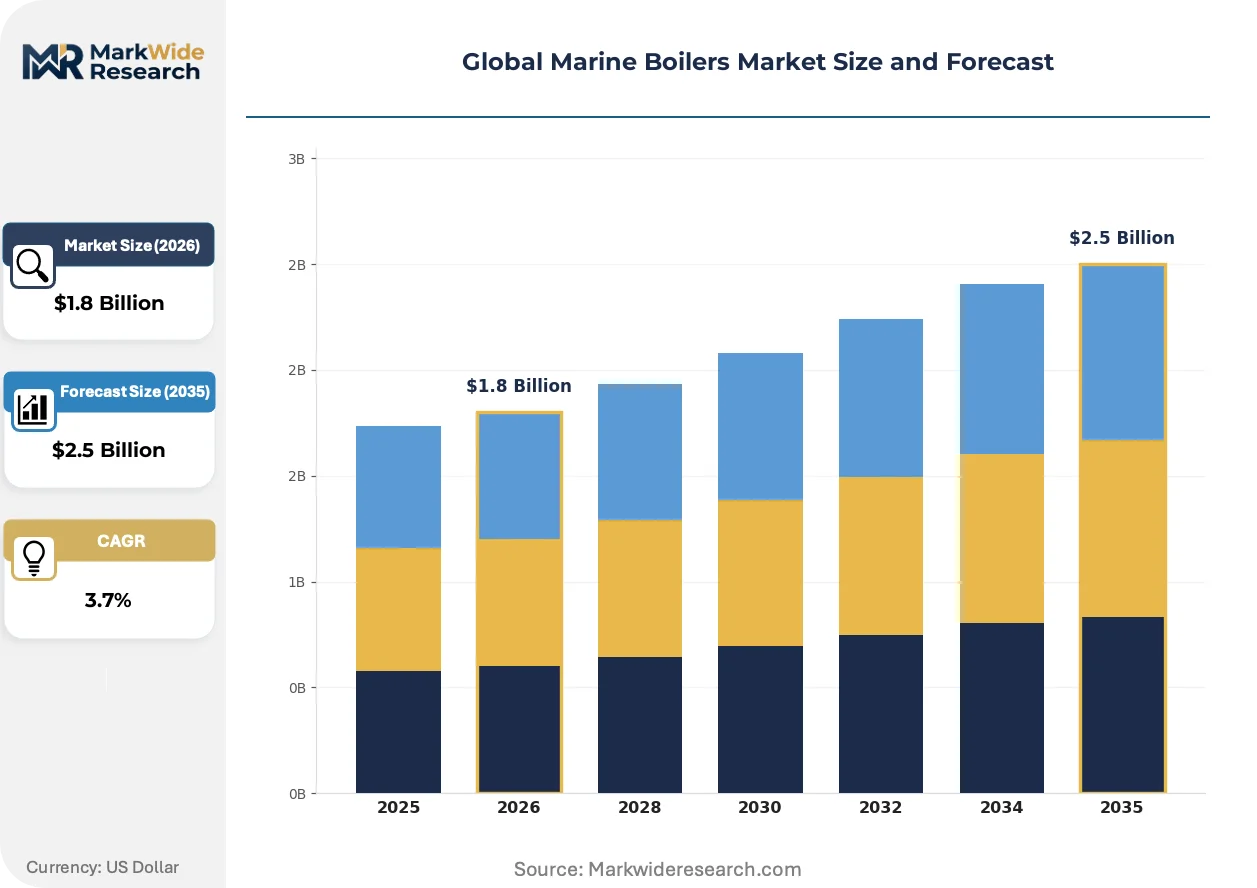
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube Boilers, Water-Tube Boilers, Composite Boilers, Exhaust Gas Boilers Industry Vertical: Commercial Shipping, Military Vessel, Offshore Platforms, Fishing Boats Fuel Type: Heavy Fuel Oil, Marine Diesel Oil, LNG, Biomass Application: Power Generation, Heating, Propulsion, Steam Production |
| Companies Covered | MAN Energy Solutions, SAACKE GmbH, Alfa Laval, Caterpillar Inc., Babcock International Group, Mitsubishi Heavy Industries, Kawasaki Heavy Industries, Dongfang Electric Corporation, Wärtsilä, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marine Boilers Market Strategic Shifts
Boiler technology trajectories are compressing around waste heat recovery and digital combustion control, with regulatory compliance now inseparable from product design rather than an aftermarket consideration.
Composite boiler architectures are collapsing the distinction between auxiliary and exhaust gas heat sources. These integrated systems simultaneously fire conventional fuels and capture engine waste heat, eliminating separate boiler footprints. Cruise operators and Ro-Ro fleets are specifying composite designs for newbuilds at accelerating rates. The technology is collapsing capex budgets by removing redundant auxiliary boiler installations while meeting EEDI Phase 3 requirements.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are reshaping marine boiler auxiliary systems. The regulation limits refrigerant options for steam-driven HVAC and refrigeration, forcing boiler-integrated heat pump redesigns. European ferry operators and refrigerated cargo fleets face the steepest compliance curves, with classification societies DNV and Lloyd's Register issuing updated certification protocols for low-GWP alternatives.
Shipowners are unbundling aftermarket service from initial equipment procurement. Container lines now negotiate boiler maintenance separately from newbuild contracts, favoring specialized service providers over OEM captive arrangements. This pattern is most pronounced in Singapore and Hamburg, where independent marine engineering firms have captured significant retrofit and spare parts volume from traditional supplier relationships.
Global Marine Boilers Market Segmentation
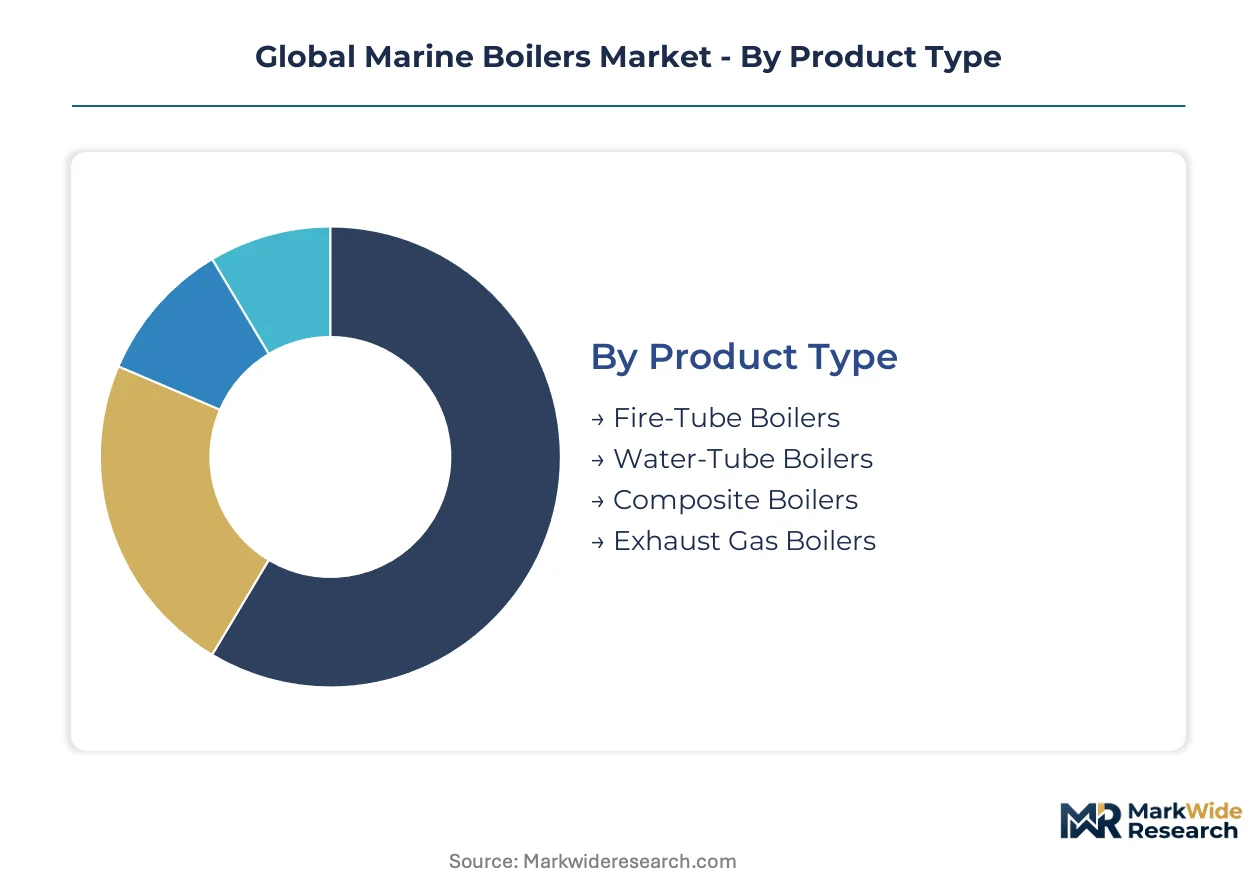
Marine boiler segmentation reveals divergent technology trajectories across vessel classes and regulatory environments. Product architecture, fuel chemistry, and operational duty cycles create distinct procurement patterns that suppliers must navigate simultaneously.
Product Type:
Mature fire-tube designs coexist with emerging composite architectures as shipyards balance proven reliability against IMO efficiency mandates.
- Water-Tube Boilers:These configurations route feedwater through high-pressure tubes surrounded by combustion gases, enabling thermal outputs exceeding 50 MW with rapid steam ramp rates. South Korean shipbuilding clusters around Ulsan and Geoje specify water-tube designs for newbuild container vessels above 15,000 TEU capacity, driven by EEDI Phase 3 compliance requirements and faster port turnaround schedules.
- Exhaust Gas Boilers:Heat recovery systems capture thermal energy from main engine exhaust streams without dedicated fuel combustion, operating at lower capital intensity than auxiliary-fired alternatives. Cruise operators and Ro-Ro fleets in Hamburg and Singapore are specifying exhaust gas economizers for retrofit programs, compelled by Carbon Intensity Indicator thresholds that reward waste heat utilization without bunker fuel consumption.
- Fire-Tube Boilers:Combustion gases pass through tubes immersed in water reservoirs, delivering lower pressure tolerance but simpler maintenance protocols suited to smaller auxiliary loads.
- Composite Boilers:Dual-source architectures integrate conventional firing with exhaust heat capture, eliminating redundant boiler footprints through single-unit multifunctionality.
Water-tube boilers handle the majority of throughput; exhaust gas boilers are expanding most quickly on share.
Industry Vertical:
Procurement patterns diverge sharply between scheduled-service commercial fleets and mission-driven military specifications.
- Commercial Shipping:Container lines, tanker operators, and bulk carriers constitute the dominant demand pool, with procurement decisions increasingly bundled under long-term service agreements rather than discrete equipment purchases. Singapore and Rotterdam port authorities are mandating LNG-ready boiler specifications for vessels calling under green shipping corridor agreements, accelerating dual-fuel adoption timelines.
- Offshore Platforms:Platform supply vessels and floating production installations require high-pressure auxiliary boilers for dynamic positioning and process heating. Brazilian pre-salt field expansion is driving demand for compact, high-reliability steam generators capable of sustained operation in harsh marine environments.
- Military Vessel:Naval specifications prioritize redundancy and damage tolerance over thermal efficiency, with procurement cycles detached from commercial regulatory pressures.
- Fishing Boats:Smaller vessel classes favor compact fire-tube or exhaust gas configurations with minimal crewing requirements for auxiliary machinery.
Commercial shipping commands the dominant procurement volume; offshore platforms are climbing the fastest as deepwater exploration accelerates.
Fuel Type:
Regulatory chemistry is forcing a binary transition between residual hydrocarbons and cryogenic methane across fleet segments.
- LNG:Liquefied natural gas firing eliminates sulfur oxide emissions and reduces carbon intensity versus oil-derived fuels, though requiring cryogenic storage and vaporization systems integrated with burner architecture. Singapore, Rotterdam, and South Korean bunkering terminals are scaling LNG availability, enabling dual-fuel boiler adoption without range constraints for Asia-Europe container routes.
- Heavy Fuel Oil:High-viscosity residual fuel retains installed base across deep-sea tankers where engine room spatial constraints block LNG storage retrofits, despite IMO sulfur cap compliance requiring scrubber co-installation or low-sulfur distillate blending.
- Marine Diesel Oil:Distillate fuels serve as pilot ignition sources for dual-fuel systems and primary fuel for smaller vessels without LNG infrastructure access.
- Biomass:Biofuel-compatible burner modifications are emerging for ferry operators in Baltic and North Sea jurisdictions with renewable fuel mandates.
Heavy fuel oil retains the largest installed base; LNG is gaining share fastest as bunkering infrastructure matures.
Application:
Duty cycle requirements separate continuous-baseload propulsion systems from intermittent auxiliary heating loads.
- Propulsion:Steam turbine propulsion has contracted to niche applications—LNG carriers with boil-off gas utilization and some naval vessel classes—where boiler reliability directly determines voyage completion. Mitsubishi Heavy Industries and Kawasaki Heavy Industries in Japan maintain specialized production lines for these high-integrity specifications.
- Steam Production:General-purpose steam supply for cargo heating, tank cleaning, and hotel services represents the broadest application category, with demand scaling directly against fleet tonnage and trading intensity.
- Power Generation:Auxiliary electrical generation via steam turbine or turboalternator sets serves vessels with high electrical load profiles including reefer containers and cruise hotel operations.
- Heating:Direct thermal applications—fuel oil heating, accommodation HVAC, and galley services—consume lower-pressure steam from auxiliary or composite boiler sources.
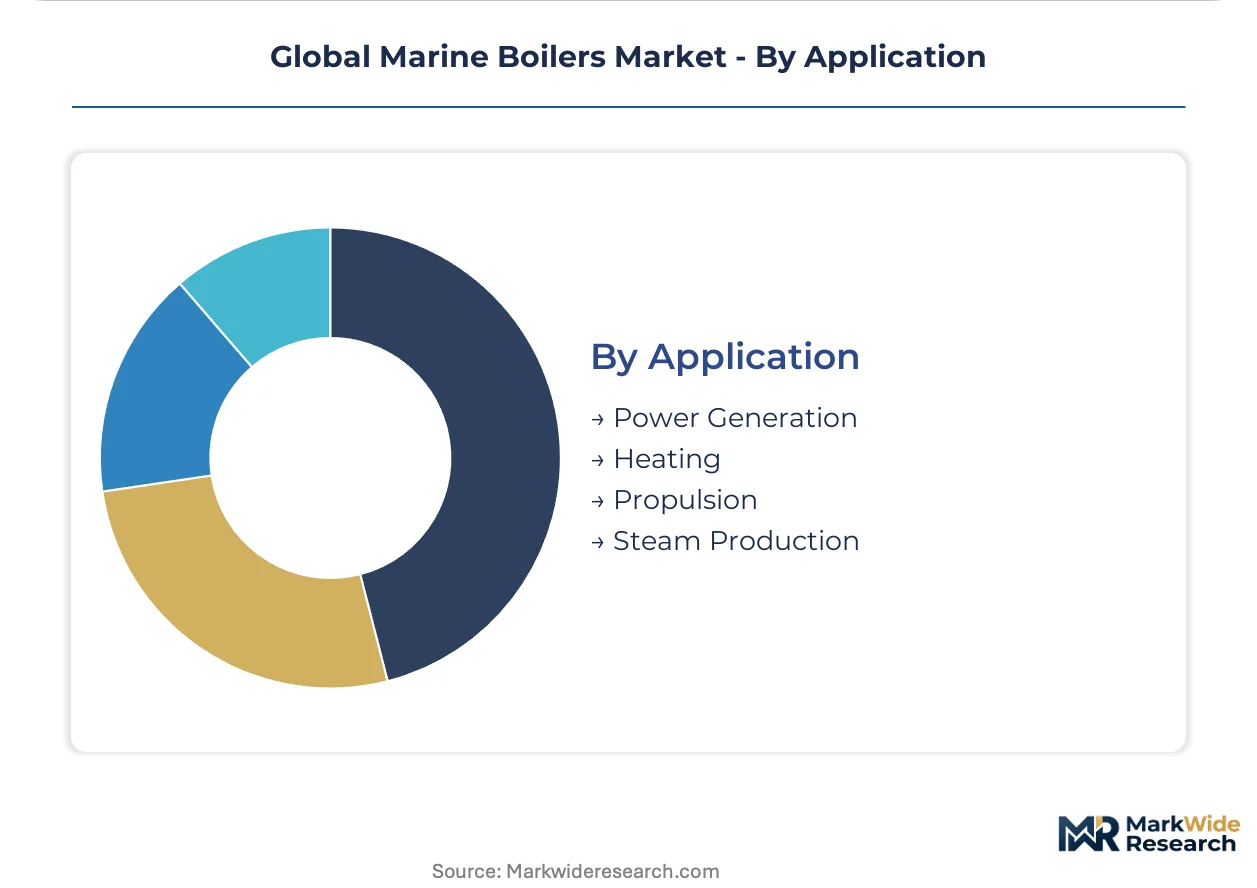
Steam production handles the majority of installed capacity; propulsion is contracting slowest as steam turbine niches persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Ministry of Trade, Industry and Energy anchors the dominant geography through shipbuilding cluster subsidies and EEDI compliance enforcement. Regulatory pressure from IMO carbon intensity standards concentrates procurement decisions in three East Asian manufacturing centers.
South Korea
Dual-fuel boiler retrofits and newbuild LNG-ready specifications drive procurement intensity. The Ministry of Oceans and Fisheries enforces green shipping corridor mandates for vessels calling at Busan and Incheon. Ulsan and Geoje districts concentrate fabrication capacity for water-tube designs exceeding 50 MW thermal output.
China
State-owned shipyard consolidation and domestic LNG bunkering network expansion accelerate boiler replacement cycles. The Ministry of Industry and Information Technology implements GB standards for marine equipment efficiency certification. Shanghai and Dalian port authorities mandate exhaust gas heat recovery installations for container vessels under environmental compliance protocols.
Japan
Steam turbine propulsion niches in LNG carriers sustain specialized boiler demand alongside cruise ship newbuilds. METI coordinates domestic shipbuilder technology roadmaps for EEDI Phase 3 alignment. Nagasaki and Kobe manufacturing bases retain production lines for high-integrity naval and commercial specifications.
Germany
EU F-Gas Regulation compliance forces heat pump integration redesigns in ferry and refrigerated cargo fleets. ECHA oversees refrigerant transition timelines affecting boiler-auxiliary system certification. Hamburg port engineering clusters capture unbundled aftermarket service contracts from traditional OEM arrangements.
Singapore
LNG bunkering infrastructure scaling enables dual-fuel boiler adoption without range constraints for Asia-Europe routes. The Maritime and Port Authority mandates green shipping corridor participation for registry vessels. Tuas port development concentrates retrofit engineering capacity for exhaust gas economizer installations.
Global Marine Boilers Market Competitive Environment
Integrated system bundlers and component specialists split the market along the fault line between turnkey power-plant packages and standalone boiler architectures. The vendor base concentrates around three strategic archetypes: exhaust gas heat recovery integrators, burner system specialists, and full-propulsion-package providers. Competitive positioning hardens through long-term service agreement capture and shipyard consolidation of procurement channels. Technology licensing and backward integration into alloy supply chains represent the dominant competitive moves.
Among European-based engineering groups, Alfa Laval and Wärtsilä exemplify divergent strategic positions within the integrated systems tier. SAACKE GmbH anchors the specialist archetype through sustained burner architecture focus. These three entities occupy distinct competitive territories without direct product overlap in the exhaust gas recovery, full power-plant bundling, and combustion subsystem domains.
| Leading Market Players |
|---|
| MAN Energy Solutions |
| SAACKE GmbH |
| Alfa Laval |
| Caterpillar Inc. |
| Babcock International Group |
| Mitsubishi Heavy Industries |
| Kawasaki Heavy Industries |
| Dongfang Electric Corporation |
| Wärtsilä |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese shipyard boiler fabrication is compressing margins across Asian supply bases and forcing Korean and Japanese suppliers into premium positioning strategies. This utilization asymmetry rewards integrated OEMs with captive alloy sourcing while squeezing standalone boiler specialists on fixed-price newbuild contracts.
Pricing Analysis
East Asian price spreads between South Korean and Chinese water-tube boiler quotations have widened as nickel-molybdenum alloy input costs diverge across regional supply bases. Three-tier pricing structure across IMO-certified premium, classification-standard, and non-certified economy levels separates Lloyd's Register-approved systems from yard-generic alternatives. Cost compression in the economy tier is intensifying because shipyard consolidation has eliminated smaller procurement channels. Container lines with bundled long-term service agreements exhibit lowest price sensitivity; independent fishing fleet operators face acute budget constraints.
Supply Chain Analysis
Export control regimes on advanced pressure-vessel welding equipment limit technology transfer to non-allied shipbuilding jurisdictions, constraining fabrication quality in emerging yards. Supply concentrates in South Korea, China, and Japan, with Ulsan and Geoje districts anchoring high-capacity water-tube production. Fabrication draws from nickel, molybdenum, and specialized chromium steel feedstocks. Single-source vulnerability from South Korean cluster dependency creates geographic concentration risk. Distribution runs through shipyard-direct procurement channels with long-term service agreement overlays displacing traditional OEM distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine boiler incumbents face substitution pressure from integrated power-plant packages that bundle boilers with auxiliary engines, threatening standalone boiler specialists with margin compression and channel displacement.
For Market Incumbents: Entrench through backward integration into nickel-molybdenum alloy supply chains and certification investment for IMO 2023 EEXI compliance. Capture shipyard-direct procurement relationships before bundled power-plant competitors consolidate channel control. Vertical integration into alloy sourcing defends margin position against raw material volatility. For New Entrants and Emerging Players: Establish a beachhead in Brazilian offshore support vessel auxiliary boilers where pre-salt field expansion outpaces incumbent service capacity. Target exhaust gas economizer retrofits for Hamburg and Singapore cruise operators facing Carbon Intensity Indicator thresholds. Lead with digital boiler management platforms that bridge legacy 1990s vessel automation without custom protocol development. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across LNG-ready dual-fuel boiler architectures as cryogenic storage integration expands equipment scope. Favor acquisition targets with ASME Section IX welding certification pipelines and established Lloyd's Register approval pathways. Watch for inflection when South Korean shipyard utilization crosses sustainable thresholds and triggers geographic sourcing diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel-molybdenum sourcing insulates margins from commodity volatility in water-tube fabrication. |
| Long-Term Service Agreement Capture | Direct fleet procurement relationships bypass traditional OEM distribution and lock in aftermarket revenue streams. |
| Digital Boiler Management Platform Launch | Protocol bridges to 1990s-era vessel automation reduce retrofit engineering costs for container fleet upgrades. |
| Composite Boiler Architecture Certification | Dual-source exhaust heat integration meets EEDI Phase 3 without redundant auxiliary boiler capital expenditure. |
| Brazilian Offshore Vessel Market Entry | Pre-salt field expansion drives demand for high-pressure auxiliary boilers in platform supply and crew transfer segments. |
Study Parameters
Desk research of Lloyd's Register classification databases, DNV maritime equipment registries, and IMO greenhouse gas strategy documentation preceded structured interviews with shipyard procurement directors, marine boiler OEM technical leads, and fleet engineering superintendents. Primary fieldwork across Ulsan, Geoje, Shanghai, and Hamburg clusters combined with customs trade data and shipbuilding orderbook analysis. Bottom-up vessel-level boiler specifications and top-down regional fleet composition estimates were triangulated for volume reconciliation.
Assumptions held fixed include IMO EEXI and CII enforcement timelines, LNG bunkering infrastructure buildout rates at Singapore and Rotterdam, and nickel-molybdenum price banding across the analysis window. Segmentation modeling covered product architecture, fuel chemistry, vessel class, and application duty cycle dimensions. CAGRs were derived from regression against fleet renewal rates and regulatory compliance deadlines, with exhaust gas boiler adoption curves and composite system penetration serving as primary forecast inputs.
Stress conditions across alloy price volatility, shipyard capacity utilization, and LNG bunkering network expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and classification society rule stability. Material shifts in IMO carbon intensity threshold stringency or grandfathering relief provisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Power Plant Boiler Market
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
District Heating Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Waste Heat Boiler Market
Boilers
Boiler Control Solutions Market
Boilers
Marine Boiler Burner Market
Boilers
Global Boiler Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Biomass Boiler Market
Boilers
Residential Boiler Market
Boilers
Superheater Tubes Market
Boilers
Germany Combined Heat and Power Market
Boilers
Europe Combined Heat and Power Market