
 Gas Fired Boilers Market | 2026-2036
Gas Fired Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Fired Boilers Market Analysis
Wholesale distribution through HVAC contractors is narrowing as direct-to-installer digital platforms gain share. Viessmann leverages its captive heat pump-gas hybrid portfolio to control specification channels across German-speaking Europe. Worcester Bosch anchors the UK replacement market through installer loyalty programs and same-day parts availability. Lochinvar specializes in stainless-steel fire-tube designs for commercial applications, competing on thermal efficiency rather than price.
Gas fired boilers are pressurized vessels that combust natural gas, propane, or biogas to transfer thermal energy to water or steam through fire-tube or water-tube configurations, operating at efficiencies ranging from 80% to 98% depending on condensing technology and return-water temperature management. These systems serve space heating, domestic hot water production, and process steam generation across residential, commercial, and industrial facilities. Industrial boilers dominate installed base value due to higher pressure ratings and custom engineering requirements, while modular boilers represent the fastest-expanding product category because of their redundancy benefits and part-load optimization in healthcare and hospitality applications. Natural gas retains the leading fuel position, though biogas-compatible burner retrofits are capturing margin pools in wastewater treatment and agricultural processing facilities seeking carbon intensity reductions.
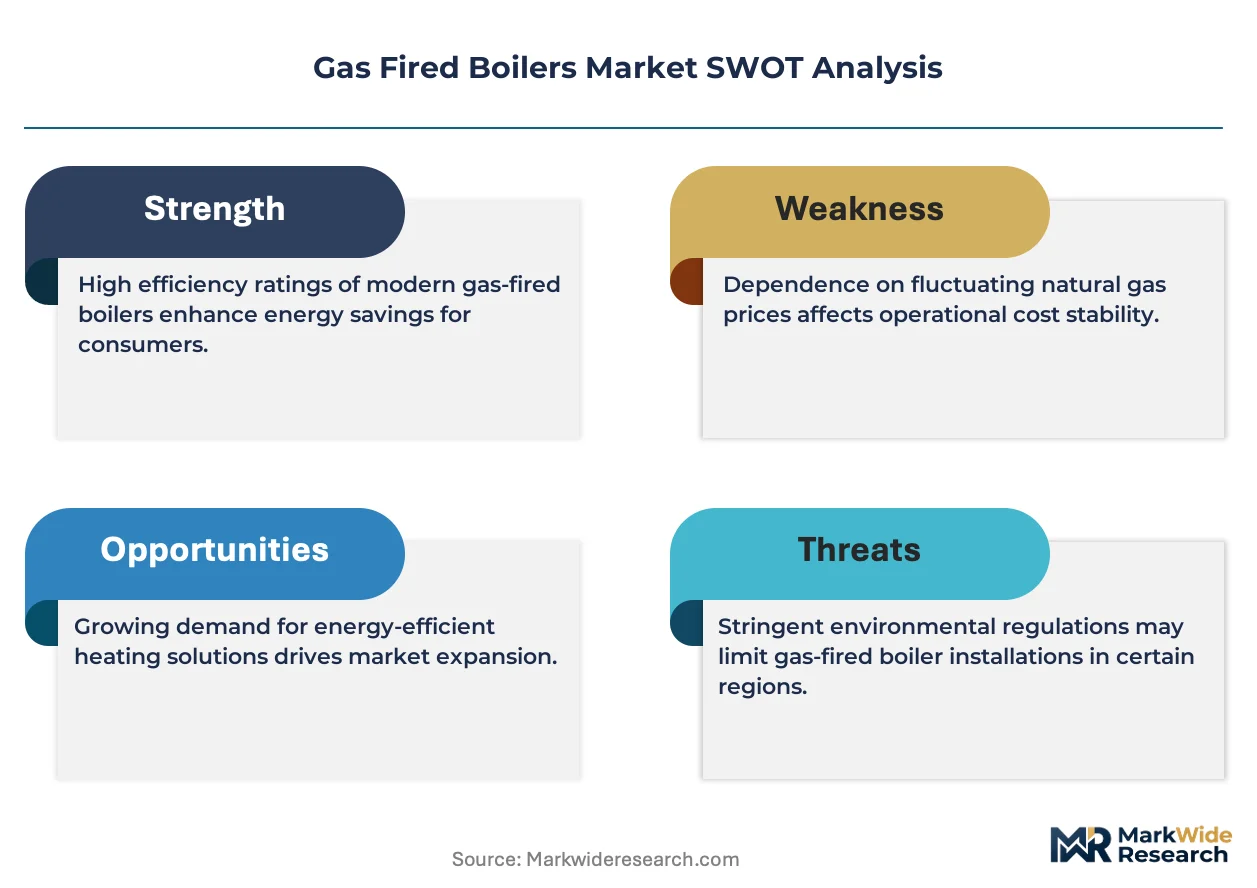
The US Department of Energy enforces minimum Annual Fuel Utilization Efficiency standards that effectively phase out non-condensing residential models, while the EU Ecodesign Directive and F-Gas Regulation push manufacturers toward lower NOx combustion and refrigerant-free hybrid configurations. China's GB standards for industrial boiler efficiency and emissions intensity reshape export qualification requirements for combustion component suppliers. Stakeholders must monitor how building electrification mandates in specific jurisdictions alter the economic viability of gas-only versus hybrid system investments.
Market Dynamics
The US Department of Energy's escalating Annual Fuel Utilization Efficiency thresholds are systematically eliminating non-condensing boiler architectures from residential channels, forcing combustion engineering investments toward modulating burner systems and low-temperature hydronic optimization.
Growth Catalysts
- German building retrofit mandates:The country's Energetische Sanierung requirements sustain replacement cycles across aging housing stock, creating predictable demand for high-efficiency condensing units integrated with district heating infrastructure.
- Modular boiler architectures:Healthcare and hospitality facilities adopt redundant, part-load optimized configurations to meet reliability requirements while minimizing standby losses during off-peak thermal demand periods.
- Biogas burner retrofits:Wastewater treatment and agricultural processing facilities deploy biogas-compatible combustion systems to satisfy carbon intensity reduction protocols while utilizing captive methane streams.
Market Restraints
- Stainless steel cost volatility:Fire-tube heat exchanger fabrication depends on austenitic steel grades subject to nickel and chromium price swings, compressing margins for premium efficiency product lines.
- Combustion component supply concentration:Precision burner assemblies and electronic control modules concentrate among German and Italian component specialists, creating single-source vulnerability for North American original equipment manufacturers.
- Building electrification substitution:Municipal heat pump mandates in Scandinavian municipalities and progressive US jurisdictions threaten gas-only system viability in new construction segments.
Strategic Opportunities
- Heat pump-gas hybrid configurations:The EU F-Gas Regulation's refrigerant phase-down creates specification openings for refrigerant-free bivalent systems combining gas backup with electric heat pump primacy.
- Direct-to-installer digital platforms:Contractor-facing e-procurement channels bypass traditional wholesale distribution, capturing margin pools through specification control and real-time inventory visibility.
- China's GB standard export alignment:Industrial boiler efficiency and emissions intensity requirements reshape qualification protocols for combustion component suppliers seeking access to municipal district heating retrofits.
Industry Challenges
- Condensing technology field commissioning:Low-temperature return water management and flue gas condensation drainage require specialized hydronic design expertise scarce among residential HVAC contractors.
- NOx certification timeline compression:The EU Ecodesign Directive's tightening nitrogen oxide limits force iterative burner development cycles, extending type-approval durations and delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Fired Boilers Market |
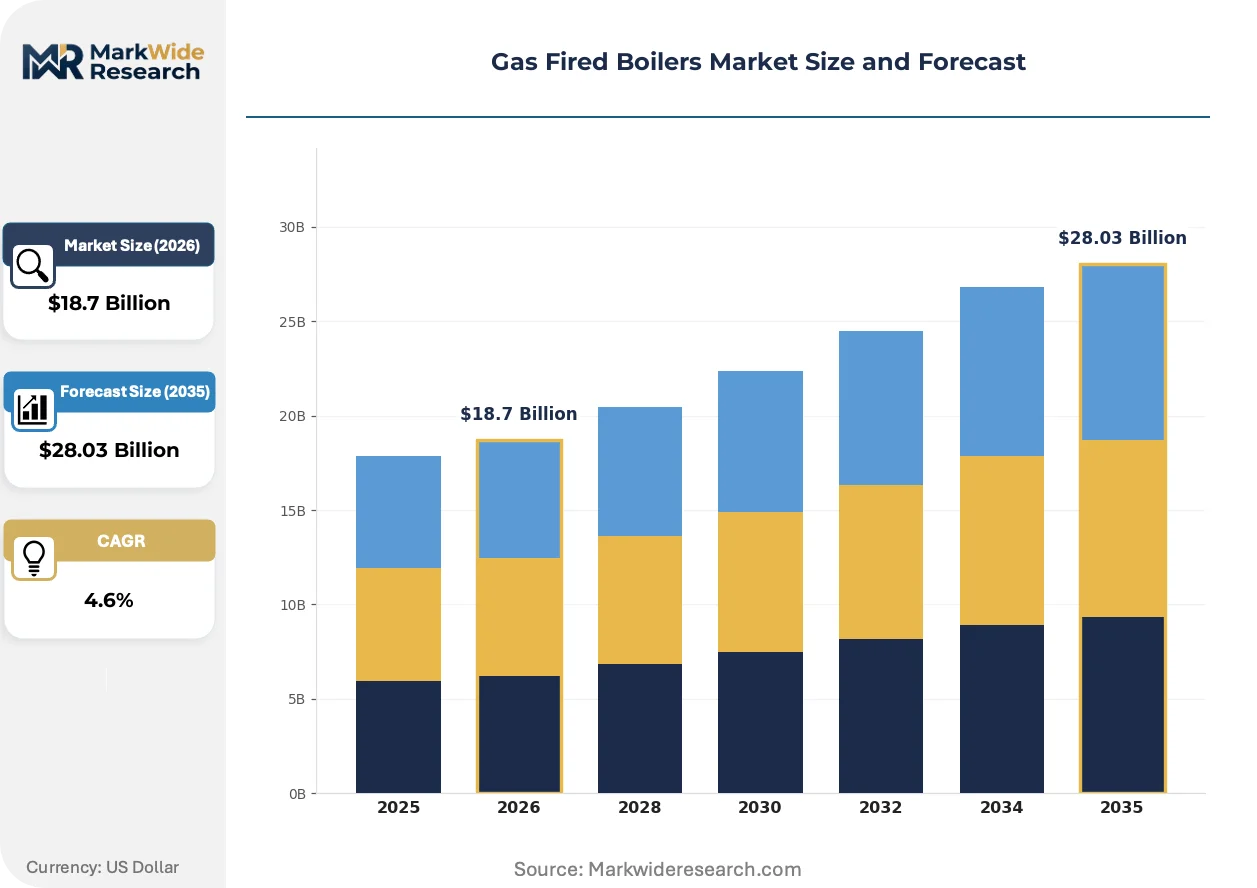
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Boilers, Commercial Boilers, Industrial Boilers, Modular Boilers Fuel Type: Natural Gas, Propane, Biogas, Others Installation Type: Wall-Mounted, Floor-Standing, Integrated Systems, Hybrid Systems End Use: Residential, Hospitality, Manufacturing, Healthcare |
| Companies Covered | Hurst Boiler and Welding Company, AERCO International, Viessmann, Thermal Solutions, Lochinvar, Worcester Bosch, Burnham Commercial, PB Heat, Ideal Boilers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Fired Boilers Market Emerging Trajectories
Combustion engineering is pivoting from standalone gas systems toward integrated thermal platforms, with digital specification channels and refrigerant-free hybrid architectures reshaping competitive positioning across residential and commercial segments.
Condensing fire-tube designs with extended heating surfaces and optimized water-side convection are rendering obsolete traditional cast-iron sectional boilers in sub-300 kW commercial applications. Regional healthcare networks and university campuses accelerate adoption to satisfy decarbonization commitments. This architectural shift compresses the addressable market for non-condensing atmospheric units while elevating stainless steel fabrication capabilities to competitive differentiator status.
The EU F-Gas Regulation's hydrofluorocarbon phase-down mandates are accelerating refrigerant-free hybrid system development across German-speaking markets. Manufacturers integrate gas-fired backup modules with air-source heat pump primacy to circumvent synthetic refrigerant dependency. Residential new construction in Austria and Switzerland now specifies these bivalent configurations as standard, forcing pure gas boiler suppliers toward auxiliary role positioning.
Installer loyalty programs and same-day parts availability networks are consolidating specification influence among national service organizations. Independent HVAC contractors in the UK and Ireland migrate toward manufacturer-captive procurement platforms offering technical training certification and priority logistics. This channel transformation disadvantages traditional wholesale distributors unable to deliver predictive maintenance analytics and digital submittal tools.
Gas Fired Boilers Market Segmentation
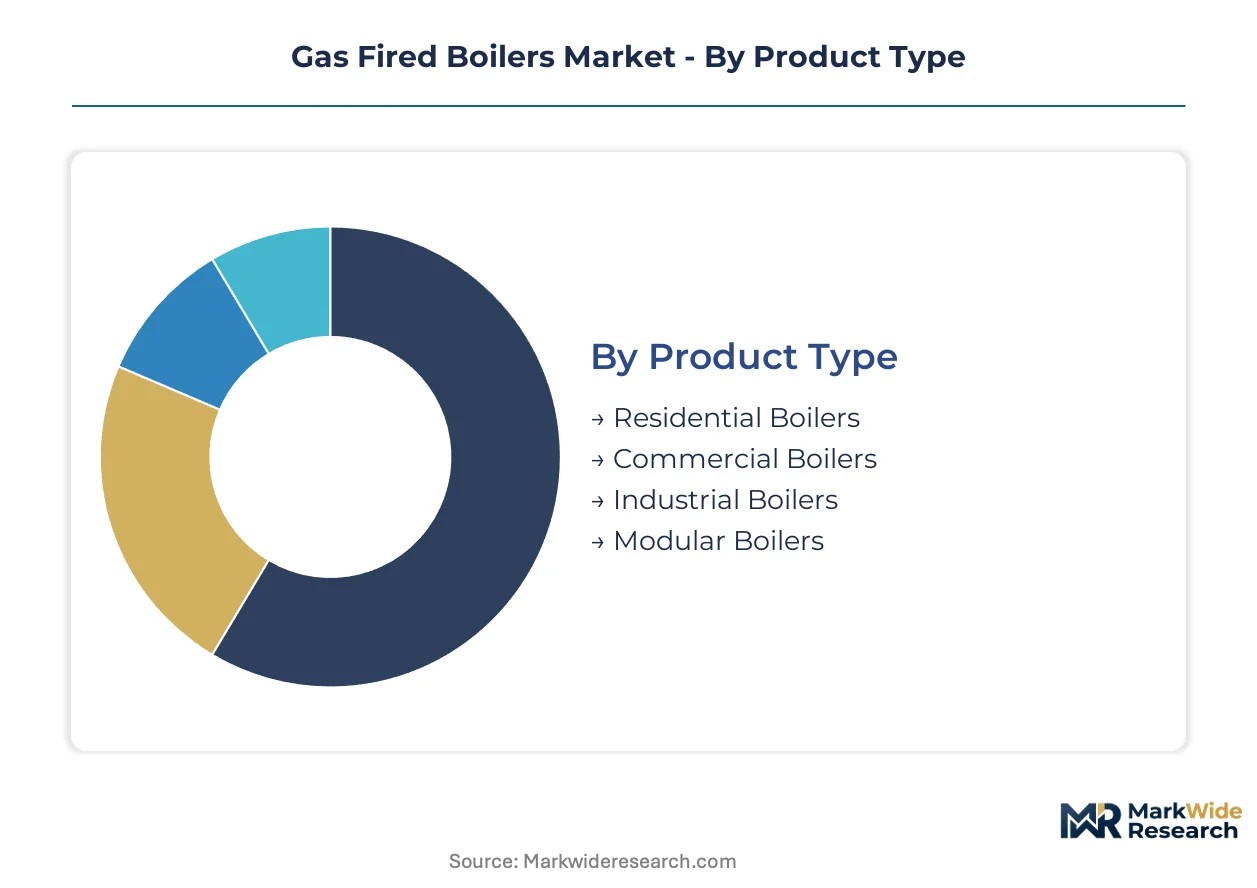
Segmentation in the Gas Fired Boilers Market reveals how thermal demand fragments across building typologies, fuel sources, and installation constraints. Product architecture and end-use requirements determine specification pathways, procurement channels, and service lifecycle economics.
Product Type:
Mature condensing architectures dominate residential and commercial channels, while emerging modular configurations address reliability-critical facilities.
- Industrial Boilers:High-pressure water-tube and fire-tube designs rated above 300 kW serve process steam generation and heavy manufacturing thermal loads. German chemical processing clusters and US Gulf Coast refineries sustain replacement demand for custom-engineered units with ASME certification requirements.
- Modular Boilers:Redundant, part-load optimized arrays of sub-150 kW modules enable healthcare and hospitality facilities to maintain thermal continuity during single-unit maintenance cycles. Healthcare networks in Austria and Switzerland specify these configurations for decarbonization compliance.
- Residential Boilers:Wall-hung and floor-standing condensing units dominate suburban North American housing stock replacement cycles.
- Commercial Boilers:Mid-range fire-tube designs serve office buildings, schools, and retail complexes with 80-300 kW thermal output requirements.
Industrial Boilers retain volume leadership; Modular Boilers hold the steepest expansion curve.
Fuel Type:
Supply concentration and infrastructure availability shape fuel selection across installation geographies.
- Natural Gas:Pipeline-distributed methane remains the baseline fuel for 80-98% efficiency condensing systems across North American and European installed bases. German district heating integration and US shale gas availability sustain dominant specification share.
- Biogas:Anaerobic digester output from agricultural processing and wastewater treatment facilities feeds carbon-neutral combustion retrofits. Danish agricultural cooperatives and Italian food processing plants deploy membrane-upgraded biogas in captive CHP configurations.
- Propane:Liquefied petroleum gas serves rural installations beyond natural gas pipeline reach, particularly in North American exurban markets.
- Others:Landfill gas and synthetic methane blends occupy niche applications in circular economy pilot projects.
Natural Gas commands installed base value; Biogas is gaining share fastest in carbon-constrained jurisdictions.
Installation Type:
Spatial constraints and system integration requirements drive specification divergence between replacement and new construction channels.
- Hybrid Systems:Bivalent configurations combining gas-fired backup with air-source heat pump primacy circumvent EU F-Gas Regulation refrigerant phase-down mandates. Austrian and Swiss residential new construction now specifies these as standard for sub-100 kW thermal loads.
- Wall-Mounted:Compact condensing units with polymer or stainless-steel heat exchangers maximize floor space efficiency in urban multi-family housing.
- Floor-Standing:Traditional cast-iron and steel designs persist in commercial replacement cycles where flue gas venting constraints limit condensing technology adoption.
- Integrated Systems:Factory-packaged boiler plants with pre-piped ancillary equipment reduce field commissioning complexity for institutional clients.
Floor-Standing units retain replacement market dominance; Hybrid Systems are climbing the fastest in new construction specifications.
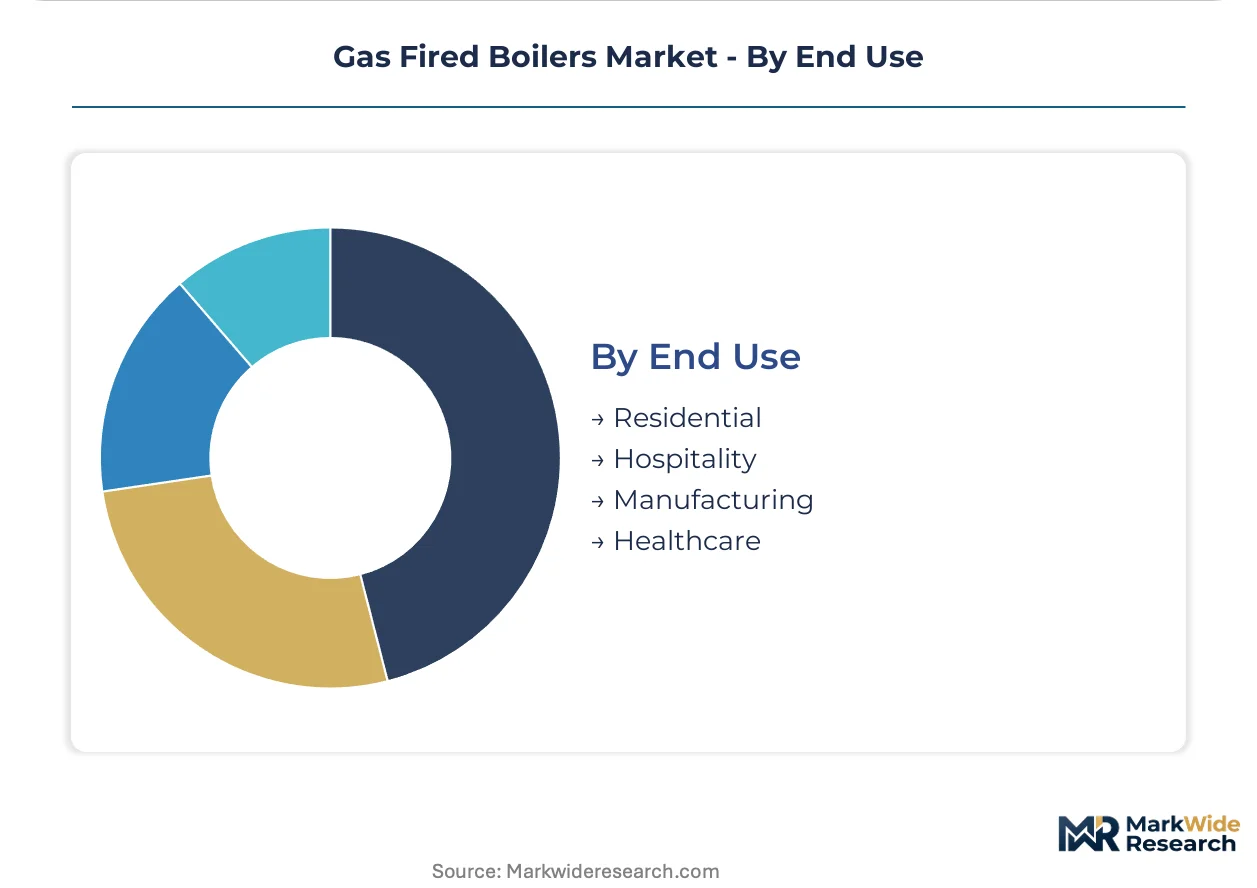
End Use:
Reliability requirements and carbon accounting protocols create distinct procurement behaviors across building typologies.
- Healthcare:Hospital thermal systems demand N+1 redundancy for patient safety compliance, driving premium specification of modular and dual-fuel configurations. German Klinikum networks and UK NHS trusts prioritize ISO 14001-certified suppliers with predictive maintenance contracts.
- Manufacturing:Process steam and direct-fired heating requirements in food processing, pharmaceuticals, and chemicals sustain industrial boiler demand. Bavarian automotive suppliers and Texas petrochemical facilities invest in high-pressure custom designs with SCR NOx reduction.
- Residential:Single-family and multi-family space heating dominates unit volume, with efficiency standards forcing condensing technology penetration.
- Hospitality:Hotels and resorts balance guest comfort reliability with sustainability marketing, creating demand for visible low-carbon thermal solutions.
Manufacturing retains value concentration; Healthcare is expanding most quickly in specification premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nord Stream pipeline network and Germany's district heating backbone anchor European thermal infrastructure demand for high-efficiency gas systems. Shale gas distribution networks across the Appalachian Basin sustain North American residential replacement cycles.
United States
Suburban residential construction in Texas and Florida drives condensing boiler retrofits as homeowners replace aging atmospheric units. The DOE's escalating AFUE thresholds eliminate non-condensing architectures from 2026 compliance windows. Houston's petrochemical corridor sustains industrial boiler demand for process steam in Gulf Coast refineries.
Germany
The Energetische Sanierung retrofit mandate creates predictable replacement demand across aging housing stock in North Rhine-Westphalia. The EU Ecodesign Directive's NOx limits force burner technology upgrades ahead of 2027 enforcement deadlines. Munich's Klinikum networks specify modular configurations for hospital thermal redundancy compliance.
China
Municipal district heating expansions in Beijing-Tianjin-Hebei reshape combustion component qualification under GB efficiency standards. The MEE's emissions intensity protocols accelerate industrial boiler upgrades in Shandong chemical clusters. Xi'an's aerospace manufacturing base sustains custom high-pressure water-tube demand.
United Kingdom
Installer loyalty programs consolidate specification influence across Greater London replacement markets. The Future Homes Standard threatens gas-only viability in new construction from 2025 implementation. Manchester's university campuses accelerate condensing fire-tube adoption for decarbonization commitments.
Switzerland
Bivalent heat pump-gas hybrid configurations dominate Austrian and Swiss residential new construction specifications. The EU F-Gas Regulation's refrigerant phase-down mandates refrigerant-free thermal platforms. Zurich's healthcare networks prioritize ISO 14001-certified suppliers with predictive maintenance contracts.
Gas Fired Boilers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling burner assemblies and electronic control modules. The vendor base organizes around three archetypes: captive heat pump-gas hybrid portfolio holders, stainless-steel fire-tube fabricators, and installer loyalty program operators. Consolidation pressures concentrate specification influence among national service organizations with same-day parts networks. Dominant competitive moves include direct-to-installer digital platform launches and captive hybrid system development circumventing refrigerant regulations.
Among German-speaking platform integrators, Viessmann exemplifies the captive hybrid portfolio archetype controlling specification channels across Austria and Switzerland. Worcester Bosch anchors UK replacement market positioning through installer-facing procurement platforms. Lochinvar occupies the stainless-steel fire-tube specialization tier for commercial thermal efficiency applications.
| Leading Market Players |
|---|
| Hurst Boiler and Welding Company |
| AERCO International |
| Viessmann |
| Thermal Solutions |
| Lochinvar |
| Worcester Bosch |
| Burnham Commercial |
| PB Heat |
| Ideal Boilers |
| Others |
Supply Flow & Price Mechanics
German and Italian burner assembly specialists concentrate precision combustion component supply, anchoring margin capture upstream while North American OEMs face procurement vulnerability. This concentration cascades into tiered pricing structures downstream, where specification control determines who retains value.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates stainless-steel condensing units from cast-iron atmospheric designs and entry-level wall-hung models. Price differentiation hinges on AFUE certification grade and after-sales service bundling, with ISO 14001-certified suppliers commanding specification premiums in healthcare and institutional channels. Cost compression in the standard tier is intensifying because nickel and chromium volatility squeezes fire-tube heat exchanger fabrication margins. Residential HVAC contractors exhibit highest price sensitivity, while hospital procurement committees prioritize thermal redundancy over unit economics.
Supply Chain Analysis
EU dual-use export controls on precision burner electronics limit technology flows to non-integrated third-country assemblers, reshaping qualification protocols. Component fabrication concentrates in Germany, Italy, and China, drawing from austenitic steel grades, silicon carbide ignition modules, and membrane-upgraded biogas conditioning systems. Single-source vulnerability in electronic control modules creates supply chain risk for North American boiler OEMs lacking captive burner engineering. Distribution runs through manufacturer-captive digital platforms and traditional HVAC wholesale channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building electrification mandates fragment demand across gas-only, hybrid, and full-electric thermal platforms, creating specification niches for differentiated system architectures.
For Market Incumbents: Entrench specification influence through captive heat pump-gas hybrid portfolios that circumvent EU F-Gas Regulation refrigerant phase-down mandates. Deepen backward integration into stainless-steel fire-tube fabrication to offset raw material cost volatility. Acquire regional service organizations with same-day parts networks to consolidate installer loyalty before digital platforms disintermediate wholesale distribution. For New Entrants and Emerging Players: Pursue biogas burner retrofit opportunities in Danish agricultural cooperatives and Italian food processing clusters where carbon intensity protocols drive captive CHP investment. Target modular boiler configurations for Austrian and Swiss healthcare networks seeking N+1 redundancy compliance. Lead with refrigerant-free bivalent system specifications in residential new construction channels where EU regulations disadvantage pure gas competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed HVAC platform aggregators consolidating regional service organizations across UK and German-speaking markets. Five-to-ten year viability depends on hybrid system development capabilities and district heating integration positioning. Monitor municipal heat pump mandate announcements in Scandinavian municipalities and progressive US jurisdictions as inflection indicators for gas-only asset impairment risk.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump-Gas Hybrid Development | Refrigerant-free bivalent configurations circumvent EU F-Gas Regulation phase-down mandates in German-speaking markets. |
| Direct-to-Installer Digital Platform Launch | Manufacturer-captive procurement channels bypass wholesale distribution and capture specification control through real-time inventory visibility. |
| Stainless-Steel Fabrication Backward Integration | In-house fire-tube production mitigates nickel and chromium price volatility compressing premium efficiency product margins. |
| Biogas Burner Retrofit Program | Membrane-upgraded biogas compatibility opens carbon-neutral specification pathways in wastewater treatment and agricultural processing. |
| Installer Loyalty Network Acquisition | Same-day parts availability and technical certification programs consolidate specification influence among national service organizations. |
Methodological Framework
A standing panel of boiler OEM product managers, HVAC contractor procurement leads, district heating utility planners, and combustion component engineering directors provided ongoing calibration throughout the study. Primary interview insights combined with secondary validation from DOE efficiency standard filings, EU Ecodesign Directive implementation reports, and GB standards documentation. Customs records for austenitic steel grades and burner assembly trade flows anchored supply-side triangulation against bottom-up demand modeling across residential, commercial, and industrial end-use segments.
Scenario-bracketing around building electrification mandate intensity and biogas infrastructure buildout rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, fuel type, installation configuration, and end-use reliability requirements. CAGRs derived from iterative convergence between top-down macroeconomic thermal demand indicators and bottom-up unit shipment analysis by efficiency tier and geographic regulatory cluster. Industrial boiler pressure ratings and modular redundancy specifications provided industry-specific forecast inputs.
Sensitivities concentrate around municipal heat pump mandate announcements, EU NOx limit enforcement timelines, and nickel price volatility affecting fire-tube fabrication economics. Forecasts reflect assumptions about district heating integration rates and biogas infrastructure maturity without presuming specific policy implementation schedules. Material shifts in building electrification regulatory trajectory or combustion component export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Marine Boiler Burner Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Power Plant Boiler Market
Boilers
Advanced Utility Boilers Market
Boilers
Industrial Biomass Boiler Market
Boilers
Watertube Boilers Market
Boilers
Boiler System Market
Boilers
North America Industrial Boiler Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Netherlands Combined Heat and Power Market
Boilers
GCC Electric Water Heater Market
Boilers
Fuel Operated Heaters Market
Boilers
Europe Residential Boiler Market
Boilers
US Boiler Market
Boilers
Middle East and Africa Power Plant Boiler Market