
 Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market | 2026-2036
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market Size, Share, and Industry Trends Forecast 2026-2036
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market Insights
The performance gap between premium supercritical CFBC systems and commodity subcritical units is broadening. Doosan Heavy Industries & Construction leverages its Korean manufacturing base to dominate large-scale power plant contracts. Babcock & Wilcox Enterprises anchors North American utility retrofits with its established emission control integration. ANDRITZ competes across European biomass co-firing projects where fuel flexibility commands premium positioning.
A circulating fluidized bed combustion boiler suspends fuel particles in an upward-flowing air stream, maintaining combustion temperatures between 800°C and 900°C to suppress thermal NOx formation while enabling sulfur capture via in-bed limestone injection. CFBC systems primarily serve power generation and industrial steam applications requiring fuel flexibility across coal ranks, biomass, and petroleum coke. The fuel type dimension shows coal retaining volume leadership while biomass segments attract margin premiums from European carbon pricing mechanisms. End user concentration in power generation reflects baseload capacity additions across emerging economies, though chemical manufacturing represents the fastest-growing application as process industries seek captive power with multi-fuel capability.
The US EPA enforces Maximum Achievable Control Technology standards that shape boiler emission architecture and retrofit timelines. China's MEE implements dual carbon goals that restrict new pulverized coal plants while permitting CFBC installations with biomass co-firing ratios above twenty percent. India's CEA mandates supercritical parameters for new thermal units above 660 MW, directly influencing technology selection criteria. Stakeholders must monitor regulatory divergence between emission intensity standards and fuel-flexibility incentives when configuring regional product portfolios.
Market Dynamics
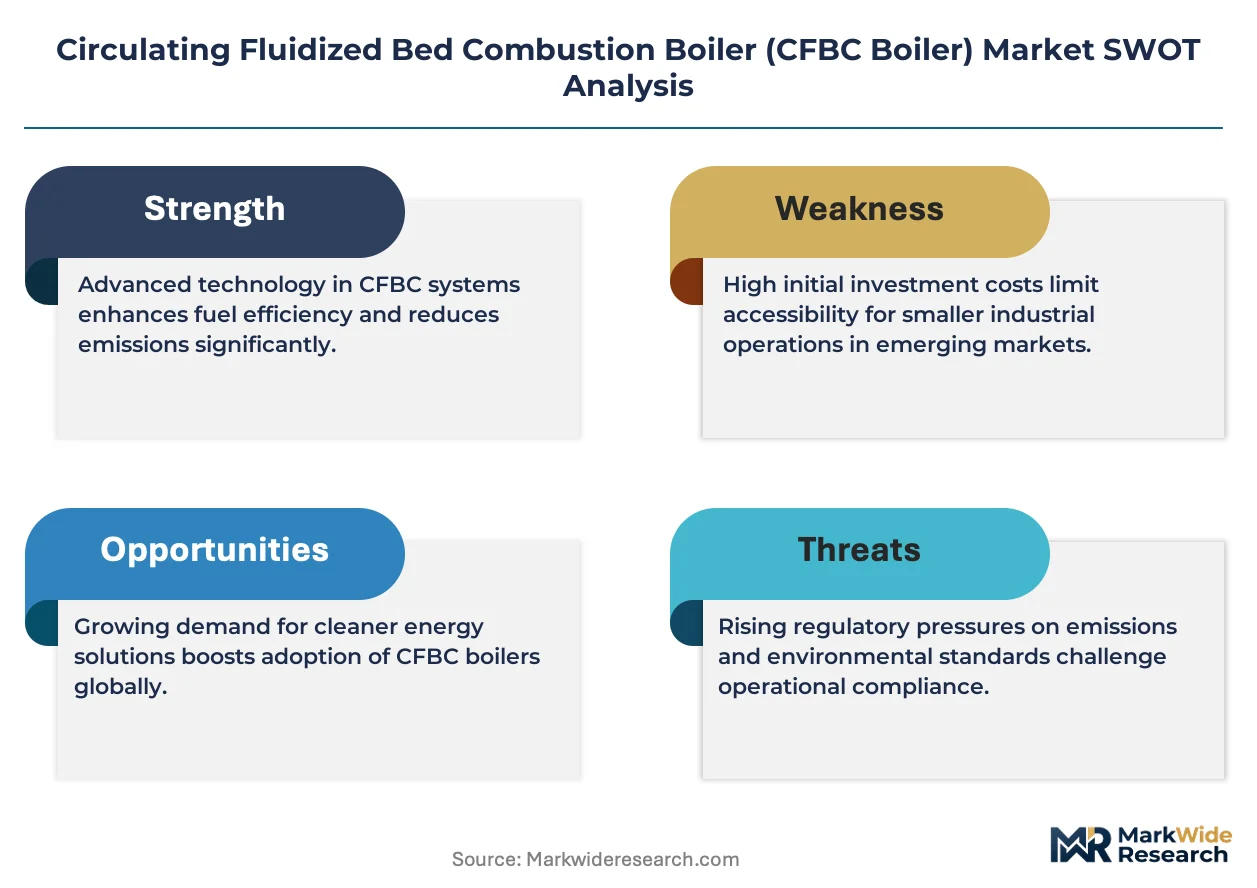
The CFBC boiler market faces intensifying pressure from emission intensity standards that favor fuel-flexible combustion architectures over conventional pulverized coal systems. India's Central Electricity Authority mandates supercritical parameters for new thermal units above 660 MW, while China's dual carbon goals restrict new pulverized coal plants and incentivize biomass co-firing ratios above twenty percent.
Growth Catalysts
- EU Green Deal emission benchmarks:Stricter NOx and SOx ceilings under the EU Green Deal force utilities across Germany, Poland, and Italy to retrofit existing plants with CFBC systems that enable in-bed limestone injection for sulfur capture.
- Petcoke firing in Indian cement and power:NTPC and state power boards favor CFBC technology for high-ash coal and petroleum coke combustion, creating sustained procurement volume from domestic manufacturing clusters in Gujarat and Tamil Nadu.
- Biomass co-firing mandates:China's Ministry of Ecology and Environment permits new CFBC installations with biomass co-firing ratios above twenty percent, accelerating technology upgrades in provincial power grids seeking carbon intensity reductions.
Market Restraints
- Refractory material cost volatility:High-alumina castables and silicon carbide tiles face price swings tied to bauxite and petroleum coke feedstock markets, squeezing project margins for EPC contractors in Southeast Asia.
- Critical component supply concentration:Cyclone separators and loop seal fabricators concentrate in South Korean and Chinese manufacturing bases, creating vulnerability for utilities in India and Indonesia seeking localized sourcing.
- Steam parameter limitations:Subcritical CFBC units cannot achieve the efficiency thresholds required by India's CEA mandates for units above 660 MW, segmenting the market into retrofit-only versus greenfield-suitable technology tiers.
Strategic Opportunities
- Indonesian archipelago captive power:Nickel smelting and palm oil processing facilities across Sulawesi and Kalimantan seek multi-fuel boilers capable of switching between low-rank coal and biomass residues.
- US EPA MACT retrofit wave:Maximum Achievable Control Technology standards for industrial boilers create replacement demand across chemical manufacturing and pulp-and-paper facilities in the Ohio River Valley.
- Supercritical CFBC technology convergence:Integration of once-through steam generators with circulating bed combustion is absorbing R&D investment from Korean and Japanese equipment suppliers targeting efficiency parity with ultrasupercritical pulverized coal.
Industry Challenges
- CFD modeling and combustion engineering talent scarcity:Computational fluid dynamics specialists capable of optimizing bed hydrodynamics for varying fuel mixes remain concentrated in European and East Asian engineering centers, constraining local project execution in emerging markets.
- Extended commissioning timelines:Cold commissioning and hot load testing for large-scale CFBC units require 18-24 month validation cycles, compressing revenue recognition and straining contractor working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market |
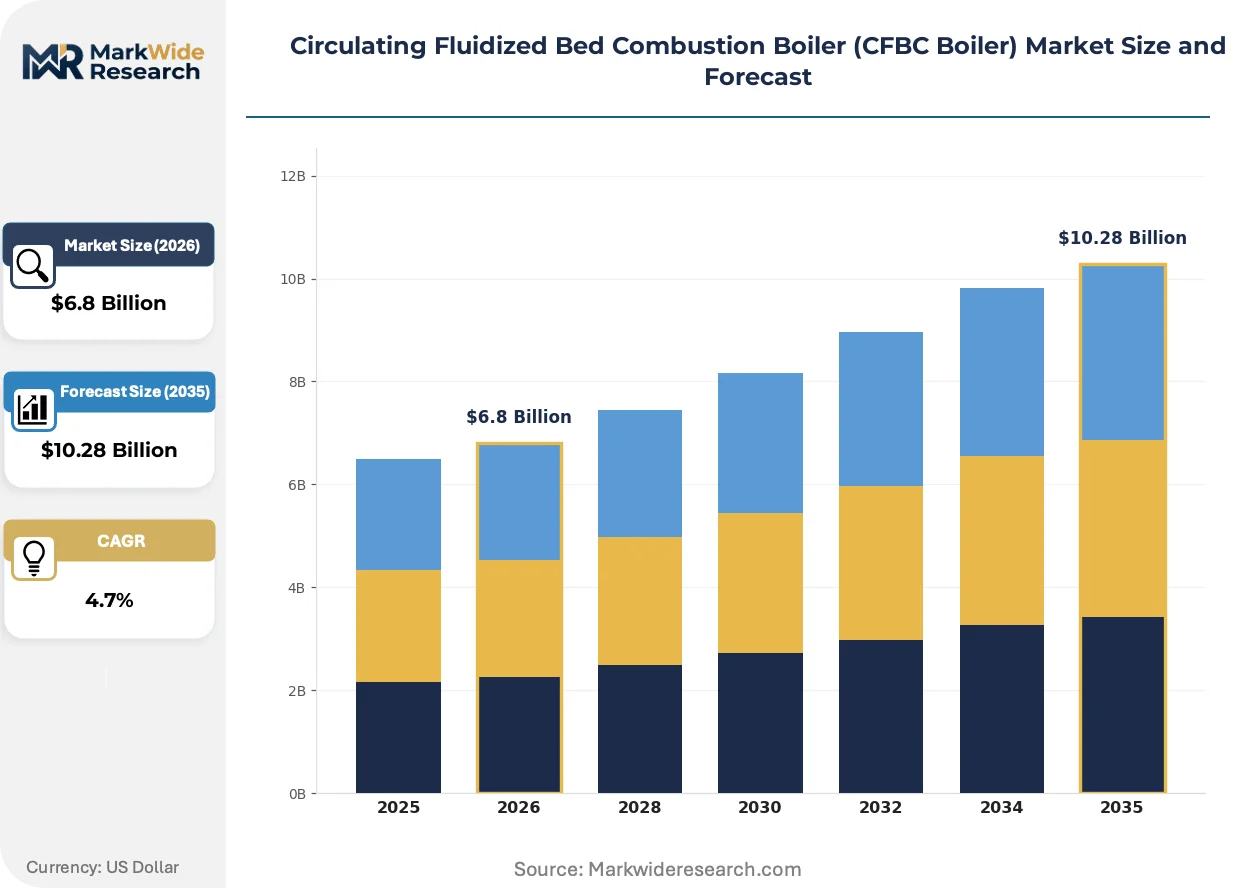
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Circulation, Double Circulation, Large Capacity, Modular Fuel Type: Coal, Biomass, Petcoke, Waste End User: Power Generation, Industrial Processes, Chemical Manufacturing, Oil Refining Technology: Combustion Control, Emission Control, Heat Recovery, Automation |
| Companies Covered | Doosan Heavy Industries & Construction, Zhengzhou Boiler Co. Ltd, Mitsubishi Heavy Industries Ltd, General Electric, ANDRITZ, Babcock & Wilcox Enterprises, Thermax Ltd, Valmet, Sumitomo Heavy Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market Trends and Innovations
Technology trajectories in the CFBC boiler sector center on elevating steam parameters while expanding fuel tolerance beyond design coal ranges. Equipment suppliers and utilities are co-developing combustion architectures that reconcile emission intensity targets with baseload reliability requirements.
Oxy-fuel CFBC combustion is absorbing capital allocation from European utilities pursuing carbon capture readiness. The technology recycles flue gas with oxygen enrichment to produce concentrated CO2 streams for sequestration. RWE and Uniper are piloting retrofits at lignite-fired stations in Germany. This configuration is absorbing the premium positioning previously reserved for integrated gasification combined cycle plants, compressing the cost gap between capture-ready and conventional thermal assets.
China's dual carbon goals under MEE oversight are mandating biomass co-firing ratios as a condition for new CFBC permitting. Provincial grid operators in Shandong and Inner Mongolia must demonstrate twenty percent biomass thermal input to secure construction approvals. This policy is forcing equipment suppliers to redesign fuel feeding systems and bed inventory management for highly variable biomass calorific values and moisture content.
Indian state power boards are consolidating procurement under framework agreements that bundle engineering, procurement, and construction with ten-year operations and maintenance contracts. NTPC's bulk tendering for 660 MW supercritical CFBC units is displacing fragmented, project-by-project vendor selection. This consolidation concentrates award decisions in New Delhi and Mumbai headquarters, marginalizing regional equipment distributors who previously influenced site-level specification.
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market Segmentation
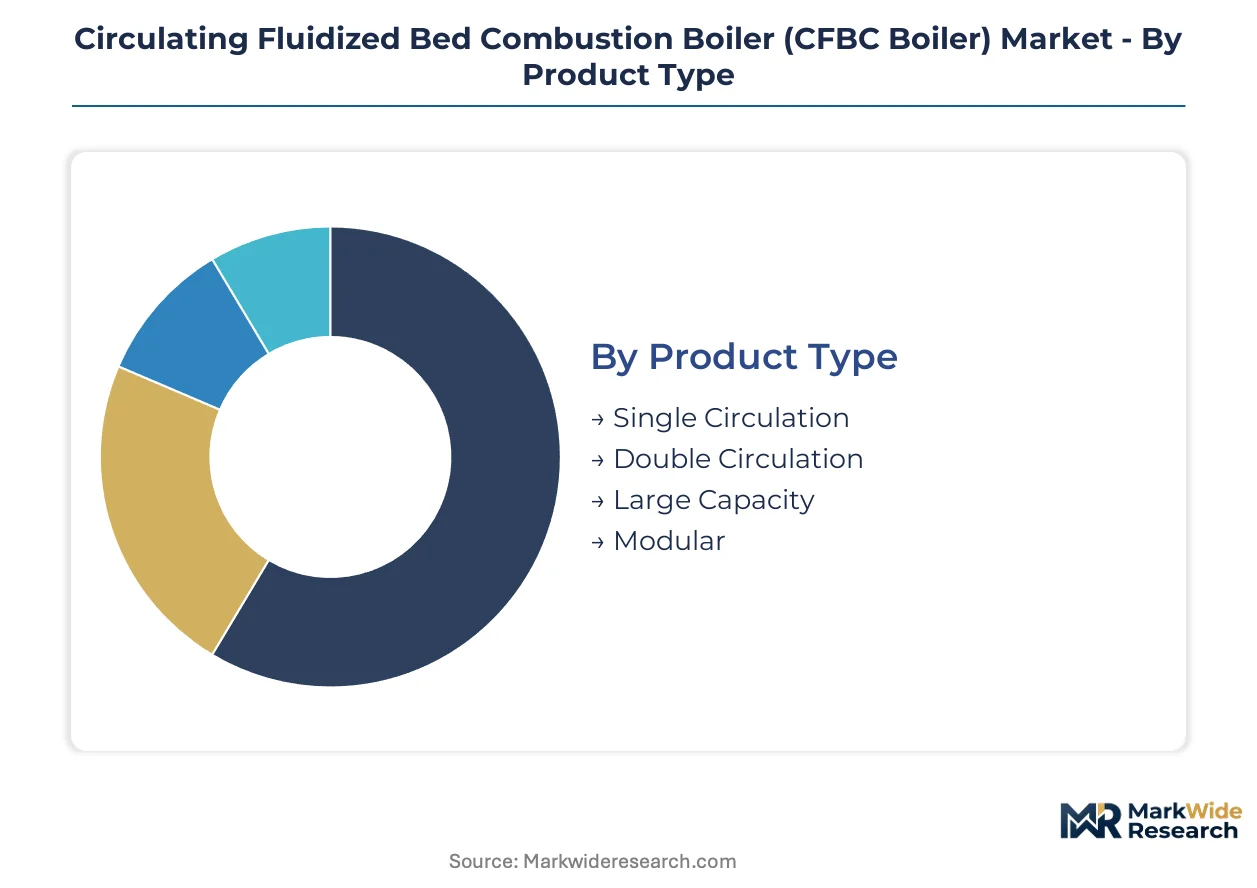
CFBC boiler procurement decisions pivot on fuel flexibility requirements, emission compliance thresholds, and steam parameter specifications. Technology selection varies sharply between baseload power utilities seeking supercritical efficiency and industrial operators prioritizing multi-fuel capability for captive generation.
Product Type:
Technology architecture determines project scale, capital intensity, and operational flexibility across deployment scenarios.
- Single Circulation:Compact design with one solids return loop from cyclone separator to furnace bed. Demand concentrates in Indian cement plants and Indonesian nickel smelters where space constraints and moderate steam loads dominate specifications.
- Double Circulation:Dual loop seal configuration enables higher solids flux density and improved combustion efficiency for high-ash coal firing. NTPC's 660 MW supercritical tenders specify this architecture for petroleum coke blending above 30 percent thermal input.
- Large Capacity:Units exceeding 300 MW electrical output requiring integrated once-through steam generators. Deployment tracks China's provincial grid expansion under MEE dual carbon permitting frameworks.
- Modular:Shop-fabricated sub-assemblies reducing field construction duration for remote industrial sites. Sulawesi palm oil processors and Kalimantan coal upgrading facilities favor rapid installation timelines.
Mature deployment sits with Single Circulation. Newer deployment is concentrated in Double Circulation.
Fuel Type:
Feedstock selection dictates bed inventory chemistry, limestone injection rates, and emission control system sizing.
- Coal:Retains volume leadership across high-ash Indian deposits and Indonesian low-rank reserves. CEA supercritical mandates for units above 660 MW preserve coal-fired baseload architecture despite carbon intensity pressures.
- Biomass:Agricultural residues and energy crops command margin premiums from EU carbon pricing mechanisms. Shandong and Inner Mongolia grid operators must demonstrate twenty percent biomass thermal input under MEE permitting conditions.
- Petcoke:High-sulfur petroleum coke firing requires enhanced limestone injection systems and modified cyclone refractory specifications. Gujarat cement clusters and Tamil Nadu power boards sustain procurement volume for this fuel category.
- Waste:Refuse-derived fuel and industrial waste streams demand specialized feeding systems and corrosion-resistant heat transfer surfaces. European waste-to-energy retrofits absorb limited but technically sophisticated project flow.
Volume concentration remains with Coal. Margin expansion is climbing the fastest in Biomass.
End User:
Application context shapes steam parameter requirements, load factor expectations, and fuel switching frequency.
- Power Generation:Baseload utilities require 85+ percent capacity factors with supercritical steam parameters. India's CEA mandates drive technology selection for NTPC and state power board procurement.
- Industrial Processes:Captive power for cement, steel, and textiles prioritizes fuel flexibility over peak efficiency. Gujarat and Tamil Nadu manufacturing clusters favor CFBC systems for petcoke and coal switching.
- Chemical Manufacturing:Process steam demand with high pressure and temperature stability requirements. This segment is expanding most quickly as specialty chemical producers seek multi-fuel captive generation.
- Oil Refining:Heavy residue and petcoke firing for refinery power and steam balances. Complex integration with delayed coking units limits vendor pool to specialized EPC contractors.
Procurement scale concentrates in Power Generation. Technology refresh is accelerating fastest in Chemical Manufacturing.
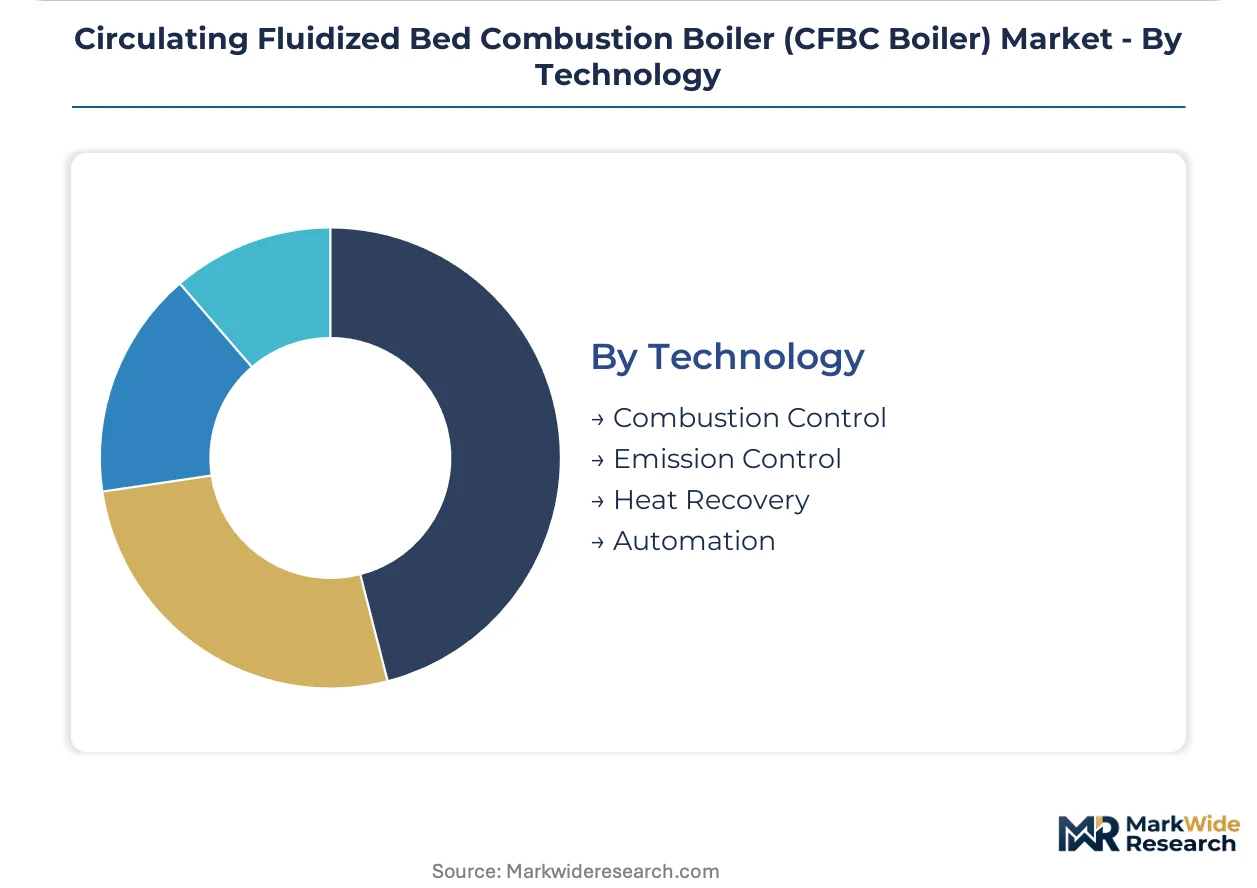
Technology:
Sub-system specialization determines emission compliance capability, operational automation, and maintenance intervals.
- Combustion Control:Bed temperature regulation through primary-secondary air staging and solids recirculation rate modulation. Essential for thermal NOx suppression below 200 mg/Nm3 without selective catalytic reduction.
- Emission Control:In-bed limestone injection for sulfur capture combined with fabric filters or electrostatic precipitators. EU Green Deal benchmarks force retrofit upgrades across German and Polish lignite stations.
- Heat Recovery:External heat exchangers and INTREX superheater configurations enabling supercritical steam parameters. Korean and Japanese suppliers concentrate R&D investment in this subsystem.
- Automation:Distributed control systems with bed hydrodynamics modeling and fuel feed optimization. Extended commissioning timelines of 18-24 months strain contractor working capital for complex automation integration.
Established deployment dominates Combustion Control. Investment flow is concentrating in Heat Recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors CFBC boiler manufacturing through Doosan Heavy Industries & Construction's fabrication complexes, supplying supercritical units across Southeast Asian power grids. Procurement clusters in India and Indonesia concentrate demand for high-ash coal flexibility.
China
Provincial grid operators in Shandong and Inner Mongolia drive biomass co-firing retrofits under MEE dual carbon permitting frameworks. The Ministry of Ecology and Environment mandates twenty percent biomass thermal input for new CFBC approvals. Equipment fabricators in Harbin and Shanghai redesign fuel feeding systems for variable agricultural residue calorific values.
India
NTPC's bulk tendering for 660 MW supercritical units concentrates procurement decisions in New Delhi and Mumbai headquarters. The Central Electricity Authority mandates supercritical parameters for thermal units above 660 MW. Gujarat cement clusters and Tamil Nadu power boards sustain petcoke-fired CFBC installations for captive generation.
United States
Chemical manufacturers and pulp-and-paper facilities in the Ohio River Valley face EPA Maximum Achievable Control Technology retrofit deadlines. The Environmental Protection Agency enforces emission standards that favor in-bed sulfur capture architectures. Engineering procurement contractors in Pittsburgh and Houston specialize in industrial boiler upgrades with emission control integration.
Indonesia
Nickel smelting operations across Sulawesi and Kalimantan seek multi-fuel boilers for low-rank coal and palm oil residue switching. Provincial energy regulators in East Kalimantan prioritize captive power for mineral processing investments. Palm oil processing clusters in Sumatra negotiate rapid-installation modular CFBC configurations.
Germany
RWE and Uniper pilot oxy-fuel CFBC retrofits at lignite-fired stations for carbon capture readiness. EU Green Deal emission benchmarks force NOx and SOx ceiling compliance across German utility fleets. Engineering centers in Düsseldorf and Munich concentrate computational fluid dynamics talent for combustion optimization.
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the CFBC boiler supply base. Korean and Japanese fabricators dominate large-scale supercritical manufacturing through integrated foundry and assembly operations. European specialists anchor emission control retrofits with combustion engineering expertise. Chinese boiler houses compete on modular configurations for remote industrial sites. Strategic moves concentrate on technology licensing partnerships and regional EPC consortium formation.
Among Korean integrated fabricators, Doosan Heavy Industries & Construction exemplifies the capital-intensive archetype with domestic manufacturing scale. Mitsubishi Heavy Industries Ltd and Sumitomo Heavy Industries Ltd represent Japanese engineering-led positioning through precision component supply. Babcock & Wilcox Enterprises occupies the North American retrofit specialist tier with emission control integration capabilities.
| Leading Market Players |
|---|
| Doosan Heavy Industries & Construction |
| Zhengzhou Boiler Co. Ltd |
| Mitsubishi Heavy Industries Ltd |
| General Electric |
| ANDRITZ |
| Babcock & Wilcox Enterprises |
| Thermax Ltd |
| Valmet |
| Sumitomo Heavy Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
High-alumina refractory castables move from bauxite extraction through South Korean fabrication to EPC contractor pricing tiers, with silicon carbide tile volatility transmitting directly to supercritical unit premiums and subcritical retrofit discounts downstream.
Pricing Analysis
Uptime-guarantee contracting anchors value-based pricing for CFBC systems, with Korean and Japanese suppliers commanding premiums for 85+ percent availability commitments against commodity fabricators offering equipment-only terms. Three-tier pricing structure across premium supercritical, standard subcritical, and economy modular configurations reflects steam parameter certification and after-sales bundling intensity. Cost compression in the economy tier is intensifying because Indonesian nickel smelters and Indian cement clusters prioritize rapid installation over efficiency optimization. State power boards in India and provincial grid operators in China exhibit lowest price sensitivity due to CEA and MEE mandates locking technology specifications.
Supply Chain Analysis
Dual-sourcing requirements from NTPC and Indonesian state utilities mandate qualified cyclone separator fabricators in both South Korea and China, eliminating single-country dependency for critical pressure-part components. Component manufacturing concentrates in South Korea, China, and Japan, with raw material feeds drawing from Australian bauxite, Chinese silicon metal, and Indian refractory clay deposits. Single-source vulnerability concentrates in loop seal and external heat exchanger fabrication where only two qualified suppliers exist globally. Distribution runs through EPC-led consortiums bundling engineering, procurement, and construction with decade-long operations contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into refractory material production and captive foundry capacity represents the dominant vertical-integration race, as equipment suppliers seek insulation from bauxite and petroleum coke feedstock volatility.
For Market Incumbents: To counter modular configuration entrants from Chinese boiler houses, Doosan Heavy Industries and Mitsubishi Heavy Industries should deepen in-house production of high-alumina castables and silicon carbide tiles while expanding supercritical certification investment for 660 MW-plus tenders. Cyclone separator supply concentration creates a vulnerability that incumbents can exploit through exclusive foundry partnerships.
For New Entrants and Emerging Players: Digital-channel engineering procurement platforms offer the lowest-friction entry path for remote Indonesian industrial sites seeking rapid-installation modular units. Sulawesi nickel smelters and Kalimantan coal upgrading facilities represent the most penetrable geography due to fragmented incumbent presence. Target biomass co-firing retrofit demand in Shandong and Inner Mongolia through technology licensing partnerships with established emission control integrators.
For Investors and Strategic Acquirers: NTPC's consolidation of procurement under framework agreements is the leading indicator that long-term viability rests on operations and maintenance contract bundling rather than equipment-only sales. Acquisition targets should emphasize EPC contractors with ten-year O&M capabilities and supercritical project execution track records. Watch for MEE permitting acceleration for biomass co-firing ratios above twenty percent as the inflection signal for technology refresh demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Production | In-house bauxite processing insulates Doosan and Mitsubishi from raw material cost swings. |
| Supercritical Certification Investment | CEA mandates for 660 MW units lock Korean and Japanese suppliers into premium positioning. |
| Biomass Co-firing Technology Licensing | MEE permitting frameworks in Shandong create recurring revenue from fuel system redesigns. |
| Modular Configuration Rapid Deployment | Indonesian nickel smelters in Sulawesi prioritize installation speed over efficiency optimization. |
| Long-term O&M Contract Bundling | NTPC's framework agreements displace fragmented vendor selection with decade-long service locks. |
Research Methodology
Document review covered EPC contractor filings, utility procurement databases, and MEE permitting records, complemented by interviews with power plant engineering directors, refractory material procurement leads, and grid planning officers at provincial utilities. Secondary validation drew from customs trade data for high-alumina castables, CEA tender documentation, and SEC disclosures from listed equipment suppliers. Bottom-up unit deployment tracking across India, China, and Indonesia triangulated against top-down market sizing from fuel flexibility investment flows.
Installed capacity projections by fuel type and steam parameter tier emerged from the analytical framework across the analysis window, with segmentation modeling capturing coal, biomass, petcoke, and waste feedstock categories alongside subcritical, supercritical, and modular product architectures. CAGRs derived from regression against historical utility capex cycles and regulatory mandate implementation timelines, incorporating MEE dual carbon permitting velocity and CEA supercritical adoption curves as industry-specific forecast inputs.
The model holds under continued CEA enforcement of 660 MW supercritical mandates and MEE biomass co-firing thresholds; deviation in refractory material cost volatility or cyclone separator supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Marine Boiler Burner Market
Boilers
Utility Boiler Market
Boilers
Boiler Control Solutions Market
Boilers
Netherlands Combined Heat and Power Market
Boilers
Hydrogen Boilers Market
Boilers
US Commercial Boiler Market
Boilers
Water Tube Industrial Boiler Market
Boilers
US Boiler Market
Boilers
Industrial Biomass Boiler Market
Boilers
Biomass Boiler Market
Boilers
Advanced Utility Boilers Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
GCC Electric Water Heater Market
Boilers
Boiler Combustion Chamber Market
Boilers
Gas Fired Boilers Market
Boilers
Fuel Operated Heaters Market