
 Israel Renewable Energy Market | 2026-2036
Israel Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Renewable Energy Market Foresight
Utility procurement channels is rewriting how Israeli power developers secure offtake agreements for new renewable capacity. SolarEdge Technologies leverages its power electronics specialization to dominate inverter supply for distributed solar installations. Ormat Technologies anchors the geothermal segment through its long-established expertise in the Dead Sea Rift Valley. Nofar Energy competes aggressively on utility-scale solar and energy storage project development across southern Israel.
Israel renewable energy encompasses electricity generation systems that harness solar irradiance, wind kinetic energy, organic biomass combustion, and subsurface geothermal heat through photovoltaic panels with typical conversion efficiencies of 18-22%, onshore turbines rated at 2-3 MW, anaerobic digesters, and binary-cycle geothermal plants. Solar Photovoltaic leads technology deployment due to declining module costs and high direct normal irradiance exceeding 2,000 kWh/m² annually in the Negev. Power Generation applications attract the largest capital allocation, while Industrial end users drive behind-the-meter adoption to hedge volatile grid tariffs.
The Israel Public Utilities Authority—Electricity governs tariff structures and renewable energy certificate mechanisms, while the Ministry of Environmental Protection enforces emissions standards that accelerate coal plant retirement. CEA interconnection regulations and the national net metering framework shape project economics and market access for distributed generators. Stakeholders must monitor evolving storage procurement mandates and grid stability requirements as renewable penetration rises.
Market Dynamics
Grid interconnection reforms under CEA guidelines are compressing project timelines for utility-scale solar developers while forcing distributed generators to adapt to evolving net metering frameworks. This regulatory momentum is redistributing capital toward storage-integrated installations.
Growth Catalysts
- Negev Desert irradiance concentration:Direct normal irradiance exceeding 2,000 kWh/m² annually attracts utility-scale photovoltaic deployment. Land availability in southern Israel supports gigawatt-scale project pipelines.
- Coal plant retirement mandates:The Ministry of Environmental Protection enforces emissions standards that accelerate baseload replacement. Baseload capacity gaps create procurement urgency for renewable offtake.
- Net metering framework expansion:Distributed generators gain market access through revised tariff structures. Commercial and industrial rooftops in central Israel monetize behind-the-meter generation.
Market Restraints
- Land use competition:Military zones and nature reserves constrain available acreage for utility-scale development. Project siting requires coordination with multiple state authorities.
- Grid stability requirements:The Public Utilities Authority—Electricity mandates synchronous condensers and frequency response capabilities. Interconnection costs escalate for remote Negev installations.
- Storage procurement mandates:Co-located battery systems add capital intensity to solar projects. Lithium supply concentration in East Asia creates input cost volatility.
Strategic Opportunities
- Eilat-Arava renewable corridor:The southernmost district offers untapped land and Jordanian cross-border interconnection potential. Regional energy trade frameworks could unlock export revenues.
- Agrivoltaics integration:Dual-use solar arrays above desert agriculture preserve land productivity. Kibbutzim and moshavim pilot shade-crop synergies in the northern Negev.
- Green hydrogen offtake:Industrial consumers in Haifa Bay seek renewable hydrogen for ammonia and refining processes. Electrolyzer demand could anchor multi-gigawatt solar expansion.
Industry Challenges
- Grid code compliance timelines:CEA interconnection regulations require extensive inverter certification and stability testing. Project commissioning delays average six to nine months.
- Skilled technician scarcity:High-voltage substation engineering and battery integration expertise concentrate in Tel Aviv and Haifa. Negev project execution depends on mobile contracting teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Renewable Energy Market |
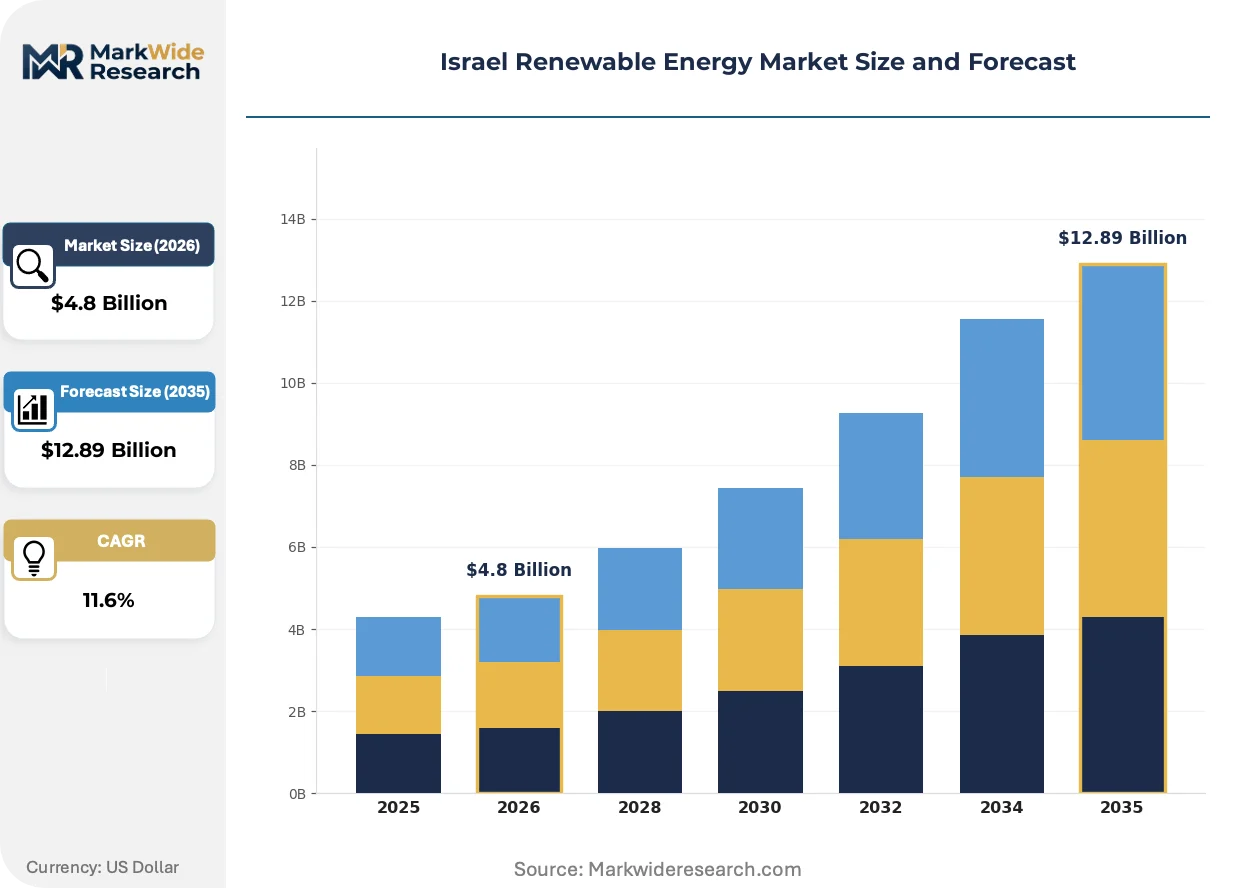
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Photovoltaic, Wind Power, Biomass, Geothermal Application: Residential, Commercial, Industrial, Power Generation Service Type: Consulting, Installation, Maintenance, Operation End User: Utilities, Governments, Enterprises, Households |
| Companies Covered | SolarEdge Technologies, Ormat Technologies, BrightSource Energy, Nofar Energy, Eco Wave Power, H2Pro, Electreon, Augury, IDE Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Renewable Energy Market Shifts & Advancements
Digital intelligence is penetrating power electronics and grid management systems, compressing operational response times while enabling predictive maintenance. These capabilities are reshaping how Israeli developers structure O&M contracts and asset performance guarantees.
Power optimizers and module-level electronics are digitizing solar array performance management. Commercial installers in Jerusalem and Tel Aviv metropolitan areas adopt rapid shutdown and arc-fault detection capabilities. Real-time monitoring granularity is compressing insurance premiums and enabling output-based financing structures.
The Public Utilities Authority—Electricity is tightening grid code requirements for distributed energy resources. New inverter standards mandate frequency-watt and volt-watt response curves. Residential and commercial segments face retrofit obligations for pre-2023 installations.
Industrial offtakers are consolidating renewable energy certificate procurement through long-term power purchase agreements. Food processing and data center operators in central Israel bypass traditional utility channels. Direct contracting with Negev project developers is compressing intermediary margins and reshaping developer business models.
Israel Renewable Energy Market Segmentation
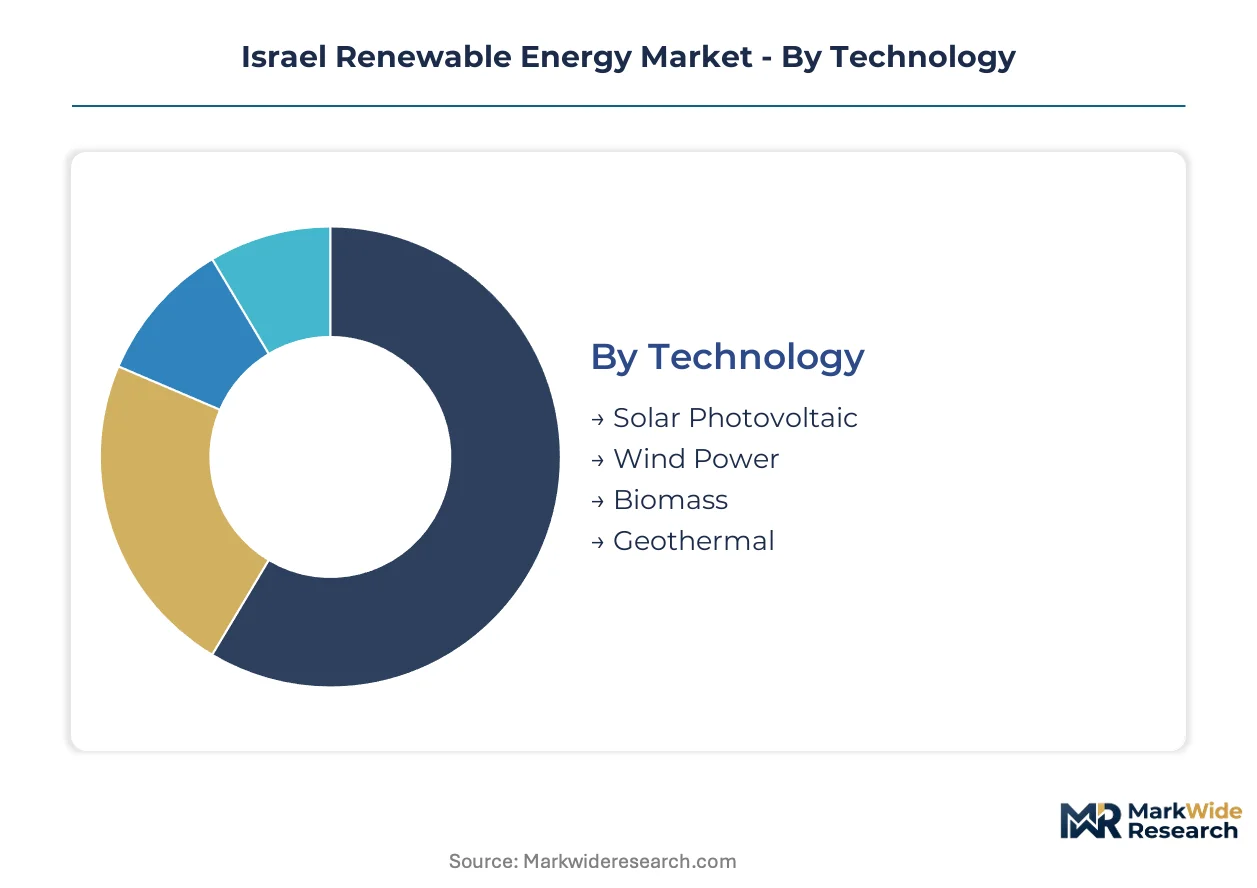
Segmentation reveals how capital allocation and project timelines diverge across Israeli renewable energy value chains. Technology cycles, application payback periods, and service contract durations each create distinct investment rhythms for developers and financiers.
Technology:
Module replacement cycles and equipment lifespans create starkly different capital turnover profiles across generation technologies.
- Solar Photovoltaic:Silicon wafer modules with 25-year performance warranties dominate Israeli deployment. Negev Desert utility-scale arrays attract institutional capital seeking long-dated yields, while rooftop distributed systems in Tel Aviv and Haifa metropolitan areas turn over equipment every 12-15 years through inverter and module upgrades.
- Wind Power:Onshore turbines rated at 2-3 MW with 20-year design lives concentrate in the Golan Heights and Galilee ridges. Permitting complexity and grid interconnection queues extend project development cycles to 4-6 years, compressing annual deployment velocity relative to solar.
- Biomass:Anaerobic digesters and combustion systems process agricultural residues from kibbutzim and moshavim in the Jezreel Valley. Feedstock supply agreements with poultry and dairy operations determine project economics.
- Geothermal:Binary-cycle plants exploiting Dead Sea Rift Valley heat resources operate as baseload assets with 30-year operational horizons. Ormat Technologies maintains exclusive access to exploration licenses.
Solar Photovoltaic anchors the volume base while Geothermal gains share at the steepest rate given its dispatchable profile and scarcity of suitable geological formations.
Application:
Customer scale determines tariff structures and offtake security, with behind-the-meter installations commanding premium economics over wholesale-exposed generation.
- Residential:Rooftop systems under 15 kW leverage net metering frameworks and Israel Electric Corporation buyback rates. Battery attachment rates are climbing in central Israel suburbs as grid tariff volatility spurs self-consumption optimization.
- Commercial:Office buildings, shopping centers, and hotels in Jerusalem and Tel Aviv deploy 50-500 kW arrays to hedge volatile commercial electricity tariffs. Power purchase agreement tenors typically span 15-20 years.
- Industrial:Food processing, chemicals, and data center operators in Haifa Bay and central Israel procure multi-megawatt installations. Direct contracting with Negev developers bypasses utility intermediation.
- Power Generation:Utility-scale photovoltaic and future wind farms sell into the wholesale market or secure government auction contracts. The Public Utilities Authority—Electricity governs tariff regulation and renewable energy certificate mechanisms.
Power Generation commands the largest absolute capacity additions while Industrial applications deliver the highest margin per installed kilowatt through behind-the-meter tariff arbitrage.
Service Type:
Contract duration and recurring revenue intensity separate installation peaks from steady-state operational cash flows.
- Consulting:Feasibility studies, grid interconnection applications, and permitting navigation for CEA compliance. Project development advisory concentrates in Tel Aviv engineering consultancies.
- Installation:EPC contractors execute module mounting, inverter commissioning, and substation integration. Skilled technician scarcity in the Negev extends commissioning timelines.
- Maintenance:Preventive and corrective O&M contracts spanning 10-20 years. Module cleaning, vegetation management, and inverter replacement dominate scope in desert climates.
- Operation:Asset management and energy optimization services. Real-time monitoring platforms and predictive analytics are compressing insurance premiums and enabling output-based financing.
Installation captures the largest revenue spike during market expansion phases while Operation delivers the most stable long-term cash flows.
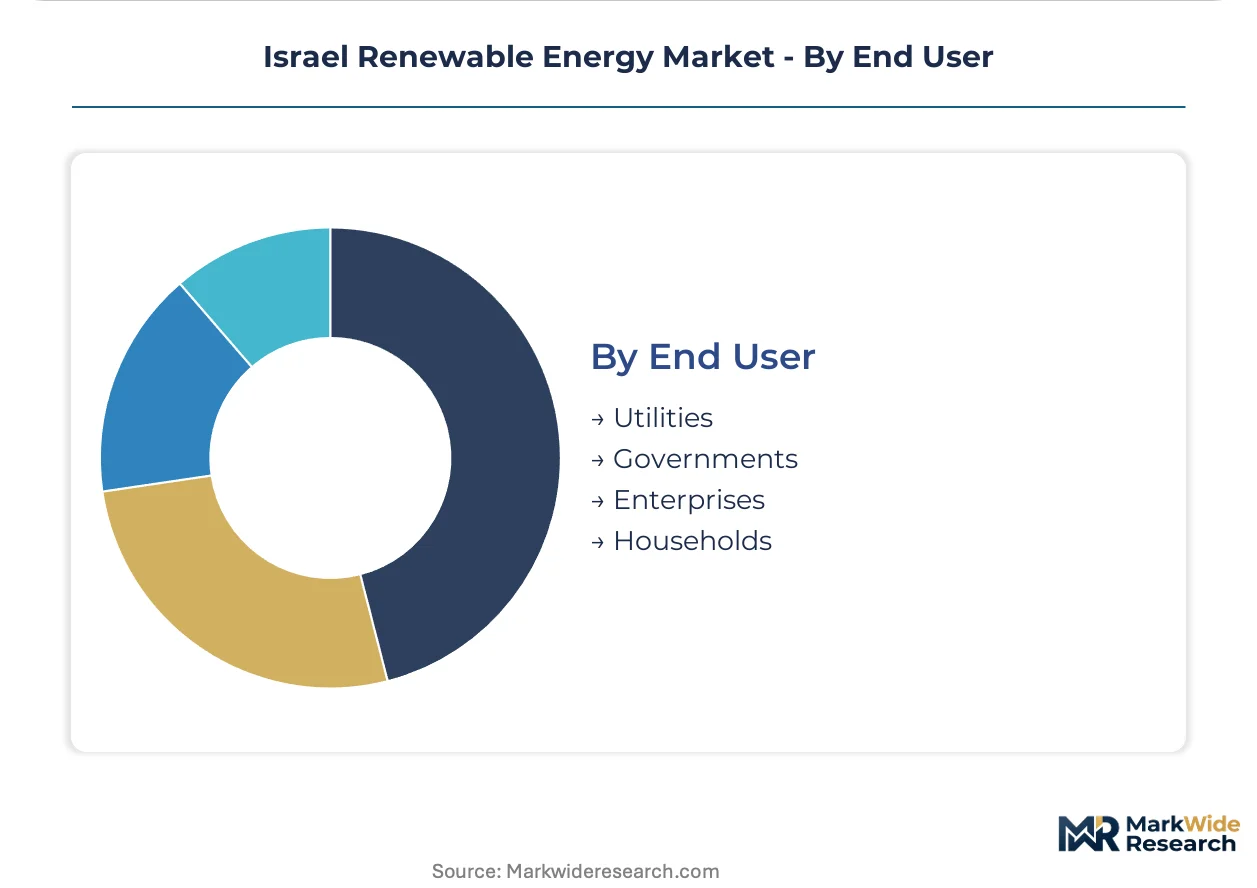
End User:
Procurement authority and creditworthiness shape project finance structures and offtake security premiums.
- Utilities:Israel Electric Corporation and independent power producers procure bulk capacity through competitive auctions. Sovereign-backed offtake supports lowest-cost project finance.
- Governments:Municipal authorities and state-owned enterprises deploy solar on public buildings. Ministry of Finance green bond frameworks are emerging as a capital source.
- Enterprises:Corporate power purchase agreements from food processing, chemicals, and technology firms. Direct contracting with Negev developers is reshaping traditional utility channels.
- Households:Distributed rooftop adoption driven by net metering economics and battery cost declines. Residential segment shows highest sensitivity to interconnection queue delays.
Utilities dominate absolute procurement volumes while Enterprises are expanding their share most aggressively through direct PPA structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli developers command premium offtake rates in the Negev Desert while metropolitan Tel Aviv faces land scarcity premiums. This pricing-power asymmetry shapes capital flows across sub-regional markets.
Southern District
The Negev Desert anchors utility-scale photovoltaic deployment with direct normal irradiance exceeding 2,000 kWh/m² annually. The Public Utilities Authority—Electricity governs competitive auction mechanisms for wholesale capacity. Ashalim and Ketura Sun solar complexes concentrate gigawatt-scale installations where state land leases minimize siting friction.
Central District
Commercial and industrial rooftops in Tel Aviv and Haifa metropolitan areas drive behind-the-meter solar adoption. Net metering frameworks enable tariff arbitrage for food processing and data center operators. Petah Tikva and Rehovot industrial parks host distributed arrays serving pharmaceutical and technology campuses.
Jerusalem District
Municipal solar procurement on public buildings accelerates under Ministry of Finance green bond frameworks. The Ministry of Environmental Protection enforces emissions standards that accelerate coal displacement. Jerusalem and Bethlehem corridor projects navigate complex land authority coordination.
Northern District
The Golan Heights and Galilee ridges concentrate onshore wind development with 2-3 MW turbine installations. Grid interconnection queues under CEA guidelines extend project timelines relative to solar. Kiryat Shmona and Safed substations anchor regional transmission infrastructure.
Dead Sea Rift Valley
Geothermal resources support binary-cycle baseload generation with 30-year operational horizons. Ormat Technologies maintains exploration license exclusivity in this geologically active zone. Ein Gedi and Ein Boek host the country's only operating geothermal facilities.
Israel Renewable Energy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in power electronics and resource extraction. The Israeli market structures around three archetypes: inverter and optimizer manufacturers, project developers with utility-scale pipelines, and geothermal resource holders with exclusive geological access. Competitive moves concentrate on storage-integrated EPC bundling and cross-border partnership formation for regional export corridors.
Among power electronics specialists, SolarEdge Technologies exemplifies the component-dominant archetype through its optimizer and inverter focus. Geothermal resource concentration is represented by Ormat Technologies, which occupies the exclusive position in Dead Sea Rift Valley development. Nofar Energy anchors the utility-scale developer tier with aggressive project origination across southern Israel. These three players illustrate how technology specialization, geological exclusivity, and development velocity create distinct competitive moats.
| Leading Market Players |
|---|
| SolarEdge Technologies |
| Ormat Technologies |
| BrightSource Energy |
| Nofar Energy |
| Eco Wave Power |
| H2Pro |
| Electreon |
| Augury |
| IDE Technologies |
| Others |
Supply & Pricing Matrix
The Haifa Port-Eilat logistics corridor shapes cost dynamics across Israeli renewable energy supply chains, concentrating pricing power among East Asian equipment suppliers while forcing downstream price differentiation between utility-scale and distributed solar segments. Container freight volatility from Shanghai and Busan feeds directly into module landed costs, compressing margins for EPC contractors serving Negev utility projects.
Pricing Analysis
The customization-premium spread separates standard utility-scale photovoltaic arrays from configured-to-order distributed installations with module-level power electronics. Project-based long-term offtake contracts dominate utility procurement through Public Utilities Authority—Electricity auctions, while commercial rooftops in Tel Aviv metropolitan areas command price premiums for rapid shutdown and arc-fault detection capabilities. Price differentiation rests on certification tier (IEC 61215/61730 vs enhanced grid code compliance) and after-sales service bundling. Cost compression in standard utility tiers is intensifying because lithium-ion battery co-location mandates add capital intensity. Industrial offtakers in Haifa Bay show lowest price sensitivity through direct PPA structures, while residential rooftop adopters in central Israel exhibit highest sensitivity to interconnection queue delays.
Supply Chain Analysis
Tariff exposure between China and Israel dominates supply chain risk for photovoltaic module procurement, with anti-dumping investigations periodically disrupting shipment schedules. Manufacturing concentration in China, South Korea, and Vietnam feeds polysilicon wafers, lithium iron phosphate cells, and power electronics into Israeli project pipelines. Raw material dependencies center on polysilicon ingots, silver metallization paste, and cobalt-free cathode materials. Single-source vulnerability in inverter firmware certification creates commissioning bottlenecks under CEA grid code requirements. Distribution runs through Tel Aviv-based EPC aggregators and direct manufacturer relationships for utility-scale developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel renewable energy is exiting a capital-intensive buildout phase into a cyclical recovery anchored by coal plant retirement mandates. Baseload replacement urgency creates procurement windows that favor developers with storage-integrated project pipelines.
For Market Incumbents: Harden grid code compliance capabilities against emerging EPC competitors from Southern Europe. Invest in captive technician training programs to reduce Negev project execution delays. Prioritize vertical integration into battery integration services to capture storage procurement mandate premiums.
For New Entrants and Emerging Players: The Eilat-Arava renewable corridor offers untapped land availability and cross-border interconnection potential with Jordanian grid infrastructure. Target agrivoltaic pilots on kibbutzim in the northern Negev where dual-use solar arrays face minimal siting friction. Pursue direct contracting with industrial hydrogen offtakers in Haifa Bay as anchor demand for greenfield electrolyzer projects.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core renewable development arms. Long-term viability hinges on regulatory capture in CEA interconnection queue management and storage procurement mandate compliance. Monitor Public Utilities Authority—Electricity auction participation rates as inflection indicator for developer margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Storage-Integrated EPC Bundling | Co-located battery systems satisfy Public Utilities Authority procurement mandates while capturing grid stability service revenues. |
| Cross-Border Interconnection Partnership | Jordanian grid access unlocks Eilat-Arava export corridors under regional energy trade frameworks. |
| Agrivoltaic Pilot Scale-Up | Dual-use arrays on kibbutzim preserve agricultural productivity while expanding deployable land area. |
| Green Hydrogen Offtake Anchoring | Industrial consumers in Haifa Bay provide demand certainty for multi-gigawatt electrolyzer investments. |
| Grid Code Compliance Certification | CEA inverter standards create competitive moats through six-to-nine-month commissioning timelines. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation. Stakeholder interviews captured procurement timelines, interconnection queue dynamics, and storage procurement mandate implementation. Secondary sources included Israel Electric Corporation regulatory filings, Public Utilities Authority—Electricity auction results, Ministry of Environmental Protection emissions data, and CEA technical standards documentation. Bottom-up project pipeline aggregation was triangulated against top-down capacity forecasts.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling capacity additions against coal retirement schedules and industrial load growth. Segmentation dimensions included technology type, project scale tier, application segment, and regional grid infrastructure type. CAGRs were derived from installed capacity trajectories and capital expenditure flows. Forecast inputs incorporated lithium supply cost curves and inverter certification backlog estimates.
Practitioners should monitor CEA regulatory amendments and storage procurement mandate revisions for early signals of project economics shifts. Forecasts reflect assumptions regarding interconnection queue clearance rates and module import tariff stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Romania Wind Energy Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Solar Oven Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
East Africa Renewable Energy Market