
 Micro Combined Heat and Power (CHP) Market | 2026-2036
Micro Combined Heat and Power (CHP) Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Combined Heat and Power (CHP) Market Intelligence
Hybrid fuel cell architectures is reconfiguring how micro CHP systems balance electrical and thermal output ratios for residential applications. Panasonic Corporation leverages its solid oxide fuel cell expertise to anchor premium segments in Japanese single-family housing. Vaillant Group competes through integrated heating system portfolios that bundle micro CHP with conventional boilers across European markets. Ceres Power Holdings specializes in steel-supported cell technology that extends manufacturing scalability beyond traditional ceramic substrates.
Micro Combined Heat and Power denotes distributed generation systems under 50 kWe that simultaneously produce usable heat and electricity from a single fuel input, typically achieving total system efficiencies of 80-90% through heat recovery integration. Fuel cell technology leads value capture due to superior electrical efficiency and quiet operation profiles suited to dense residential settings, while reciprocating engine systems dominate installed volume in commercial complexes where higher thermal loads justify capital outlay. Retrofit projects represent a structurally constrained segment given building envelope compatibility requirements, whereas new construction applications absorb grid-connected configurations that optimize net metering arrangements.
Japan's METI enforces efficiency benchmarks that effectively mandate fuel cell adoption in new residential builds, while the EU Green Deal and F-Gas Regulation reshape refrigerant and combustion standards across member states. Germany's KBA and federal building codes increasingly reference primary energy factors that reward simultaneous heat and power generation in efficiency ratings. Stakeholders must monitor how evolving carbon accounting methodologies treat on-site generation versus grid-delivered electricity when evaluating project economics.
Market Dynamics
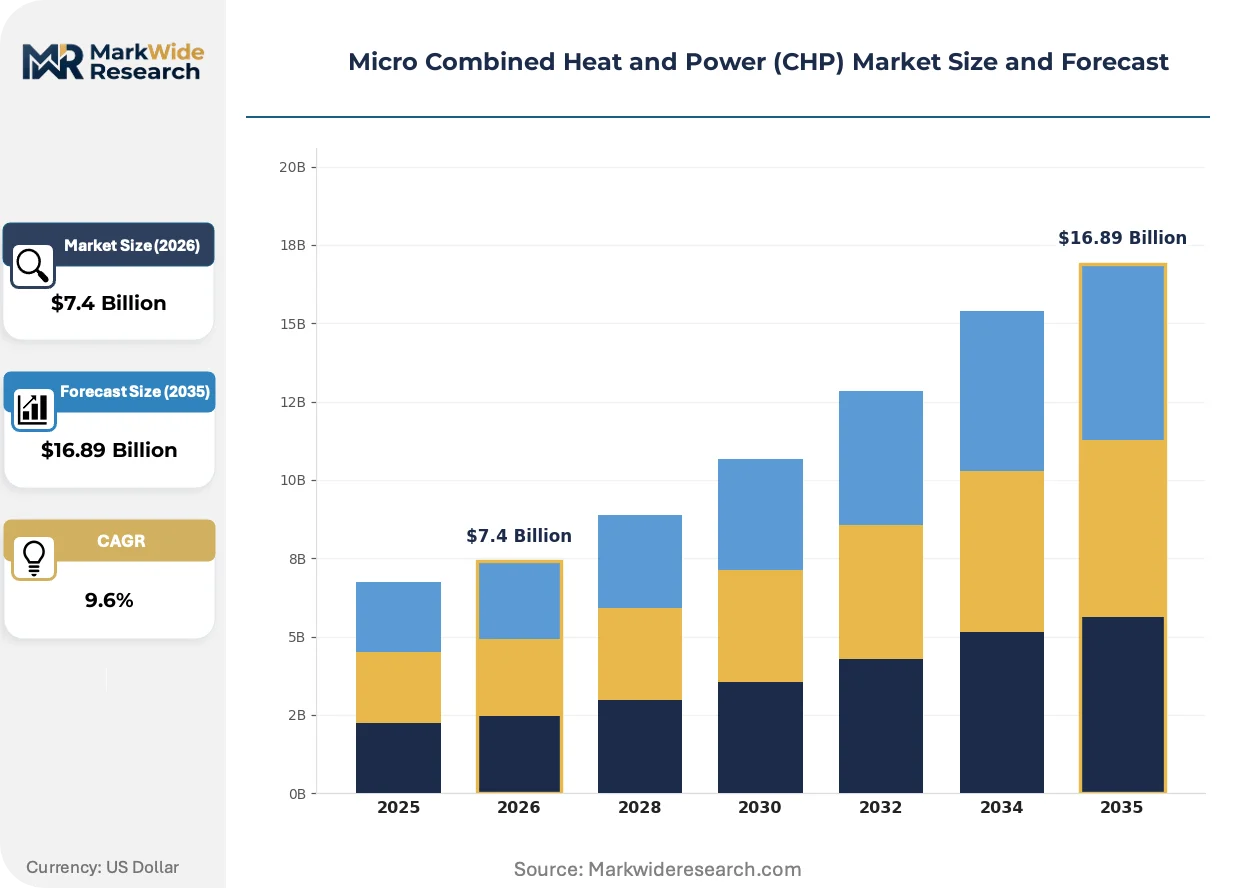
Fuel cell electrical efficiency gains are compressing payback periods for residential micro CHP installations, while Japan's METI efficiency mandates and Germany's KBA building code revisions accelerate technology substitution across single-family housing stock.
Growth Catalysts
- Japan's METI Efficiency Benchmarks:Mandatory fuel cell adoption thresholds for new residential construction create guaranteed demand pull. Single-family developers face compliance deadlines that lock in technology selection.
- District Heating Integration:Northern European municipalities in Denmark, Sweden, and the Netherlands embed micro CHP into decentralized thermal networks. Grid operators reward simultaneous heat and power generation with priority dispatch.
- Solid Oxide Cell Advances:Steel-supported substrates slash manufacturing costs versus ceramic alternatives. Production scalability expands addressable market beyond premium housing segments.
Market Restraints
- Platinum Group Metal Costs:Proton exchange membrane fuel cells depend on iridium and platinum catalysts. Price volatility in South African and Russian supply channels squeezes stack economics.
- Building Envelope Retrofit Constraints:Legacy housing stock lacks thermal efficiency and grid connection capacity. Installation feasibility drops sharply in pre-1990 construction across established European cities.
- Heat Pump Substitution:Air-source and ground-source electric heat pumps capture policy support through simplified installation and lower upfront capital. Residential buyers in moderate climates favor electrification over combustion-based cogeneration.
Strategic Opportunities
- Commercial Microgrids:Hotels, hospitals, and data centers in Germany seek resilience against grid instability. Fuel cell CHP provides baseload power with waste heat absorption for cooling via absorption chillers.
- Hydrogen-Ready System Architectures:Manufacturers designing for 100% hydrogen combustion future-proof installed base. EU Green Deal hydrogen infrastructure funding accelerates pilot deployments in the Netherlands.
- Utility-Owned Leasing Models:Energy retailers in Japan bundle micro CHP hardware with maintenance contracts. Capital barrier removal expands addressable customer base beyond affluent owner-occupiers.
Industry Challenges
- Fuel Cell Stack Technician Shortage:Specialized electrochemistry expertise remains concentrated in automotive and aerospace sectors. HVAC installers lack certification pathways for solid oxide and PEM system maintenance.
- Multi-Regulatory Certification Burden:Products must satisfy EU F-Gas refrigerant rules, CE marking, and national building codes simultaneously. Approval timelines extend 18-24 months for cross-border deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Combined Heat and Power (CHP) Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $16.89 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fuel Cell, Reciprocating Engine, Microturbine, Stirling Engine Application: Residential Buildings, Commercial Complexes, Institutional Facilities, Municipal Services End User: Property Managers, Educational Campuses, Healthcare Facilities, Local Governments Installation Type: New Construction, Retrofit Projects, Off-Grid Systems, Grid-Connected Systems |
| Companies Covered | Aisin Corporation, SOLIDpower, Vaillant Group, Viessmann Manufacturing Company, 2G Energy AG, BDR Thermea Group, Panasonic Corporation, Yanmar Co. Ltd., Ceres Power Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Combined Heat and Power (CHP) Market Strategic Shifts & Innovations
Hybrid system architectures are blurring technology boundaries as manufacturers combine fuel cell electrical generation with conventional boiler thermal backup. This convergence demands new control software and shifts competitive advantage toward integrated heating system portfolios.
Solid oxide fuel cell technology is migrating from ceramic substrate manufacturing toward steel-supported cell production. Vaillant Group and Ceres Power Holdings accelerate adoption in German and British residential markets through simplified supply chains. The shift compresses capital intensity for gigawatt-scale manufacturing and enables cost parity with premium condensing boilers.
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in absorption cooling systems paired with CHP waste heat. Equipment manufacturers reformulate working fluids and redesign heat exchangers to maintain coefficient of performance. Commercial building operators in France and Germany face retrofit decisions as maintenance windows close for legacy refrigerant stocks.
Residential buyers increasingly select micro CHP through energy service contracts rather than equipment purchase. Japanese utilities and German municipal energy companies capture long-term revenue streams by retaining ownership and maintenance responsibility. The model spreads fastest in markets with established heat-as-a-service regulatory frameworks and net metering compensation structures.
Micro Combined Heat and Power (CHP) Market Segmentation
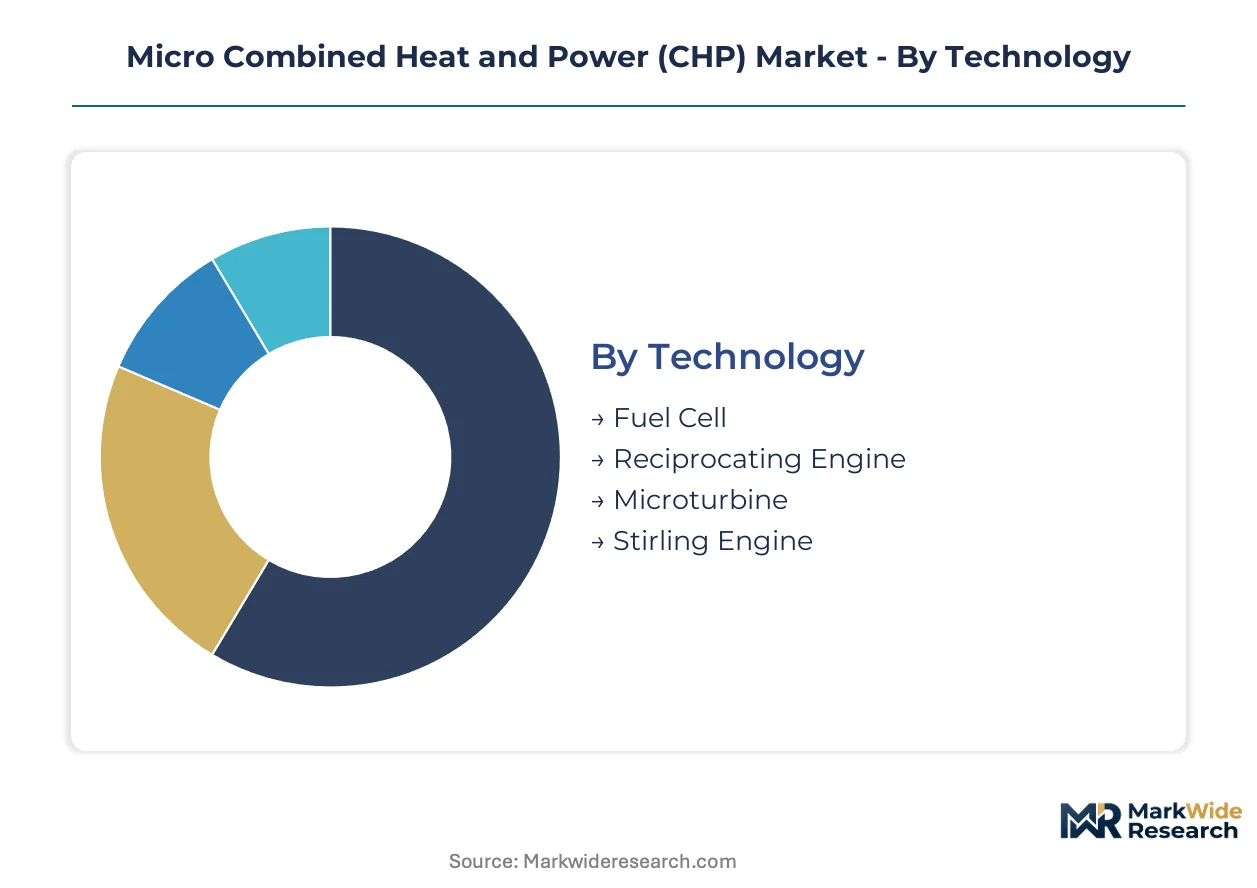
Segmentation in micro CHP markets reveals how technology economics, building stock age, and regulatory frameworks create divergent deployment patterns across customer types. Understanding these boundaries helps manufacturers align product portfolios with addressable demand pools and margin profiles.
Technology:
Cycle times vary dramatically: fuel cell stacks require replacement every 40,000-60,000 operating hours while reciprocating engines demand major overhauls at shorter intervals but with lower per-event costs.
- Fuel Cell:Solid oxide and proton exchange membrane architectures achieve 45-60% electrical efficiency through electrochemical conversion without combustion. Japanese single-family housing under METI efficiency mandates absorbs the majority of global deployment, with Panasonic and Toshiba anchoring supply chains. Premium pricing persists due to platinum group metal catalyst requirements and precision manufacturing.
- Reciprocating Engine:Internal combustion derivatives adapted from automotive and industrial genset platforms deliver 25-35% electrical efficiency with mature service networks. German commercial complexes and Dutch greenhouse operations favor these units for thermal load matching and rapid startup capability. Capital costs run 40-60% below comparable fuel cell capacity.
- Microturbine:Radial flow turbomachinery operating at 70,000-100,000 RPM achieves sub-30% electrical efficiency but excels in high-grade heat recovery applications.
- Stirling Engine:External combustion kinematic drives offer fuel flexibility including biomass and solar thermal inputs, though power density limitations constrain residential applicability.
Reciprocating engines anchor the volume base while fuel cell systems gain share at the steepest rate.
Application:
Cost tier stratification separates premium new construction with integrated design from constrained retrofit economics and budget-conscious municipal procurement.
- Residential Buildings:Single-family and multi-family units under 50 kWe dominate unit shipments, with Japan's detached housing stock and Germany's Energieeffizienzhaus standards driving specification. Fuel cell systems achieve payback through combined electricity export and thermal displacement in high-heat-load climates.
- Commercial Complexes:Hotels, retail centers, and office buildings deploy 30-400 kWe systems with absorption cooling integration. Netherlands and Denmark district heating networks prioritize these installations for network stability contributions.
- Institutional Facilities:Universities and hospitals value resilience against grid interruption, with CHP providing critical power during peak demand events.
- Municipal Services:Wastewater treatment plants and district heating substations exploit biogas or natural gas access for combined thermal and electrical output.
Residential applications concentrate manufacturing scale while commercial complexes expand most quickly through district heating integration.
End User:
Customer sophistication and capital access determine procurement modality, from utility-managed leases to direct equipment purchase with performance contracting.
- Property Managers:Multi-building portfolios in Germany and Netherlands negotiate fleet pricing and centralized maintenance agreements, favoring standardized reciprocating engine platforms.
- Educational Campuses:University facilities in Denmark and Sweden integrate CHP with existing district heating infrastructure and research-driven sustainability commitments.
- Healthcare Facilities:Hospital operators in Japan and Germany prioritize uninterrupted power supply for critical care infrastructure.
- Local Governments:Municipal procurement in France and Netherlands emphasizes lifecycle cost optimization through energy performance contracts.
Property managers dominate transaction volume while healthcare facilities adopt at the steepest expansion trajectory.
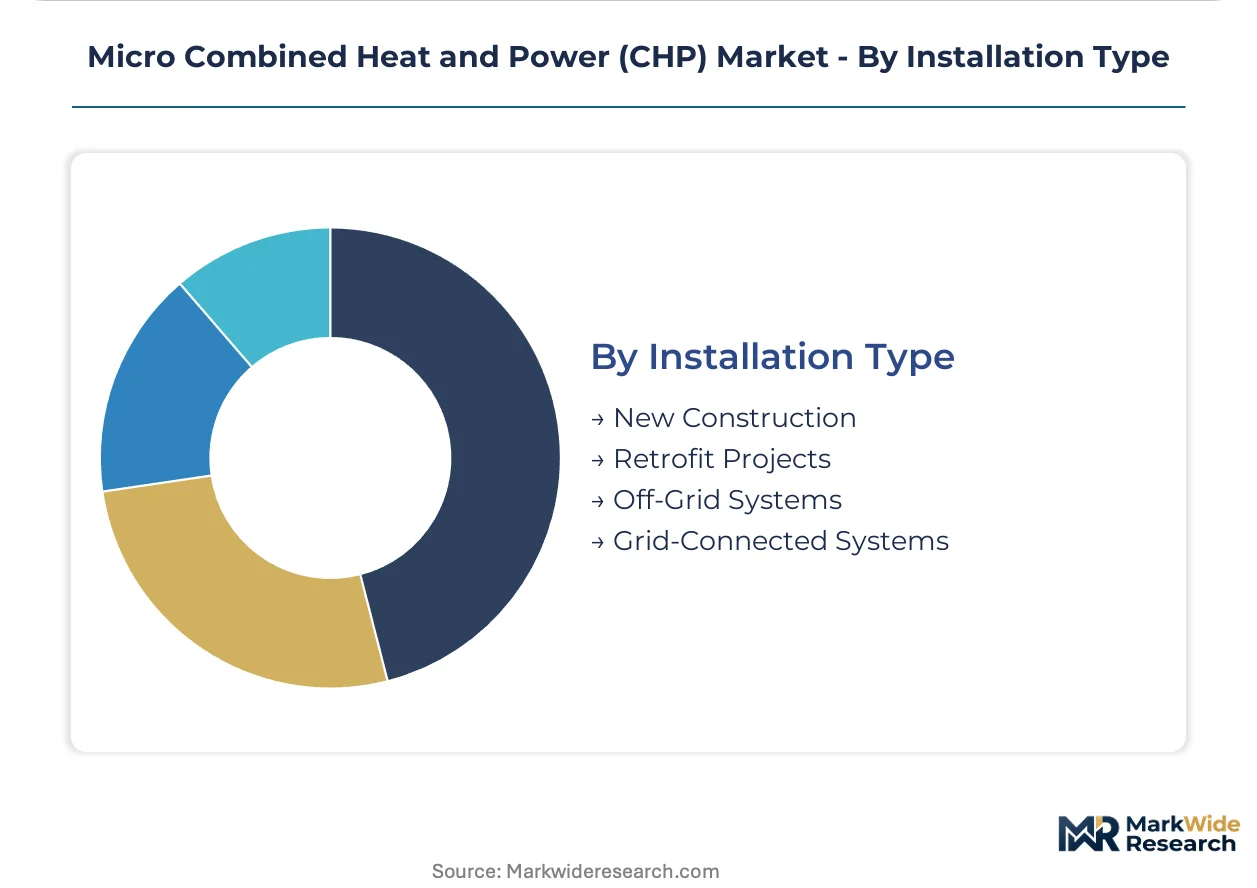
Installation Type:
Volume distribution skews heavily toward new construction where mechanical room design and grid interconnection planning occur during architectural phases.
- New Construction:Integrated design enables optimal unit sizing, heat distribution architecture, and net metering configuration. Japanese post-2020 building codes and German KBA efficiency ratings effectively mandate CHP consideration in single-family developments.
- Retrofit Projects:Legacy building constraints including envelope thermal performance, electrical service capacity, and flue routing feasibility eliminate 60-70% of candidate structures in established European cities.
- Off-Grid Systems:Remote installations in Nordic regions and island communities exploit CHP reliability without grid interconnection costs.
- Grid-Connected Systems:Net metering and feed-in tariff structures in Germany, Netherlands, and Japan determine operating economics through export compensation rates.
New construction commands the volume base while retrofit projects climb the fastest despite structural constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-family housing developers in Japan and Germany concentrate procurement authority for residential micro CHP systems, while Dutch and Danish district heating operators control commercial deployment decisions. These buyer archetypes dictate regional demand patterns and technology specifications.
Japan
Detached housing construction in suburban Tokyo and Osaka corridors absorbs solid oxide fuel cell systems under METI efficiency mandates. The agency's 2020 building code revisions established primary energy benchmarks that effectively exclude conventional boilers from new single-family developments. Panasonic Corporation and Toshiba Energy Systems anchor manufacturing clusters in Kansai and Chubu regions.
Germany
North Rhine-Westphalia and Bavaria municipal utilities embed micro CHP into decentralized heat networks serving multi-family housing estates. Germany's KBA federal motor transport authority and federal building energy codes reward simultaneous heat and power generation through primary energy factor adjustments. Vaillant Group and Viessmann Manufacturing Company maintain production facilities across Hesse and Lower Saxony.
Netherlands
Randstad metropolitan greenhouse operators deploy reciprocating engine systems for combined electrical generation and CO2 fertilization of horticultural crops. The national climate agreement subsidizes gas-fired CHP as transitional technology toward hydrogen-ready district heating networks. Eindhoven Region technical universities pilot steel-supported fuel cell manufacturing processes.
Denmark
Copenhagen and Aarhus district heating companies prioritize micro CHP installations for network stability and peak shaving capacity. Danish Energy Agency regulations mandate renewable gas blending quotas that favor adaptable cogeneration over pure heat pumps. Aalborg University research clusters advance absorption cooling integration for commercial building applications.
United Kingdom
Southeast England residential developers specify fuel cell CHP for new-build estates targeting net-zero carbon certifications. Ofgem's Smart Export Guarantee compensates grid electricity exports, improving project economics for owner-occupiers. Ceres Power Holdings operates steel-supported cell manufacturing facilities in West Sussex serving export markets.
Micro Combined Heat and Power (CHP) Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent go-to-market strategies. The market structure consolidates around integrated heating system portfolios and fuel cell stack manufacturing capabilities, with three strategic archetypes dominating: diversified heating equipment conglomerates, fuel cell technology specialists, and reciprocating engine genset adaptors. Competitive moves concentrate on technology licensing agreements and manufacturing capacity expansion for steel-supported cell architectures.
Within the diversified heating equipment tier, Vaillant Group and Viessmann Manufacturing Company exemplify integrated portfolio strategies that bundle micro CHP with conventional boilers and heat pumps. Panasonic Corporation occupies a distinct position as a fuel cell technology anchor in Japanese residential markets. Ceres Power Holdings represents the steel-supported cell specialist archetype targeting manufacturing scalability beyond traditional ceramic substrates.
| Leading Market Players |
|---|
| Aisin Corporation |
| SOLIDpower |
| Vaillant Group |
| Viessmann Manufacturing Company |
| 2G Energy AG |
| BDR Thermea Group |
| Panasonic Corporation |
| Yanmar Co. Ltd. |
| Ceres Power Holdings |
| Others |
Cost & Logistics Intelligence
Undercapacity in Japanese fuel cell stack manufacturing compresses supplier bargaining power and sustains premium pricing for solid oxide systems bound for residential applications. Germany's KBA efficiency mandates and METI building codes in Japan amplify demand concentration, allowing incumbent manufacturers to maintain cost-plus contract structures with limited buyer recourse.
Pricing Analysis
Cost-plus contracts with platinum group metal indexation dominate fuel cell procurement, while reciprocating engine systems trade on fixed-price terms with volume discounts. Price differentiation separates premium solid oxide units with extended warranties from standard PEM configurations and economy-tier engine adaptations. Cost compression in the reciprocating engine tier intensifies as Chinese component suppliers expand European distribution. Municipal utilities and property managers exhibit highest price sensitivity, whereas healthcare facilities prioritize reliability over capital outlay.
Supply Chain Analysis
Tariff exposure between South Africa and Japan dominates raw material risk profiles for proton exchange membrane catalyst procurement. Manufacturing concentrates in Japan, Germany, and South Korea for fuel cell stacks, with reciprocating engine assembly anchored in Germany and the Netherlands. Supply chains draw from iridium and platinum catalysts, steel-supported ceramic substrates, and precision turbomachinery components. Single-source vulnerability persists for solid oxide electrolyte materials. Distribution runs through OEM-direct channels for residential units and specialized HVAC contractors for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat opportunity anchored in regulatory entrenchment. Japan's METI efficiency mandates and Germany's KBA building code revisions create structural barriers that lock in technology specifications and freeze out unapproved competitors.
For Market Incumbents: Entrench position through backward integration into steel-supported cell manufacturing and captive catalyst recycling capabilities. Heat pump substitution in moderate climates threatens residential fuel cell volumes, necessitating absorption cooling bundling for commercial segments. Capacity addition in North Rhine-Westphalia secures district heating network access.
For New Entrants and Emerging Players: Pursue hydrogen-ready system architectures as the most penetrable white space, targeting Dutch greenhouse operators and Nordic island communities. Commercial microgrids for data centers and hospitals offer faster payback validation than residential channels. Energy-as-a-service leasing models bypass capital barriers among price-sensitive municipal buyers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among utility-owned leasing providers with maintenance contract bundling. Long-term viability favors fuel cell stack specialists with steel-supported manufacturing scalability over engine adaptors facing electrification headwinds. Watch hydrogen infrastructure subsidy announcements in the Netherlands as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Steel-Supported Cell Manufacturing Scale-Up | Ceres Power Holdings and Vaillant Group compress capital intensity for gigawatt-scale fuel cell production. |
| Hydrogen-Ready System Certification | EU Green Deal hydrogen infrastructure funding accelerates pilot deployments in Dutch district heating networks. |
| Utility-Owned Leasing Model Expansion | Japanese utilities and German municipal energy companies capture long-term revenue through heat-as-a-service frameworks. |
| Absorption Cooling Integration Partnership | Commercial building operators in France and Germany reformulate working fluids under EU F-Gas Regulation phase-down timelines. |
| Fuel Cell Stack Technician Certification Program | HVAC installers require electrochemistry training pathways to address solid oxide and PEM system maintenance shortages. |
Research Approach
The analysis maps fuel cell stack manufacturing, reciprocating engine assembly, and district heating integration sub-sectors, each validated through plant managers at OEM facilities, procurement leads at municipal utilities, and aftermarket service heads at HVAC contractors. Primary interviews with regulatory affairs specialists at METI and KBA supplemented secondary validation through EIA generation data, IEA distributed energy reports, FERC interconnection filings, and EU F-Gas Regulation compliance databases. Bottom-up unit shipment tallies triangulate against top-down market value estimates.
The analytical framework holds regulatory mandate timelines and hydrogen infrastructure subsidy schedules fixed across the projection horizon, while varying platinum group metal price trajectories and heat pump cost curves. Segmentation dimensions include technology architecture, application scale tier, end-user sophistication, and installation type. CAGRs derive from installed base growth rates and replacement cycle assumptions. Forecast inputs incorporate METI building code compliance deadlines and EU Green Deal carbon accounting methodology revisions.
Sensitivities concentrate around platinum group metal supply disruptions and hydrogen infrastructure deployment delays. Forecasts reflect assumptions regarding regulatory mandate enforcement continuity and district heating network expansion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Reformer Unit Market
Boilers
Fuel Operated Heaters Market
Boilers
Watertube Boilers Market
Boilers
Gas Condensing Boiler Market
Boilers
Biomass Boiler Market
Boilers
Waste Heat Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
GCC Electric Water Heater Market
Boilers
Industrial and Residential Heating Market
Boilers
Commercial Boiler Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
Oil-Fired Boiler Market
Boilers
Power Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Feed Water Heater for Power Plants Market