
 Brazil Combined Heat and Power Market | 2026-2036
Brazil Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Combined Heat and Power Market Outlook
A shortage of certified turbine technicians is bifurcating the Brazil Combined Heat and Power Market into projects that can secure qualified labor and those facing commissioning delays. Siemens AG anchors its position through localized service networks that sustain long-term maintenance contracts across the sugar-energy sector. Mitsubishi Heavy Industries competes by leveraging its gas turbine expertise to dominate large-scale industrial installations in the Southeast.
Combined Heat and Power refers to integrated systems that simultaneously generate electricity and useful thermal energy from a single fuel source, typically achieving total efficiencies of 60-80% through heat recovery steam generators or absorption chillers. The technology serves Brazil's industrial base by reducing grid dependency and converting waste heat into process steam for manufacturing. Gas turbines command the technology segment due to their scalability for 50-300 MW installations serving petrochemical and pulp complexes. Biomass leads fuel type adoption as sugar mills retrofit bagasse-fired boilers with extraction-condensing steam turbines. The onsite installation category captures margin pools through turnkey engineering contracts that bundle equipment supply with civil works and grid synchronization.
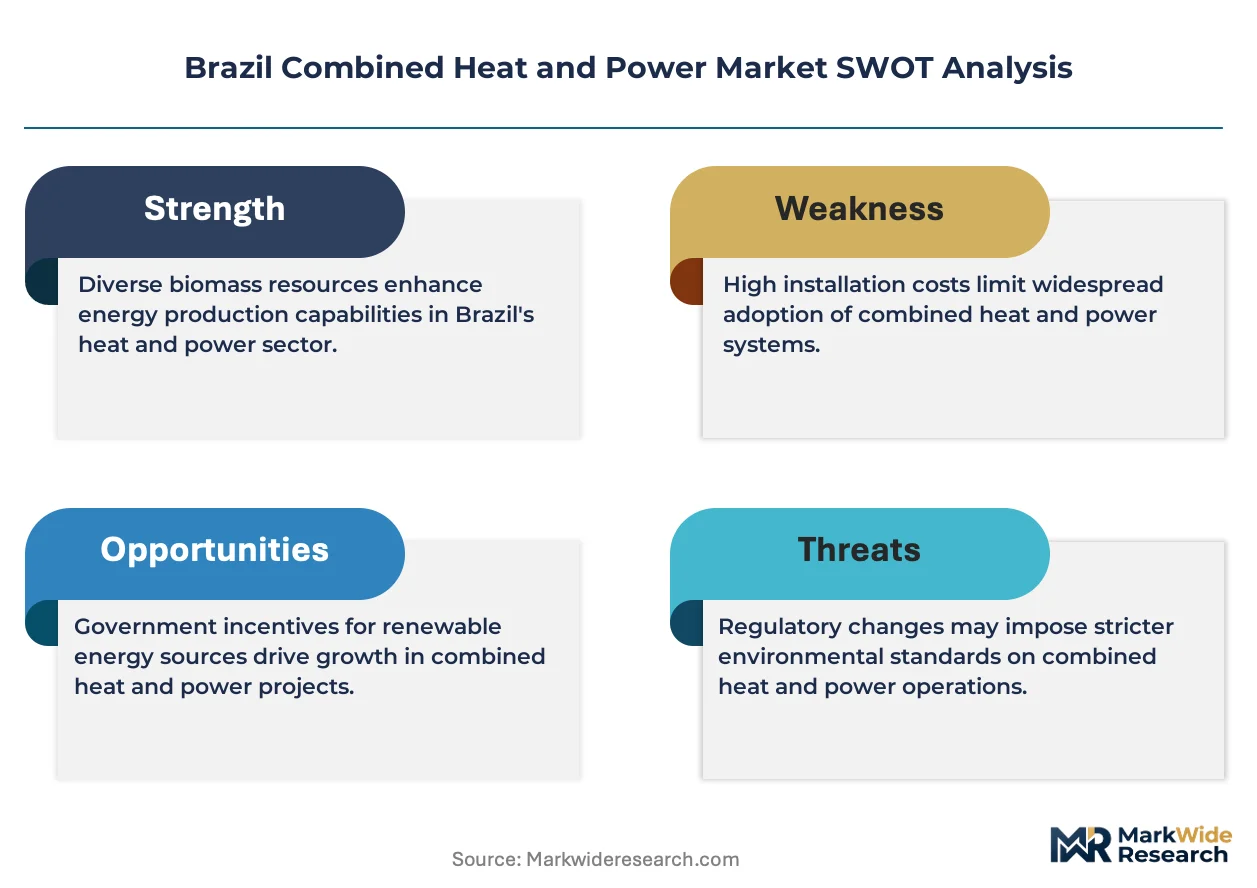
ANVISA oversees pressure vessel certification requirements that shape equipment import timelines and local fabrication partnerships. The Brazilian Electricity Regulatory Agency sets distributed generation compensation rules that determine project payback periods for commercial adopters. ISO 50001 energy management standards increasingly filter into utility procurement criteria, redirecting vendor qualification pathways. Stakeholders must monitor how proposed reforms to net metering tariffs reshape the economics behind compact and modular system deployments.
Market Dynamics
RenovaBio decarbonization credits are compressing payback periods for bagasse-fired cogeneration investments, redirecting capital from conventional grid-tied generation toward integrated sugar-energy complexes in São Paulo state.
Growth Catalysts
- RenovaBio Credit Mechanisms:The Brazilian biofuel certification program generates tradeable decarbonization credits that improve project IRRs for biomass-based systems. Sugar mills capture additional revenue streams beyond electricity sales.
- Sugar-Energy Sector Consolidation:Processing facilities achieve scale economies through shared turbine maintenance infrastructure and centralized bagasse logistics. São Paulo's industrial density supports equipment pooling arrangements.
- Extraction-Condensing Retrofits:Steam turbine upgrades allow simultaneous process steam delivery and power export. Mills monetize thermal energy that previously vented to atmosphere.
Market Restraints
- Certified Technician Scarcity:ANVISA pressure vessel inspection requirements demand specialized labor pools that concentrate in Southeast Brazil. Remote projects face commissioning delays of six to eighteen months.
- Grid Synchronization Standards:Brazilian Electricity Regulatory Agency interconnection rules impose technical compliance costs that disadvantage sub-10 MW installations. Distributed generators absorb disproportionate soft costs.
- Natural Gas Price Volatility:Petrochemical and pulp complexes exposed to import-linked fuel pricing experience margin compression during exchange rate fluctuations. Biomass systems gain relative competitiveness.
Strategic Opportunities
- Minas Gerais Industrial Corridor:Steel and mining clusters outside São Paulo present unserved thermal demand for tri-generation systems. Grid instability in interior regions strengthens onsite reliability premiums.
- ISO 50001 Procurement Filtering:Energy management certification increasingly gates vendor qualification for utility-scale tenders. Early compliance creates preferred supplier positioning.
- Absorption Chiller Integration:Waste heat recovery for cooling applications opens commercial building segments beyond traditional industrial bases. District cooling networks in Campinas and Ribeirão Preto pilot thermal distribution models.
Industry Challenges
- Turbine Maintenance Skill Gaps:OEM service networks control specialized diagnostic capabilities. Independent operators struggle to retain technicians against corporate employment packages.
- Legacy Boiler Integration:Decades-old bagasse combustion systems require extensive civil modifications to accommodate modern extraction-condensing configurations. Retrofit engineering extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Combined Heat and Power Market |
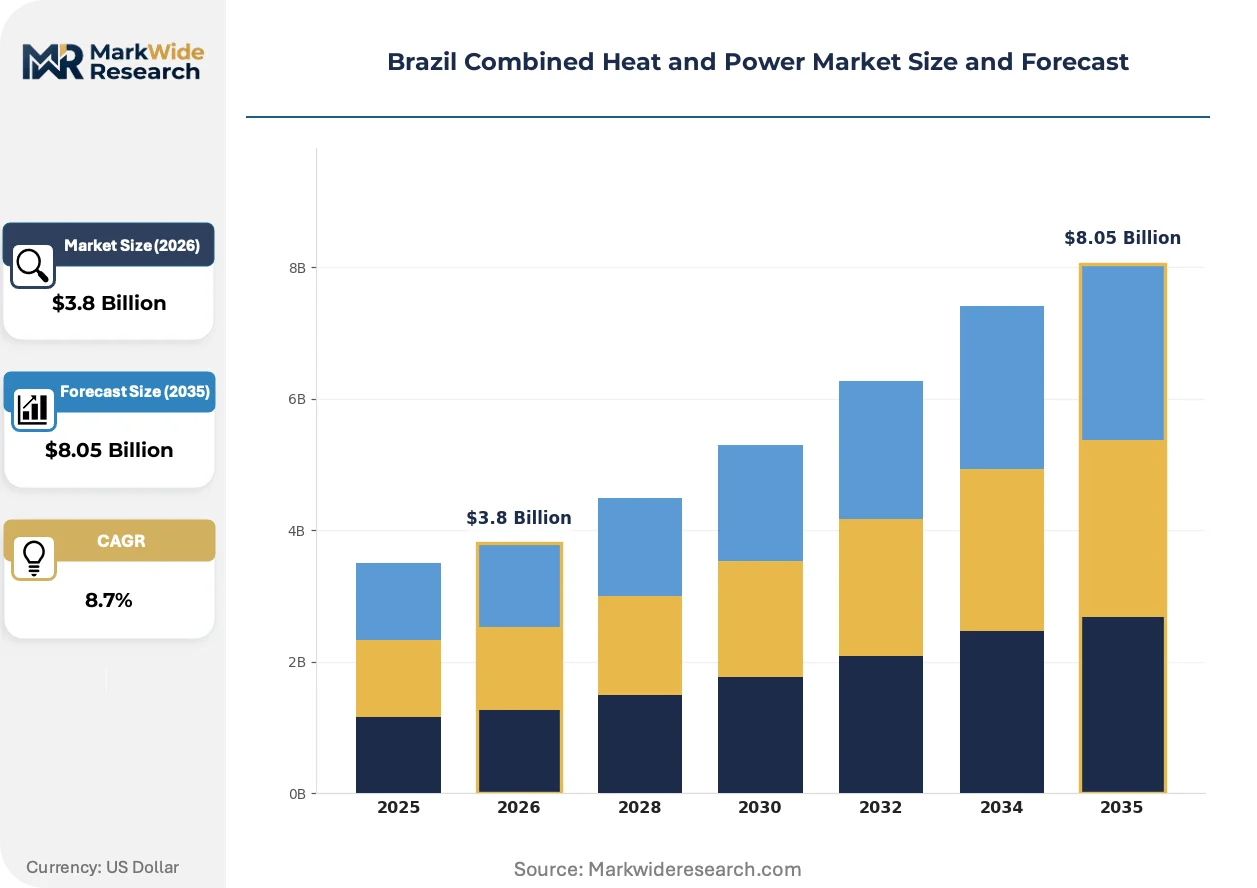
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbines, Steam Turbines, Reciprocating Engines, Microturbines End User: Industrial, Commercial, Residential, Institutional Fuel Type: Natural Gas, Biomass, Coal, Oil Installation: Onsite, District Energy, Compact, Modular |
| Companies Covered | Mitsubishi Heavy Industries, Siemens AG, Cummins Inc., 2G Energy AG, Veolia, Caterpillar Inc., General Electric Company, MAN Energy Solutions SE, CHP Brasil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Combined Heat and Power Market Strategic Shifts
Digital monitoring platforms and modular equipment architectures are compressing deployment cycles while reshaping competitive differentiation between turnkey integrators and component suppliers.
Advanced extraction-condensing steam turbine configurations are bifurcating the technology landscape between high-efficiency greenfield installations and legacy boiler retrofit projects. Sugar mills with capital access deploy 60 MW+ systems with live steam pressures above 100 bar. Facilities with constrained balance sheets remain locked into 22 bar configurations that sacrifice power export revenue for lower upfront investment.
ANVISA pressure vessel certification timelines are extending equipment import lead times by four to seven months. The regulatory friction is forcing partnerships between European OEMs and Brazilian fabricators for localized weld qualification and hydrostatic testing. Vendors with established domestic assembly footprints capture market share in municipal and commercial segments where speed-to-commissioning determines project viability.
Utility procurement departments are unbundling long-term service contracts from initial equipment supply. Buyers negotiate separate agreements for spare parts logistics, remote diagnostics, and scheduled overhauls. The disaggregation is most visible in São Paulo state where sugar-energy groups operate sufficient installed base to justify in-house maintenance capabilities rather than OEM dependency.
Brazil Combined Heat and Power Market Segmentation
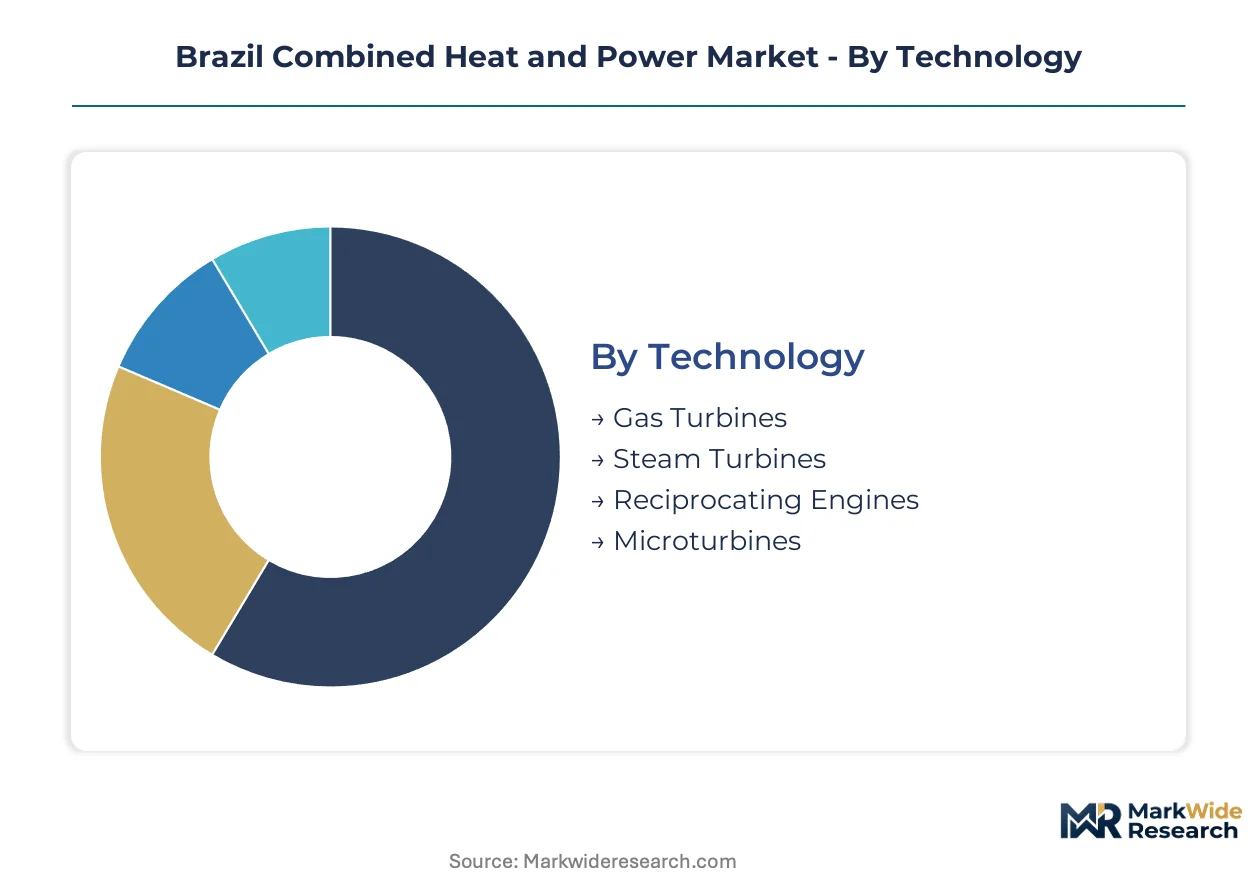
Segmentation in Brazil's Combined Heat and Power Market reveals how technology choices, fuel availability, and installation constraints fragment opportunity across radically different customer economics. Sugar-energy complexes, petrochemical clusters, and municipal utilities each demand configurations that resist standardization.
Technology:
Domestic fabrication capacity concentrates on steam turbine assembly for bagasse applications, while gas turbine imports serve large industrial anchor loads.
- Gas Turbines:These systems achieve rapid start capabilities and scale efficiently to 300 MW for petrochemical and pulp complexes. São Paulo's industrial corridor absorbs the majority of deployments where grid interconnection standards favor centralized thermal blocks.
- Steam Turbines:Extraction-condensing configurations dominate sugar mill retrofits, enabling simultaneous process steam delivery and power export. ANVISA pressure vessel certification requirements extend lead times for high-pressure live steam systems above 100 bar.
- Reciprocating Engines:Modular diesel and gas-fired units serve commercial buildings requiring sub-5 MW reliability backup.
- Microturbines:Compact 25-500 kW systems target distributed commercial installations with limited thermal demand profiles.
Steam turbines hold the largest share; momentum sits with gas turbines as petrochemical expansions accelerate in the Southeast.
End User:
Cost tier stratification separates capital-intensive industrial installations from commercial adopters financing through energy service contracts.
- Industrial:Sugar mills, petrochemical complexes, and pulp facilities anchor demand through captive fuel supplies and 24/7 thermal baseload requirements. São Paulo state's sugar-energy sector consolidates around shared maintenance infrastructure.
- Commercial:Hotels, hospitals, and shopping centers deploy smaller systems where absorption chilling converts waste heat into air conditioning. District cooling pilots in Campinas validate thermal distribution economics.
- Residential:Limited penetration reflects unfavorable scale economics and net metering tariff structures that disadvantage sub-100 kW generators.
- Institutional:Universities and government facilities pilot microturbine installations for resilience demonstration projects.
Industrial users dominate installed capacity; commercial applications are climbing the fastest as cooling-load economics improve.
Fuel Type:
Supply geography dictates competitive positioning, with bagasse availability concentrating biomass systems in São Paulo while natural gas exposure tracks petrochemical corridor locations.
- Natural Gas:Pipeline-connected industrial users in the Southeast favor this fuel for dispatch flexibility. Exchange rate volatility compresses margins when import-linked pricing spikes.
- Biomass:Bagasse-fired systems monetize agricultural residues through RenovaBio decarbonization credits. Mills with capital access deploy high-pressure configurations maximizing power export revenue.
- Coal:Limited to legacy industrial sites with existing fuel handling infrastructure and environmental compliance grandfathering.
- Oil:Diesel reciprocating engines serve remote mining operations lacking pipeline or grid access in Minas Gerais interior regions.
Biomass leads by installed base; natural gas shows the steepest expansion trajectory as petrochemical capacity additions proceed.
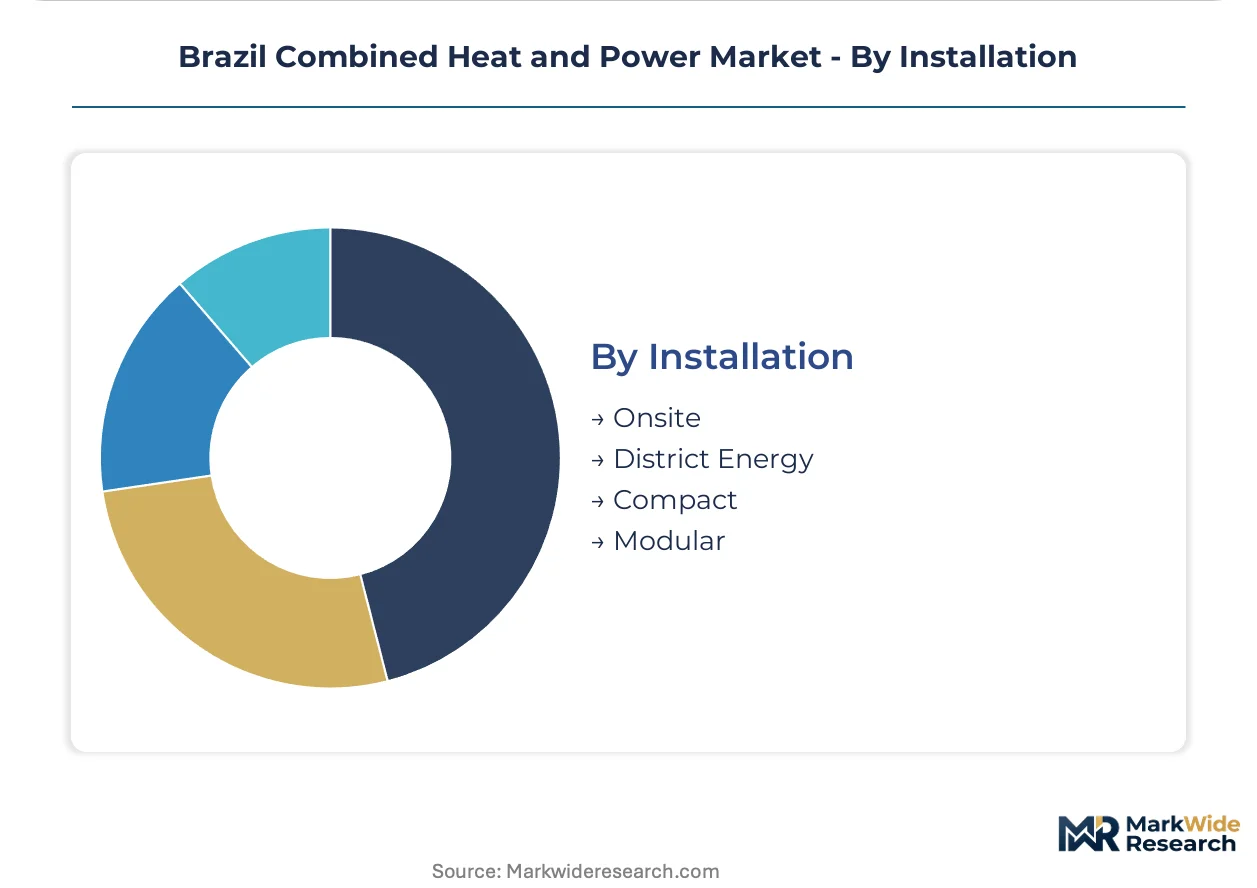
Installation:
Customer type determines whether projects bundle as turnkey engineering contracts or deploy as standardized modular packages.
- Onsite:Turnkey contracts dominate industrial applications, bundling equipment supply with civil works and ANVISA certification management. Extended project timelines reflect legacy boiler integration complexity.
- District Energy:Thermal distribution networks in Campinas and Ribeirão Preto pilot centralized generation serving multiple commercial buildings through insulated piping infrastructure.
- Compact:Pre-engineered sub-10 MW systems reduce commissioning duration for commercial adopters where speed-to-operation determines project viability.
- Modular:Containerized microturbine packages enable rapid deployment for institutional resilience demonstrations and remote industrial outposts.
Onsite installations command the largest share; district energy configurations are gaining share fastest as municipal pilots validate thermal distribution models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA pressure vessel certification requirements concentrate project development in Southeast Brazil, where qualified inspection labor pools and established fabrication partnerships compress equipment commissioning timelines.
São Paulo
Sugar-energy complexes dominate installed capacity through bagasse-fired extraction-condensing retrofits. RenovaBio decarbonization credits improve project economics for mills upgrading from 22 bar to 100 bar live steam configurations. The Ribeirão Preto cluster anchors biomass cogeneration investment, with shared turbine maintenance infrastructure reducing operational costs across processing cooperatives.
Minas Gerais
Steel and mining corridors generate unserved thermal demand for tri-generation systems beyond traditional sugar sector applications. Grid instability in interior regions strengthens reliability premiums for onsite generation at iron ore processing facilities. The Belo Horizonte industrial periphery pilots absorption chiller integration for district cooling networks serving commercial buildings.
Rio de Janeiro
Petrochemical complexes along the Campos Basin absorb gas turbine capacity additions tied to offshore supply chain expansion. Pipeline-connected natural gas infrastructure favors dispatch-flexible generation for 50-300 MW anchor loads. The Brazilian Electricity Regulatory Agency interconnection standards here accommodate centralized thermal blocks more readily than distributed sub-10 MW installations.
Rio Grande do Sul
Pulp and paper mills leverage existing biomass handling infrastructure for black liquor recovery boilers integrated with cogeneration. The state's renewable energy auction mechanisms channel investment toward high-efficiency greenfield steam turbine configurations. Porto Alegre's industrial hinterland consolidates around OEM service networks that sustain long-term maintenance contracts.
Paraná
Soybean processing and meatpacking facilities deploy compact modular systems where speed-to-commissioning determines project viability. Agricultural residue availability outside sugar harvest seasons creates fuel diversification challenges for year-round thermal baseload requirements. The Curitiba metro area tests containerized microturbine packages for institutional resilience demonstrations.
Brazil Combined Heat and Power Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling turnkey engineering capabilities and long-term service contracts while mid-scale fabricators compete on localized assembly speed. Market structure reflects equipment import dependency, as ANVISA certification timelines favor vendors with established Brazilian weld qualification partnerships. Three archetypes dominate: full-system integrators bundling civil works with grid synchronization, component suppliers disaggregating from service obligations, and regional specialists capturing municipal segments through speed-to-commissioning. Competitive intensity centers on maintenance contract retention and extraction-condensing retrofit expertise.
Among German-based industrial conglomerates, Siemens AG and MAN Energy Solutions SE exemplify the integrated leader archetype through localized service networks. Mitsubishi Heavy Industries represents the Asian engineering group positioning around large-scale gas turbine installations. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Siemens AG |
| Cummins Inc. |
| 2G Energy AG |
| Veolia |
| Caterpillar Inc. |
| General Electric Company |
| MAN Energy Solutions SE |
| CHP Brasil |
| Others |
Value Chain & Pricing Dynamics
Shared turbine maintenance infrastructure across São Paulo's sugar-energy cooperatives compresses operational cost floors while concentrating bargaining power among OEM service networks. This scale dynamic bifurcates the market between capital-intensive mills deploying 100 bar live steam systems and smaller operators locked into 22 bar configurations with thinner margin profiles.
Pricing Analysis
Southeast Brazil commands price premiums over interior states due to ANVISA certification proximity and qualified technician density. Project-based contracting dominates, with price differentiation hinging on after-sales service bundling and ISO 50001 compliance tier. Cost compression in sub-10 MW distributed installations intensifies as grid synchronization standards inflate soft costs. Commercial adopters through energy service contracts exhibit highest price sensitivity, while petrochemical complexes prioritize reliability over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision turbine component fabrication, while domestic Brazilian weld qualification partnerships manage ANVISA pressure vessel final assembly. High-alloy steel forgings and advanced blade coatings draw from European and Asian specialist foundries. Single-source vulnerability concentrates in extraction-condensing steam turbine engineering expertise held by incumbent OEMs. Distribution runs through turnkey EPC contractors bundling civil works with grid synchronization services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where ANVISA certification timelines and localized service network density create switching costs that cement incumbent positions against modular challengers.
For Market Incumbents: Fortify maintenance contract retention through predictive diagnostics platforms that reduce unplanned downtime for sugar-energy cooperatives. Expand backward integration into Brazilian weld qualification partnerships to compress ANVISA certification timelines against emerging regional specialists. Prioritize extraction-condensing retrofit expertise as legacy boiler integration complexity extends project timelines and deepens customer dependency. For New Entrants and Emerging Players: Remote turbine diagnostic services represent the most penetrable service-layer gap, as incumbent OEMs concentrate premium technicians in São Paulo state. Target Minas Gerais mining corridors where grid instability creates reliability premiums and ANVISA-certified labor scarcity disadvantages established players. Pursue speed-to-commissioning positioning through containerized modular packages for soybean processing facilities in Paraná. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with long-term service contracts across São Paulo's consolidated sugar-energy sector. Five-to-ten year viability favors vendors with established Brazilian fabrication footprints capable of navigating ANVISA localization requirements. Monitor RenovaBio credit mechanism reforms as the primary inflection signal for biomass system competitiveness against natural gas alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Fabrication | ANVISA weld qualification partnerships compress equipment import lead times by enabling localized pressure vessel testing. |
| Long-term Service Contract Disaggregation | Sugar-energy groups with sufficient installed base justify in-house maintenance capabilities rather than OEM dependency. |
| Absorption Chiller Technology Licensing | Waste heat recovery for cooling applications opens commercial building segments beyond traditional industrial bases. |
| RenovaBio Certification Program Alignment | Decarbonization credit mechanisms improve project IRRs and redirect capital toward biomass-based systems. |
| Joint Venture with Regional EPC Contractors | Turnkey bundling of civil works and grid synchronization captures margin pools in municipal and commercial segments. |
Study Parameters
Cross-validation between primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads anchors the qualitative findings against secondary validation through ANEEL regulatory filings, EPE energy planning reports, SEC 10-K disclosures from listed OEMs, and customs import records for turbine components. Bottom-up project pipeline tracking triangulates against top-down macroeconomic modeling across the analysis window.
Sensitivity analysis frameworks test demand elasticity across fuel source, generation capacity tier, project scale, and regional grid type segmentation dimensions. CAGRs derive from installed base depreciation curves and announced capacity additions rather than extrapolated trend fitting. RenovaBio credit pricing volatility and natural gas import-linked exchange rate exposure serve as key forecast input variables.
Underlying assumptions cover ANVISA certification timeline stability and RenovaBio program continuity, with deviation risk concentrated in proposed net metering tariff reforms and exchange rate volatility affecting gas turbine fuel economics. Recalibration cycles align with material shifts in ANEEL distributed generation regulations and RenovaBio credit market liquidity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Electric Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
Gas Condensing Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Power Boiler Market
Boilers
Biomass Boiler Market
Boilers
Boiler Control Solutions Market
Boilers
Hydrogen Boilers Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
Oil-Fired Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
GCC Electric Water Heater Market
Boilers
Combi Boiler Market