
 Combi Boiler Market | 2026-2036
Combi Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Combi Boiler Market Analysis
Installer networks across Western Europe are reshaping how combi boilers reach end users, with regional wholesalers consolidating shelf space around fewer brands. Bosch Thermotechnology leverages its captive distribution in Germany and the Netherlands to lock in retrofit contractors. Vaillant Group anchors premium positioning through dedicated training academies for heating engineers. BDR Thermea Group competes on breadth, spanning budget Baxi labels through upscale De Dietrich lines.
A combi boiler integrates space heating and domestic hot water generation in a single compact unit, typically achieving 90-94% annual fuel utilization efficiency through condensing heat exchanger technology. Gas combi boilers dominate installed base volumes across temperate climates, though electric combi boilers are gaining structural share in markets with decarbonizing grids and tightening NOx emissions limits. Smart thermostat control types now command margin premiums as utilities and regulators push demand-response compatibility, while wall-mounted installation types remain the default in European residential retrofits where floor space is scarce.
The EU ErP Directive and F-Gas Regulation set minimum efficiency tiers and refrigerant phase-down schedules that filter non-compliant products from the single market. The UK's Boiler Upgrade Scheme and Future Homes Standard create parallel compliance tracks that manufacturers must navigate separately from continental CE marking. Stakeholders should monitor how national building codes recalibrate hydrogen-readiness mandates, as this will determine which product architectures survive the next equipment replacement cycle.
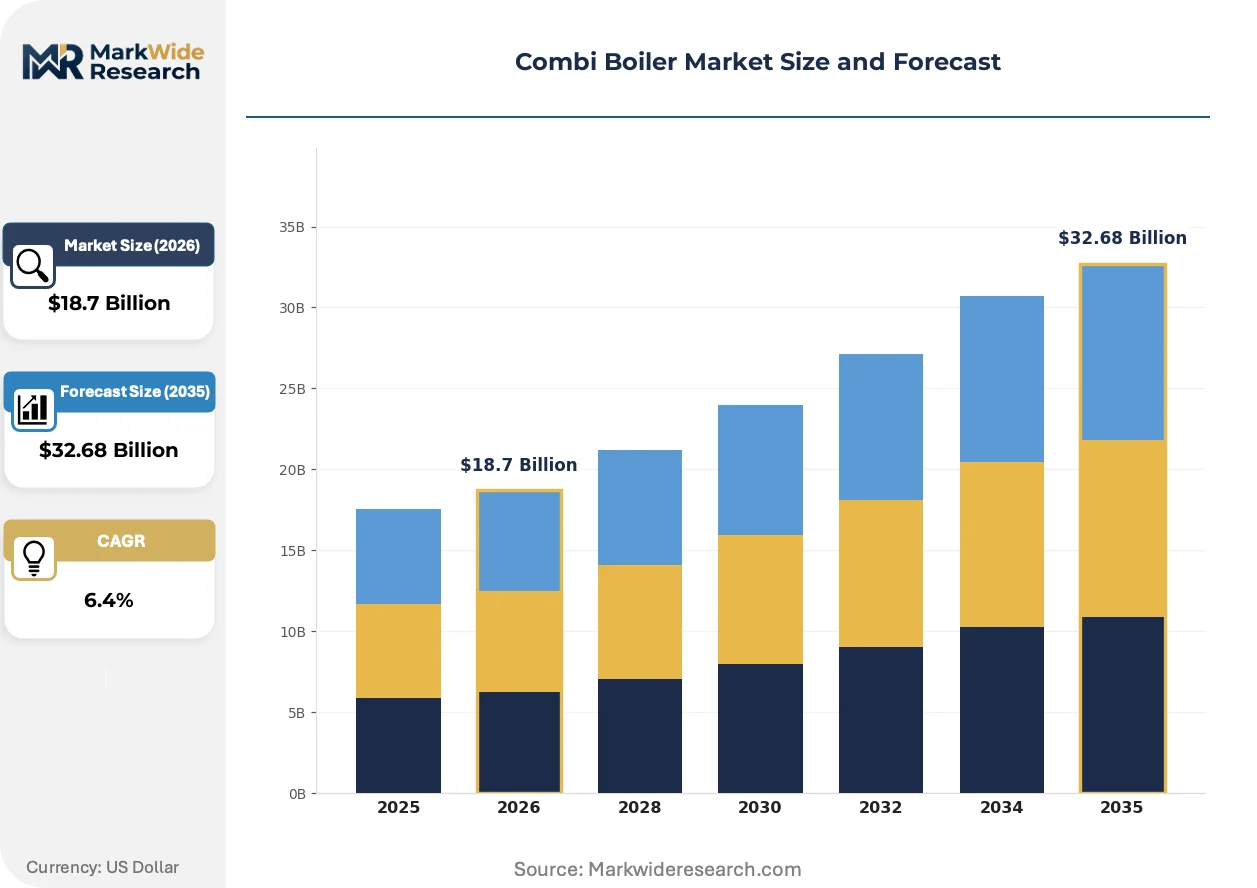
Market Dynamics
EU F-Gas Regulation phase-down schedules and hydrogen-readiness mandates are compressing product lifecycles across the installed base, forcing manufacturers to redesign heat exchanger architectures and control systems ahead of natural replacement cycles.
Growth Catalysts
- ErP Directive efficiency tiers:Minimum performance standards under the EU Energy-related Products Directive are filtering non-condensing models from the single market, accelerating voluntary upgrades among efficiency-conscious homeowners.
- UK Boiler Upgrade Scheme:Grant incentives for low-carbon heating transitions are pulling forward replacement demand among households that would otherwise defer capital expenditure.
- Smart thermostat integration:Demand-response compatibility requirements from utilities are creating specification premiums for connected control systems that modulate output based on grid signals.
Market Restraints
- Copper and stainless steel input costs:Heat exchanger fabrication depends on volatile commodity inputs that compress margin buffers when spot prices spike.
- Installer capacity constraints:Certified heating engineer shortages in Germany and the Netherlands are elongating order backlogs and capping volume throughput regardless of manufacturing capacity.
- Natural gas infrastructure lock-in:Existing distribution networks create path dependency that slows electrification transitions even where grid decarbonization advances.
Strategic Opportunities
- Hydrogen-blend-ready architectures:Products certified for 20% hydrogen injection are capturing specification preference in the Netherlands where grid blending trials advance fastest.
- Heat-as-a-service contracting:Outcome-based models that unbundle equipment ownership from thermal delivery are penetrating social housing portfolios in France.
- Heat pump hybrid systems:Dual-source configurations that switch between gas combi and electric heat pump operation are opening retrofit applications where full electrification proves technically prohibitive.
Industry Challenges
- Hydrogen combustion engineering:Flame stability and NOx control at 100% hydrogen operation requires R&D investment that strains mid-tier engineering budgets.
- CE marking timeline compression:Parallel certification tracks for UKCA and CE conformity are duplicating testing expenditure and extending time-to-market for platform refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combi Boiler Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Combi Boilers, Electric Combi Boilers, Oil Combi Boilers, Instantaneous Combi Boilers Installation Type: Wall-Mounted, Floor-Standing, Compact, Standard Control Type: Smart Thermostats, Manual Controls, Programmable Controls, Remote Access End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Vaillant Group, Bosch Thermotechnology, BDR Thermea Group, Viessmann, A. O. Smith Corporation, Daikin, Wolf GmbH, Fondital, HTP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combi Boiler Market Emerging Trajectories
Condensing technology maturation and refrigerant phase-downs are converging to redefine product architecture, while digital integration and service model unbundling reshape how value reaches end users.
Pre-mix condensing burners with modulating gas valves are rendering obsolete atmospheric combustion designs that dominated the installed base through the 1990s. Social housing landlords and large retrofit contractors are specifying fully modulating systems exclusively. The technology is rendering obsolete fixed-output cast-iron heat exchangers that cannot achieve the 92% minimum efficiency thresholds now required for new installations.
F-Gas Regulation refrigerant phase-down schedules are tightening supply chains for hydrofluorocarbon-dependent components used in some hybrid heat pump systems. Component suppliers are reformulating working fluids and redesigning sealed system architectures to maintain compliance. Heat pump combi hybrids sold into Nordic markets face the steepest certification burden given the region's early adoption of stricter quota allocation mechanisms.
Heating engineers are consolidating specification influence as end users delegate technical selection to trusted installers. Regional wholesaler chains are responding by consolidating shelf space around fewer supplier relationships with deeper training support. France and Belgium exhibit the most pronounced channel concentration, where national distributor mergers have reduced effective brand access points by half over the past decade.
Combi Boiler Market Segmentation
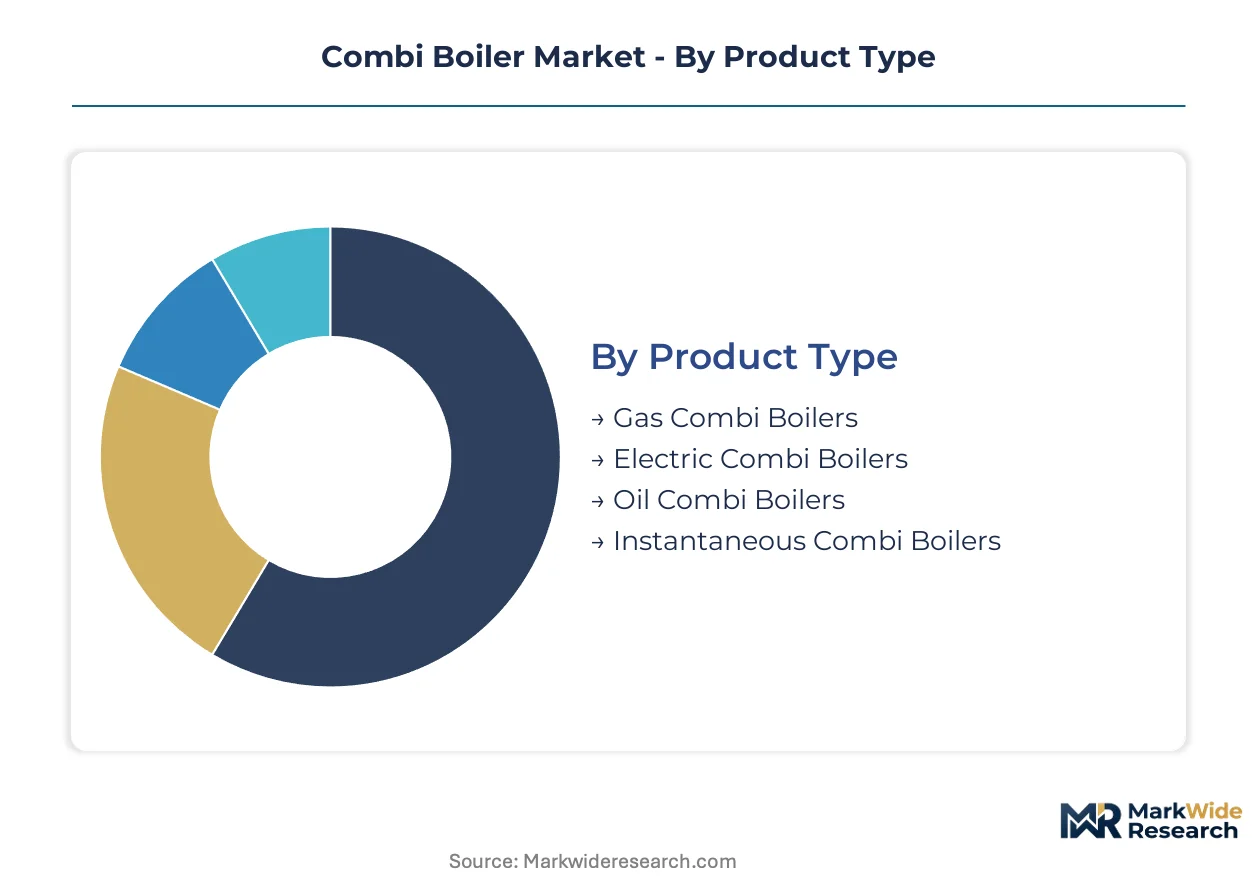
Combi boiler procurement decisions split across technical specifications, spatial constraints, and control sophistication. Installers and specifiers navigate these dimensions simultaneously when matching equipment to building stock age, fuel availability, and end-user sophistication.
Product Type:
Cost tier differentiation separates mass-market gas units from emerging electric alternatives and specialized oil configurations.
- Gas Combi Boilers:Condensing burners with modulating gas valves deliver 90-94% annual fuel utilization efficiency through pre-mix combustion architectures. Demand concentrates in German and UK residential retrofits where natural gas distribution density supports replacement economics, though hydrogen-readiness mandates are compressing product lifecycles ahead of natural replacement cycles.
- Electric Combi Boilers:Resistance heating elements or electrode boilers eliminate combustion emissions entirely, achieving near-unity efficiency at point of use. French and Dutch markets exhibit accelerating specification preference where grid decarbonization advances fastest and NOx emissions limits tighten most aggressively, despite higher operating costs versus gas alternatives.
- Oil Combi Boilers:Retain installed base concentration in rural German and Irish properties beyond natural gas grid reach, with condensing technology now mandatory under ErP Directive minimums.
- Instantaneous Combi Boilers:Eliminate storage cylinder requirements through high-output heat exchangers sized for simultaneous heating and hot water loads.
Gas combi boilers hold installed capacity. Electric combi boilers are rotating up the share rankings.
Installation Type:
Volume distribution across mounting configurations reflects European housing stock density and floor space scarcity.
- Wall-Mounted:Compact heat exchanger assemblies suspended from structural walls dominate residential retrofits where utility room footprints are minimal. UK and Netherlands replacement cycles specify these exclusively for flats and terraced housing, with dry weight limits under 35kg enabling single-installer handling.
- Compact:Reduced-depth cabinets under 300mm project accommodate kitchen cupboard integrations in space-constrained Parisian and Milanese apartments. Belgian and French social housing landlords specify these for standardized portfolio upgrades where every square meter carries opportunity cost.
- Floor-Standing:Larger water content and service access characterize commercial and high-output residential applications.
- Standard:Full-dimension cabinets with integrated expansion vessels and pump sets serve detached housing with dedicated plant rooms.
Wall-mounted units dominate replacement volumes. Compact configurations are climbing the fastest.
Control Type:
Margin structure separates connected systems with demand-response capability from basic thermostatic regulation.
- Smart Thermostats:Modulating controls with weather compensation and occupancy sensing command specification premiums across Dutch and Danish markets where utility demand-response programs compensate load flexibility. OpenTherm protocol compatibility enables boiler-output modulation based on real-time heat loss calculations rather than fixed temperature setpoints.
- Remote Access:Cloud-connected diagnostics and technician-enabled parameter adjustment reduce service call frequency for social housing operators in France and Belgium managing dispersed portfolios.
- Programmable Controls:Time-based temperature scheduling satisfies efficiency-conscious owner-occupiers without connectivity infrastructure requirements.
- Manual Controls:Basic thermostatic radiator valves and dial thermostats persist in price-sensitive replacement segments and landlord-minimum compliance installations.
Smart thermostats hold specification preference in premium retrofits. Remote access capabilities are expanding most quickly among institutional landlords.
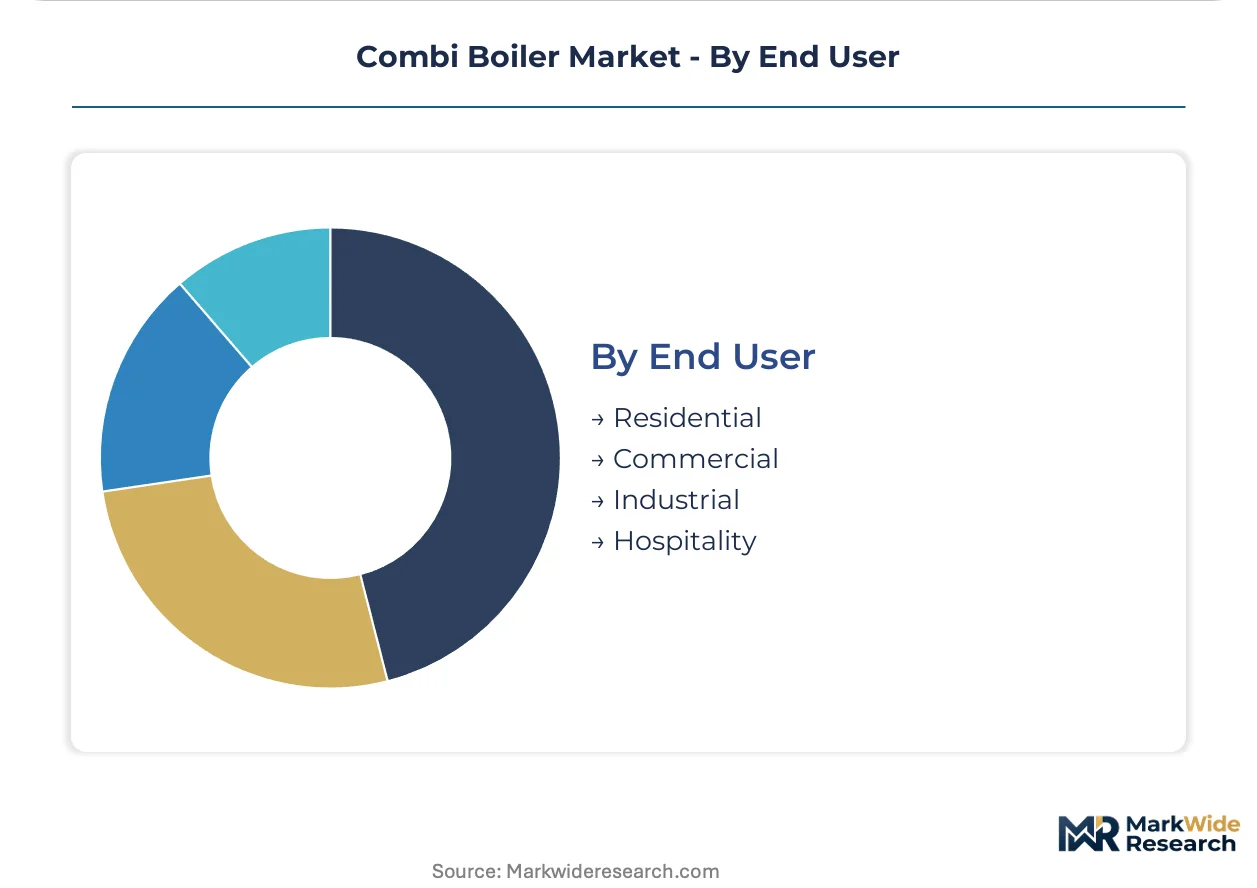
End User:
Customer type determines procurement channel, service contract attachment rates, and equipment lifecycle expectations.
- Residential:Individual homeowners and private landlords drive replacement demand through installer-mediated channel relationships. German and Italian markets exhibit the shortest replacement cycles as efficiency-conscious owners respond to ErP Directive tier upgrades, with average equipment age at replacement now below 12 years.
- Commercial:Small office and retail applications specify mid-output wall-mounted units with extended warranty terms, procuring through mechanical contractor relationships rather than retail plumbing merchants.
- Hospitality:Hotels and restaurants prioritize redundancy and rapid hot water recovery over peak efficiency metrics.
- Industrial:Process hot water and space heating integration in light manufacturing represents niche specification territory.
Residential retrofits anchor volume throughput. Commercial applications are gaining specification share in multi-tenant building service upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers capture pricing premiums through captive distribution networks, while UK installers compete on speed and grant-access navigation rather than technical differentiation. This asymmetry shapes procurement patterns across the two largest replacement markets.
Germany
Aging housing stock in the Ruhr Valley and eastern Länder drives replacement cycles below 12 years average equipment age. The national hydrogen-readiness mandate under the Energy Efficiency Act forces premature heat exchanger redesigns ahead of natural replacement timelines. Manufacturing clusters around North Rhine-Westphalia and Bavaria concentrate R&D investment in 20% hydrogen-blend architectures.
United Kingdom
The Boiler Upgrade Scheme pulls forward demand among households deferring capital expenditure, particularly in Greater London and the Southeast. Future Homes Standard compliance tracks diverge from CE marking, duplicating certification costs for continental suppliers. Installer networks in Manchester and Birmingham consolidate specification influence as end users delegate technical selection.
Netherlands
Grid decarbonization and aggressive NOx limits accelerate electric combi specification preference in Randstad urban cores. Hydrogen blending trials in the northern provinces create first-mover advantage for hydrogen-ready product certifications. Wholesaler consolidation around Rotterdam and Amsterdam reduces effective brand access points by half over the past decade.
Italy
Efficiency-conscious homeowners in Lombardy and Veneto respond fastest to ErP Directive tier upgrades, shortening replacement cycles. The national building code recalibration toward hydrogen-readiness remains pending, creating regulatory uncertainty for equipment planning. Industrial clusters around Milan and Turin specialize in compact wall-mounted configurations for space-constrained Mediterranean housing.
France
Social housing landlords in Île-de-France and Auvergne-Rhône-Alpes specify heat-as-a-service contracting models that unbundle equipment ownership from thermal delivery. The RE2020 environmental regulation tightens new-build efficiency requirements, though retrofit incentives lag continental counterparts. Training academies in Lyon and Paris anchor installer specification influence in premium segments.
Combi Boiler Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying heat exchangers, burners, and control modules to assembly operations. The vendor base concentrates around German and Dutch headquarters with captive distribution networks, while mid-tier competitors compete on price through wholesale merchant channels. Three archetypes dominate: full-system integrators with training academy investments; multi-brand portfolio owners spanning premium through economy tiers; and regional specialists with deep installer relationships. M&A activity targets hydrogen-readiness engineering capabilities, while strategic partnerships lock in heat pump hybrid system supply chains.
Among German-based platform integrators, Vaillant Group and Bosch Thermotechnology exemplify the training-academy archetype, embedding specification influence through certified heating engineer networks. BDR Thermea Group represents the multi-brand portfolio structure, spanning budget labels through upscale lines without unified corporate branding. These three anchors illustrate how competitive positioning depends on channel control depth rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Vaillant Group |
| Bosch Thermotechnology |
| BDR Thermea Group |
| Viessmann |
| A. O. Smith Corporation |
| Daikin |
| Wolf GmbH |
| Fondital |
| HTP |
| Others |
Supply Flow & Price Mechanics
North Rhine-Westphalia's manufacturing corridor concentrates heat exchanger fabrication capacity, giving incumbent assemblers pricing leverage over mid-tier competitors sourcing from merchant suppliers. The region's captive foundry networks translate into 15-20 point margin advantages on configured-to-order systems versus standard catalog units.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standard catalog configurations, with customization for hydrogen-readiness certification and smart thermostat integration driving the spread. Three-tier pricing structure across premium, standard, and economy levels separates Vaillant and Bosch offerings from Baxi budget lines and white-label imports. Cost compression in the economy tier is intensifying because Turkish and Polish assemblers are flooding wholesale channels with ErP-minimum condensing units. Social housing landlords exhibit the highest price sensitivity, while efficiency-conscious German owner-occupiers show willingness to pay for modulating controls and extended warranties.
Supply Chain Analysis
Contract manufacturing concentrates among Austrian and Czech metal-forming specialists that stamp stainless steel heat exchanger assemblies for German platform integrators. Final assembly draws from copper tubing sourced from Bulgarian mills, electronic control modules from Hungarian EMS providers, and gas valves from Italian precision component houses. Single-source vulnerability runs through Austrian heat exchanger stampers serving multiple competing brands. Distribution runs through national wholesaler chains that have consolidated shelf space around fewer supplier relationships with deeper training academies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The combi boiler market is entering a cyclical recovery phase as EU F-Gas Regulation phase-downs and hydrogen-readiness mandates force premature replacement cycles ahead of natural equipment lifespans.
For Market Incumbents: Insulate specification influence by deepening captive installer academy investments before hydrogen-blend certifications become table stakes. Secure backward integration into heat exchanger stamping capacity to offset margin compression from volatile stainless steel input costs. Mid-tier Polish and Turkish competitors threaten volume positions in the economy tier through wholesale channel price aggression. For New Entrants and Emerging Players: Build out heat-as-a-service contracting capabilities targeting French and Belgian social housing landlords seeking to unbundle equipment ownership from thermal delivery. Electric combi specification preference in Dutch Randstad urban cores represents the most penetrable geography, given grid decarbonization tailwinds and aggressive NOx limits that disadvantage gas alternatives. A direct contracting model bypassing traditional wholesale channels offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orphaned heating divisions lacking hydrogen-readiness R&D investment. The five-to-ten year viability window favors platform integrators with installed base lock-in through connected control ecosystems. Hydrogen combustion engineering talent scarcity at mid-tier competitors serves as the primary acquisition target archetype. Certification timeline compression across parallel UKCA and CE marking tracks signals margin pressure that will force portfolio rationalization among sub-scale players. Watch for quarterly order backlog elongation at German and Dutch installers as the inflection indicator for demand-supply imbalance.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Blend Certification Investment | 20% hydrogen-ready architectures capture specification preference in Dutch grid blending trials. |
| Installer Academy Network Expansion | Certified heating engineer pipelines lock in retrofit contractor specification influence against wholesale price competition. |
| Heat Pump Hybrid System Partnership | Dual-source configurations open retrofit applications where full electrification proves technically prohibitive. |
| Heat-as-a-Service Contracting Launch | Outcome-based models penetrate French social housing portfolios by unbundling equipment ownership from thermal delivery. |
| Smart Thermostat Protocol Integration | OpenTherm compatibility enables demand-response revenue streams from Dutch and Danish utility programs. |
Methodological Framework
A spread of perspectives from heating engineering contractors, social housing procurement directors, wholesaler category managers, and OEM platform engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EU ErP Directive compliance databases, F-Gas Regulation quota allocation filings, and national building code recalibration notices. Customs data on heat exchanger component trade flows, SEC filings from listed HVAC parent companies, and utility demand-response program enrollment statistics anchored volume triangulation. Bottom-up equipment shipment tallies and top-down replacement cycle modeling were cross-referenced for convergence.
Demand-supply balance across the analysis window reflects replacement cycle acceleration from regulatory mandates rather than natural equipment failure rates. Segmentation dimensions modeled include fuel type, installation configuration, control sophistication, and end-user procurement channel. CAGRs were derived from regression against historical retrofit penetration rates and forward projection of hydrogen-readiness mandate timelines. Hydrogen blending trial advancement rates and certified installer capacity growth curves served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Turkish assemblers or accelerated heat pump substitution would shift outcomes. Quarterly review of installer order backlogs, hydrogen certification approval velocities, and wholesale inventory turns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
US Industrial Boiler Market
Boilers
Circulating Fluid Bed Boilers Market
Boilers
Oil-Fired Boiler Market
Boilers
Fuel Operated Heaters Market
Boilers
US Commercial Boiler Market
Boilers
Space Heating Boilers Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
US Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Waste Heat Boiler Market
Boilers
Utility Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Boiler Control Market
Boilers
Residential Boiler Market