
 Commercial Boiler Market | 2026-2036
Commercial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Boiler Market Intelligence
Healthcare systems are reorganizing capital allocation toward energy-efficient heating infrastructure, displacing traditional hospitality-led procurement cycles. Cleaver-Brooks dominates the North American institutional segment through specialized fire-tube configurations. Bosch Thermotechnology anchors European demand with advanced condensing platforms. Vaillant Group extends its position across modular installation formats in commercial retrofit projects.
A commercial boiler is a pressurized vessel engineered to generate hot water or steam for space heating, process loads, or domestic hot water in non-residential buildings, typically operating at pressures up to 160 psig and thermal outputs ranging from 300,000 to 75,000,000 BTU per hour. Steam boilers retain structural importance in manufacturing end-use applications where process heat requirements exceed hydronic system capabilities. Condensing boilers capture latent heat from flue gases and represent the fastest-expanding technology segment as efficiency mandates tighten across jurisdictions. Natural gas-fired systems occupy the dominant share of new installations, though biomass technology gains traction in districts with established feedstock supply chains.
The EPA enforces emissions limits under New Source Performance Standards that compel nitrogen oxide reductions in commercial boiler fleets across the United States. The EU F-Gas Regulation and Ecodesign directives progressively restrict greenhouse gas intensity in heating equipment sold throughout Europe. The International Energy Agency and ISO 15500 standards shape product certification pathways for cross-border equipment trade. Stakeholders must monitor evolving carbon border mechanisms and local building performance standards when configuring regional manufacturing and distribution strategies.
Market Dynamics
Condensing technology is compressing the installed base of conventional atmospheric boilers as efficiency mandates harden across jurisdictions. Building retrofit programs and healthcare infrastructure renewal are redirecting procurement specifications toward higher-performance thermal systems.
Growth Catalysts
- EPA New Source Performance Standards:Nitrogen oxide emission limits in the United States are compelling fleet replacements in institutional buildings. Healthcare facilities are accelerating boiler upgrades to maintain air quality permits.
- EU Ecodesign Directive:Progressive efficiency requirements for heating equipment sold in Europe are elevating condensing boiler penetration rates. Germany's building energy codes are tightening minimum performance thresholds for commercial retrofits.
- Natural gas infrastructure density:Distribution network expansion in China's urban clusters is enabling gas-fired boiler deployment in manufacturing zones previously dependent on coal combustion.
Market Restraints
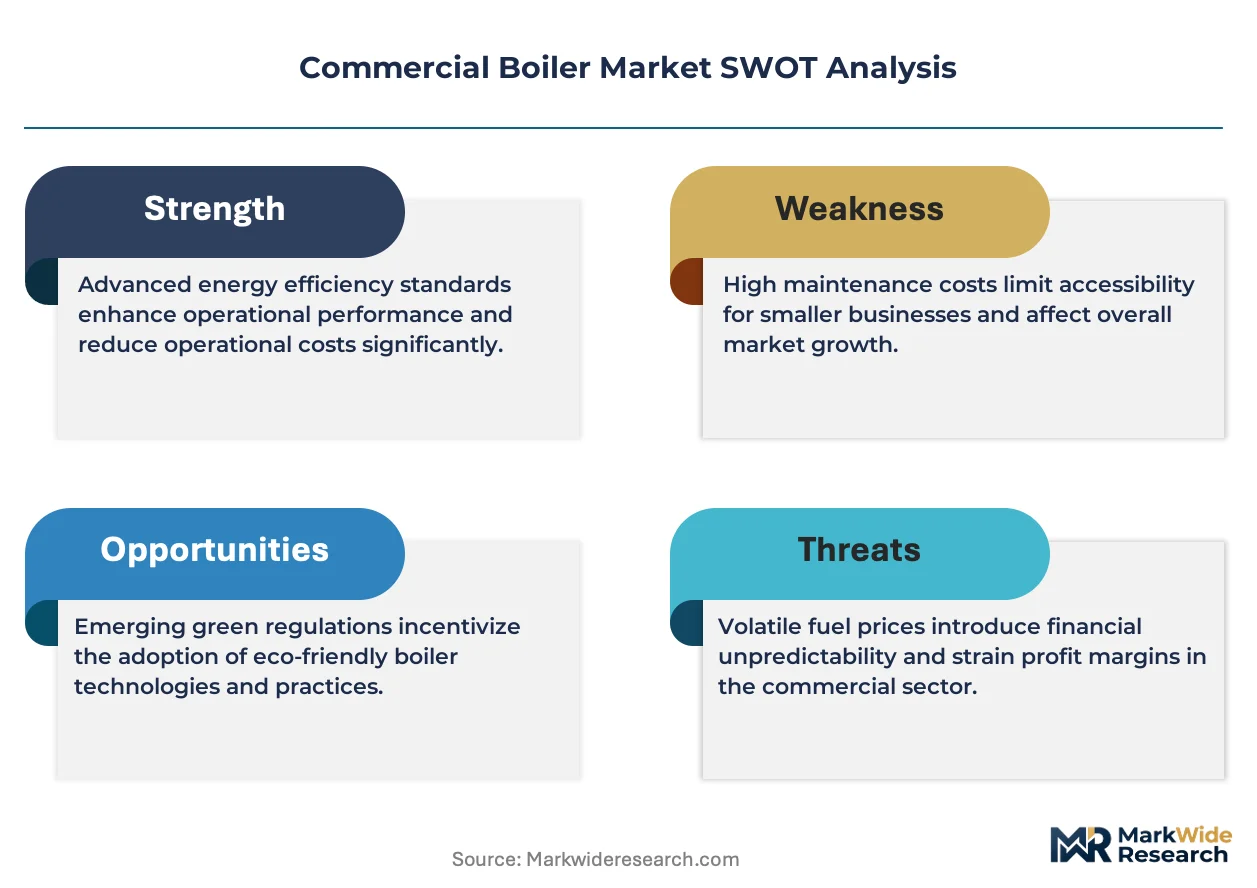
- Stainless steel alloy volatility:Heat exchanger material costs fluctuate with nickel and chromium spot markets. Fabricators face margin compression when input prices spike without contract pass-through mechanisms.
- Skilled technician scarcity:Condensing system commissioning requires specialized combustion analysis expertise. The qualified installer pool concentrates in mature European markets and major North American metropolitan corridors.
- Biomass feedstock inconsistency:Solid fuel boiler viability depends on localized supply chain reliability. District heating operators in Scandinavian markets encounter seasonal moisture content variation that degrades combustion efficiency.
Strategic Opportunities
- Modular cascade configurations:Small-footprint boiler arrays are penetrating urban commercial retrofits where plant room space constraints previously blocked replacement projects. United Kingdom building services contractors are specifying twin-module systems for hospitality renovations.
- Hydrogen-ready burner development:Dual-fuel combustion technology is positioning installed bases for grid decarbonization pathways. Dutch district heating operators are piloting hydrogen blending trials in existing natural gas infrastructure.
- Remote monitoring integration:IoT-enabled predictive maintenance platforms are unbundling traditional service contracts. French facility management firms are adopting outcome-based thermal performance agreements.
Industry Challenges
- Condensate neutralization compliance:Acidic discharge from high-efficiency systems requires pH treatment before sewer release. Municipal plumbing codes in multiple United States jurisdictions lack harmonized disposal standards.
- Legacy control integration:Building automation system interoperability demands proprietary protocol translation. Hospital energy managers encounter commissioning delays when merging new boiler controls with existing Siemens or Johnson Controls networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Boiler Market |
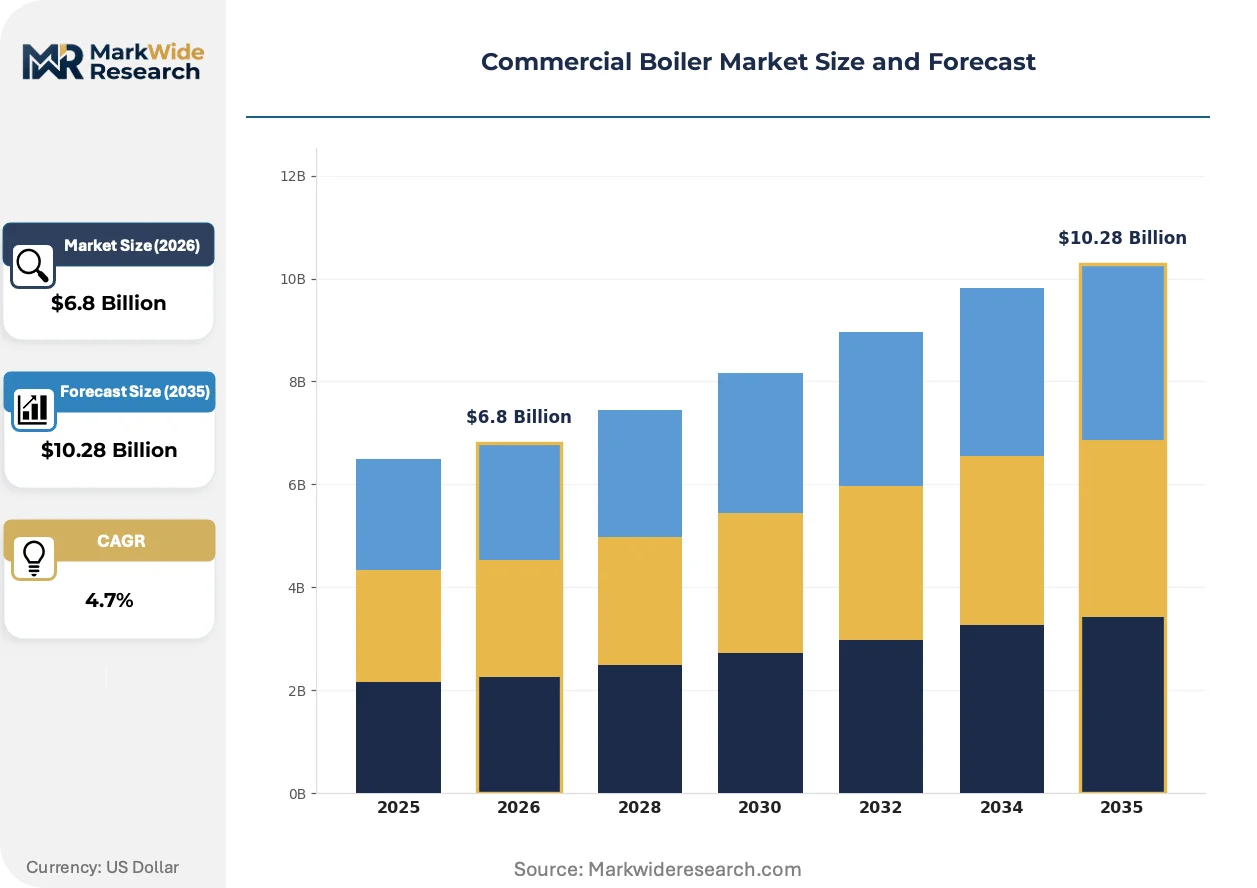
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Water Boilers, Steam Boilers, Condensing Boilers, Fire-Tube Boilers Technology: Natural Gas, Propane, Biomass, Electric End User: Manufacturing, Hospitality, Healthcare, Education Installation: Indoor, Outdoor, Modular, Centralized |
| Companies Covered | A.O. Smith Corporation, Bosch Thermotechnology, Cleaver-Brooks, Fulton Boiler Company, Cochran Limited, Vaillant Group, Superior Boiler Works, Weil-McLain, Parker Boiler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Boiler Market Strategic Shifts & Innovations
Digital combustion optimization and low-NOx burner architectures are redefining performance benchmarks across the commercial thermal equipment sector. Equipment specification is pivoting from capital cost minimization toward lifecycle carbon intensity metrics.
Condensing heat exchanger technology is decomposing the traditional efficiency ceiling of non-recuperative boiler designs. Healthcare and university facilities in Germany and the northeastern United States are specifying fully condensing systems as baseline requirements. The technology is decomposing the market position of mid-efficiency atmospheric boilers in jurisdictions with active building performance standards.
REACH chemical registration requirements in Europe are restricting combustion catalyst materials and sealant compounds used in burner assemblies. Manufacturers are reformulating product lines to eliminate restricted substances ahead of sunset dates. The regulatory pressure is most acute for export-oriented fabricators serving multiple continental markets with single stock-keeping units.
Specification authority is migrating from mechanical contractors toward energy performance consultants and sustainability officers. Engineering firms are displacing traditional wholesaler influence in large institutional procurements. This behavioral shift is most visible in United States healthcare system capital planning departments and United Kingdom local authority decarbonization programs.
Commercial Boiler Market Segmentation
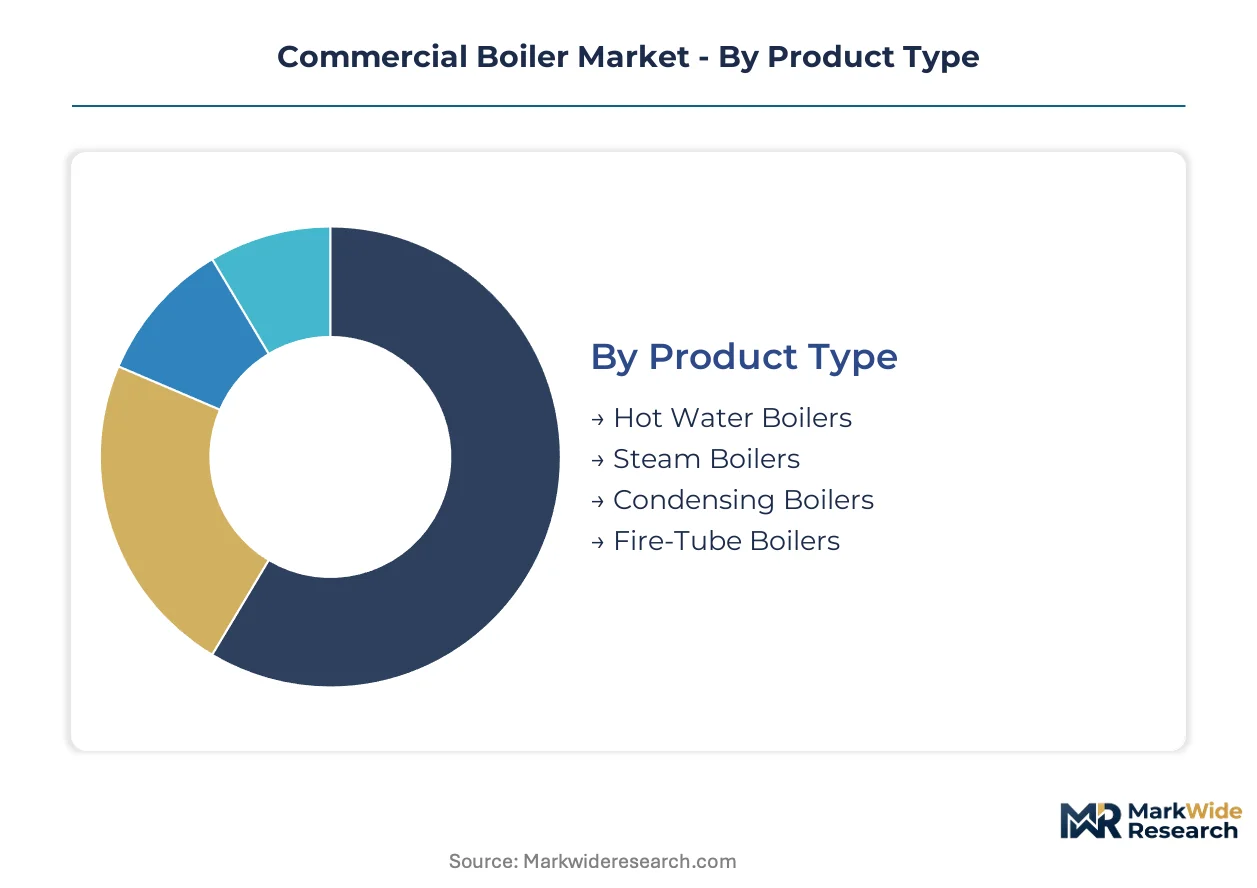
Commercial boiler procurement decisions fragment across thermal output requirements, fuel infrastructure availability, and regulatory compliance obligations. Specification authority varies dramatically by building type, with healthcare and education procurement committees imposing stricter efficiency benchmarks than manufacturing facilities.
Product Type:
Margin pools concentrate in condensing configurations where efficiency premiums justify higher equipment costs through operational savings.
- Condensing Boilers:These systems capture latent heat from flue gases through secondary heat exchangers, achieving thermal efficiencies above 90 percent. Healthcare facilities in Germany and the northeastern United States specify condensing units as baseline requirements under tightening building energy codes.
- Steam Boilers:Pressurized vessels generate saturated steam for process applications requiring temperatures exceeding hydronic system limits. Manufacturing plants in China's industrial clusters deploy steam boilers for sterilization and chemical processing where thermal loads exceed hot water capabilities.
- Hot Water Boilers:Low-pressure hydronic systems dominate space heating applications across commercial building stock.
- Fire-Tube Boilers:Combustion gases pass through tubes immersed in water, offering simpler maintenance protocols for institutional facilities.
Steam boilers hold installed capacity across legacy manufacturing infrastructure. Condensing boilers are rotating up the share rankings as retrofit programs accelerate.
Technology:
Application requirements dictate fuel selection, with natural gas infrastructure density determining viable technology choices in urban versus rural deployments.
- Natural Gas:Distribution network availability anchors technology selection in metropolitan corridors across the United States, Germany, and China. EPA New Source Performance Standards and EU Ecodesign directives are compressing the addressable market for conventional atmospheric gas burners.
- Biomass:Solid fuel systems depend on localized feedstock supply chains with consistent moisture content. District heating operators in Scandinavian markets encounter seasonal combustion efficiency degradation when wood chip quality fluctuates.
- Propane:Liquefied petroleum gas serves rural commercial buildings beyond natural gas pipeline reach.
- Electric:Resistance and electrode boilers penetrate markets with low-carbon electricity grids or strict indoor air quality requirements.
Natural gas retains dominant share in new installations. Biomass is climbing the fastest in districts with established forestry processing infrastructure.
End User:
Capital allocation cycles and regulatory exposure vary sharply across building types, with healthcare and education facing stricter emissions compliance timelines.
- Healthcare:Hospital systems reorganize capital planning around energy performance consultants rather than traditional mechanical contractors. EPA nitrogen oxide limits compel fleet replacements to maintain air quality permits.
- Education:University facilities specify fully condensing systems under sustainability mandates. Campus central plant operators prioritize lifecycle carbon intensity metrics over first-cost minimization.
- Manufacturing:Process heat requirements sustain demand for high-pressure steam configurations.
- Hospitality:Hotel renovation projects favor modular cascade configurations where plant room space constraints block conventional replacement pathways.
Manufacturing holds legacy thermal capacity. Healthcare is gaining share fastest as emissions compliance deadlines tighten.
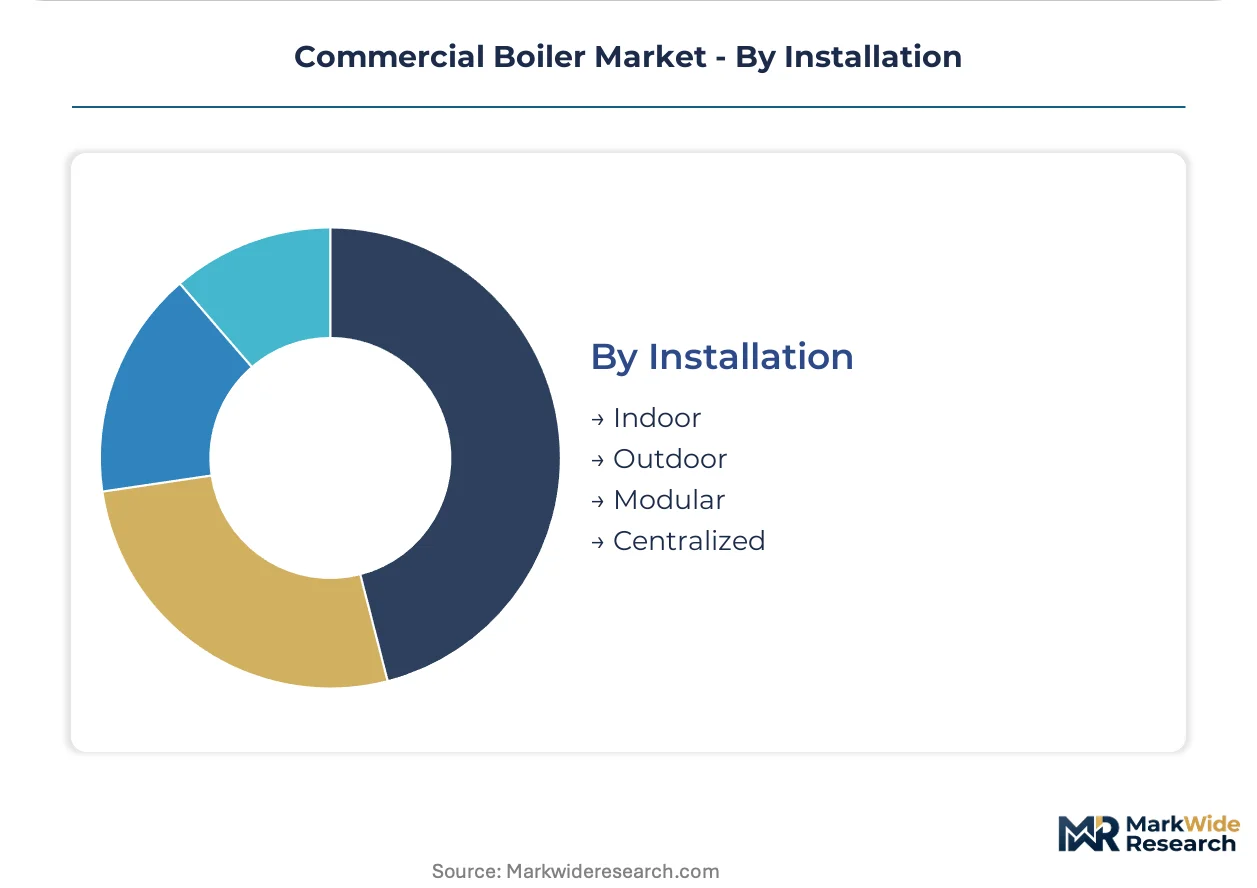
Installation:
Physical constraints and redundancy requirements shape configuration selection, with urban retrofits driving modular format adoption.
- Modular:Small-footprint boiler arrays enable phased capacity expansion and maintenance redundancy. United Kingdom building services contractors specify twin-module systems for hospitality renovations where single large units cannot navigate existing plant room access routes.
- Centralized:Single large-capacity units serve campus and district heating applications with dedicated boiler houses. University central plants in Germany favor centralized configurations for operational simplicity.
- Indoor:Weather-protected installations dominate institutional building stock.
- Outdoor:Weatherized enclosures serve manufacturing facilities with limited interior mechanical space.
Centralized configurations hold capacity across legacy campus infrastructure. Modular formats are rotating up the share rankings as urban commercial retrofits multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in Germany, the United States, and China, with each geography responding to distinct regulatory timelines and infrastructure constraints. Healthcare retrofit mandates and building energy code tightening are redirecting procurement flows across these three demand centers.
United States
Hospital systems in Massachusetts and New York are accelerating boiler fleet replacements to comply with EPA New Source Performance Standards. The agency enforces nitrogen oxide emission limits that compel institutional building upgrades. Healthcare facilities in the Northeast Corridor face compressed compliance timelines as air quality permits approach renewal deadlines.
Germany
The EU Ecodesign Directive and national building energy codes are elevating condensing boiler specifications in commercial retrofits. REACH chemical registration requirements restrict combustion catalyst materials in burner assemblies. Industrial clusters in North Rhine-Westphalia and Bavaria anchor European manufacturing capacity for high-efficiency thermal systems.
China
Urban gas distribution network expansion enables natural gas boiler deployment in manufacturing zones previously dependent on coal combustion. The Ministry of Ecology and Environment enforces dual carbon goals that redirect industrial heating procurement. Yangtze River Delta and Pearl River Delta industrial parks represent concentrated demand for process steam applications.
United Kingdom
Building services contractors specify modular cascade configurations for hospitality renovations where plant room access constraints block conventional replacement pathways. Local authority decarbonization programs tighten minimum performance thresholds for commercial retrofits. London and Southeast England concentrate specification authority among energy performance consultants.
Commercial Boiler Market Key Industry Players
Concentration sits with diversified thermal equipment conglomerates and specialized institutional fabricators. The vendor base spans three tiers: multinational HVAC conglomerates with boiler divisions, mid-cap specialists focused on fire-tube and condensing configurations, and regional fabricators serving localized service networks. Dominant competitive moves include hydrogen-ready burner development and IoT-enabled predictive maintenance platform integration.
Within the institutional-specialist tier, Cleaver-Brooks and Fulton Boiler Company occupy positions anchored in North American fire-tube expertise. Bosch Thermotechnology represents the diversified conglomerate archetype with European condensing platform leadership. Vaillant Group exemplifies the modular-system specialist serving commercial retrofit acceleration across multiple continental markets.
| Leading Market Players |
|---|
| A.O. Smith Corporation |
| Bosch Thermotechnology |
| Cleaver-Brooks |
| Fulton Boiler Company |
| Cochran Limited |
| Vaillant Group |
| Superior Boiler Works |
| Weil-McLain |
| Parker Boiler |
| Others |
Cost & Logistics Intelligence
Sixteen-week heat exchanger lead times concentrate procurement leverage among German and Chinese fabricators with captive stainless steel processing. This inventory compression cascades into pricing power for condensing system manufacturers while forcing smaller North American fabricators toward premium alloy spot markets.
Pricing Analysis
EPA New Source Performance Standards dictate the pricing tier structure across institutional procurement channels. Three-tier pricing structure across premium condensing, mid-efficiency, and atmospheric legacy levels separates healthcare systems with compliance deadlines from budget-constrained municipal buildings. Stainless steel alloy volatility is compressing margins in standard-tier equipment because nickel spot price spikes lack contract pass-through mechanisms. Manufacturing facilities exhibit highest price sensitivity due to process heat commoditization, while hospital systems prioritize lifecycle efficiency over first cost.
Supply Chain Analysis
Shanghai port congestion periodically chokes heat exchanger export flows to European assembly plants. Manufacturing concentration clusters in Germany, the United States, and China, with North Rhine-Westphalia and Bavaria anchoring European high-efficiency production. Nickel and chromium alloys, copper tubing, and combustion control modules feed from specialized metallurgical suppliers. Single-source vulnerability sits with precision burner assembly vendors in Northern Italy. Distribution runs through authorized mechanical contractor networks with factory-trained commissioning requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building automation system interoperability is redefining this market as a platform-economics inflection, with BACnet and Modbus protocol integration becoming the decisive specification gate.
For Market Incumbents: Secure hydrogen-ready burner development pipelines ahead of Dutch and German grid blending mandates. Deepen captive heat exchanger production in Germany to offset stainless steel alloy volatility. Bosch Thermotechnology and Cleaver-Brooks must defend against modular-system specialists capturing urban retrofit share through space-constrained cascade configurations. For New Entrants and Emerging Players: Anchor in United Kingdom hospitality renovation channels where plant room access constraints block incumbent centralized units. Target twin-module specifications for London hotel mechanical upgrades. Pursue outcome-based thermal performance contracting to bypass traditional wholesaler relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA and EU Ecodesign tightening guarantees replacement demand regardless of new construction cycles. Acquire mid-cap fabricators with hydrogen combustion IP and established European service networks. Watch hydrogen blending trial results in Dutch district heating as the decisive technology inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Burner Development | Positions installed bases for Dutch and German grid decarbonization pathways. |
| Modular Cascade System Expansion | Captures United Kingdom hospitality retrofits with plant room space constraints. |
| IoT Predictive Maintenance Platform | Unbundles traditional service contracts for French facility management firms. |
| Condensing Heat Exchanger Backward Integration | Insulates margin from nickel and chromium spot market volatility. |
| REACH-Compliant Burner Reformulation | Eliminates restricted catalyst materials ahead of European sunset dates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across the primary research phase. Hospital energy managers, commercial mechanical contractors, district heating operators, and burner assembly engineers provided field-level procurement and specification intelligence. Secondary validation drew from EPA enforcement databases, EU Ecodesign implementation reports, customs trade flows for heating equipment, and manufacturer SEC disclosures. Bottom-up unit shipment estimates triangulated against top-down addressable building stock calculations.
Across the analysis window, volume and value outputs reflect segmented modeling across product type, fuel technology, end-user building category, and installation configuration dimensions. CAGRs derive from regression analysis of historical replacement cycles mapped to regulatory compliance deadline clustering. Forecast inputs incorporate natural gas infrastructure expansion timelines in Chinese urban clusters and healthcare capital allocation survey data from German hospital systems.
Decision-makers should treat outputs as directional under stable alloy pricing and regulatory enforcement continuity assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as hydrogen infrastructure deployment and carbon border mechanism implementations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Global Boiler Market
Boilers
Superheater Market
Boilers
Power Plant Boiler Market
Boilers
Boiler Control Solutions Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Water Tube Industrial Boiler Market
Boilers
US Commercial Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Waste Heat Boiler Market
Boilers
Oil-Fired Boiler Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Superheater Tubes Market
Boilers
Circulating Fluidized Bed Boilers Market