
 Global Industrial Burner Market | 2026-2036
Global Industrial Burner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Burner Market Intelligence
The European Union's Green Deal, with its stringent targets for industrial emissions, is expanding the market for low-NOx and hydrogen-ready burners. Honeywell International Inc. leverages its automation and control systems to offer integrated combustion solutions. John Zink Hamworthy Combustion specializes in custom-engineered solutions for complex process applications. Andritz AG competes with its portfolio of advanced burners designed for biomass and other alternative fuels.
An industrial burner is a mechanical device that mixes fuel and an oxidizer, typically air, to produce a controlled flame for heat generation. These systems are designed for specific heat release rates and flame geometries required in large-scale industrial processes like metallurgy and cement production. Natural gas burners continue to dominate the fuel type segment due to infrastructure availability. Retrofits for power generation facilities represent a significant portion of activity, driven by efficiency upgrade cycles.
Regulations from bodies like the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) set strict limits on NOx and SOx emissions, shaping product design. The EU's REACH regulation also influences the materials and chemicals permissible in burner components and coatings. Vendor selection increasingly hinges on the ability to deliver burners compatible with future fuel sources, particularly hydrogen and biofuels.
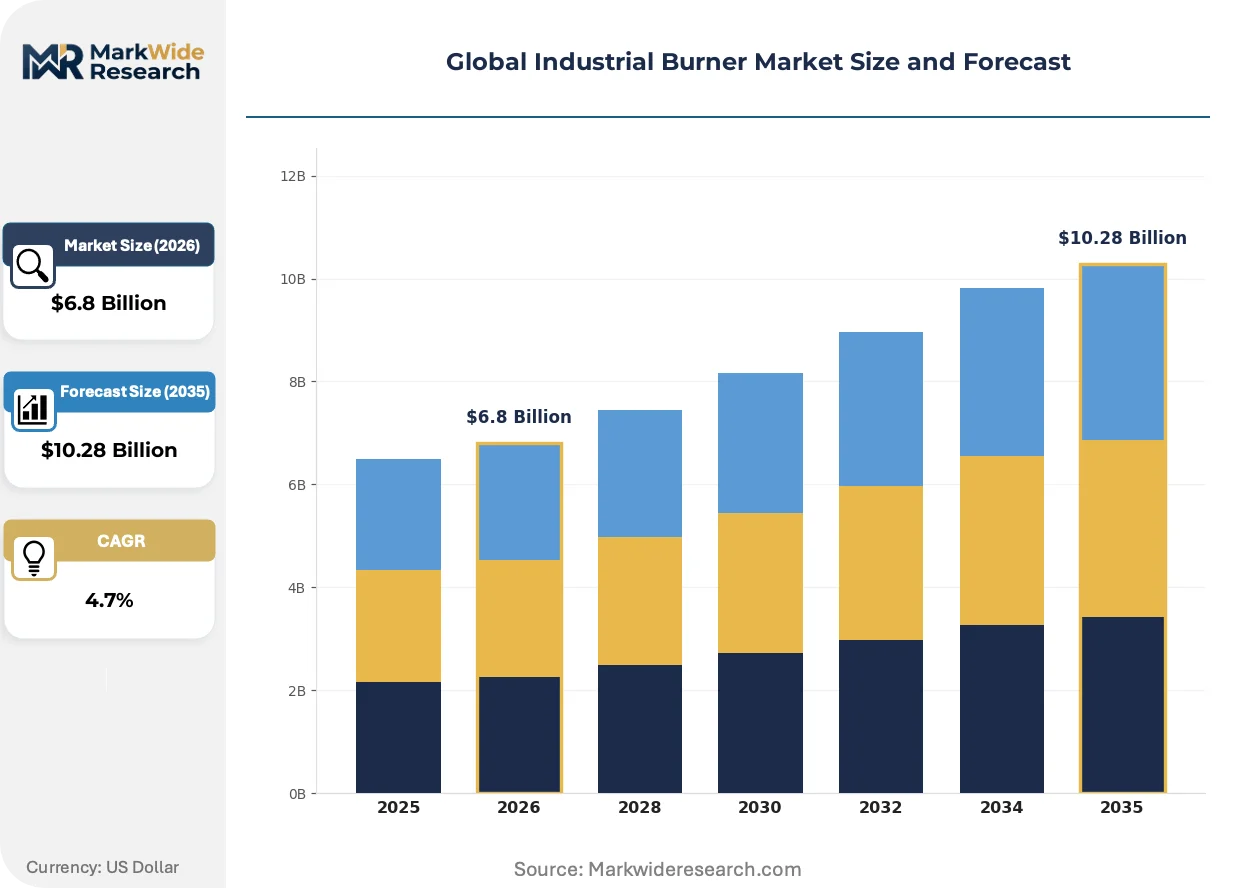
Market Dynamics
The global push for industrial decarbonization, codified in policies like the EU's Green Deal and China's dual carbon goals, is the central force reshaping the industrial burner market. This pressure mandates designs compatible with alternative fuels and accelerates the obsolescence of legacy systems.
Growth Catalysts
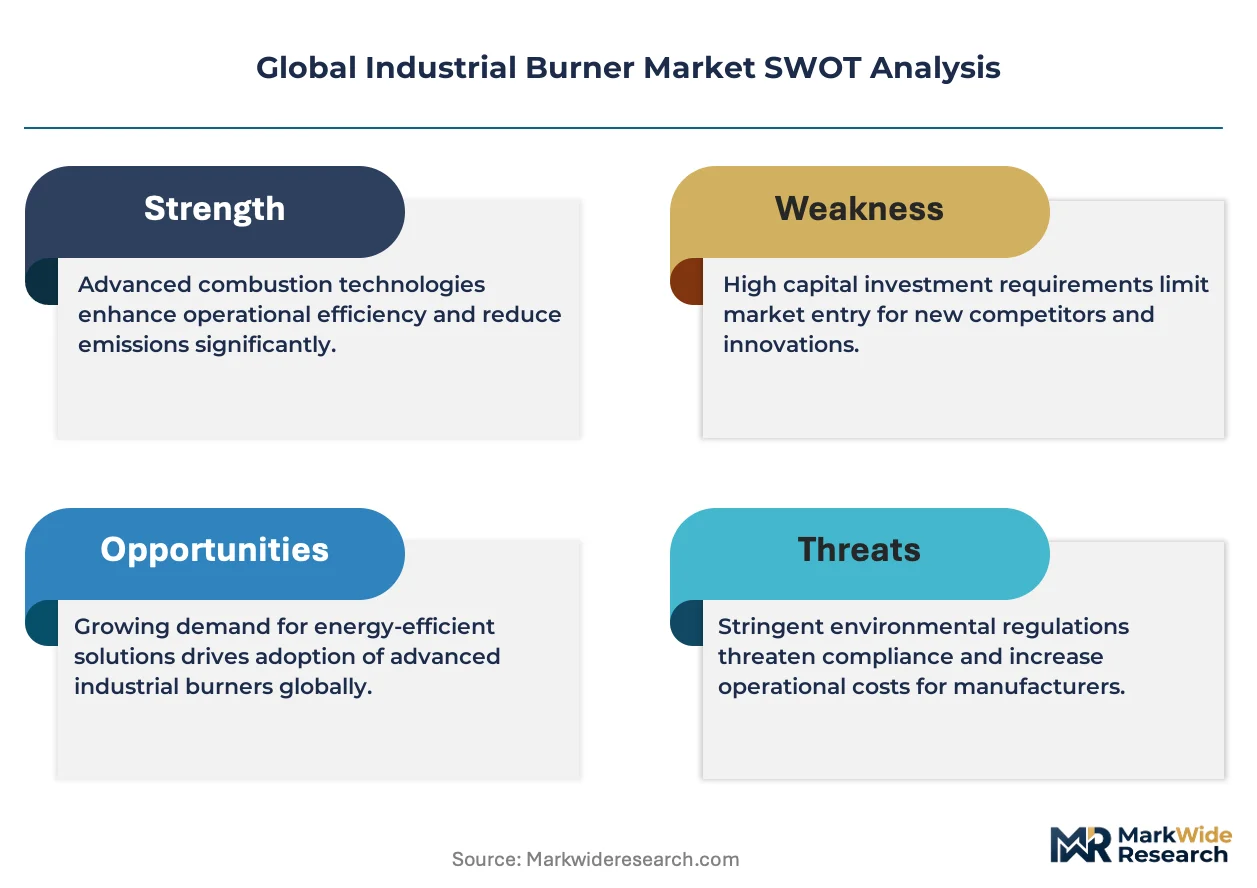
- Chinese National Goals:China's dual carbon targets are driving mandatory upgrades in the power generation and steel sectors, creating sustained demand for high-efficiency, low-NOx burners to replace older, less compliant equipment.
- Indian Manufacturing Expansion:National manufacturing initiatives in India are boosting capital investment in new cement, steel, and chemical plants, directly pulling demand for industrial burners for greenfield projects.
- Power Generation Retrofits:The cyclical nature of efficiency upgrades in existing natural gas power plants, particularly in the United States, provides a consistent stream of large-scale retrofit projects for advanced burner systems.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for advanced low-NOx or hydrogen-ready burner systems, including control system integration, deters adoption in cost-sensitive industries like food processing.
- Material Science Limitations:The challenge of hydrogen embrittlement in existing metal alloys and components limits the immediate, widespread deployment of burners designed for high-concentration hydrogen blends.
- Inconsistent Regulatory Timelines:A lack of harmonized global standards for hydrogen and biofuel blends creates uncertainty for manufacturers, slowing investment in product development for future fuel compatibility.
Strategic Opportunities
- Carbon Capture Integration:Designing burners for oxy-combustion processes, which use pure oxygen instead of air, presents an opportunity as it simplifies downstream CO2 capture in cement and power generation facilities.
- EU Green Deal Mandates:The European Union's stringent emissions targets for industrial sites create a guaranteed market for best-available-technology retrofits, particularly for hydrogen-ready and ultra-low NOx burners.
- Biomass Fuel Systems:Expanding portfolios to include advanced burners for biomass gasification in Southeast Asian pulp and paper mills addresses a regional need for waste-to-energy solutions.
Industry Challenges
- Combustion Engineering Skill Gap:A shortage of skilled combustion engineers and technicians capable of commissioning and tuning complex, multi-fuel burner systems creates installation bottlenecks and service delays for end-users.
- Legacy System Integration:Integrating modern, digitally controlled burners with older, analog plant control systems in brownfield sites poses significant technical complexity and cost overruns for retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Burner Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Burner Type: Furnace Burners, Boiler Burners, Process Burners, Infrared Burners Fuel Type: Natural Gas, Diesel, Propane, Biofuel, Fuel Oil Application Sector: Metallurgy, Cement Production, Power Generation, Food Processing Installation Mode: New Setup, Retrofit, Mobile Units, Fixed Units |
| Companies Covered | Oilon Group Oy, John Zink Hamworthy Combustion, Honeywell International Inc., Bloom Engineering Inc., Riello S.p.A., Weishaupt Corp., Andritz AG, Power Flame Inc., Baltur Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Burner Market Strategic Shifts & Innovations
Fuel-agnostic design and digital twin integration are altering product development priorities. The focus is shifting from optimizing for a single fuel source to ensuring operational resilience and emissions compliance across a future mix of energy inputs.
Digital twin technology creates a virtual replica of a physical burner system, allowing for real-time performance monitoring and predictive maintenance simulation. Operators in the power generation and petrochemical sectors are adopting this technology to optimize combustion and minimize unplanned downtime. The integration of sensor data and simulation software is consolidating the market for burner systems with integrated automation and control packages, squeezing out purely mechanical hardware vendors.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure of industrial emissions and decarbonization strategies. This forces companies to quantify the emissions performance of their combustion assets, creating direct accountability for capital expenditure on cleaner technologies. The metallurgy and chemicals sectors are most affected, now prioritizing burners with verifiable, low-emission performance data to meet their new reporting obligations.
End-users are increasingly specifying burners based on guaranteed emissions performance and fuel flexibility rather than on upfront capital cost alone. This model disrupts the traditional tender process, favoring vendors who can provide long-term service agreements and performance warranties over simple equipment suppliers. This shift is most prominent in the European power generation market, where emissions penalties make performance guarantees a critical procurement criterion.
Global Industrial Burner Market Segmentation
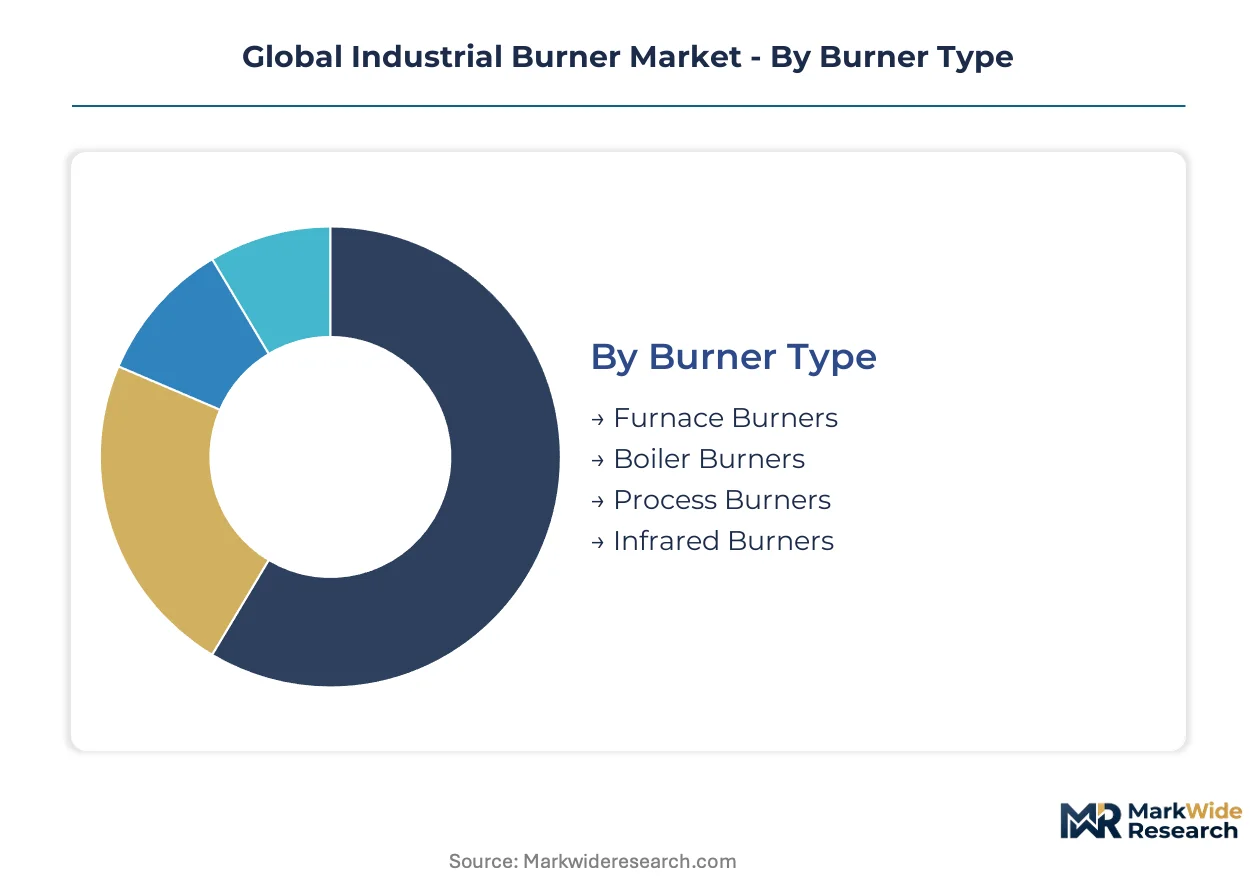
The industrial burner market is segmented to reflect the diverse operational demands and technological requirements across various heavy industries. Understanding these segments provides a granular view of where investment is concentrating and how specific industrial needs drive product development and adoption patterns.
Burner Type:
The selection of an industrial burner type hinges primarily on the specific thermal requirements and operational parameters of the industrial process.
- Furnace Burners:Furnace burners are engineered for high-temperature applications within industrial furnaces, providing uniform heat distribution for processes like metal heat treating. Demand concentrates in metallurgy and glass manufacturing, driven by the need for precise temperature control.
- Boiler Burners:Boiler burners generate steam for power generation and process heating, designed for efficient combustion within boiler fireboxes. Retrofits for existing power generation facilities represent significant activity, particularly in North America, due to efficiency upgrade cycles.
- Process Burners:Process burners provide direct heat for chemical reactors and drying operations, requiring robust design for continuous duty.
- Infrared Burners:Infrared burners use radiant heat transfer for drying and curing applications, often specified for food processing and textile industries.
Volume sits with Boiler Burners; growth tilts toward Process Burners.
Fuel Type:
The operational cost and environmental impact of industrial burners are heavily influenced by the chosen fuel type.
- Natural Gas:Natural gas burners utilize methane as their primary fuel, offering clean combustion and widespread infrastructure availability. This fuel type dominates in regions with established gas grids, such as the United States and parts of Europe, due to consistent supply.
- Biofuel:Biofuel burners are designed to combust renewable organic materials, reducing reliance on fossil fuels and lowering net carbon emissions. Demand for these systems is expanding in Southeast Asian pulp and paper mills, seeking waste-to-energy solutions.
- Diesel:Diesel burners serve as a reliable option for remote industrial sites or backup systems, providing high energy density.
- Propane:Propane burners offer a cleaner-burning alternative to fuel oil in regions without natural gas access, suitable for diverse industrial uses.
- Fuel Oil:Fuel oil burners remain in use for heavy industrial applications, particularly in older installations where infrastructure is already present.
Natural gas systems continue to capture the largest installed base, while biofuel burner systems are gaining share fastest.
Application Sector:
The operational environment and regulatory landscape dictate specific burner requirements across different application sectors.
- Power Generation:Burners in power generation facilities convert fuel into thermal energy to produce steam, driving turbines for electricity output. Strict emissions regulations from the US Environmental Protection Agency and the EU Green Deal drive retrofits for low-NOx and hydrogen-ready systems.
- Metallurgy:Metallurgy applications require burners capable of reaching extremely high temperatures for processes like smelting, forging, and heat treatment of metals. China's dual carbon goals are mandating upgrades in its steel sector, creating significant demand for high-efficiency burners.
- Cement Production:Cement production utilizes industrial burners for clinker kilns, demanding robust systems to handle high dust loads and high temperatures.
- Food Processing:Food processing relies on burners for drying, baking, and sterilization, requiring precise temperature control and hygienic designs.
Power generation facilities represent a substantial portion of burner consumption, with the metallurgy sector showing the steepest expansion trajectory.
Installation Mode:
The lifecycle stage of an industrial facility significantly impacts the choice of burner installation mode.
- Retrofit:Retrofit installations involve upgrading or replacing existing burner systems in operational facilities to improve efficiency or meet new emissions standards. These projects are prevalent in the United States power generation sector, driven by cyclical efficiency upgrade programs.
- New Setup:New setup installations equip greenfield industrial plants with entirely new combustion systems, designed for optimal performance from inception. Indian manufacturing initiatives are boosting capital investment in new cement and steel plants, directly pulling demand for these systems.
- Mobile Units:Mobile units offer flexible heating solutions for temporary industrial sites or specialized field operations, providing portability.
- Fixed Units:Fixed units are permanently installed burner systems integrated into static industrial infrastructure, common in large-scale manufacturing.
Retrofit projects constitute a large segment of current activity, while new setups are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial burner market exhibits a significant divide between regions focused on consumption-driven demand and those prioritizing advanced manufacturing. China and India are driving new installations, while the United States and Europe focus on efficiency upgrades and decarbonization mandates. This regional segmentation influences product development and investment flows across the globe.
China
China's dual carbon goals mandate upgrades in the steel sector, creating demand for high-efficiency burners. The Ministry of Ecology and Environment (MEE) enforces strict emission limits, accelerating the obsolescence of older equipment. Industrial clusters in the Yangtze River Delta invest heavily in compliant combustion technologies.
India
National manufacturing initiatives in India boost capital investment in new cement and steel plants, pulling demand for industrial burners. The Production Linked Incentive (PLI) scheme supports domestic manufacturing. Major industrial hubs in Gujarat and Maharashtra are witnessing significant greenfield project development.
United States
Efficiency upgrades in existing natural gas power plants provide a consistent stream of large-scale retrofit projects. The US Environmental Protection Agency (EPA) sets strict limits on NOx and SOx emissions. Petrochemical facilities along the Gulf Coast continuously upgrade combustion units to meet performance and environmental targets.
Germany
The EU Green Deal mandates stringent emissions targets for industrial sites, creating demand for best-available-technology retrofits. The REACH regulation influences permissible materials in burner components. Industrial areas in North Rhine-Westphalia adopt hydrogen-ready and ultra-low NOx burners for compliance.
Italy
European decarbonization goals drive the adoption of low-NOx and hydrogen-ready burners across industrial sectors. The EU's Corporate Sustainability Reporting Directive (CSRD) mandates detailed emissions disclosure. Industrial centers in Lombardy focus on retrofitting existing facilities with advanced combustion solutions to meet new reporting obligations.
Global Industrial Burner Market Key Industry Players
The competitive structure tilts toward specialized engineering firms and integrated solution providers rather than pure hardware manufacturers. The market sees a tiered landscape, with a few global players dominating advanced combustion technologies. Strategic archetypes include custom-engineered solutions specialists, automation-integrated providers, and alternative fuel system developers. Dominant competitive moves involve portfolio diversification into hydrogen-ready systems and strategic partnerships for complex project execution.
Within the integrated solutions tier, Honeywell International Inc. exemplifies a player leveraging its extensive automation and control systems for comprehensive combustion offerings. John Zink Hamworthy Combustion represents a specialist in custom-engineered solutions for complex process applications, focusing on tailored industrial needs. Andritz AG occupies a position as an advanced burner developer for biomass and alternative fuels, catering to specific waste-to-energy requirements and regional demands, particularly in Southeast Asia.
| Leading Market Players |
|---|
| Oilon Group Oy |
| John Zink Hamworthy Combustion |
| Honeywell International Inc. |
| Bloom Engineering Inc. |
| Riello S.p.A. |
| Weishaupt Corp. |
| Andritz AG |
| Power Flame Inc. |
| Baltur Spa |
| Others |
Cost & Logistics Intelligence
The EU Green Deal, with its stringent emissions targets, gates both qualified burner supply and premium-tier pricing access for compliant technologies across Europe. This mandate forces manufacturers to invest in advanced R&D, impacting production costs and ultimately pricing strategies.
Pricing Analysis
Outcome-based pricing, tied to guaranteed emissions performance and fuel flexibility, anchors advanced industrial burner systems. Price differentiation drivers include verified low-NOx compliance and comprehensive after-sales service agreements, which ensure long-term operational efficiency. Pricing softness runs through the standard equipment segment, influenced by increasing competition from Asian manufacturers. Food processing and other cost-sensitive industries exhibit the highest price sensitivity, often opting for more basic, transactional equipment.
Supply Chain Analysis
A shortage of skilled combustion engineers and technicians in key manufacturing geographies limits the rapid scaling of complex burner system production. Geographic supply concentration for critical components centers on Germany for precision engineering and China for cost-effective manufacturing of standard parts. Raw material dependencies include specialized high-temperature alloys, advanced ceramic insulation, and integrated control electronics. Single-source vulnerability for highly specialized components presents a structural supply chain risk. Distribution runs through a hybrid model, combining direct sales to large industrial end-users with EPC contractors for integrated project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's dual carbon goals create a significant cost-of-compliance story, establishing a barrier-to-entry moat for burner manufacturers capable of meeting strict emission limits.
For Market Incumbents:Cement leadership by diversifying portfolios into hydrogen-ready and carbon capture-integrated burner systems, anticipating future fuel shifts. Invest in advanced material science R&D to overcome hydrogen embrittlement challenges, mitigating the threat of material science limitations. Leverage existing automation and control system expertise to offer integrated combustion solutions, reinforcing a competitive advantage. Form strategic partnerships with engineering firms specializing in complex process applications to broaden project execution capabilities.
For New Entrants and Emerging Players:Small and medium-sized industrial facilities in emerging markets represent an underserved buyer archetype for modular, easily deployable burner solutions. Target India's rapidly expanding manufacturing sector, focusing on greenfield cement and steel plants with standardized, high-efficiency offerings. Develop specialized burners for biomass gasification in Southeast Asian pulp and paper mills, addressing a regional waste-to-energy need. A go-to-market angle focusing on verifiable performance data and lower total cost of ownership will resonate with compliance-driven buyers.
For Investors and Strategic Acquirers:Widespread adoption of the EU's Corporate Sustainability Reporting Directive across industrial sectors is the leading indicator that demand for verifiable low-emission combustion assets will intensify. The long-term viability of the industrial burner market, spanning the next 5-10 years, hinges on the decarbonization imperative across heavy industry. Target specialized engineering firms proficient in ultra-low NOx and alternative fuel combustion technologies. Increased investment in hydrogen infrastructure buildout remains a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Hydrogen-Ready Systems | Expands market reach into future fuel landscapes, securing long-term revenue streams for manufacturers. |
| Strategic Partnerships for Complex Project Execution | Enhances capability to deliver integrated combustion solutions for large-scale industrial upgrades. |
| Investment in Digital Twin Technology Integration | Optimizes burner performance and enables predictive maintenance, reducing operational costs for end-users. |
| Expansion of Biomass Burner Solutions in Southeast Asia | Addresses regional waste-to-energy needs and diversifies revenue away from fossil fuel-dependent markets. |
| Development of Carbon Capture-Compatible Burner Designs | Positions vendors for growth in industries requiring CO2 capture, particularly cement and power generation. |
Research Approach
IEA reports, EPA filings, MEE regulations, and corporate sustainability reports formed the secondary backbone for market sizing and trend identification. This desk research was triangulated with primary interviews involving plant engineers, procurement leads, R&D directors, and environmental compliance officers from key industrial sectors. The approach combined bottom-up data aggregation with top-down market validation, ensuring comprehensive coverage.
A bottom-up analytical lens, building market size from segmented burner types, fuel types, application sectors, and installation modes, informed the forecast framework. The model also incorporated regional regulatory frameworks and industrial capital expenditure projections as key segmentation dimensions. CAGRs were derived by analyzing historical trends, projected regulatory impacts, and anticipated technology adoption curves across the modeling period. Decarbonization policy timelines served as a critical industry-specific forecast input.
Revisions become necessary when significant geopolitical shifts affecting energy prices, unforeseen technological breakthroughs in combustion, or major regulatory changes materialize. Forecasts reflect assumptions documented at the time of publication, acknowledging inherent uncertainties in long-term projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Hydrogen Fuel Tanks Market
Fuels
North America Aviation Fuel Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Aviation Fuel Additives Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
North America Wood Pellet Market
Fuels
LPG Gas Cylinder Market
Fuels
Wood Charcoal Market
Fuels
Tire Derived Fuel Market
Fuels
Diesel As Fuel Market
Fuels
Anthracite Coal Mining Market