
 Germany Combined Heat and Power Market | 2026-2036
Germany Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Combined Heat and Power Market Foresight
The EU Green Deal's 55% emissions reduction target for 2030 is repositioning Germany's industrial energy procurement toward on-site cogeneration. Siemens AG leverages its gas turbine portfolio to anchor utility-scale district heating projects across North Rhine-Westphalia. 2G Energy AG specializes in biogas-fueled CHP modules that sustain agricultural and waste-sector deployments. Viessmann Group competes through compact gas engine systems positioned at commercial building scale.
Combined heat and power denotes simultaneous generation of usable thermal energy and electrical power from a single fuel source, typically achieving total system efficiencies of 75-90% through waste heat recovery for process steam or space conditioning. Gas engines dominate the technology segment due to their dispatch flexibility and sub-10 MW footprint suitability for German industrial estates. District heating applications are expanding fastest as municipalities retrofit urban heat networks with low-carbon CHP baseload. Data centers represent an emerging demand pocket where thermal-electric coupling addresses both power reliability and cooling loads.
KBA enforces emissions compliance for mobile and stationary engines under Germany's implementation of EU non-road mobile machinery standards, while the Federal Network Agency (Bundesnetzagentur) governs grid connection tariffs that determine CHP project economics. REACH and the EU F-Gas Regulation jointly constrain refrigerant and combustion chemistry choices, pushing OEMs toward hydrogen-ready engine architectures. Stakeholders must monitor hydrogen infrastructure buildout timelines and carbon contract-for-difference auctions to calibrate technology bets between natural gas transition platforms and zero-carbon fuel cell systems.
Market Dynamics
Germany's F-Gas Regulation phase-down is compressing the operational window for conventional natural gas engines while hydrogen-ready architectures and biogas integration gain engineering priority across OEM portfolios.
Growth Catalysts
- EU Green Deal 55% target:Industrial energy procurement pivots toward on-site cogeneration as grid-decarbonization mandates harden. Process industries seek thermal-electric coupling to lock in emissions compliance.
- Bavaria's chemical corridor:Energy-intensive clusters concentrate demand for cost-stable baseload supply. CHP installations anchor site-level energy security for continuous process operations.
- Biogas feedstock expansion:Agricultural and waste-sector deployments multiply as anaerobic digestion infrastructure matures. Modular CHP units capture methane streams previously flared or vented.
Market Restraints
- Natural gas price volatility:Input cost swings erode project finance assumptions. Developers face margin compression when hedging fails to cover fuel exposure.
- Grid connection tariff uncertainty:Bundesnetzagentur rate revisions delay investment decisions. CHP economics depend on stable feed-in compensation that regulatory proceedings disrupt.
- Heat pump substitution:Electric compression technology advances on coefficient-of-performance gains. Residential and light commercial thermal loads migrate away from combustion-based solutions.
Strategic Opportunities
- North Rhine-Westphalia district heating retrofit:Municipal heat network upgrades create utility-scale CHP installation slots. Urban density supports viable heat offtake contracts.
- Data center thermal-electric coupling:Power reliability requirements intersect with cooling load recovery. Waste heat absorption chillers displace electrically-driven compression cooling.
- Hydrogen infrastructure buildout:Carbon contract-for-difference auctions de-risk H2-ready engine investments. OEMs can bridge natural gas transition platforms toward zero-carbon fuel cell systems.
Industry Challenges
- REACH compliance chemistry:Reformulated lubricants and combustion additives require recertification cycles. Product development timelines extend as toxicology dossiers accumulate.
- Legacy control system integration:Digital retrofit of existing CHP assets demands protocol translation layers. Site engineers confront heterogeneous automation architectures.
- Specialized technician scarcity:Dual competence in thermal engineering and power electronics remains rare. Vocational pipelines have not scaled to match deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Combined Heat and Power Market |
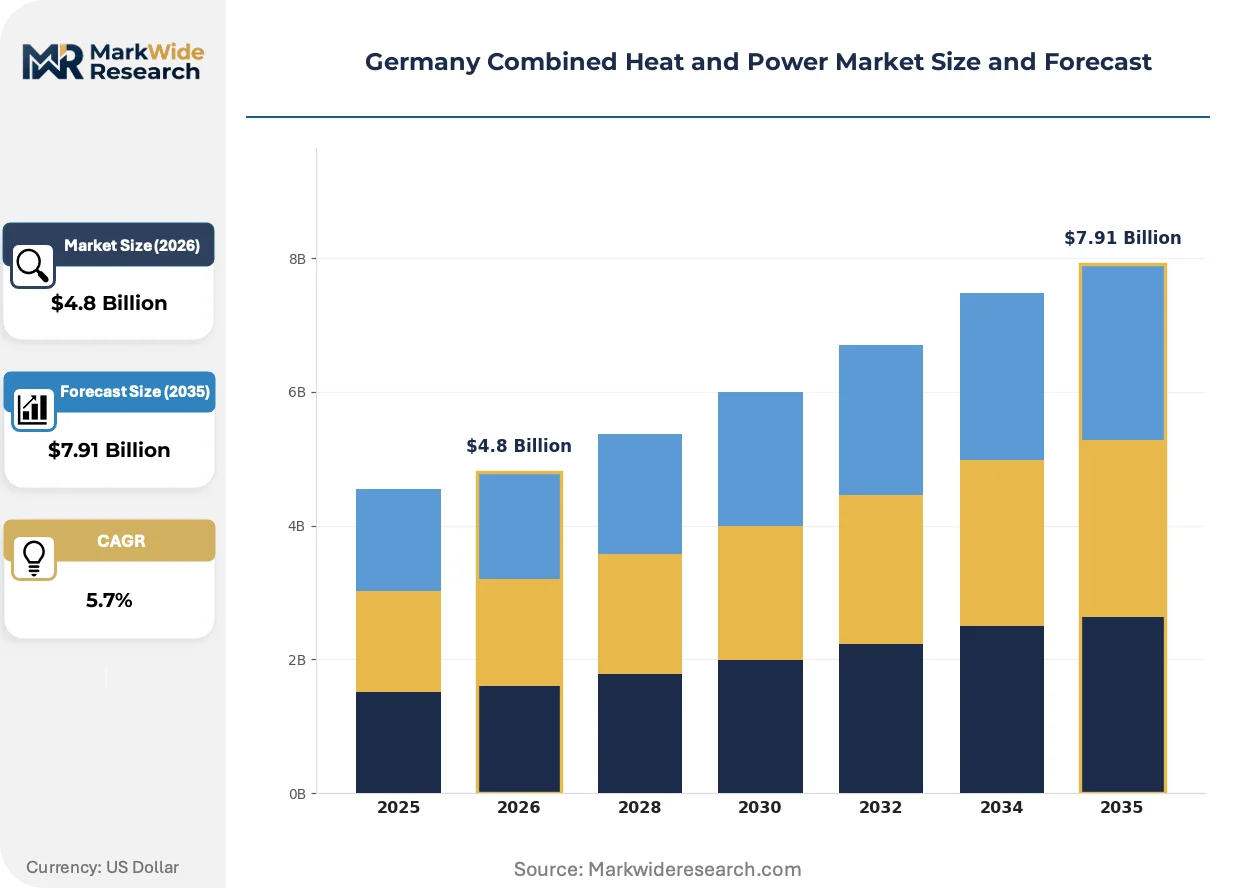
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Engines, Steam Turbines, Microturbines, Fuel Cells, Reciprocating Engines Application: Industrial Manufacturing, Commercial Buildings, District Heating, Agriculture, Data Centers End User: Chemical Plants, Food Processing Units, Universities, Hotels, Sports Facilities Deployment Model: On-site, Modular Systems, Centralized Plants, Decentralized Systems, Mobile Units |
| Companies Covered | Siemens AG, 2G Energy AG, ABB Ltd., Caterpillar Inc., Capstone Turbine Corporation, General Electric Company, Viessmann Group, Vaillant Group, Thüga Holding GmbH & Co. KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Combined Heat and Power Market Shifts & Advancements
Modular CHP architectures are fragmenting the traditional project-scale paradigm. Equipment miniaturization, software-defined dispatch, and fuel-flexible combustion systems are compressing deployment cycles.
Containerized biogas CHP systems are decentralizing agricultural energy supply. Dairy cooperatives and food processors adopt skid-mounted units beneath 500 kW. Standardized balance-of-plant components collapse engineering-procurement-construction timelines from months to weeks.
The EU F-Gas Regulation is forcing refrigerant transitions in CHP-linked heat pumps and absorption chillers. Hydrofluorocarbon phase-down schedules accelerate natural working fluid adoption. Equipment manufacturers in Baden-Württemberg and Lower Saxony retest thermodynamic cycles with ammonia and carbon dioxide as heat transfer media.
Energy-as-a-service contracting is displacing capital purchase in commercial building deployments. Facility managers prefer fixed thermal-electric tariffs over balance-sheet ownership. Munich and Hamburg property portfolios lead this shift, with municipal utilities underwriting performance guarantees that bundle maintenance, fuel procurement, and carbon reporting.
Germany Combined Heat and Power Market Segmentation
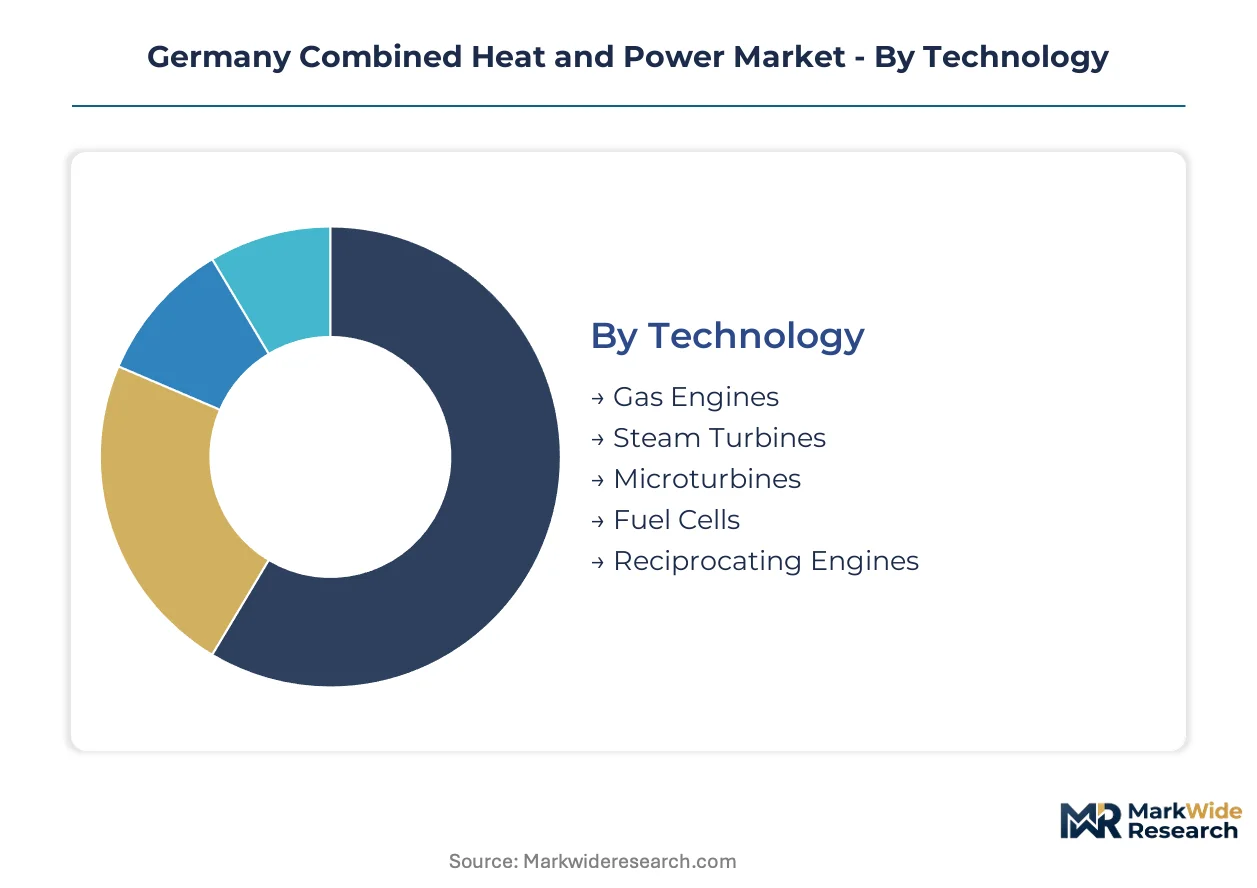
Technology and deployment configurations in Germany's CHP market carry distinct certification obligations under KBA emissions enforcement and Bundesnetzagentur grid codes. Segment selection dictates fuel flexibility, thermal output range, and connection tariff eligibility. Procurement teams align specifications with site-level energy security requirements and decarbonization timelines.
Technology:
KBA type-approval requirements vary sharply across prime mover categories, with gas engines facing the most stringent NOx and methane slip testing protocols under EU non-road mobile machinery standards.
- Gas Engines:Spark-ignition and lean-burn configurations dominate sub-10 MW industrial installations. Bavaria's chemical corridor clusters specify these units for baseload process steam and power reliability. KBA enforces staged emissions compliance that compresses operational windows for conventional natural gas variants.
- Steam Turbines:Backpressure and extraction-condensing designs serve utility-scale district heating networks. North Rhine-Westphalia municipal retrofits anchor demand where urban heat density supports viable offtake contracts. REACH-constrained lubricant formulations extend recertification cycles for high-temperature operation.
- Microturbines:Compact recuperated designs suit commercial building rooftops with limited mechanical space.
- Fuel Cells:Solid oxide and proton exchange membrane systems command premium positioning for hydrogen-ready sites.
- Reciprocating Engines:Compression-ignition variants persist in heavy-fuel and dual-fuel marine-derivative applications.
Leading the category by volume: Gas Engines. Growing fastest: Fuel Cells.
Application:
End-use thermal load profiles determine CHP sizing economics, with continuous process steam demand outperforming intermittent space heating in capacity factor optimization.
- Industrial Manufacturing:Chemical, pharmaceutical, and paper sectors deploy CHP for uninterruptible thermal-electric supply. Site-level energy security priorities override grid dependency risks. Process continuity mandates drive specifications toward 90%+ availability guarantees.
- District Heating:Municipal heat network retrofits create utility-scale installation slots across North Rhine-Westphalia and Berlin. Urban density supports long-term heat purchase agreements that underwrite project finance. F-Gas Regulation phase-down accelerates natural working fluid adoption in linked absorption chillers.
- Commercial Buildings:Hotels and office complexes favor energy-as-a-service contracting over capital ownership.
- Agriculture:Anaerobic digestion coupling with biogas CHP captures methane from dairy and food waste streams.
- Data Centers:Power reliability requirements intersect with waste heat recovery for absorption cooling.
Industrial Manufacturing holds the largest installed base. Data Centers show the steepest expansion trajectory.
End User:
Facility scale and thermal load continuity separate capital-purchase candidates from energy-as-a-service prospects across German industrial estates.
- Chemical Plants:Energy-intensive continuous processes demand baseload thermal-electric coupling. Site clusters in Ludwigshafen and Leverkusen anchor multi-megawatt installations. Procurement teams prioritize hydrogen-ready engine architectures for carbon contract-for-difference eligibility.
- Food Processing Units:Dairy cooperatives and meat processors adopt containerized biogas CHP beneath 500 kW. Standardized balance-of-plant components compress deployment timelines. Agricultural feedstock security determines project bankability.
- Universities:Campus district heating systems favor modular gas engine additions.
- Hotels:Munich and Hamburg property portfolios lead energy-as-a-service adoption.
- Sports Facilities:Swimming pools and ice rinks present seasonal thermal load mismatches.
Chemical Plants dominate capital deployment. Food Processing Units expand most quickly on biogas integration.
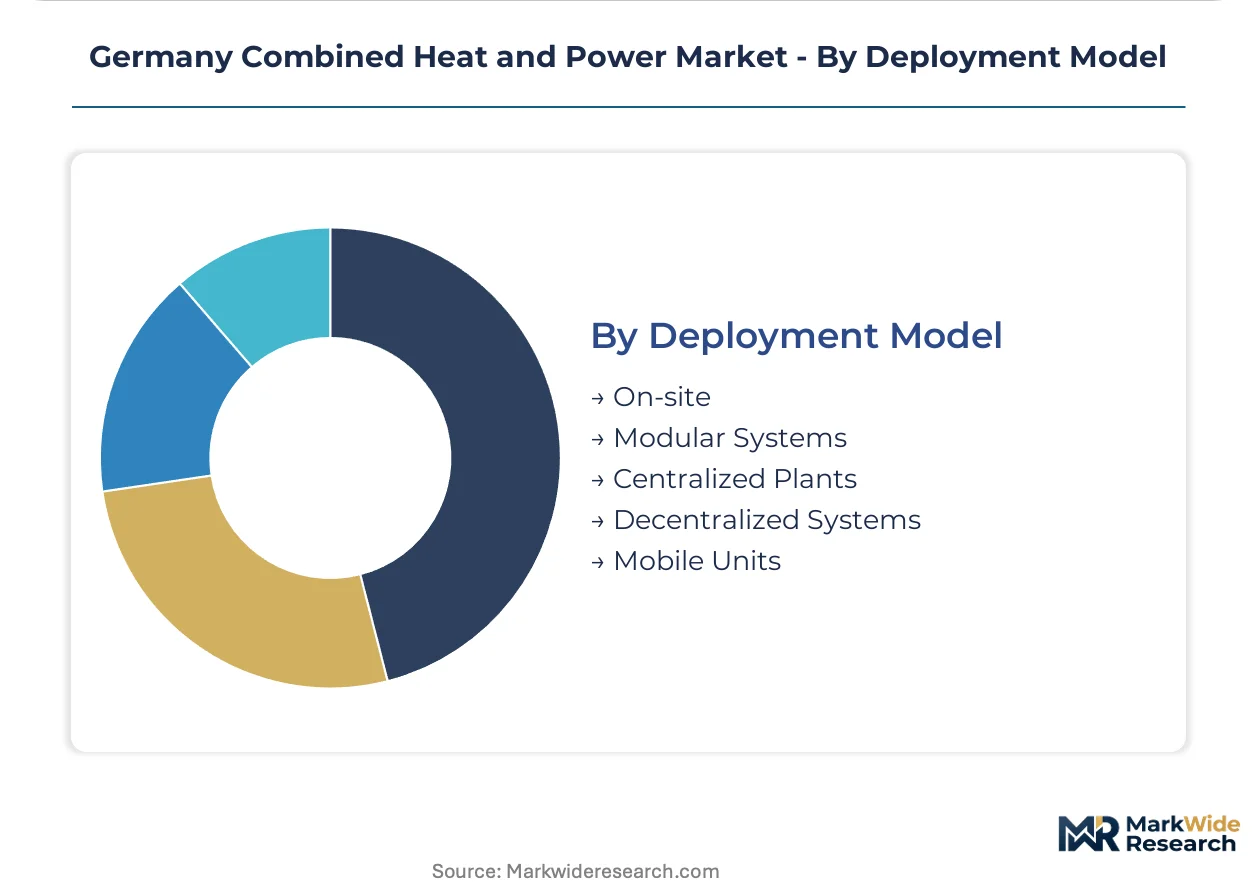
Deployment Model:
Engineering-procurement-construction risk allocation and operational control preferences shape procurement between turnkey ownership and performance-based contracting.
- On-site:Captive generation at industrial facilities retains full operational control and fuel procurement flexibility. Balance-sheet ownership suits entities with investment-grade credit and internal maintenance capabilities. Grid connection tariff exposure remains with the asset owner.
- Modular Systems:Skid-mounted and containerized configurations collapse deployment cycles from months to weeks. Dairy cooperatives and distributed commercial sites favor standardized units beneath 2 MW. Factory acceptance testing reduces site commissioning risk.
- Centralized Plants:Utility-scale district heating anchors require municipal offtake guarantees.
- Decentralized Systems:Virtual power plant aggregation enables smaller units to participate in balancing markets.
- Mobile Units:Rental CHP serves construction sites and temporary industrial load.
On-site deployment commands the greatest cumulative capacity. Modular Systems gain share fastest on standardization and speed-to-operation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors Germany's industrial CHP density through BASF's integrated chemical complex and surrounding pharmaceutical clusters demanding continuous thermal-electric supply.
Bavaria
Chemical and pharmaceutical manufacturers along the Danube-Isar corridor deploy sub-10 MW gas engines for process steam reliability. KBA enforces staged NOx compliance that compresses operational windows for conventional natural gas variants. Munich's municipal utility retrofits district heating networks with modular CHP additions.
North Rhine-Westphalia
Ruhr Valley municipalities upgrade urban heat networks with utility-scale steam turbine installations. The EU Green Deal's 55% target accelerates coal-to-gas CHP transitions in Essen and Dortmund. Industrial estates in Leverkusen anchor multi-megawatt captive generation for Bayer's continuous process operations.
Baden-Württemberg
Automotive suppliers and machine tool manufacturers favor compact gas engine systems beneath 2 MW. REACH-constrained lubricant formulations extend recertification cycles for high-temperature operation. Stuttgart's technology parks pilot hydrogen-ready engine architectures for carbon contract-for-difference eligibility.
Lower Saxony
Dairy cooperatives and food processors adopt containerized biogas CHP beneath 500 kW. Agricultural feedstock security determines project bankability across the Lüneburg Heath anaerobic digestion belt. Hanover's municipal utility aggregates distributed units through virtual power plant platforms.
Hamburg
Port logistics and maritime services drive demand for dual-fuel engine flexibility. Energy-as-a-service contracting displaces capital purchase in commercial building portfolios. The city's district heating operator sources waste heat from industrial CHP installations along the Elbe.
Germany Combined Heat and Power Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology complexity and fuel-flexibility dimensions. The vendor base organizes into three tiers: diversified industrial conglomerates with turbine portfolios, specialized CHP module manufacturers, and regional boiler-to-CHP transition specialists. Strategic moves concentrate on hydrogen-ready platform development and energy-as-a-service contract structuring.
Within the diversified industrial tier, Siemens AG and General Electric Company occupy positions anchored by utility-scale gas turbine capabilities. Among specialized German manufacturers, 2G Energy AG exemplifies the biogas-fueled modular segment. Viessmann Group represents the building-scale transition archetype, bridging conventional boiler installations with compact cogeneration systems.
| Leading Market Players |
|---|
| Siemens AG |
| 2G Energy AG |
| ABB Ltd. |
| Caterpillar Inc. |
| Capstone Turbine Corporation |
| General Electric Company |
| Viessmann Group |
| Vaillant Group |
| Thüga Holding GmbH & Co. KGaA |
| Others |
Supply & Pricing Matrix
Natural gas input costs cascade through CHP equipment pricing tiers, compressing margins for standard gas engine configurations while hydrogen-ready architectures command premium positioning. Component sourcing from Baden-Württemberg and Lower Saxony manufacturing clusters feeds into three-tier pricing structures across utility-scale, industrial, and commercial deployment scales.
Pricing Analysis
Energy-as-a-service contracts anchor value-based pricing to thermal-electric uptime guarantees rather than capital equipment transfer. Pricing stratifies across premium, standard, and economy tiers differentiated by fuel flexibility and KBA emissions certification grade. Cost compression in standard gas engine segments intensifies as heat pump substitution erodes residential thermal loads. Commercial building portfolios exhibit highest price sensitivity, while chemical plants prioritize availability over unit economics.
Supply Chain Analysis
KBA type-approval and REACH compliance certification gate access to German industrial procurement channels, extending product development timelines for reformulated lubricant and combustion chemistry portfolios. Manufacturing concentrates in Germany, Austria, and Switzerland for precision engine components, with steel castings and electronic control modules drawing from Czech and Polish supplier bases. Single-source vulnerability persists in specialized turbocharger assemblies. Distribution runs through OEM-direct and municipal utility channels for utility-scale projects, with regional EPC contractors handling industrial site integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician scarcity constrains deployment velocity, propping pricing power for OEMs with captive service networks. Capacity bottlenecks in hydrogen-ready engine architectures limit supply response to carbon contract-for-difference auction demand surges.
For Market Incumbents: Acquire biogas CHP module specialists to consolidate agricultural sector positioning against containerized system entrants. Backward integration into anaerobic digestion engineering capabilities secures feedstock-linked project pipelines. Counter heat pump substitution threat through thermal-electric coupling performance guarantees for process industries. For New Entrants and Emerging Players: Enter via data center waste heat recovery segments where absorption cooling integration creates differentiated value propositions. Bavaria's chemical corridor sub-10 MW replacement cycle presents the most penetrable incumbent stronghold. Pursue energy-as-a-service contracting models to bypass capital purchase barriers in commercial building portfolios. For Investors and Strategic Acquirers: Hydrogen infrastructure buildout timeline acceleration is the leading indicator that hydrogen-ready engine platform valuations will detach from natural gas transition asset multiples. Long-term viability centers on OEMs bridging carbon contract-for-difference eligibility toward fuel cell system integration. Target acquisition archetype: modular CHP manufacturers with virtual power plant software stacks and established Bundesnetzagentur grid code certifications.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Platform Development | Carbon contract-for-difference auctions de-risk H2 engine investments for Bayer and BASF site clusters. |
| Energy-as-a-Service Contract Structuring | Munich and Hamburg municipal utilities bundle maintenance, fuel procurement, and carbon reporting for commercial portfolios. |
| Biogas Feedstock Integration | Anaerobic digestion coupling captures methane streams across Lower Saxony's Lüneburg Heath agricultural belt. |
| Virtual Power Plant Aggregation | Hanover's municipal utility enables sub-500 kW units to participate in Bundesnetzagentur balancing markets. |
| District Heating Network Retrofit | Ruhr Valley coal-to-gas transitions in Essen and Dortmund anchor utility-scale steam turbine demand. |
Research Methodology
Multi-period observation of KBA emissions enforcement patterns and Bundesnetzagentur tariff proceedings anchored the trend analysis, supplemented by interviews with CHP plant engineers, EPC contractors, municipal utility planning officers, and anaerobic digestion project developers. Secondary validation drew from Federal Network Agency regulatory filings, EU F-Gas Regulation implementation schedules, VDMA industry association statistics, and REACH compliance databases. Bottom-up installation tracking across Bavaria, North Rhine-Westphalia, and Lower Saxony triangulated against top-down OEM revenue segmentation.
Input-output matrices modeled capacity additions, fuel source transitions, and technology substitution elasticities across the projection horizon. Segmentation dimensions included prime mover category, deployment scale tier, end-use thermal load profile, and regional grid interconnection type. CAGRs derived from regression-adjusted deployment trajectories incorporating hydrogen infrastructure buildout scenarios and carbon contract-for-difference auction participation rates.
Revisions become necessary when F-Gas Regulation phase-down schedules accelerate, natural gas price volatility exceeds modeled bands, or heat pump coefficient-of-performance gains compress CHP economic viability in commercial building segments. A model refresh is warranted upon material change in Bundesnetzagentur grid connection tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
North America Residential Boiler Market
Boilers
Residential Boiler Market
Boilers
Power Boiler Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Industrial Boiler MRO Market
Boilers
North America Industrial Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Oil-Fired Boiler Market
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Global Fuel Flexible Boiler Market
Boilers
Combi Boiler Market
Boilers
Reformer Unit Market
Boilers
Industrial and Residential Heating Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Middle East and Africa Power Plant Boiler Market