
 Iran Wind Energy Market | 2026-2036
Iran Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Wind Energy Market Foresight
Multi-sourced turbine procurement is restructuring supply dynamics for Iranian wind developers. MAPNA Group leverages domestic manufacturing capacity to anchor large-scale utility projects across southeastern provinces. Vestas Wind Systems competes through technology leadership in high-capacity factor turbine designs suited to Iran's arid wind corridors. Siemens Gamesa Renewable Energy extends its regional service network to sustain long-term operations and maintenance contracts.
Iran wind energy encompasses the conversion of kinetic wind flow into electrical power through rotating blade assemblies driving generator systems, typically rated from kilowatt-scale units to multi-megawatt turbines with rotor diameters exceeding 100 meters for utility deployment. Horizontal axis configurations dominate installed capacity due to mature aerodynamic efficiency and proven grid synchronization protocols. The application dimension shows power generation commanding the primary investment stream, while distributed generation segments attract faster growth from industrial offtakers seeking behind-the-meter supply security. Component-level margin pools concentrate in control systems, where software-integrated pitch and yaw management differentiates turbine performance in variable wind regimes.
The Renewable Energy Organization of Iran (SUNA) administers feed-in tariff structures that shape project bankability and developer returns. National Iranian Oil Company diversification mandates and central bank foreign exchange allocation rules jointly determine import capacity for foreign turbine suppliers. Grid integration standards issued by the country's national electricity regulator constrain deployment timelines in remote wind-rich zones lacking transmission backbone. Stakeholders must monitor currency access protocols and domestic content requirements as these mechanisms determine competitive positioning between local assemblers and international technology providers.
Market Dynamics
Feed-in tariff restructuring by SUNA is forcing Iranian utilities to accelerate grid-connected wind procurement while foreign exchange allocation bottlenecks reshape turbine import economics.
Growth Catalysts
- Sistan-Baluchestan wind corridors:Sustained 120-day wind seasons in southeastern Iran attract state-backed developers seeking high-capacity factor sites.
- National Iranian Oil Company diversification mandates:Fossil fuel dependency reduction targets redirect capital toward renewable generation portfolios.
- Domestic blade manufacturing:MAPNA Group's local assembly capacity cuts import dependency and accelerates project commissioning timelines.
Market Restraints
- Foreign exchange rationing:Central bank hard currency controls restrict Vestas and Siemens Gamesa turbine imports, forcing developers toward domestic suppliers.
- Transmission backbone gaps:Remote wind-rich zones in Kerman and Yazd provinces lack high-voltage lines, delaying grid synchronization.
- Steel price volatility:Tower and nacelle fabrication costs fluctuate with global metallurgical input markets, eroding project IRRs.
Strategic Opportunities
- Industrial behind-the-meter deployment:Steel and cement offtakers in Isfahan Province seek captive wind supply to hedge grid instability.
- Control system software convergence:Pitch-yaw algorithm integration with SCADA platforms differentiates turbine performance in variable wind regimes.
- Service network localization:Vestas regional maintenance hubs extend contract durations and recurring revenue streams.
Industry Challenges
- Grid code compliance timelines:National electricity regulator synchronization standards delay commercial operation dates for remote projects.
- Specialized technician scarcity:Gearbox and generator maintenance expertise concentrates in Tehran, constraining field response capacity in Baluchestan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Wind Energy Market |
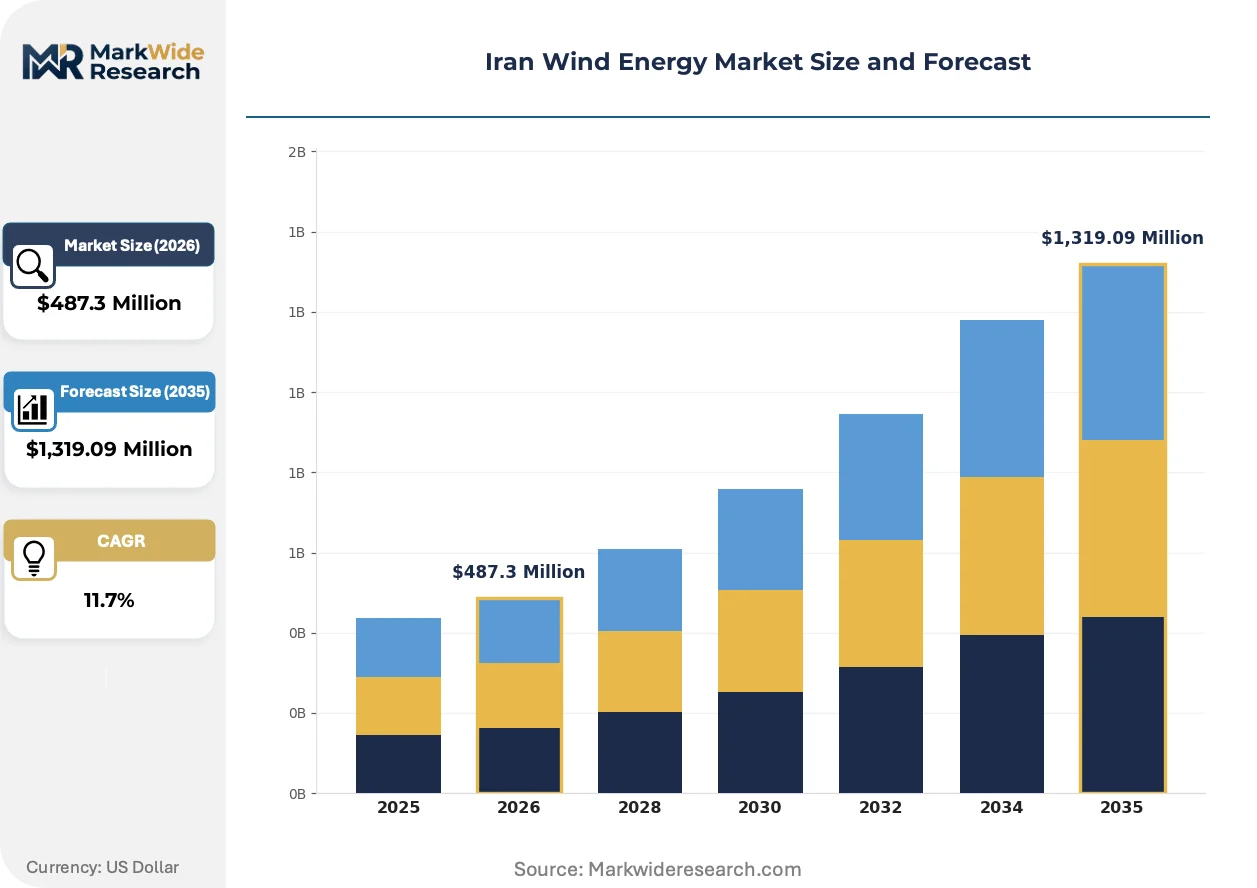
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Small Wind Turbines, Offshore Wind Application: Power Generation, Hybrid Systems, Distributed Generation, Remote Power Supply End User: Utilities, Independent Power Producers, Commercial Users, Residential Users Component: Turbines, Control Systems, Towers, Inverters |
| Companies Covered | Siemens Gamesa Renewable Energy, Ming Yang Smart Energy, MAPNA Group, Saba Niroo, General Electric Company, MahTaab Group, Vestas Wind Systems, Envision Group, Goldwind, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Wind Energy Market Shifts & Advancements
Digitalization of turbine control architectures is compressing operational response times while regulatory pressure on fossil fuel generators accelerates renewable procurement mandates.
Advanced pitch control systems are automating real-time blade angle adjustments based on lidar wind sensing. Iranian utility operators deploy these systems in Sistan-Baluchestan corridors to maximize capture factors during seasonal wind peaks. The technology is automating manual intervention requirements, reducing downtime events and extending gearbox service intervals.
SUNA feed-in tariff banding reforms now differentiate payment rates by capacity factor tier and grid zone congestion. Developers face compressed returns in transmission-constrained regions while incentivized to cluster projects near existing substations. Southeastern provinces with backbone access command developer priority queues.
Industrial offtakers now negotiate direct power purchase agreements bypassing utility intermediaries. Steel mills in Isfahan and cement plants in Kerman contract directly with wind farm operators for behind-the-meter supply security. This bilateral contracting pattern concentrates in manufacturing zones with unreliable grid uptime histories.
Iran Wind Energy Market Segmentation
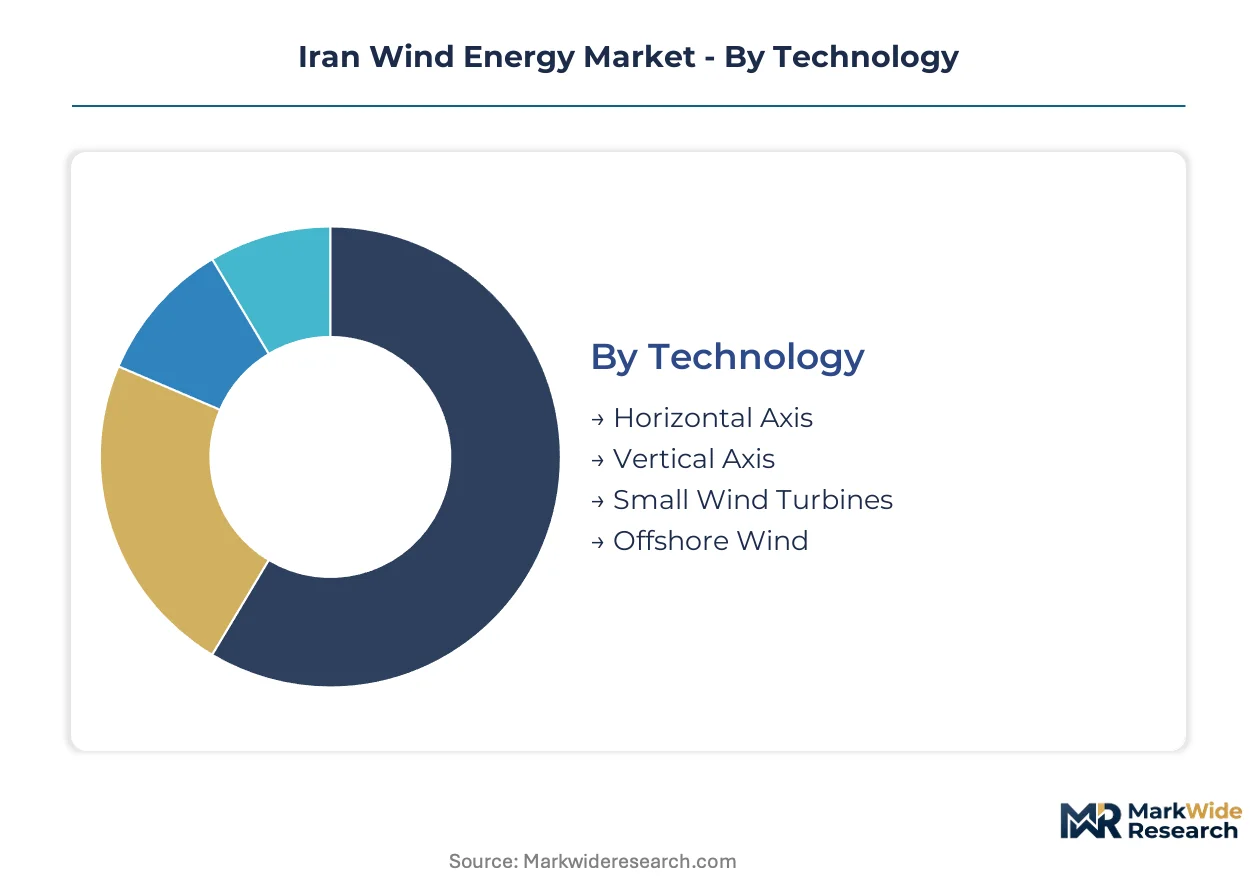
Technology configuration and application architecture determine procurement patterns across Iran's wind corridors. Component sourcing strategies and end-user risk profiles further differentiate investment timelines and return expectations in this regulated market.
Technology:
Customization concentrates in rotor diameter and hub height specifications, while standardization dominates drivetrain and generator platforms across Iranian installations.
- Horizontal Axis:Rotor assemblies with three blades mounted on upwind-facing nacelles dominate utility-scale deployment. Iranian developers in Sistan-Baluchestan prioritize these configurations for their proven aerodynamic efficiency in sustained 120-day wind seasons.
- Vertical Axis:Darrieus and Savonius designs eliminate yaw mechanisms, reducing mechanical complexity for distributed applications. Demand clusters around industrial compounds in Isfahan Province where maintenance access constraints favor simpler architectures.
- Small Wind Turbines:Units below 100kW rated capacity serve behind-the-meter installations with lower grid interconnection burdens.
- Offshore Wind:Floating platform concepts remain pre-commercial in Iranian waters given Caspian Sea depth constraints and Persian Gulf shipping corridor conflicts.
Leading the category by volume: Horizontal Axis. Expanding most quickly: Small Wind Turbines.
Application:
Cost tier stratification separates centralized utility projects from decentralized industrial offtake arrangements.
- Power Generation:Grid-connected wind farms feeding national transmission infrastructure constitute the primary investment stream. SUNA feed-in tariff banding shapes project economics, with southeastern provinces commanding developer priority due to backbone access.
- Distributed Generation:Behind-the-meter installations supply captive industrial loads, bypassing utility intermediaries. Steel mills and cement plants in manufacturing zones negotiate direct power purchase agreements to hedge grid instability.
- Hybrid Systems:Wind-solar and wind-diesel configurations optimize capacity factors across variable renewable resource profiles.
- Remote Power Supply:Off-grid installations serve mining operations and border infrastructure in transmission-constrained zones.
Highest capital deployment: Power Generation. Gaining share fastest: Distributed Generation.
End User:
Customer type determines financing structure and offtake risk allocation in project development.
- Utilities:State-backed procurement entities scale grid-connected capacity under National Iranian Oil Company diversification mandates. Foreign exchange rationing forces these buyers toward MAPNA Group domestic assembly capacity.
- Independent Power Producers:Private developers navigate SUNA tariff reforms and central bank currency access protocols to structure bankable projects.
- Commercial Users:Industrial offtakers in Isfahan and Kerman provinces contract directly with wind farm operators.
- Residential Users:Small-scale rooftop and mini-turbine installations serve rural electrification programs.
Dominant procurement volume: Utilities. Steepest expansion trajectory: Commercial Users.
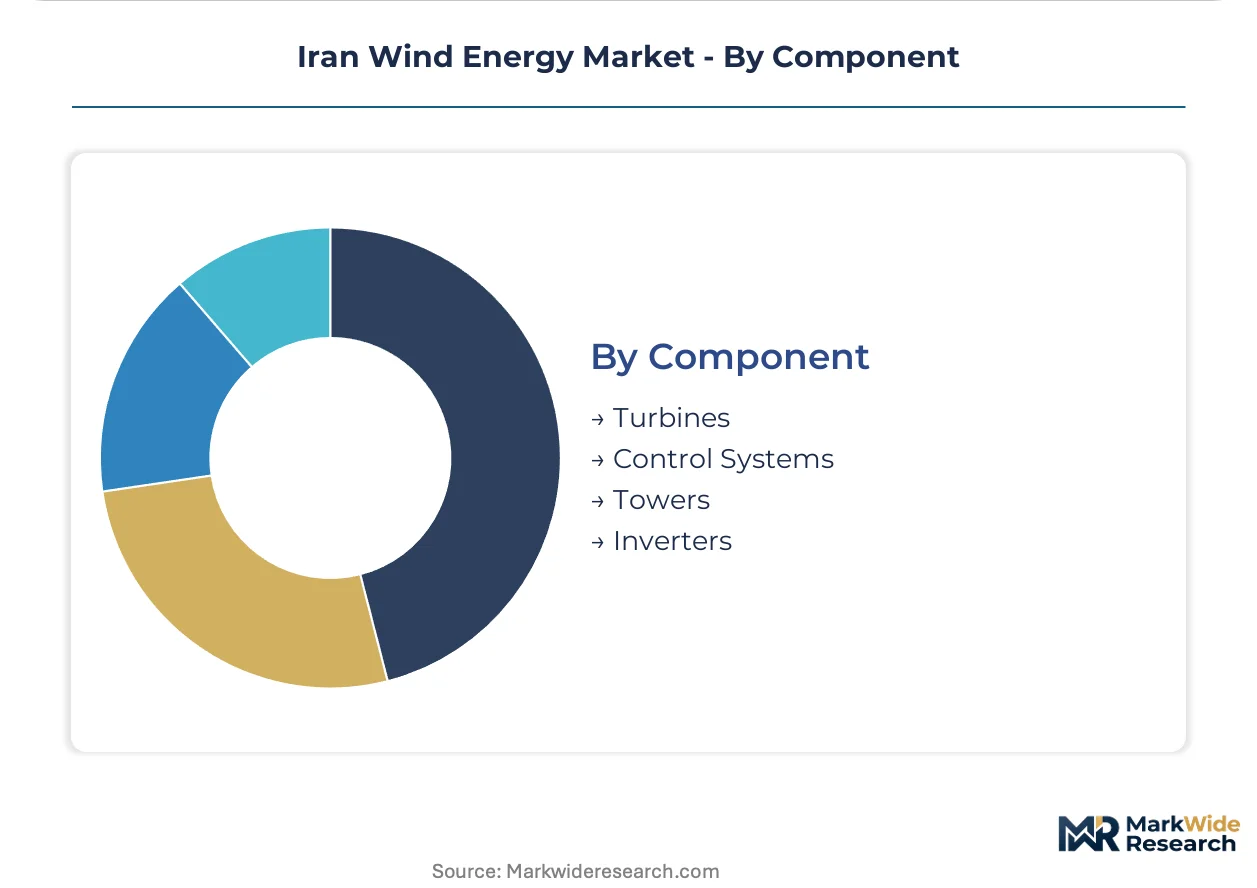
Component:
Margin concentration follows software integration intensity rather than commodity fabrication.
- Control Systems:Pitch-yaw algorithms integrated with SCADA platforms differentiate turbine performance in variable wind regimes. Software-integrated management commands premium pricing from operators seeking automated response to lidar wind sensing.
- Turbines:Nacelle assemblies housing generators, gearboxes, and main bearings represent the largest capital expenditure line item. MAPNA Group's domestic blade manufacturing cuts import dependency and accelerates commissioning timelines.
- Towers:Steel tubular structures face cost pressure from global metallurgical input volatility.
- Inverters:Power electronics synchronize variable frequency generator output with grid frequency requirements.
Highest margin pool: Control Systems. Fastest technology refresh: Inverters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for wind energy infrastructure concentrates in Iran's southeastern wind corridors, where sustained seasonal patterns and state-backed procurement programs reshape investment flows across provincial boundaries.
Sistan-Baluchestan Province
The 120-day wind season and high-capacity factor sites attract both MAPNA Group deployments and private developer interest. SUNA feed-in tariff banding prioritizes projects near existing transmission infrastructure. Zahedan and Chabahar anchor utility-scale procurement clusters where grid backbone access accelerates commercial operation timelines.
Kerman Province
Industrial offtakers from cement and mining sectors drive behind-the-meter distributed generation demand. National Iranian Oil Company diversification mandates redirect capital toward renewable portfolios in this zone. The Zarand and Rafsanjan industrial corridors host direct power purchase agreements that bypass utility intermediaries for supply security.
Yazd Province
Arid wind regimes and steel sector energy demand create captive wind deployment opportunities. Central bank foreign exchange rationing forces developers toward domestic turbine assembly capacity. The Yazd steel mill cluster negotiates bilateral contracts with independent power producers for behind-the-meter supply.
Isfahan Province
Manufacturing zone grid instability pushes steel and cement producers toward distributed wind investments. SUNA regulatory frameworks accommodate industrial direct contracting outside traditional utility structures. The Isfahan Steel Complex and surrounding industrial parks represent concentrated commercial user procurement.
Khorasan Razavi Province
Transmission-constrained wind resources await backbone expansion under national electricity regulator grid integration standards. Remote power supply applications serve mining operations and border infrastructure. The Mashhad periphery and Sarakhs corridor hold pre-development sites pending high-voltage line completion.
Iran Wind Energy Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic assembly investments and foreign technology licensing reshape supply availability. The vendor base stratifies between state-backed integrated manufacturers, international technology licensors, and regional service specialists. Three archetypes define positioning: domestic full-solution providers with manufacturing depth, international turbine suppliers with technology leadership, and regional maintenance operators with localization advantages. Competitive intensity centers on foreign exchange access negotiations and domestic content compliance rather than pure price rivalry.
Among international technology providers, Vestas Wind Systems and Siemens Gamesa Renewable Energy occupy positions shaped by currency rationing constraints and service network reach. MAPNA Group anchors the domestic assembly tier through backward integration into blade manufacturing and nacelle fabrication. These three represent the dominant competitive anchors as procurement patterns bifurcate between import-dependent utility-scale projects and locally sourced distributed generation deployments.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Ming Yang Smart Energy |
| MAPNA Group |
| Saba Niroo |
| General Electric Company |
| MahTaab Group |
| Vestas Wind Systems |
| Envision Group |
| Goldwind |
| Others |
Supply & Pricing Matrix
Steel metallurgical input costs cascade through turbine tower fabrication into project-level capital expenditure tiers, with domestic MAPNA assembly commanding premium positioning against import-dependent alternatives constrained by central bank foreign exchange rationing.
Pricing Analysis
Volume procurement by state-backed utilities anchors the lower-margin tier, while distributed generation contracts for industrial offtakers capture higher-margin returns through bilateral power purchase agreements. Price differentiation hinges on domestic content compliance thresholds and after-sales service bundling duration. Cost compression in the import-dependent segment is intensifying because currency access bottlenecks force developers toward MAPNA's locally assembled offerings. State utilities exhibit highest price sensitivity due to SUNA feed-in tariff banding constraints, whereas captive industrial buyers in Isfahan and Kerman provinces demonstrate lowest sensitivity as they prioritize supply security over unit economics.
Supply Chain Analysis
Freight cost escalation from European and East Asian manufacturing hubs compounds landed turbine pricing for Vestas and Siemens Gamesa shipments subject to Iranian port handling complexities. Component sourcing draws from Germany for precision drivetrain assemblies, Denmark for blade design licensing, and China for power electronics and rare earth magnet supplies. Raw material dependencies span high-grade steel for towers, copper for generator windings, and bauxite for nacelle housing alloys. Single-source vulnerability concentrates in advanced pitch control systems where proprietary software integration limits supplier substitution. Distribution runs through MAPNA Group's domestic assembly facilities for utility-scale deployment, while regional service hubs sustain long-term operations contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foreign exchange rationing creates a supply-constrained procurement environment where domestic manufacturing capacity anchors pricing power and compresses import-dependent competitor margins.
For Market Incumbents: Anchor market position through backward integration into blade manufacturing and nacelle fabrication, mirroring MAPNA Group's captive supply model that insulates against currency access volatility. Deepen service network localization in Sistan-Baluchestan corridors to extend contract durations and recurring revenue streams. Defend against emerging Chinese turbine suppliers by accelerating control system software convergence with SCADA platforms. For New Entrants and Emerging Players: Capture white-space opportunity in industrial behind-the-meter deployment across Isfahan and Kerman manufacturing zones, where grid instability drives captive wind investment outside traditional utility structures. Target Yazd Province steel sector offtakers negotiating bilateral contracts for supply security. Penetrate through direct power purchase agreement structuring expertise rather than equipment supply competition. For Investors and Strategic Acquirers: SUNA feed-in tariff banding reforms that prioritize transmission-backed sites over remote wind corridors is the leading indicator that project development rights in southeastern provinces with backbone access will command scarcity premiums. Long-term viability rests on exposure to distributed generation segments with industrial offtaker diversification. Acquisition targets should demonstrate domestic content compliance capabilities and established currency access protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | MAPNA Group's blade assembly expansion reduces import dependency and accelerates commissioning timelines under SUNA procurement mandates. |
| Control System Software Licensing | Pitch-yaw algorithm integration with SCADA platforms differentiates turbine performance in Sistan-Baluchestan's variable wind regimes. |
| Service Network Localization | Vestas regional maintenance hubs in southeastern provinces extend contract durations and recurring revenue streams. |
| Industrial Direct Power Purchase Agreements | Steel and cement offtakers in Isfahan bypass utility intermediaries for behind-the-meter supply security. |
| Transmission-Backed Site Prioritization | Developers cluster projects near existing substations to capture SUNA tariff banding premiums in grid-accessible zones. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings on procurement pattern shifts. Secondary validation draws from SUNA regulatory filings, national electricity regulator grid integration standards, central bank foreign exchange allocation protocols, and project development databases. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators to establish market sizing boundaries.
Rate-of-change decomposition across the analysis window isolates capacity factor improvements, tariff reform impacts, and currency access volatility effects on investment timelines. Segmentation dimensions span technology configuration, application architecture, end-user type, and component category alongside regional grid backbone availability. CAGRs derive from installed capacity buildout trajectories, project pipeline maturation curves, and industrial offtake contracting velocity. Forecast inputs incorporate steel price volatility indices and foreign exchange rationing protocol adjustments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SUNA regulatory continuity, transmission infrastructure completion schedules, and geopolitical trade restriction evolution. Forecasts reflect documented assumptions regarding feed-in tariff stability and domestic manufacturing capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Greece Wind Energy Market