
 Water Tube Industrial Boiler Market | 2026-2036
Water Tube Industrial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Water Tube Industrial Boiler Market Analysis
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote monitoring platforms. Babcock and Wilcox Enterprises leverages its century-long field service archive to anchor long-term operator agreements. Siemens competes through digital twin integration that sustains recurring software revenue streams alongside hardware sales.
Water tube industrial boilers contain heated water and steam within tubes that circulate through a combustion-heated furnace, with operating pressures commonly exceeding 150 psi for heavy process loads. Their primary purpose is to generate high-pressure steam for continuous industrial operations requiring thermal energy at scale. Gas-fired systems occupy the largest installed base across chemical and food processing plants, while biomass configurations represent the fastest-growing technology category as carbon accounting tightens. Combined Heat and Power applications concentrate margin pools where facilities can monetize both steam and electricity outputs.
EPA emissions standards under the Clean Air Act shape boiler MACT requirements for hazardous air pollutants, while ASME Boiler and Pressure Vessel Code governs design certification and market access across North American installations. India's Central Electricity Authority mandates efficiency benchmarks that filter out subcritical units from new industrial permits. Stakeholders must monitor how carbon border adjustment mechanisms redefine the cost calculus between fossil and renewable thermal systems.
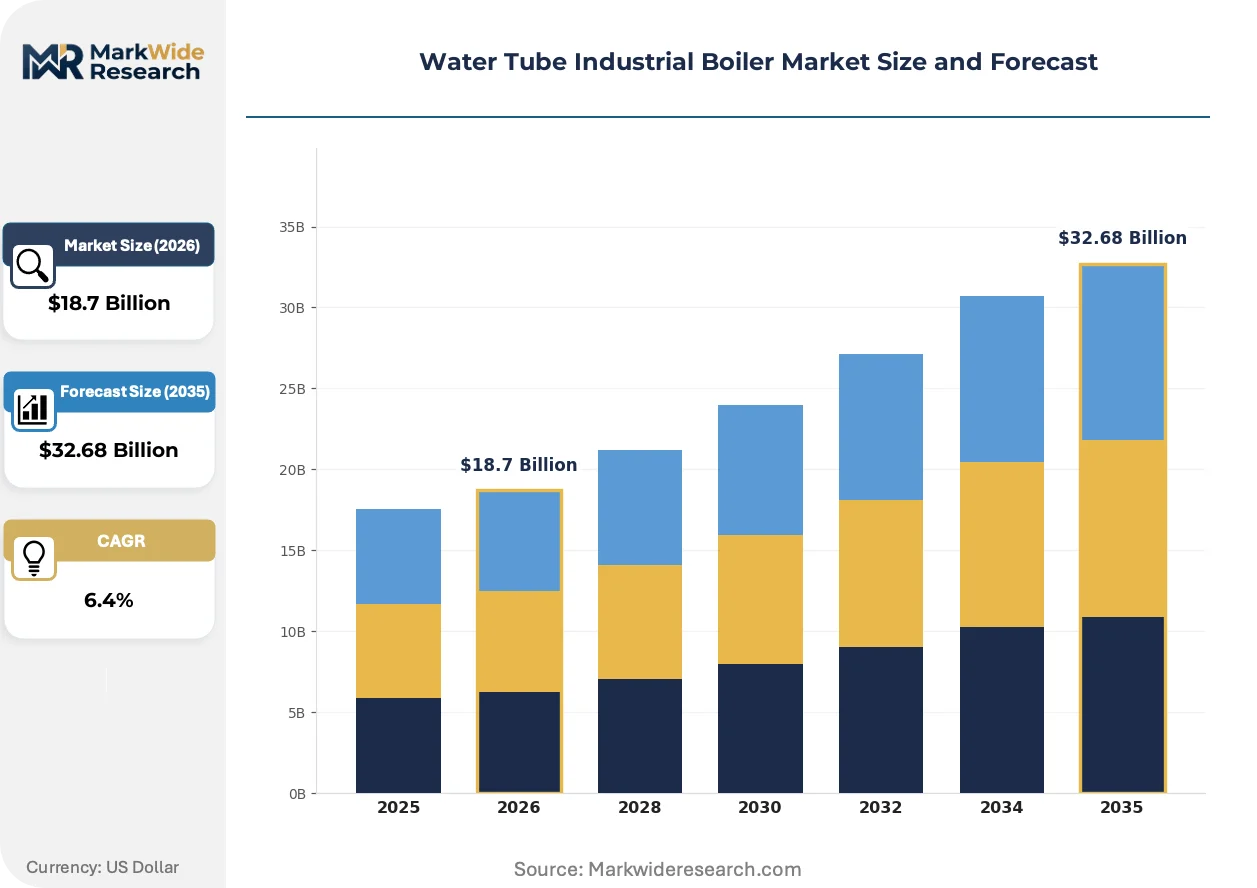
Market Dynamics
Carbon border adjustment mechanisms are rewriting the fuel economics of industrial steam generation, forcing facility operators to recalculate payback periods on biomass retrofits against gas-fired baseload systems.
Growth Catalysts
- CEA Efficiency Mandates:India's Central Electricity Authority benchmarks filter subcritical units from new industrial permits, accelerating replacement demand across Maharashtra and Gujarat manufacturing clusters.
- Biomass Combustion Technology:Carbon accounting tightening in EU ETS jurisdictions drives adoption of agricultural residue and wood pellet firing systems in food processing and pulp operations.
- Southeast Asian Chemical Corridor Expansion:Petrochemical capacity additions in Vietnam, Indonesia, and Thailand require high-pressure steam infrastructure for continuous process heat.
Market Restraints
- Specialized Alloy Supply Concentration:ASME Section I certified tubing for supercritical pressures sources predominantly from German and Japanese specialty steel mills, creating input bottlenecks.
- EPA Boiler MACT Compliance Costs:Hazardous air pollutant monitoring and control retrofit requirements impose capital burdens on aging coal and residual oil installations.
- Electrification Substitution:Industrial heat pumps and electrode boilers capture low-temperature steam loads below 150 psi in food and textile applications.
Strategic Opportunities
- India Western Industrial Belt:State-level energy efficiency mandates in Gujarat and Rajasthan compress replacement cycles for aging grate-fired assets.
- Digital Twin Convergence:Integration of physics-based simulation with IoT sensor networks enables predictive tube failure detection and outage scheduling optimization.
- Green Hydrogen Combustion Trials:Pilot programs at European chemical complexes test hydrogen cofiring in modified gas-fired water tube furnaces for near-zero process heat.
Industry Challenges
- ASME Stamp Certification Timelines:Third-party inspection backlogs and witness hold points extend project delivery schedules by 4-8 months for pressure vessel fabrication.
- Specialized Welder Scarcity:Qualified tube-to-header welders for high-alloy materials command premium wages and constrain fabrication capacity at OEM shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Tube Industrial Boiler Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Coal-Fired, Gas-Fired, Biomass, Oil-Fired End User: Chemical Industry, Food Processing, Pharmaceuticals, Power Generation Technology: Condensing, Superheated, Circulating Fluidized Bed, Combined Heat and Power Application: Heating, Steam Generation, Process Heating, Power Supply |
| Companies Covered | Babcock and Wilcox Enterprises, Cleaver-Brooks, Doosan, Bosch Thermotechnology, Thermax, Bharat Heavy Electricals Limited, Siemens, Fulton Boiler Works, Hurst Boiler and Welding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Tube Industrial Boiler Market Emerging Trajectories
Steam generation technology is pivoting toward fuel flexibility and predictive operability as operators face simultaneous pressure on emissions accountability and uptime guarantees.
Supercritical once-through designs are migrating from utility-scale power generation into large industrial process applications. Chemical complexes in the US Gulf Coast and Rotterdam port zones adopt these systems for steam pressures above 3,200 psi. The technology is migrating from power-only configurations toward combined heat and power architectures that maximize exergy recovery from fuel input.
EPA's updated Boiler Maximum Achievable Control Technology standards tighten particulate matter and mercury emission limits for solid fuel combustion. Industrial facilities must install continuous emissions monitoring systems and upgrade particulate controls. Biomass-fired installations face the steepest compliance gradient, driving retrofit demand for multi-cyclone and fabric filter upgrades.
Service contracting is unbundling from equipment sales as operators prioritize availability guarantees over capital ownership. Chemical and refining buyers in the US and EU now specify long-term performance contracts with penalty clauses for unplanned outages. This restructuring concentrates margin pools with field service organizations that maintain century-long equipment archives and predictive analytics capabilities.
Water Tube Industrial Boiler Market Segmentation
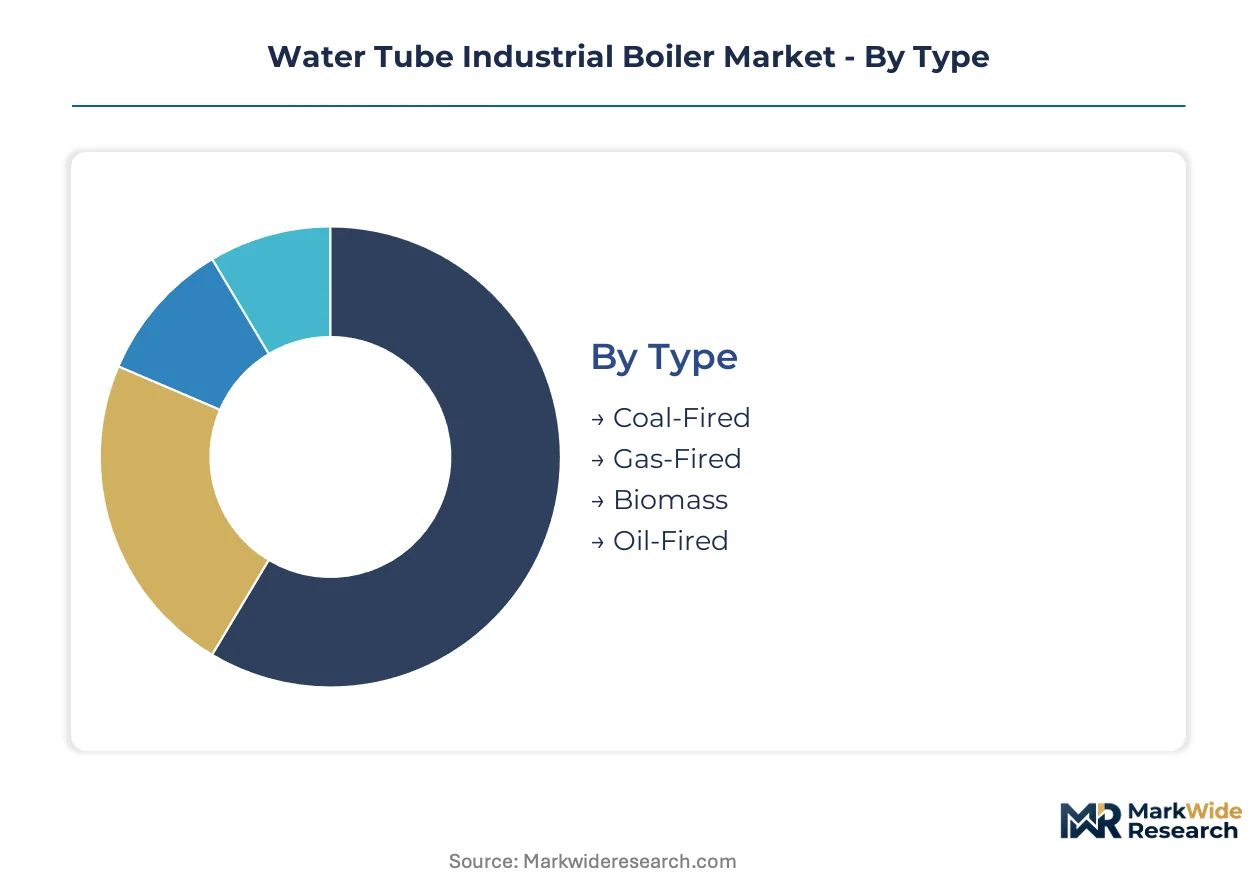
Water tube industrial boiler procurement decisions cascade through four distinct filtering dimensions. Fuel type determines emissions compliance pathways and operating cost structures. End-use concentration shapes pressure specifications and redundancy requirements across process industries.
Type:
Fuel selection anchors capital expenditure profiles and regulatory exposure for facility operators.
- Gas-Fired:Natural gas burners achieve sub-9 ppm NOx emissions without post-combustion controls. Chemical plants along the US Gulf Coast specify these systems to satisfy EPA Boiler MACT limits while maintaining thermal efficiency above 85 percent.
- Biomass:Agricultural residue and wood pellet combustion systems integrate fluidized bed grates with staged air injection. EU ETS carbon pricing in Germany and the Netherlands accelerates retrofit demand as facilities seek to neutralize scope 1 emissions.
- Coal-Fired:Pulverized coal configurations persist in legacy industrial parks where fuel switching economics remain unfavorable.
- Oil-Fired:Residual fuel oil units occupy backup and peaking roles in facilities with interruptible gas supply contracts.
Gas-fired systems command the established base. The steepest expansion runs through biomass configurations.
End User:
Process intensity and steam quality requirements differentiate buyer specifications across industrial verticals.
- Chemical Industry:Petrochemical crackers and specialty chemical reactors demand superheated steam above 450°C at pressures exceeding 1,500 psi. Maharashtra and Gujarat manufacturing clusters in India drive replacement demand as CEA efficiency mandates disqualify subcritical units from new permits.
- Food Processing:Sterilization and drying operations require saturated steam with precise moisture control. Southeast Asian canneries and dairy processors in Vietnam and Thailand specify stainless steel contact surfaces to satisfy FSSAI and local food safety codes.
- Pharmaceuticals:Clean steam generation for autoclaves and fermentation vessels mandates ASME BPE compliance.
- Power Generation:Cogeneration facilities monetize both electricity export and process steam to industrial off-takers.
Chemical industry buyers anchor volume concentration. Food processing applications are climbing the fastest as export-oriented manufacturing expands.
Technology:
Thermodynamic cycle architecture determines fuel conversion efficiency and operational flexibility.
- Combined Heat and Power:Cogeneration configurations extract mechanical work through back-pressure or extraction turbines before delivering process steam. Rotterdam port zone refineries deploy these systems to maximize exergy recovery from fuel input.
- Superheated:Once-through designs generate dry steam above saturation temperature for turbine drives and high-temperature process heat. US Gulf Coast chemical complexes adopt supercritical variants for pressures above 3,200 psi.
- Condensing:Full condensing turbines maximize power output where steam has no process use.
- Circulating Fluidized Bed:CFB combustion accommodates fuel variability and low-grade biomass with in-situ sulfur capture.
Combined Heat and Power dominates margin capture. Superheated technology is gaining share fastest as process intensification demands higher thermal grades.
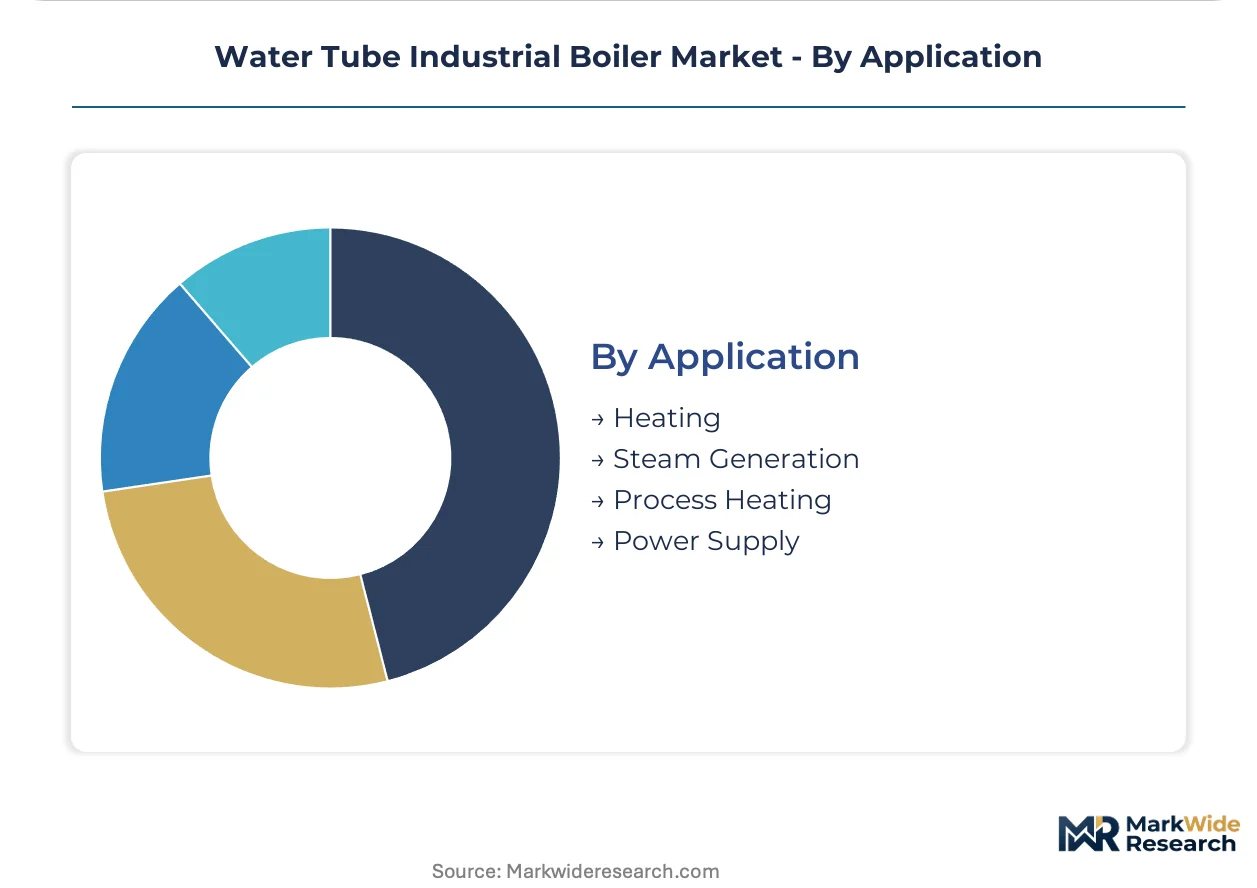
Application:
Steam end-use dictates pressure, temperature, and purity specifications for system design.
- Process Heating:Direct and indirect heat transfer to reactors, distillation columns, and thermal oxidizers consumes the largest share of industrial steam output. India's western industrial belt specifies high-pressure systems for caustic soda and fertilizer production.
- Steam Generation:Central boiler plants distribute utility steam through header networks to multiple process units. Food processing campuses in Indonesia and Thailand consolidate generation to capture scale economies.
- Heating:Space heating and hot water production for industrial facilities operates at lower pressures.
- Power Supply:Steam-to-electricity conversion for on-site generation or grid export.
Process heating commands the established base. Steam generation infrastructure is expanding most quickly as manufacturing corridors consolidate utility services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers exhibit the highest price elasticity as CEA mandates force premature retirements of subcritical assets. German purchasers absorb premium pricing for ASME-certified supercritical systems to satisfy EU ETS carbon accounting. Southeast Asian chemical operators balance capital constraints against petrochemical capacity expansion timelines.
United States
Chemical complexes along the US Gulf Coast drive supercritical adoption for steam pressures above 3,200 psi. EPA Boiler MACT standards tighten hazardous air pollutant limits for solid fuel installations. Houston and Port Arthur refining corridors specify gas-fired baseload systems to satisfy emissions benchmarks while maintaining thermal efficiency.
Germany
EU ETS carbon pricing accelerates biomass retrofit demand across pulp and food processing operations. ECHA chemical safety regulations influence material specifications for high-alloy pressure vessel fabrication. The Rhine-Ruhr industrial belt concentrates fluidized bed grate installations seeking agricultural residue combustion compliance.
India
State-level energy efficiency mandates in Gujarat and Maharashtra compress replacement cycles for aging grate-fired boilers. CEA efficiency benchmarks filter subcritical units from new industrial permits. The western industrial belt spanning Vadodara to Surat anchors chemical industry demand for high-pressure steam infrastructure.
China
Dual carbon goals and provincial emissions intensity targets drive supercritical technology adoption in coastal manufacturing zones. MIIT industrial efficiency standards accelerate retirement of sub-300 MW thermal assets. The Yangtze River Delta petrochemical corridor consolidates utility steam generation to capture scale economies.
Vietnam
Export-oriented food processing and cannery expansion creates saturated steam demand with precise moisture control requirements. National technical standards for pressure equipment safety govern ASME-equivalent certification pathways. The southern manufacturing belt around Ho Chi Minh City concentrates stainless steel contact surface specifications for FSSAI-aligned food safety codes.
Water Tube Industrial Boiler Market Vendor Landscape
Capability concentration sits with specialty alloy fabricators holding ASME Section I certifications; scale advantage sits with diversified industrial conglomerates with captive energy divisions. The market structures around three tiers: century-long field service archives anchoring long-term operator agreements, digital-integrated OEMs monetizing recurring software revenue, and regional fabricators competing on delivery timelines. Dominant competitive moves include backward integration into high-alloy tubing supply and geographic expansion through local fabrication joint ventures.
Within the diversified industrial tier, Siemens and Doosan exemplify scale-driven positioning across multiple thermal technology verticals. Babcock and Wilcox Enterprises occupies the service-archive archetype, leveraging field data repositories to anchor performance-based contracts. Among Asia-Pacific fabricators, Thermax and Bharat Heavy Electricals Limited represent regional champions with domestic regulatory alignment advantages.
| Leading Market Players |
|---|
| Babcock and Wilcox Enterprises |
| Cleaver-Brooks |
| Doosan |
| Bosch Thermotechnology |
| Thermax |
| Bharat Heavy Electricals Limited |
| Siemens |
| Fulton Boiler Works |
| Hurst Boiler and Welding |
| Others |
Supply Flow & Price Mechanics
ASME Section I certified tubing bottlenecks from German and Japanese specialty steel mills determine both pricing tier spreads and supply chain shape across supercritical pressure installations. Buyers face elongated procurement timelines when sourcing high-alloy materials for certified pressure vessels, compressing margins for project-based contracts while inflating premiums for expedited delivery.
Pricing Analysis
Long-term performance contracts with availability guarantees dominate procurement structures for chemical and refining operators in the US and EU. Pricing stratifies across ASME-certified supercritical systems, standard pressure units, and economy-grade grate-fired configurations based on certification tier and after-sales service bundling. Cost compression in the economy tier is intensifying as Indian state mandates accelerate replacement demand. Chemical industry buyers in Maharashtra and Gujarat exhibit the highest price sensitivity, while US Gulf Coast refineries absorb premium pricing for emissions-compliant gas-fired baseload systems.
Supply Chain Analysis
Contract manufacturing capacity for high-alloy pressure vessels concentrates in Germany, Japan, and India, with ASME-certified fabricators commanding 4-8 month delivery premiums. Raw material dependencies center on nickel-chromium superalloys, specialty welding consumables, and precision-machined tube headers. Single-source vulnerability runs through German and Japanese specialty steel mills for supercritical tubing. Distribution runs through OEM-direct channels for large installations and regional fabricator networks for standard pressure units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial heat pumps and electrode boilers threaten low-pressure steam applications below 150 psi, forcing incumbents to defend core high-pressure process heat positions.
For Market Incumbents: Entrench field service archives as predictive maintenance platforms to anchor long-term operator agreements and recurring revenue streams. Deepen backward integration into high-alloy tubing supply to bypass German and Japanese mill bottlenecks. Defend against electrification substitution by emphasizing supercritical steam grades that heat pumps cannot economically replicate.
For New Entrants and Emerging Players: Establish a beachhead in India's western industrial belt where CEA efficiency mandates compress replacement cycles for aging grate-fired assets. Target biomass combustion retrofits in EU ETS jurisdictions as carbon pricing accelerates agricultural residue firing adoption. Pursue joint venture fabrication partnerships with ASME-certified regional shops to circumvent third-party inspection backlogs.
For Investors and Strategic Acquirers: EPA Boiler MACT updates reshape the acquisition landscape by imposing hazardous air pollutant compliance burdens on aging coal and residual oil installations. Long-term viability favors digital-integrated OEMs with recurring software revenue streams over pure hardware fabricators. Monitor carbon border adjustment mechanism announcements as the critical inflection signal for biomass retrofit demand trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Alloy Tubing | Captive supply of ASME Section I certified materials bypasses German and Japanese mill bottlenecks. |
| Digital Twin Platform Deployment | Physics-based simulation with IoT sensor networks enables predictive tube failure detection for chemical operators. |
| Biomass Combustion Retrofit Programs | Agricultural residue firing systems capture EU ETS carbon pricing arbitrage in pulp and food processing. |
| Long-term Performance Contracting | Availability guarantees with penalty clauses shift margin pools from equipment sales to field service archives. |
| Green Hydrogen Cofiring Trials | Pilot programs at European chemical complexes test modified gas-fired furnaces for near-zero process heat. |
Methodological Framework
A standing panel of plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads provided ongoing calibration across primary fieldwork and secondary validation. Primary inputs combined structured interviews with boiler operators in chemical, food processing, and power generation facilities alongside technical discussions with ASME-certified fabricators. Secondary sources encompassed EPA Boiler MACT filings, CEA efficiency benchmark notifications, EU ETS carbon price data, and SEC disclosures from diversified industrial conglomerates. Bottom-up unit economics triangulated against top-down sectoral demand models.
Scenario-bracketing anchored the analytical framework across the projection horizon, with low-case assumptions reflecting accelerated electrification substitution and high-case assumptions incorporating green hydrogen combustion adoption. Segmentation dimensions modeled included fuel type, pressure tier, end-use industry, technology architecture, and regional regulatory cluster. CAGRs derived from installed base turnover rates, replacement cycle compression factors, and capacity expansion pipelines in petrochemical corridors.
Sensitivities concentrate around carbon border adjustment mechanism implementation timelines, ASME certification inspection backlogs, and specialty welder availability constraints. Quarterly review of EU ETS carbon price trajectories, Indian state-level mandate announcements, and EPA enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Waste Heat Boiler Market
Boilers
Advanced Utility Boilers Market
Boilers
GCC Electric Water Heater Market
Boilers
Superheater Market
Boilers
Field Erected Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Oil-Fired Boiler Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
US Commercial Boiler Market
Boilers
Boiler System Market
Boilers
Steam Boiler Market
Boilers
Industrial Biomass Boiler Market
Boilers
Europe Combined Heat and Power Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Electric Boiler Market