
 Industrial Boiler MRO Market | 2026-2036
Industrial Boiler MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Boiler MRO Market Foresight
North American aftermarket parts producers is recalibrating output schedules to match extended boiler lifecycles across aging power infrastructure. Babcock & Wilcox Enterprises leverages its heritage installation base to sustain long-term service contracts in utility-scale plants. Mitsubishi Heavy Industries anchors its position through proprietary burner technology leadership in high-pressure steam systems. General Electric Company competes on digital monitoring platforms that integrate control system diagnostics with field service dispatch.
Industrial boiler MRO encompasses the technical servicing, component replacement, and performance restoration of combustion systems operating at pressures exceeding 15 psig, involving metallurgical assessment of fire-tube and water-tube configurations to sustain thermal efficiency above mandated thresholds. The primary purpose centers on extending asset life while ensuring emissions compliance and fuel optimization across continuous-process manufacturing. Diagnostic services now command premium margins as facilities shift from calendar-based to condition-based intervention models, while burner replacement cycles accelerate under tighter NOx regulations. Water-tube technology segments attract concentrated overhaul investment due to higher pressure ratings and more complex retubing requirements in power generation end uses.
EPA boiler MACT standards and OSHA process safety management protocols in the United States shape inspection frequency and replacement part specifications, while EU F-Gas Regulation and REACH compliance in Europe constrain refrigerant and coating choices in auxiliary heat exchanger work. India's Central Pollution Control Board mandates particulate emission audits that drive control system upgrades in manufacturing clusters. Stakeholders must weigh captive maintenance team scale against third-party specialist depth as regulatory complexity outpaces in-house technical currency.
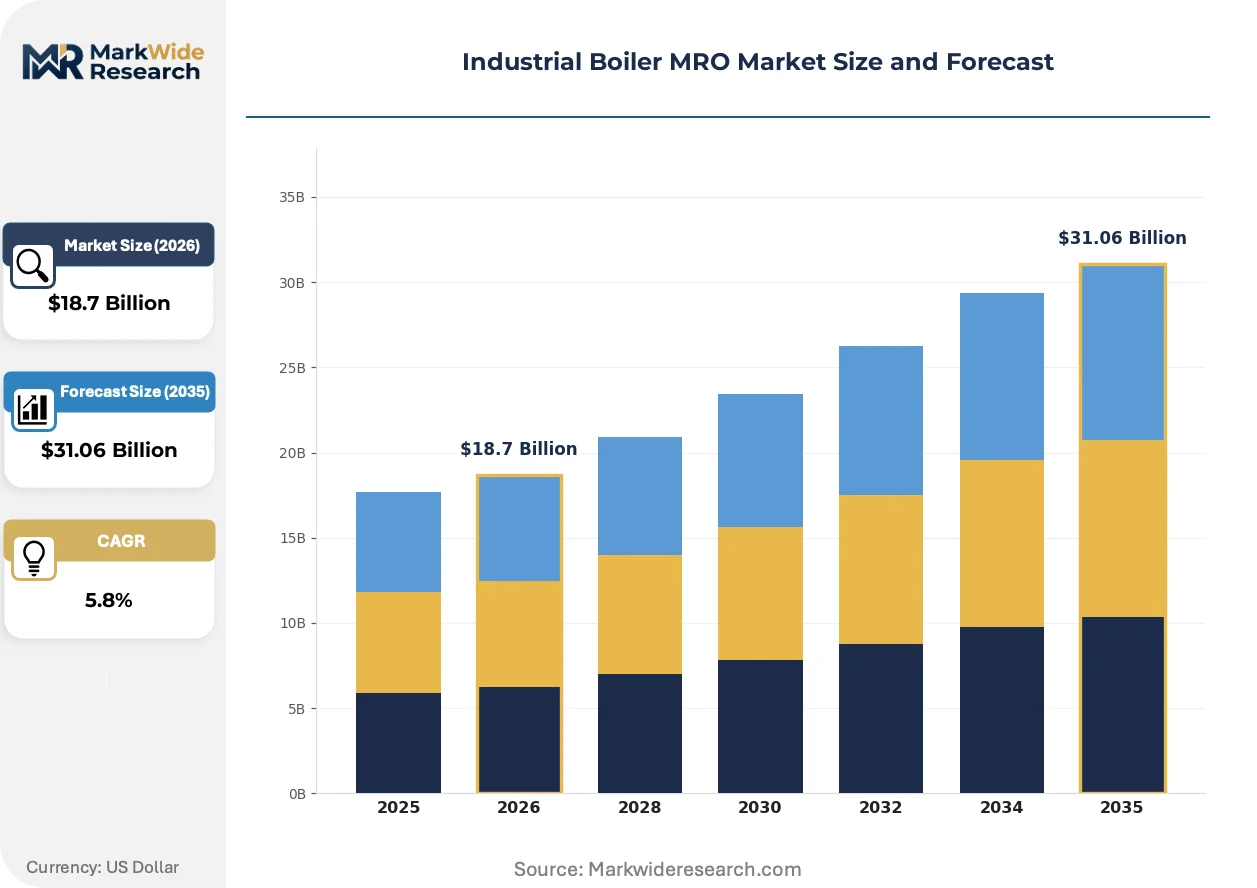
Market Dynamics
Digital twin diagnostics is consolidating maintenance protocols across industrial boiler fleets, compressing scheduled outage windows and forcing recalibration of MRO contract structures toward condition-based service models.
Growth Catalysts
- EPA Boiler MACT compliance deadlines:Chemical processing facilities along the US Gulf Coast are expanding multi-year maintenance contracts to meet emissions retrofit requirements ahead of enforcement phases.
- PM2.5 enforcement acceleration:India's Central Pollution Control Board mandates particulate emission audits that compress boiler retrofit cycles in the National Capital Region manufacturing belt.
- Predictive sensor deployment:European refineries are displacing calendar-based shutdown models with continuous vibration and thermal monitoring systems that flag tube degradation before failure.
Market Restraints
- Specialized alloy supply concentration:Superheater tube replacement depends on nickel-chromium alloy availability concentrated in limited smelting capacity regions, creating procurement bottlenecks during peak turnaround seasons.
- REACH compliance friction:EU F-Gas Regulation and ECHA coating restrictions constrain refrigerant and surface treatment choices for auxiliary heat exchanger refurbishment, extending material qualification timelines.
- Skilled welder scarcity:ASME Section IX certified pressure vessel welders command premium labor rates that inflate retubing project costs beyond budgeted maintenance allocations.
Strategic Opportunities
- Small-scale distributed generation retrofit:Food processing and pharmaceutical facilities in Germany seek modular burner upgrades to accommodate hydrogen fuel blending trials under EU Green Deal industrial decarbonization pathways.
- Remote diagnostics platform expansion:Control system OEMs are converging edge computing with cloud-based analytics to offer subscription monitoring services bypassing traditional field service dispatch models.
- Biomass cofiring conversion:Pulp and paper mills in Sweden and Finland pursue grate system modifications to handle higher-alkali agricultural residue fuels supported by national renewable heat incentive schemes.
Industry Challenges
- Legacy control system integration:Digital twin deployment requires protocol translation layers to interface with 1990s-era DCS architectures common in aging power infrastructure, complicating sensor network rollout.
- Compressed outage windows:Continuous-process chemical manufacturers resist extended shutdowns, forcing MRO contractors to execute retubing and refractory replacement in parallel with partial unit operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Boiler MRO Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Diagnostic Services Product Category: Burners, Controls, Pumps, Heat Exchangers End User: Manufacturing Plants, Power Generation, Oil & Gas, Food Processing Technology: Condensing, Modular, Fire-Tube, Water-Tube |
| Companies Covered | Thermax Global, Hurst Boiler & Welding, General Electric Company, Stork, WIKA Instruments India, Mitsubishi Heavy Industries, Babcock & Wilcox Enterprises, Jera Power Taketoyo, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Boiler MRO Market Shifts & Advancements
Maintenance execution models are pivoting from reactive component replacement toward integrated asset performance management, embedding metallurgical assessment and emissions optimization into unified service architectures.
Digital twin platforms are consolidating predictive maintenance vendor landscapes by integrating thermal-hydraulic simulation with real-time sensor feeds. Refinery operators in the Netherlands and Belgium are adopting these systems fastest, collapsing the distinction between engineering consultancy and field service provision into single-source accountability structures.
OSHA process safety management enforcement is intensifying inspection documentation requirements for high-pressure steam systems. Facilities must now maintain continuous audit trails of weld repairs and pressure test records, driving demand for blockchain-anchored maintenance logs that satisfy both regulatory review and insurance underwriting scrutiny in US manufacturing clusters.
Service contract unbundling is fragmenting traditional full-coverage MRO agreements into discrete modules for diagnostics, parts supply, and labor dispatch. Chemical processors in Texas and Louisiana are piloting this approach to match maintenance spend more precisely to actual asset condition, though the transition creates coordination friction between multiple specialist vendors during critical turnaround periods.
Industrial Boiler MRO Market Segmentation
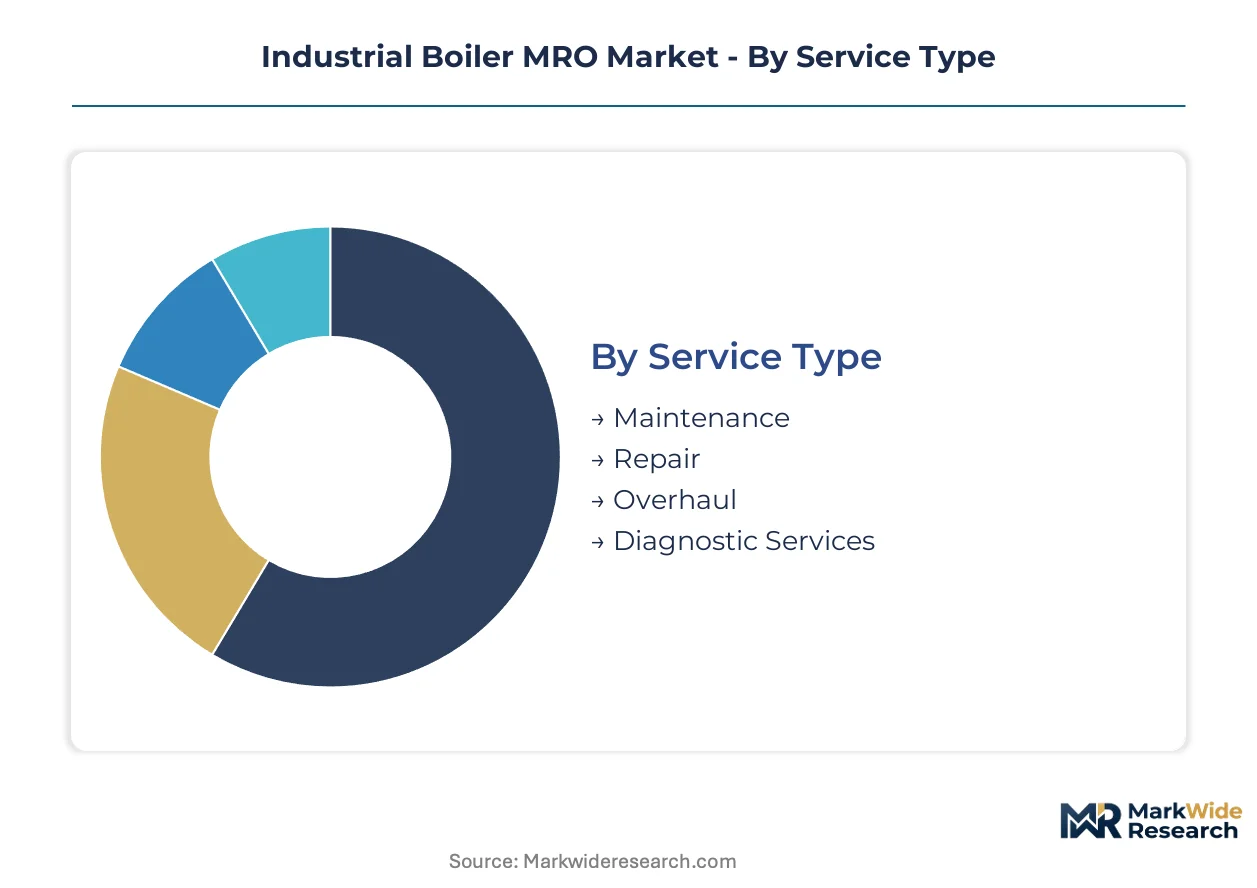
Industrial boiler MRO procurement patterns diverge sharply across service modalities, hardware categories, and technology vintages. Understanding these axes reveals where margin concentrates and where contract structures are destabilizing.
Service Type:
Technical service intensity varies by intervention depth, with predictive protocols commanding premium pricing over reactive models.
- Maintenance:Scheduled preventive work includes tube cleaning, refractory inspection, and combustion tuning to sustain thermal efficiency above regulatory thresholds. Demand clusters in Texas and Louisiana chemical corridors where EPA Boiler MACT compliance deadlines compress turnaround windows.
- Repair:Unplanned corrective interventions address tube leaks, burner degradation, and control system failures. Procurement concentrates in aging power infrastructure across the US Midwest where extended asset lifecycles outpace replacement capital availability.
- Overhaul:Comprehensive unit rebuilds involving pressure part replacement and control system modernization. Germany's industrial clusters are seeing accelerated overhaul cycles as EU F-Gas Regulation mandates auxiliary heat exchanger refurbishment.
- Diagnostic Services:Continuous monitoring and predictive analytics deployment. India's National Capital Region manufacturing belt is adopting vibration and thermal monitoring fastest under Central Pollution Control Board PM2.5 enforcement pressure.
Mature deployment sits with Maintenance. Newer deployment is concentrated in Diagnostic Services.
Product Category:
Component replacement cycles track regulatory pressure points and fuel transition timelines, with burner systems seeing shortest effective lifespans under tightening NOx limits.
- Burners:Combustion hardware requiring frequent replacement or upgrade to meet evolving emissions standards. Sweden and Finland pulp and paper mills are modifying grate systems for biomass cofiring under national renewable heat incentives.
- Controls:Distributed control system modules and safety instrumented systems. Netherlands and Belgium refineries are integrating digital twin platforms fastest, collapsing engineering consultancy and field service into unified accountability structures.
- Pumps:Feedwater and circulation pump refurbishment. Replacement demand tracks boiler utilization rates in continuous-process manufacturing.
- Heat Exchangers:Auxiliary heat recovery surface restoration. REACH compliance and ECHA coating restrictions extend material qualification timelines for European refurbishment work.
Control system retrofits are climbing the fastest as digital monitoring displaces scheduled shutdown models.
End User:
Facility type determines outage tolerance, regulatory exposure, and contract structure preferences across MRO procurement.
- Manufacturing Plants:Chemical, steel, and cement operations with continuous-process economics. US Gulf Coast facilities are expanding multi-year maintenance contracts to synchronize with EPA compliance phases.
- Power Generation:Utility and industrial captive power operations. Aging infrastructure across the US Midwest sustains long-term service relationships with heritage installation vendors.
- Oil & Gas:Refinery and petrochemical steam systems. European operators are adopting condition-based intervention models fastest through predictive sensor deployment.
- Food Processing:Lower-pressure steam applications with hygiene-critical requirements. German facilities are piloting hydrogen fuel blending trials under EU Green Deal decarbonization pathways.
Power Generation represents the most mature contract structures. Food Processing is gaining share fastest through sustainability-linked retrofit demand.
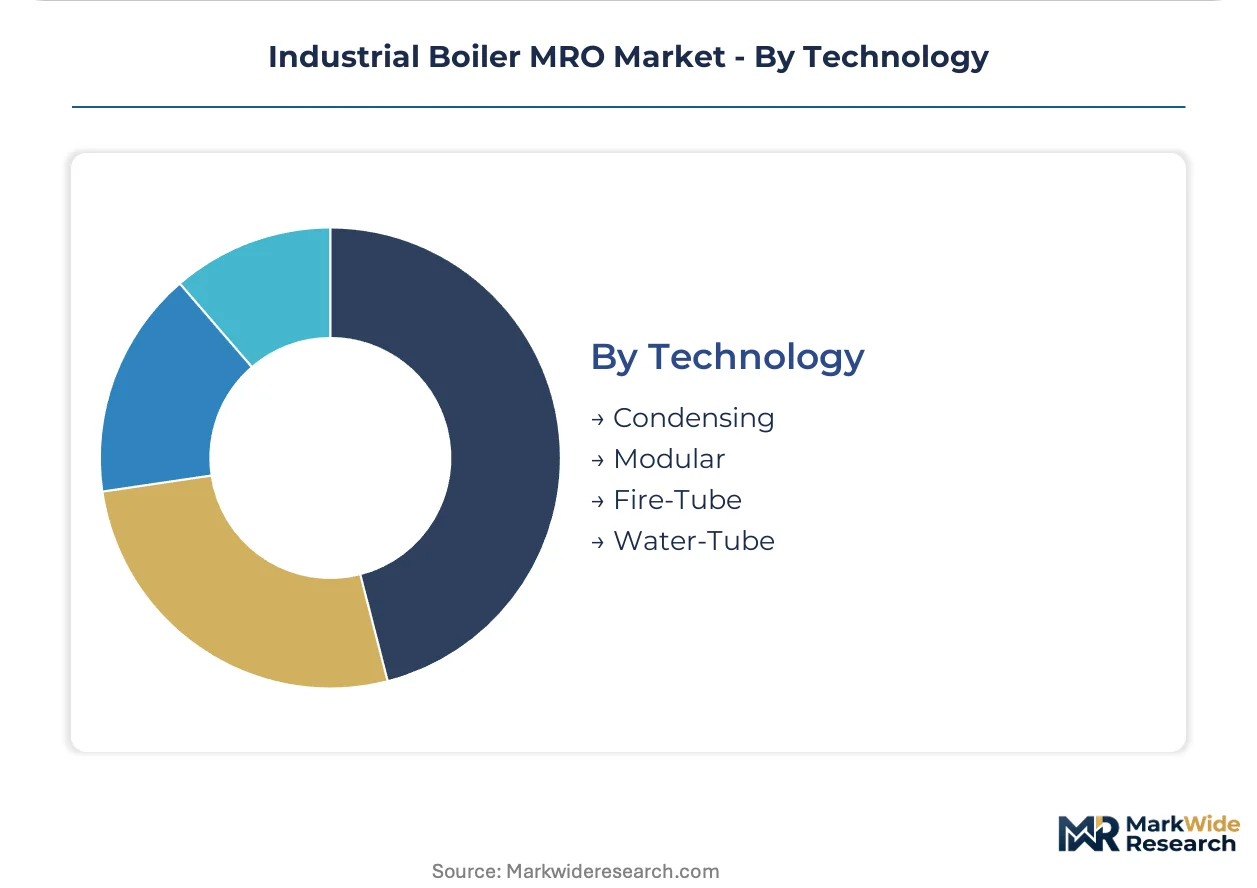
Technology:
Boiler configuration dictates pressure capability, maintenance complexity, and replacement part specifications.
- Condensing:High-efficiency designs recovering latent heat from flue gases. Deployment concentrates in European commercial and light industrial applications under energy efficiency directives.
- Modular:Skid-mounted units enabling rapid deployment and scaled capacity addition. Food and pharmaceutical facilities in Germany are adopting modular burner upgrades for fuel flexibility trials.
- Fire-Tube:Shell-and-tube designs with lower pressure ratings and simpler retubing requirements. Maintenance protocols are well-standardized across North American manufacturing plants.
- Water-Tube:High-pressure configurations with complex tube arrays and superheater circuits. Concentrated overhaul investment in power generation end uses due to metallurgical complexity and ASME Section IX welding requirements.
Fire-Tube systems represent the most standardized MRO protocols. Water-Tube technology commands the steepest expansion trajectory in diagnostic service attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel-chromium alloy smelting capacity in Russia and South Africa underpins superheater tube supply chains serving high-pressure boiler fleets across industrial corridors.
United States
EPA Boiler MACT compliance deadlines compress turnaround windows along the Gulf Coast chemical corridor. OSHA process safety management protocols mandate continuous audit trails for weld repairs and pressure test records. Texas and Louisiana facilities expand multi-year maintenance contracts to synchronize emissions retrofit requirements with enforcement phases.
Germany
EU F-Gas Regulation and REACH compliance constrain refrigerant and coating choices for auxiliary heat exchanger refurbishment. Food processing and pharmaceutical facilities pilot modular burner upgrades for hydrogen fuel blending trials under EU Green Deal industrial decarbonization pathways. The Ruhr industrial cluster sees accelerated overhaul cycles as material qualification timelines extend.
India
Central Pollution Control Board PM2.5 enforcement accelerates boiler retrofit cycles in manufacturing belts. The National Capital Region adopts vibration and thermal monitoring fastest under particulate emission audit mandates. Gujarat and Maharashtra chemical hubs contract third-party diagnostic specialists as regulatory complexity outpaces in-house technical currency.
Sweden
National renewable heat incentive schemes support grate system modifications for biomass cofiring in pulp and paper mills. Higher-alkali agricultural residue fuels drive demand for metallurgical assessment of fire-bed configurations. The Norrland forest industry corridor concentrates overhaul investment in fuel-flexible combustion hardware.
Netherlands
Refinery operators adopt digital twin platforms fastest, collapsing engineering consultancy and field service into unified accountability structures. Continuous vibration and thermal monitoring systems displace calendar-based shutdown models across Rotterdam-Antwerp petrochemical complexes. Predictive sensor deployment commands premium margins as facilities shift to condition-based intervention models.
Industrial Boiler MRO Market Competitive Landscape
Global majors compete with regional champions across heritage installation bases and digital monitoring capabilities. The vendor landscape stratifies between integrated service providers with captive burner technology and specialized diagnostic platforms licensing predictive analytics. Three archetypes dominate: heritage equipment manufacturers monetizing long-term service contracts, control system OEMs converging edge computing with cloud-based analytics, and regional fabricators capturing turnaround labor dispatch. Competitive intensity centers on M&A to secure ASME-certified welding capacity and strategic partnerships to integrate digital twin diagnostics with legacy DCS architectures.
Within the heritage manufacturer tier, Babcock & Wilcox Enterprises and Mitsubishi Heavy Industries exemplify equipment-origin service models that leverage proprietary installation bases for sustained aftermarket capture. General Electric Company occupies a position at the diagnostic-platform vector, representing the convergence of control system heritage with field service dispatch integration. These three anchors illustrate how competitive positioning separates those with captive combustion hardware intellectual property from those building subscription monitoring architectures that bypass traditional dispatch economics.
| Leading Market Players |
|---|
| Thermax Global |
| Hurst Boiler & Welding |
| General Electric Company |
| Stork |
| WIKA Instruments India |
| Mitsubishi Heavy Industries |
| Babcock & Wilcox Enterprises |
| Jera Power Taketoyo |
| Robert Bosch |
| Others |
Supply & Pricing Matrix
ASME Section IX certified welder concentration in the US Gulf Coast creates labor-cost differentials that widen pricing-tier spreads between premium turnkey contracts and economy labor-only dispatch models.
Pricing Analysis
Warranty bundling separates full-coverage service agreements from unbundled diagnostics-only subscriptions, with three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach digital twin monitoring and guaranteed uptime clauses; economy tiers cover parts-only procurement with self-managed installation. Cost compression in economy tiers is intensifying because procurement teams at Texas chemical facilities squeeze turnaround budgets ahead of EPA compliance deadlines. Small-scale food processors exhibit highest price sensitivity; utility-scale power generators demonstrate lowest sensitivity due to regulatory non-compliance penalties.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for emergency burner and tube shipments to turnaround sites. Nickel-chromium alloy smelting draws from Russia and South Africa; control system modules source from Japan and Germany. Single-source vulnerability concentrates in superheater tube metallurgy where limited smelting capacity creates procurement bottlenecks during peak maintenance seasons. Distribution runs through OEM-authorized service depots that maintain bonded inventory for critical pressure parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME-certified welding capacity scarcity props pricing power for contractors able to guarantee qualified labor availability during compressed outage windows.
For Market Incumbents: Deploy digital twin platform licensing to lock in recurring revenue streams and defend against pure-play diagnostic startups. Acquire regional welding contractors in the US Midwest to secure captive ASME Section IX capacity ahead of competing turnaround bids. Heritage installation bases at Babcock & Wilcox and Mitsubishi Heavy Industries face erosion from subscription monitoring models that bypass traditional dispatch economics. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for hydrogen-ready burner retrofit specialists serving food processing pilot programs. Target diagnostic services in India's National Capital Region where Central Pollution Control Board enforcement outpaces in-house technical currency. Pursue white-label sensor integration partnerships with established control system OEMs to bypass capital-intensive field service infrastructure buildout. For Investors and Strategic Acquirers: Re-rating potential sits with diagnostic-platform specialists given predictive maintenance attachment rate acceleration across European refineries. Long-term viability favors asset-light analytics vendors over capital-heavy fabrication operations exposed to alloy price volatility. Monitor EPA Boiler MACT enforcement phase transitions as inflection indicators for maintenance contract expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel-chromium sourcing insulates margin from Russian smelting capacity disruptions. |
| Digital Twin Platform Launch | Rotterdam refinery operators consolidate engineering consultancy and field service into unified vendor relationships. |
| ASME-Certified Welder Acquisition | Texas Gulf Coast turnaround contractors command premium pricing during EPA compliance-driven demand surges. |
| Hydrogen-Ready Burner Development | German food processors pilot EU Green Deal decarbonization pathways with modular fuel-flexible upgrades. |
| Remote Diagnostics Subscription Rollout | Cloud-based vibration monitoring displaces calendar-based shutdown models across Netherlands petrochemical complexes. |
Research Methodology
Document review covered EPA enforcement schedules, EU F-Gas regulatory filings, and ASME boiler code revisions, complemented by interviews with plant maintenance directors, aftermarket service heads at OEMs, procurement leads at chemical processors, and certified welding contractors. Secondary sources included customs trade data for alloy imports, SEC 10-K disclosures from heritage equipment manufacturers, and Central Pollution Control Board emission audit reports. Bottom-up contract value aggregation and top-down market sizing triangulation validated segment-level estimates.
Cross-referencing historical maintenance spend patterns against panel input from MRO contractors and facility operators anchored growth projections across the analysis window. Segmentation dimensions modeled encompass service type, product category, end-user industry, boiler technology configuration, and regional regulatory cluster. CAGRs derived from unit-level contract value escalation rates and attachment rate assumptions for predictive diagnostics. Forecast inputs incorporated EPA compliance phase timelines and EU Green Deal industrial decarbonization incentive trajectories.
The model assumes a particular technology adoption path; alternative pathways for digital twin deployment would alter the outlook if legacy DCS integration costs exceed projected sensor network rollout budgets. Forecasts reflect stated assumptions regarding alloy supply continuity and skilled labor availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Space Heating Boilers Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Field Erected Boiler Market
Boilers
Boiler System Market
Boilers
Industrial Biomass Boiler Market
Boilers
Oil-Fired Boiler Market
Boilers
Circulating Fluidized Bed Combustion Boiler (CFBC Boiler) Market
Boilers
Steam Boiler Market
Boilers
Fuel Operated Heaters Market
Boilers
Circulating Fluid Bed Boilers Market
Boilers
North America Commercial Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Residential Boiler Market
Boilers
Boiler Control Market
Boilers
Advanced Utility Boilers Market
Boilers
Watertube Boilers Market