
 Feed Water Heater for Power Plants Market | 2026-2036
Feed Water Heater for Power Plants Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Water Heater for Power Plants Market Intelligence
The move toward modular, pre-engineered feed water heater systems is shifting procurement decisions for power plant operators seeking faster installation and standardized performance. General Electric Company leverages its extensive portfolio in turbine and generator integration to offer bundled solutions. Mitsubishi Heavy Industries, Ltd. dominates in high-efficiency designs for large-scale thermal plants, particularly in Asia. Meanwhile, Babcock & Wilcox Enterprises specializes in custom-engineered solutions for both new build and retrofit projects.
A feed water heater for power plants is a heat exchanger designed to preheat water delivered to a steam-generating boiler. These components operate under high pressures and temperatures to improve the thermodynamic efficiency of the power generation cycle. Within product types, closed feed water heaters remain the dominant configuration due to their suitability for high-pressure systems. The application segment for nuclear power facilities shows significant growth potential, driven by stringent safety and performance requirements.
Boiler and pressure vessel codes, such as those from ASME, dictate material and fabrication standards, ensuring operational safety. Emissions regulations from bodies like the U.S. EPA and the EU under its Industrial Emissions Directive indirectly influence heater design by pushing for higher overall plant efficiency. Stakeholder decisions will center on balancing the upfront capital cost of advanced alloy heaters against the long-term operational savings from improved thermal performance.
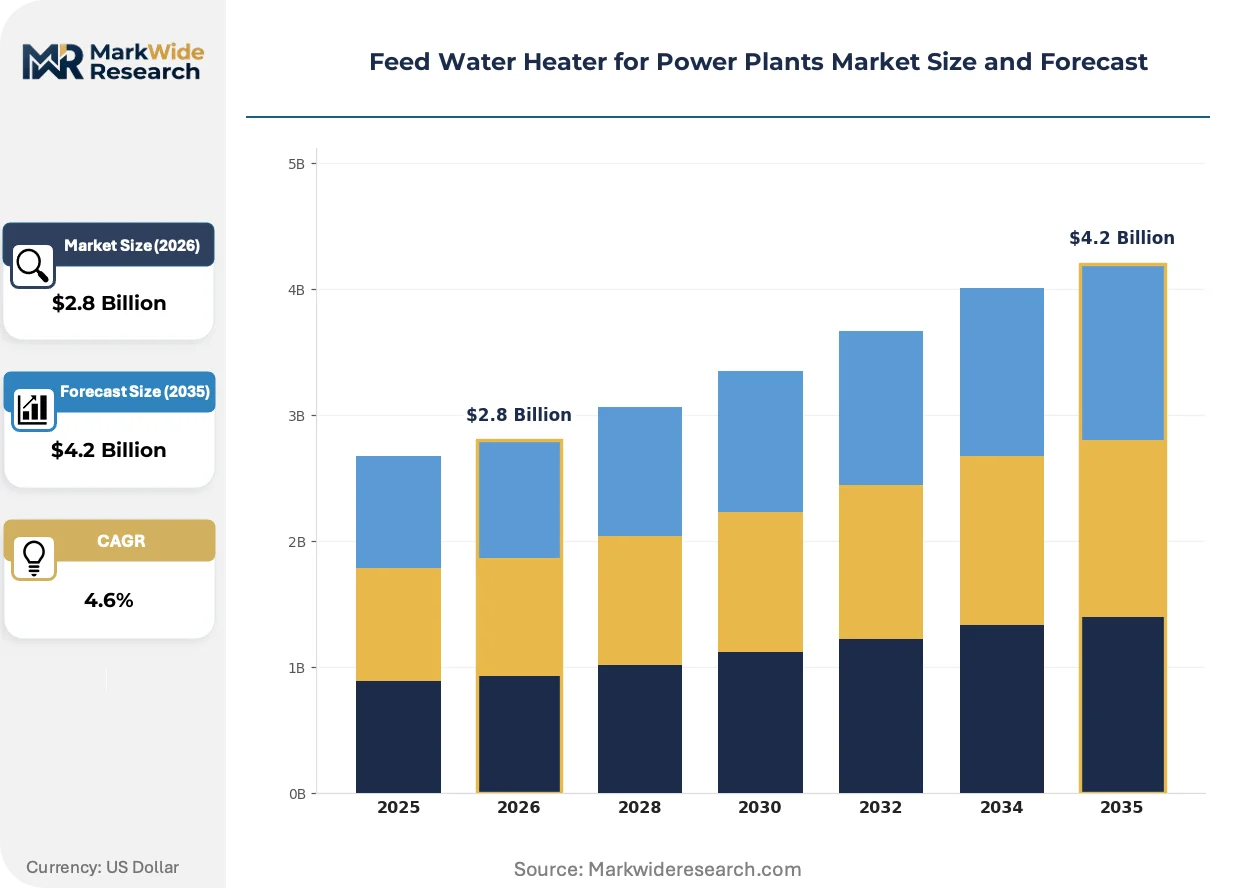
Market Dynamics
The global push for higher thermal cycle efficiency, driven by decarbonization policies like China's dual carbon goals and the EU's Industrial Emissions Directive, is the central force shaping the feed water heater market for power plants.
Growth Catalysts
- Policy Mandates:National energy policies, including India's focus on supercritical power plant construction and China's efficiency upgrade mandates, compel operators to invest in advanced feed water heater systems to meet performance targets.
- Nuclear Power Expansion:A renewed focus on nuclear energy for baseload power in countries like France and South Korea requires high-specification, reliable feed water heaters that adhere to stringent nuclear-grade safety and material codes.
- Advanced Materials:The commercial availability of high-strength, corrosion-resistant nickel and chromium alloys enables the design of heaters that can withstand the higher pressures and temperatures of ultra-supercritical power plants, improving overall efficiency.
Market Restraints
- High Capital Costs:The significant upfront investment required for heaters fabricated from advanced alloys, compared to conventional carbon steel, acts as a barrier for operators of older or smaller power plants with limited capital budgets.
- Competition from Renewables:The increasing cost-competitiveness of utility-scale solar and wind power, often paired with battery storage, reduces the economic viability and development pipeline for new large-scale thermal power plants in some regions.
- Retrofit Complexity:Integrating new, high-efficiency feed water heaters into existing power plants with space constraints and incompatible legacy piping systems presents significant engineering challenges and extended plant outage requirements.
Strategic Opportunities
- Digital Twin Integration:Developing digital twins for feed water heaters that use real-time sensor data for predictive maintenance offers a new service revenue stream and helps plant operators avoid costly unplanned failures.
- Small Modular Reactors (SMRs):The emerging SMR market presents an opportunity for standardized, factory-produced feed water heater modules that can be integrated into various reactor designs, creating a new volume-based demand segment. * Waste-to-Energy Plants: Custom-engineering heaters for the corrosive environments found in biomass and waste-to-energy facilities opens a niche application segment with specific material and design requirements distinct from conventional power generation.
Industry Challenges
- Specialized Skills Shortage:A lack of welders and technicians certified under ASME and equivalent codes to work on high-pressure tubing and exotic alloys creates project delays and increases labor costs for both manufacturing and on-site installation.
- Supply Chain Bottlenecks:Long lead times for critical components, particularly large-diameter seamless tubing and specialized forgings made from nickel alloys, can disrupt production schedules and delay power plant construction or maintenance projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Water Heater for Power Plants Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Feed Water Heater, Open Feed Water Heater, Thermosiphon Feed Water Heater, Electric Feed Water Heater Technology: Shell & Tube, Plate Heat Exchanger, Spiral Heat Exchanger, Finned Tube Heat Exchanger Application: Thermal Power Plants, Nuclear Power Facilities, Geothermal Power Stations, Biomass Power Generation End User: Independent Power Producers, Utility Companies, Engineering Procurement Contractors, Power Plant Operators |
| Companies Covered | BWX Technologies Inc, Westinghouse Electric Company LLC, KNM Group Berhad, Thermal Engineering International (USA) Inc, SPX Heat Transfer Inc, Babcock & Wilcox Enterprises, Mitsubishi Heavy Industries, Ltd., Shanghai Electric Group Co., Ltd, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Water Heater for Power Plants Market Strategic Shifts & Innovations
Innovation in the feed water heater market is driven by the parallel needs for improved thermodynamic efficiency to meet emissions targets and for faster, more predictable construction cycles. This is leading to significant changes in both product architecture and procurement models.
Pre-engineered, skid-mounted feed water heater systems combine the heat exchanger with integrated piping, valves, and control instrumentation. Engineering, procurement, and construction (EPC) firms are rapidly adopting these systems for new combined-cycle gas and nuclear power projects. This approach is modularizing the power block construction process, significantly compressing on-site installation timelines and reducing the need for specialized field labor.
The European Union's Industrial Emissions Directive (IED) establishes stringent energy efficiency benchmarks as part of its Best Available Techniques (BAT) reference documents. This regulation is forcing operators of existing large combustion plants to undertake major efficiency upgrades to remain compliant. The fossil fuel power generation segment, particularly in Germany and Poland, is most affected, stimulating a wave of retrofit projects focused on high-performance heat exchangers.
A notable behavioral shift involves power plant owners moving from one-off component purchases toward comprehensive, long-term service agreements for critical equipment. This model disrupts the traditional sales channels of independent fabricators, creating an advantage for OEMs who can bundle heater supply with ongoing monitoring, maintenance, and performance guarantees. This trend is especially prominent in the North American nuclear sector, where ensuring long-term asset reliability is the primary decision driver.
Feed Water Heater for Power Plants Market Segmentation
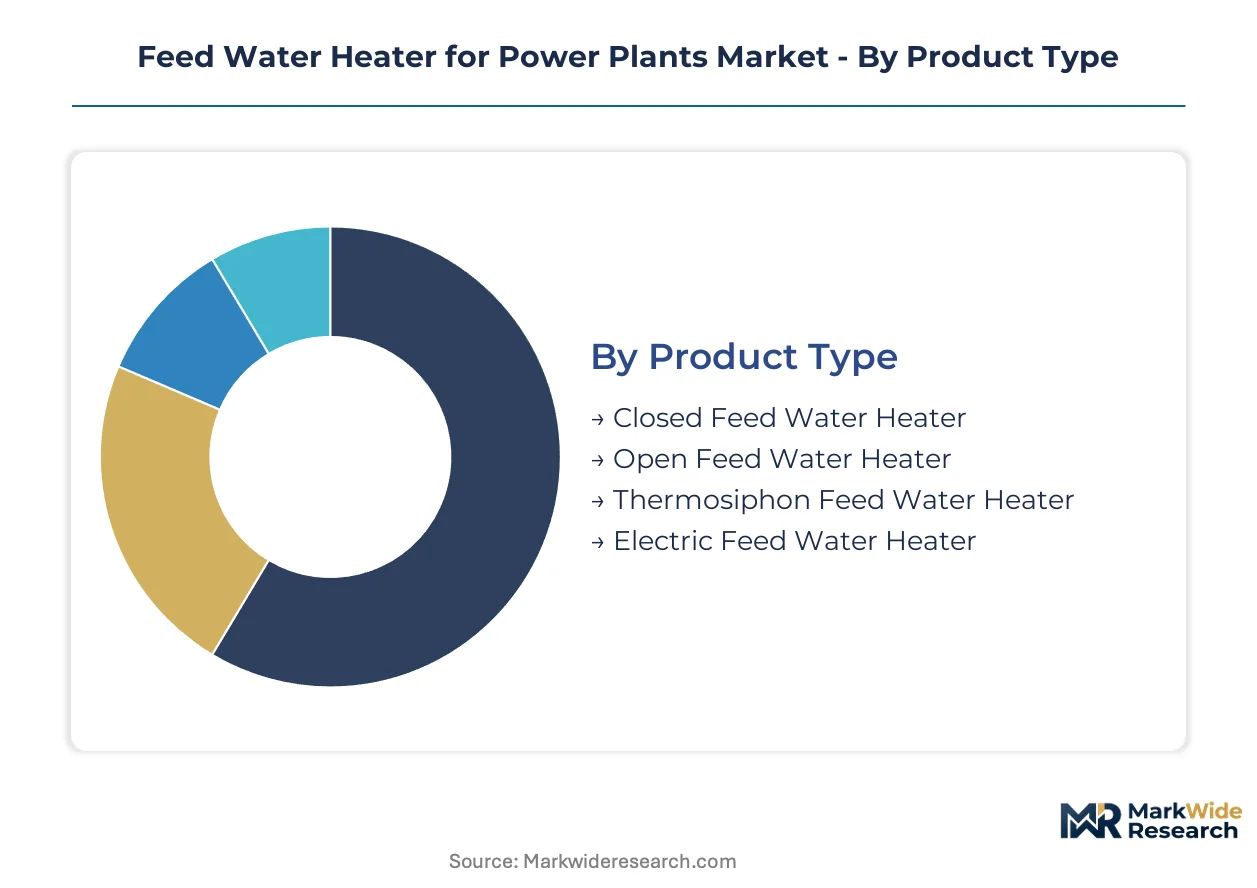
The feed water heater market for power plants segments across distinct product types, technologies, applications, and end-users, each reflecting specific operational demands and efficiency goals. Understanding these divisions reveals where advanced engineering solutions are most impactful and where procurement decisions are concentrated.
Product Type:
The design specification of feed water heaters dictates their suitability for various thermal cycle conditions.
- Closed Feed Water Heater:These heat exchangers isolate the feedwater from the heating steam, operating under high pressures and temperatures to significantly improve overall plant thermodynamic efficiency. Demand for closed systems concentrates in large-scale thermal and nuclear power facilities, where stringent performance and reliability are paramount.
- Open Feed Water Heater:Open systems directly mix exhaust steam with feedwater, serving as deaerators to remove non-condensable gases and prevent boiler corrosion. These are typically deployed in lower-pressure stages of the steam cycle, often in older thermal power plants undergoing efficiency upgrades.
- Thermosiphon Feed Water Heater:This type utilizes natural convection for heat transfer, eliminating the need for circulation pumps and reducing auxiliary power consumption. Thermosiphon heaters find niche applications in smaller industrial power generation units and waste heat recovery systems.
- Electric Feed Water Heater:Electric heaters utilize resistance heating elements to preheat feedwater, offering precise temperature control and quick response times, particularly useful for startup or auxiliary heating. Their demand is increasing in smaller modular reactors (SMRs) and facilities requiring flexible load operation.
Mature deployment sits with Closed Feed Water Heater. Newer deployment is concentrated in Electric Feed Water Heater.
Technology:
The internal configuration of feed water heaters determines their heat transfer efficiency and robustness for specific power plant environments.
- Shell & Tube:This traditional design features a bundle of tubes encased within a shell, allowing for robust operation under high pressures and temperatures with minimal maintenance. Shell & tube designs are extensively used in large-scale thermal power plants and nuclear power facilities due to their proven reliability.
- Plate Heat Exchanger:Comprising a series of corrugated plates, these units offer a compact footprint and high thermal efficiency due to their large heat transfer surface area. Plate heat exchangers are gaining traction in retrofit projects and combined-cycle gas turbine plants where space is at a premium.
- Spiral Heat Exchanger:Spiral exchangers consist of two concentric spiral channels for counter-current flow, suitable for fluids with high fouling potential or viscous media. These are often employed in biomass or waste-to-energy facilities where fluid characteristics present specific challenges.
- Finned Tube Heat Exchanger:Finned tubes enhance heat transfer by increasing the surface area on the gas side, commonly used in flue gas heat recovery applications. These are found in industrial boilers and some thermal power plants for improved exhaust heat utilization.
The market sees significant investment in Shell & Tube designs for durability. Plate Heat Exchanger technology is gaining share through its efficiency advantages.
Application:
Feed water heater applications span diverse power generation methods, each with unique operational and regulatory requirements.
- Thermal Power Plants:Coal, natural gas, and oil-fired plants represent the largest application segment, where feed water heaters are critical for improving steam cycle efficiency and reducing fuel consumption. Efficiency upgrade mandates from bodies like China's MEE and the EU's Industrial Emissions Directive drive demand here.
- Nuclear Power Facilities:Nuclear plants require high-specification, nuclear-grade feed water heaters that adhere to stringent safety and material codes due to the critical nature of their baseload power generation. A renewed focus on nuclear energy in countries like France and South Korea increases demand for these specialized components.
- Geothermal Power Stations:These facilities harness Earth's internal heat, often involving corrosive geothermal fluids that necessitate specialized material selection for feed water heaters. Geothermal applications represent a smaller but growing niche focused on renewable energy sources.
- Biomass Power Generation:Biomass plants convert organic matter into electricity, often producing corrosive combustion byproducts that require custom-engineered heaters. This segment aligns with decarbonization goals, driving demand for tailored solutions.
The largest volume of feed water heater deployment occurs in Thermal Power Plants. Nuclear Power Facilities are experiencing the steepest expansion trajectory.
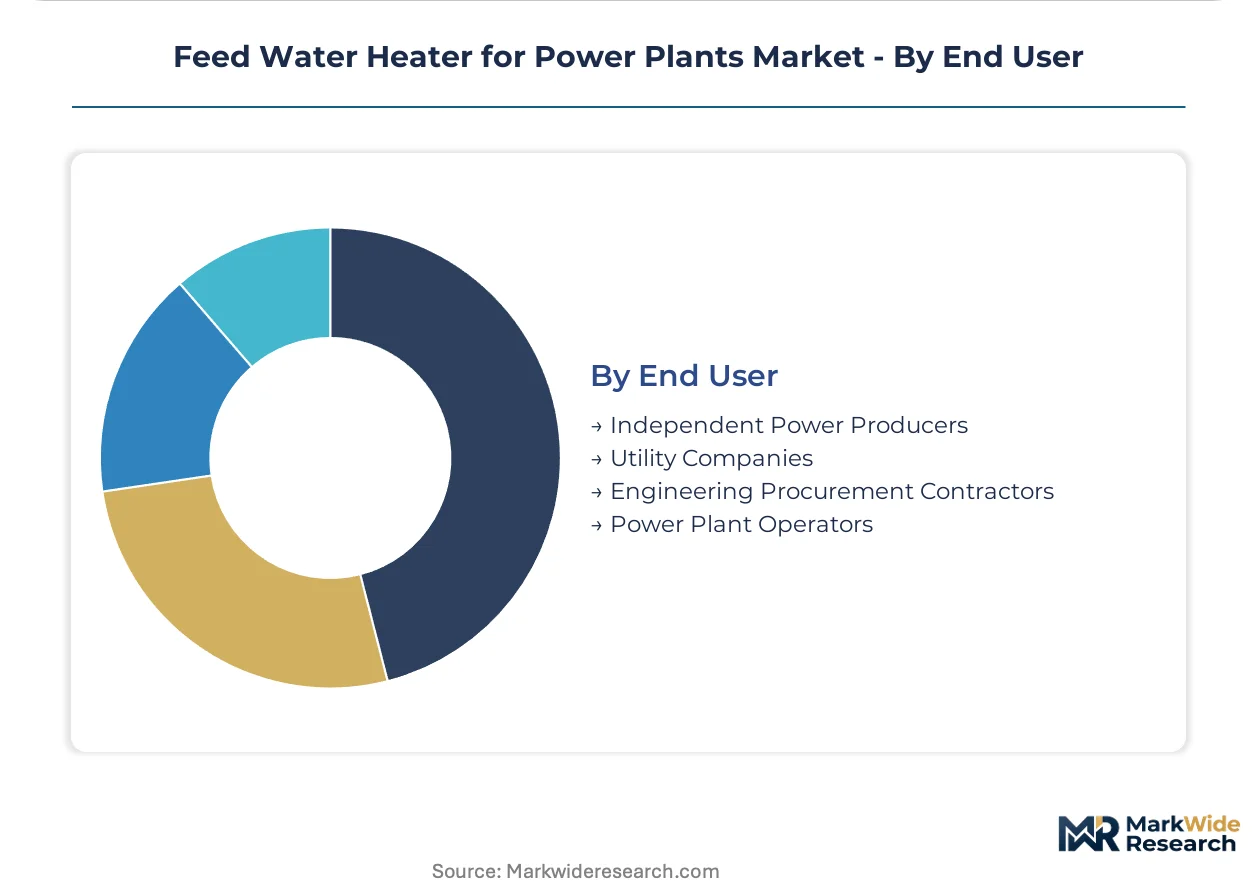
End User:
The type of organization operating power generation assets influences procurement strategies and long-term service agreements for feed water heaters.
- Independent Power Producers:These entities develop and operate power plants, selling electricity to utilities or directly to consumers, often prioritizing capital cost efficiency and project-specific solutions. Independent power producers seek performance guarantees and competitive pricing for their investments.
- Utility Companies:Large, often publicly owned or regulated entities, these companies own and operate extensive power generation fleets, focusing on long-term asset reliability and comprehensive service agreements. Utility companies in the North American nuclear sector drive demand for bundled heater supply with ongoing monitoring.
- Engineering Procurement Contractors:EPC firms manage the design, procurement, and construction of power plants, favoring modular, pre-engineered feed water heater systems for faster installation and standardized performance. EPCs are rapidly adopting these systems for new combined-cycle gas and nuclear power projects.
- Power Plant Operators:This segment includes the personnel directly managing and maintaining power generation facilities, making decisions about replacement parts, upgrades, and maintenance contracts. Operators prioritize ease of integration and predictive maintenance capabilities for critical components.
Procurement decisions for feed water heaters are heavily influenced by Utility Companies. Engineering Procurement Contractors are increasingly shaping demand for modular solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global production of feed water heaters is concentrating in industrial hubs, while consumption patterns reflect widespread demand from diverse power generation projects. Rapid industrialization and a renewed focus on energy efficiency are driving significant regional variations in market growth. Policy mandates for decarbonization and nuclear power expansion shape procurement decisions across major economies.
China
China's ambitious dual carbon goals are compelling power plant operators to invest in advanced feed water heater systems for thermal cycle efficiency upgrades. The Ministry of Ecology and Environment (MEE) mandates stringent energy efficiency benchmarks for large combustion plants. Industrial clusters in the Yangtze River Delta are seeing significant deployment of high-performance heat exchangers for new and retrofit projects.
India
Demand for advanced feed water heaters in India stems from its supercritical power plant construction initiatives and expanding industrial base. The Central Electricity Authority (CEA) issues guidelines for thermal power plant efficiency, influencing equipment specifications. Power generation projects across states like Maharashtra and Gujarat require high-efficiency components to meet national energy targets.
United States
The United States nuclear sector drives demand for high-specification, reliable feed water heaters, prioritizing long-term asset reliability. The U.S. Environmental Protection Agency (EPA) regulations indirectly influence heater design by pushing for higher overall plant efficiency. Nuclear facilities along the East Coast and in the Southeast are key centers for specialized component procurement and maintenance agreements.
Germany
Germany's energy transition policies, particularly the EU's Industrial Emissions Directive, necessitate efficiency upgrades in existing thermal power plants. These regulations compel operators to invest in high-performance heat exchangers to remain compliant. Industrial regions like North Rhine-Westphalia are undertaking significant retrofit projects for fossil fuel power generation assets.
France
France's renewed commitment to nuclear energy for baseload power requires high-specification, nuclear-grade feed water heaters. The country's national energy policies support the development and maintenance of its extensive nuclear fleet. Facilities in regions such as Auvergne-Rhône-Alpes are key centers for the procurement of specialized components adhering to stringent safety codes.
Feed Water Heater for Power Plants Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure for feed water heaters. The market sees a mix of large-scale engineering firms and niche fabricators. Strategic archetypes include integrated solution providers, specialized component manufacturers, and regional custom engineering houses. Competitive moves often involve strategic partnerships for complex projects and ongoing portfolio diversification to capture new application segments.
Mitsubishi Heavy Industries, Ltd. represents a major player in high-efficiency designs for large-scale thermal plants, particularly across Asian markets. General Electric Company leverages its extensive portfolio in turbine and generator integration to offer bundled solutions for power generation projects globally. Babcock & Wilcox Enterprises occupies a position as a specialist in custom-engineered solutions for both new build and retrofit projects, serving diverse power plant requirements.
| Leading Market Players |
|---|
| BWX Technologies Inc |
| Westinghouse Electric Company LLC |
| KNM Group Berhad |
| Thermal Engineering International (USA) Inc |
| SPX Heat Transfer Inc |
| Babcock & Wilcox Enterprises |
| Mitsubishi Heavy Industries, Ltd. |
| Shanghai Electric Group Co., Ltd |
| General Electric Company |
| Others |
Cost & Logistics Intelligence
China's efficiency upgrade mandates compel power plant operators to invest in advanced feed water heaters. This demand drives suppliers to focus on high-performance alloys, influencing overall market pricing and material sourcing strategies.
Pricing Analysis
Cost-down pressure on conventional carbon steel heaters intensifies due to competition from lower-cost regional fabricators. The dominant pricing model is project-based, often involving long-term contracts for large-scale thermal and nuclear facilities. Price differentiation stems from certification level, such as adherence to ASME codes, and the customization level required for retrofit projects. Independent Power Producers often exhibit higher price sensitivity, while Utility Companies prioritize long-term asset reliability and performance over immediate upfront cost.
Supply Chain Analysis
Refurbishment programs for existing feed water heaters extend asset lifecycles, mitigating some demand for new units in mature markets. Specialized component manufacturing concentrates in industrial hubs across China, South Korea, and Germany. Production relies heavily on critical raw materials like nickel and chromium alloys, in addition to large-diameter seamless tubing. Single-source vulnerability for exotic alloy forgings presents a significant structural supply chain risk. Distribution runs through direct sales channels for Original Equipment Manufacturers and specialized engineering firms for custom-engineered solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
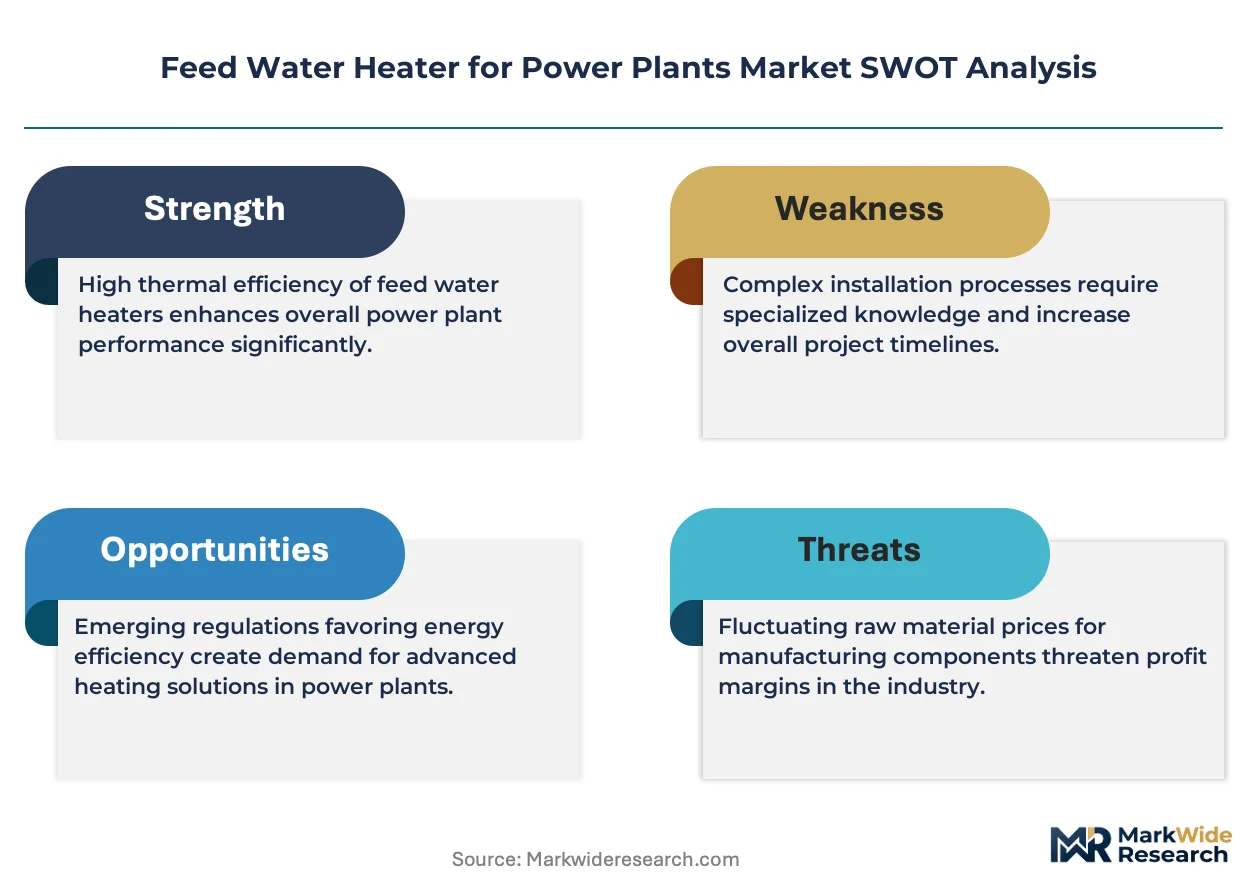
The feed water heater market presents a supply-constrained story, primarily due to the specialized skills shortage for high-pressure alloy welding. This bottleneck supports premium pricing for certified fabrication and installation services.
For Market Incumbents: Anchor existing market share by deepening backward integration into specialized alloy tubing production. Invest in advanced manufacturing automation to mitigate the specialized skills shortage for complex welding. Expand long-term service agreements, particularly in the North American nuclear sector, to defend against new entrants offering lower upfront costs. Leverage bundled solutions, combining heater supply with turbine and generator integration, to reinforce competitive positioning.
For New Entrants and Emerging Players: Launch via modular, pre-engineered feed water heater systems, targeting Engineering, Procurement, and Construction firms in rapidly industrializing economies like India. Focus on the emerging Small Modular Reactor (SMR) market with standardized, factory-produced modules. Target waste-to-energy plants, which require custom-engineered heaters for corrosive operating environments. Offer comprehensive performance guarantees and demonstrably faster installation timelines as a key market differentiator.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking niche technology or specialized manufacturing capabilities over the next 5-10 years. Long-term viability is strong, driven by global decarbonization policies and sustained nuclear energy expansion. Target mid-sized fabricators with proven ASME-certified welding expertise and proprietary alloy processing capabilities. The signal to watch is an increase in final investment decisions for Small Modular Reactor projects globally.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses long lead times for critical components, enhancing supply reliability for power plant construction. |
| Digital Twin Integration | Creates new service revenue streams and improves predictive maintenance capabilities for plant operators. |
| Advanced Alloy R&D | Enables design of heaters for higher pressures and temperatures, improving thermal efficiency for ultra-supercritical plants. |
| Strategic Partnerships | Secures access to specialized manufacturing expertise and expands market reach for complex, large-scale projects. |
| Modular Product Development | Accelerates installation timelines and reduces on-site labor requirements for new combined-cycle gas and nuclear projects. |
Research Approach
Independent corroboration across industry association reports, regulatory filings, and academic literature underwrites the qualitative findings. This approach combined primary interviews with power plant operators, EPC contractors, and material suppliers. Secondary validation drew from technical journals, patent databases, and trade publications. Bottom-up and top-down triangulation ensured data integrity across all segments.
The forecast window was anchored to historical reference periods, establishing baseline demand and supply dynamics. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user. Compound Annual Growth Rates were derived through a regression analysis of historical market trends and projected policy impacts. Key forecast inputs included projected global power plant construction rates and national efficiency upgrade mandates.
Policy shifts, raw material price volatility, and technological breakthroughs are the dominant revision risks for this analysis. Forecasts reflect assumptions regarding regulatory enforcement and global energy transition trajectories. Practitioners should monitor global energy investment trends and specialized alloy manufacturing capacity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Industrial Biomass Boiler Market
Boilers
Europe Power Plant Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Oil-Fired Boiler Market
Boilers
Global Boiler Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Power Plant Boiler Market
Boilers
Watertube Boilers Market
Boilers
Electric Boiler Market
Boilers
Germany Combined Heat and Power Market
Boilers
Netherlands Combined Heat and Power Market
Boilers
Field Erected Boiler Market
Boilers
Gas Condensing Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Fossil Fuel Fired Water Heaters Market