
 US Home and Garden Fungicides Market | 2026-2036
US Home and Garden Fungicides Market Size, Share, and Industry Trends Forecast 2026-2036
US Home and Garden Fungicides Market Intelligence
The rising popularity of home vegetable cultivation is recalibrating the end-user mix away from purely ornamental landscaping. Bayer AG leverages its chemical research portfolio for systemic and contact solutions for a wide range of diseases. Certis USA specializes in biological fungicides for the growing organic gardening segment. The Scotts Company sustains a dominant retail presence through its brand recognition in US garden centers.
Home and garden fungicides are chemical or biological agents formulated to control fungal diseases on ornamental plants, lawns, and produce grown in residential settings. These products specifically target common pathogens like powdery mildew, rust, and black spot. Biological fungicides represent the fastest-growing product type, driven by consumer preference for safer alternatives. Liquid formulations, particularly ready-to-use sprays, command a significant share due to their convenience for residential end users.
The Environmental Protection Agency (EPA) governs the registration and labeling of all fungicides sold in the United States under the Federal Insecticide, Fungicide, and Rodenticide Act (FIFRA). State-level bodies, such as California's Department of Pesticide Regulation, often impose stricter requirements on product composition and use. Formulators must navigate the evolving consumer demand for efficacy balanced against the regulatory push for lower-risk and biological ingredients.
Market Dynamics
The central dynamic in the US home and garden fungicide market is the tension between consumer demand for high-efficacy, fast-acting products and a concurrent regulatory and cultural shift towards safer, biologically-derived alternatives for use on edible and ornamental plants.
Growth Catalysts
- Home Vegetable Cultivation:An expanding interest in growing produce at home elevates the need for fungicides approved for edible plants, directly stimulating demand for products, particularly organic formulations, that can be used safely up to harvest.
- Favorable EPA Policies:The Environmental Protection Agency's framework for registering biopesticides and reduced-risk fungicides creates a faster path to market for these products, encouraging manufacturers to invest in developing safer alternatives to conventional chemical agents.
- Horticultural Activity in Key States:Year-round gardening and extensive landscaping in states like Florida and California, driven by climate and population density, create concentrated pockets of high, consistent demand for both preventative and curative fungal treatments.
Market Restraints
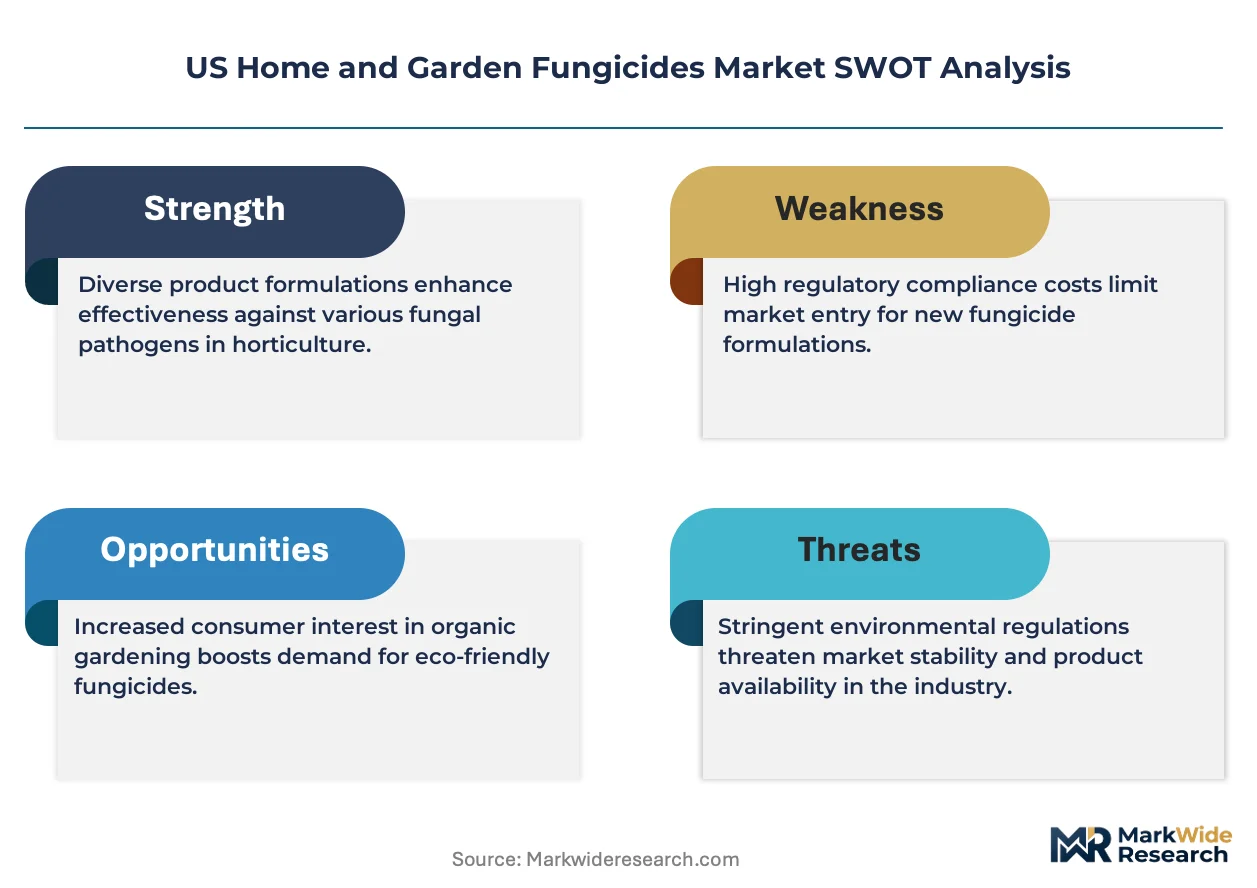
- Higher Cost of Biologicals:The production and formulation of many biological fungicides involve higher input costs and more complex quality control for live microbes compared to synthetic chemicals, often resulting in a premium price point for the end user.
- Performance Spectrum Limitations:Some biological fungicides offer a narrower spectrum of disease control or require more frequent application compared to their systemic chemical counterparts, posing a barrier for users seeking simple, broad-spectrum solutions.
- Stringent State-Level Regulations:Regulatory bodies like California's Department of Pesticide Regulation impose requirements that exceed federal EPA standards, increasing compliance costs and potentially delaying or preventing product entry into critical regional markets.
Strategic Opportunities
- Specialized Lawn Care Formulations:There is an opportunity to develop and market advanced biological fungicides specifically targeting persistent and difficult-to-control turfgrass diseases like dollar spot and brown patch, appealing to homeowners seeking eco-friendly lawn solutions.
- Direct-to-Consumer Subscription Models:The emergence of DTC channels allows for the creation of subscription-based kits that provide homeowners with a seasonally-timed regimen of lawn and garden care products, including preventative fungicides.
- Combination Nutrient and Fungicide Products:Formulating products that combine bio-fungicides with plant nutrients and biostimulants offers a value-added, all-in-one solution that enhances plant health and resilience, appealing to convenience-oriented gardeners.
Industry Challenges
- Consumer Education Gap:A significant challenge is educating residential users on the proper application timing and performance expectations of biological fungicides, which often work preventatively rather than providing the rapid curative effect of some chemicals.
- Cold Chain Distribution:Certain microbial-based fungicides require specific temperature controls throughout the supply chain to maintain viability, complicating logistics for distributors and retailers and increasing the risk of product degradation before sale.
- Environmental Performance Variability:The efficacy of many biological agents is highly dependent on environmental conditions such as temperature and humidity, leading to inconsistent results that can frustrate home gardeners and erode brand trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home and Garden Fungicides Market |
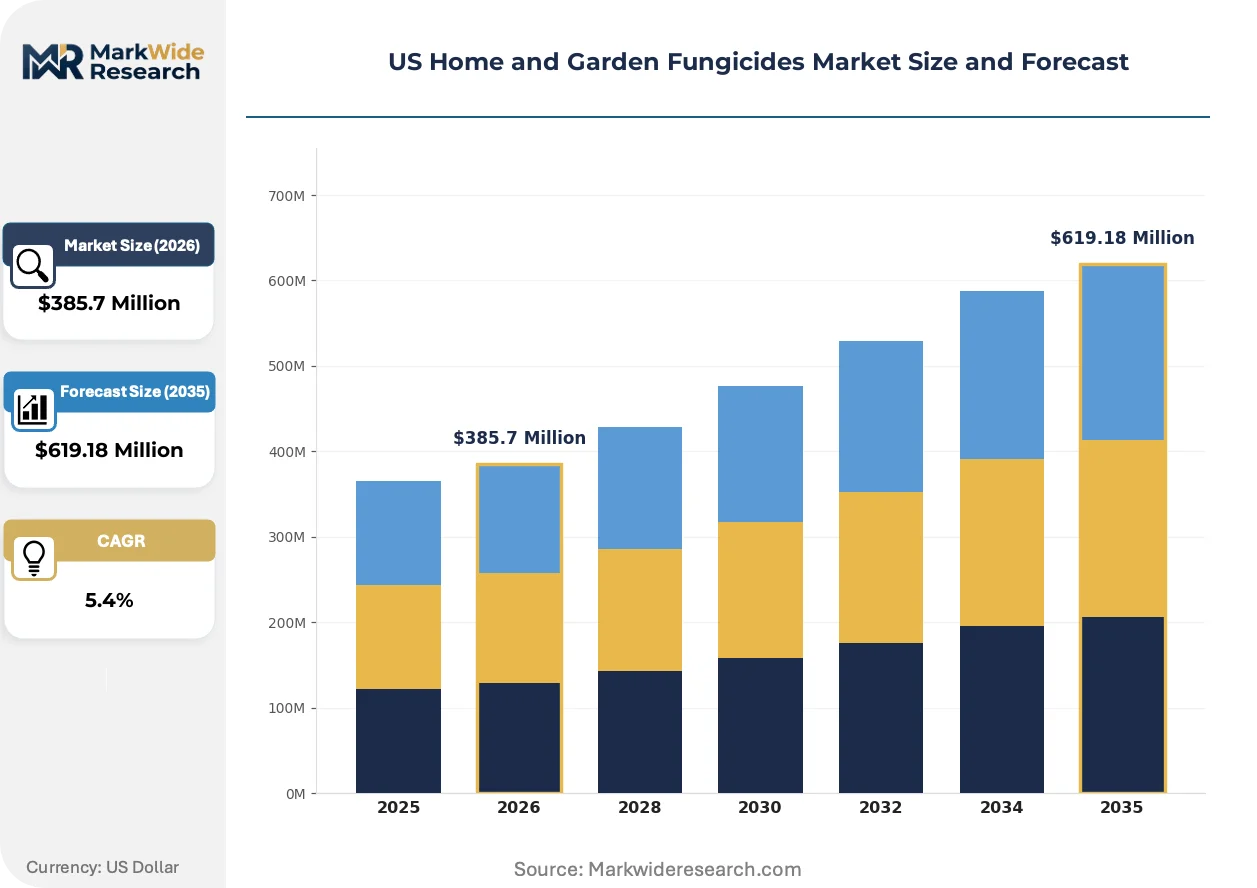
| Market Size in 2026 | $385.7 Million |
| Market Size in 2035 | $619.18 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systemic Fungicides, Contact Fungicides, Biological Fungicides, Specialty Fungicides Formulation: Granular, Liquid, Powder, Emulsifiable Concentrate Application Method: Foliar Spray, Soil Drench, Seed Treatment, Bait Application End User: Residential, Commercial, Agricultural, Landscaping |
| Companies Covered | Bayer AG, Syngenta, BASF, Corteva, Certis USA, Central Garden & Pet Company, The Scotts Company, Spectrum Brands, Nufarm US, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home and Garden Fungicides Market Strategic Shifts & Innovations
A fundamental shift toward precision and sustainability is reshaping product development in the US home and garden fungicide market. This evolution prioritizes user-friendly formulations and environmentally benign active ingredients, moving the industry beyond broad-spectrum chemical applications toward more targeted solutions.
Technology and Product Evolution
Smart-spray technologies and handheld diagnostic tools are emerging as key innovations. These systems often use smartphone apps to help users identify specific plant diseases through photo analysis. Adoption is currently highest among tech-forward gardeners and younger homeowners. This technology is automating the selection and application of the correct fungicide at the proper concentration, reducing chemical waste and improving treatment outcomes.
Regulatory and Policy Shifts
The Environmental Protection Agency's implementation of the Federal Insecticide, Fungicide, and Rodenticide Act (FIFRA) continues to evolve, favoring products with reduced-risk profiles. This regulatory preference provides an expedited review process for biopesticides and other safer chemical alternatives. The organic gardening product segment is most affected, as formulators increasingly prioritize active ingredients that qualify for these favorable EPA designations to meet growing consumer demand.
Demand-Side and Behavioral Shifts
Consumer purchasing patterns are moving from ad-hoc, large-container purchases at retail to curated, subscription-based garden care kits. This model, primarily driven by direct-to-consumer (DTC) brands, disrupts the dominance of traditional big-box stores and garden centers. This shift is most visible among homeowners in suburban US markets who value the convenience and personalization of pre-scheduled deliveries tailored to their regional climate and garden type.
US Home and Garden Fungicides Market Segmentation
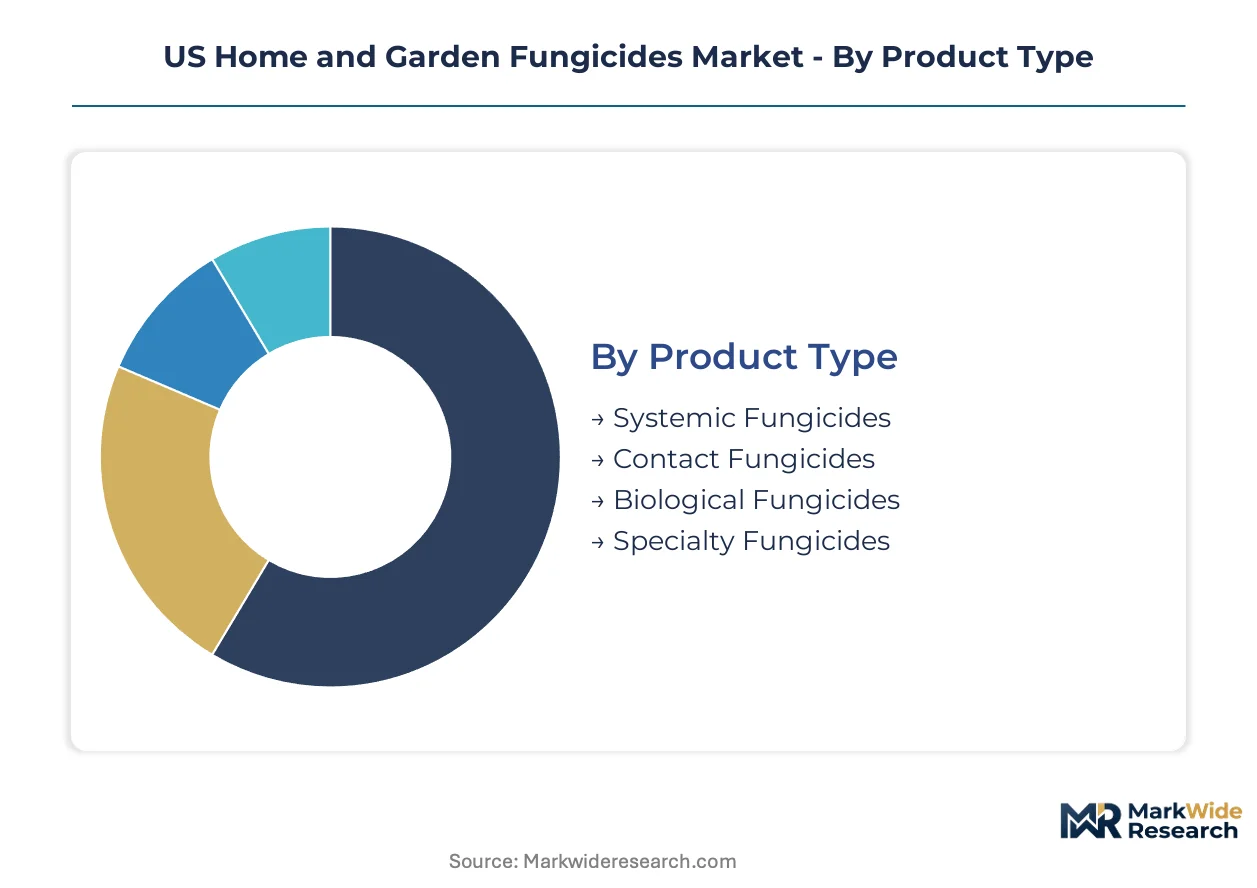
Understanding the segmentation of the US home and garden fungicides market reveals how different product attributes and end-user demands shape development priorities. This granular view helps manufacturers align their offerings with specific residential gardening practices and regulatory requirements. Product differentiation across these segments addresses varying levels of efficacy, safety, and application convenience.
Product Type:
The capital intensity of developing and bringing new fungicide products to market significantly varies across types, with biological solutions often requiring substantial investment in research and quality control for live cultures.
- Biological Fungicides:These products utilize living microorganisms or natural compounds to control fungal pathogens, appealing to the organic gardening segment. Consumer preference for safer alternatives drives demand for these environmentally benign solutions.
- Systemic Fungicides:These chemical agents are absorbed by the plant and translocated throughout its tissues, providing internal protection against disease. Bayer AG leverages its chemical research portfolio to develop these advanced solutions for a wide range of plant diseases.
- Contact Fungicides:These formulations remain on the plant surface, forming a protective barrier against fungal spores. They require thorough coverage for effective disease prevention.
- Specialty Fungicides:This category encompasses niche products designed for specific diseases or plant types, often addressing unique horticultural challenges.
Biological Fungicides absorbs the bulk of installed capacity; Systemic Fungicides is expanding most quickly.
Formulation:
User convenience and application method heavily influence the preferred formulation types for home and garden fungicides, impacting their market accessibility and residential adoption rates.
- Liquid:These ready-to-use or concentrated solutions are popular due to their ease of mixing and application via sprayers. Liquid formulations command a significant market share for residential end users.
- Emulsifiable Concentrate:This formulation consists of active ingredients dissolved in an oil solvent with an emulsifier, forming a stable emulsion when diluted with water. It offers efficient coverage for foliar applications.
- Granular:These solid, particulate formulations are typically applied to the soil or lawn, releasing the active ingredient over time. They are often used for preventative treatments in turfgrass.
- Powder:Dry powder formulations require mixing with water before application or can be dusted directly onto plants. They offer a concentrated form for transport and storage.
Liquid formulations hold the largest share of consumer purchases; Emulsifiable Concentrate forms are gaining traction among experienced gardeners.
Application Method:
The chosen application method for fungicides is critical for targeting specific diseases and ensuring optimal product efficacy on various plant types within residential settings.
- Foliar Spray:This method involves applying fungicides directly to plant leaves and stems, providing immediate protection against surface-dwelling fungi. Home gardeners widely use foliar sprays for ornamental plants and vegetables.
- Soil Drench:Fungicide solutions are poured directly onto the soil around the plant base, allowing the roots to absorb the active ingredients for systemic protection. This method targets root-borne pathogens effectively.
- Seed Treatment:Fungicides are applied directly to seeds before planting, protecting young seedlings from soil-borne diseases during germination and early growth. This preventative approach minimizes early crop loss.
- Bait Application:This less common method involves incorporating fungicides into a bait matrix to target specific fungal pests, typically for specialized situations.
Foliar Spray applications dominate residential use; Soil Drench methods show consistent utility for systemic treatments.
End User:
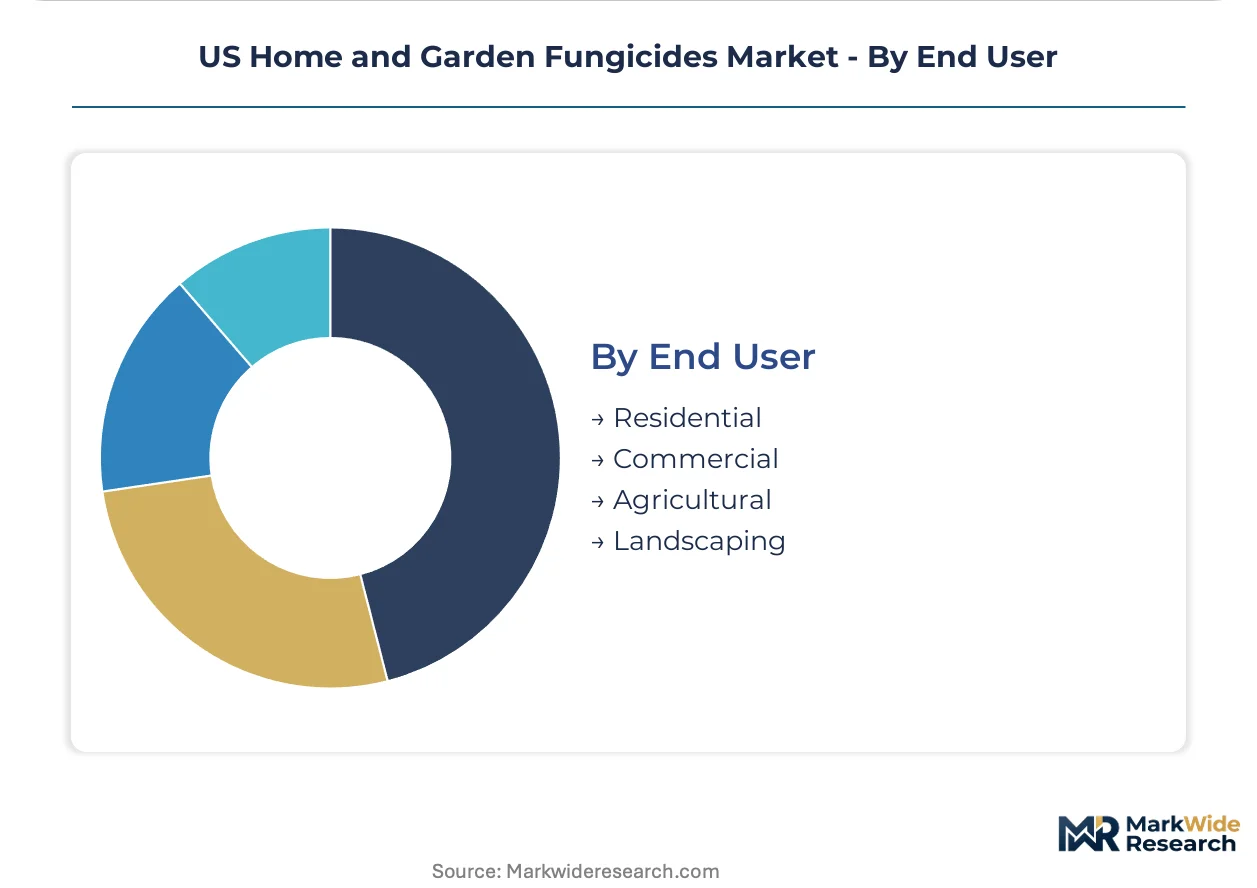
The diverse needs of different end-user segments drive distinct product development and marketing strategies within the US home and garden fungicide market, from large-scale landscaping to individual home gardening.
- Residential:This segment includes individual homeowners and hobby gardeners cultivating plants, lawns, and vegetables in their personal spaces. Rising interest in home vegetable cultivation elevates demand for organic and safe-to-use formulations.
- Landscaping:Professional landscapers and garden maintenance companies constitute this segment, requiring effective solutions for large-scale ornamental plantings and turfgrass. Extensive horticultural activity in states like Florida and California creates concentrated demand.
- Commercial:This category includes nurseries, greenhouses, and other commercial entities involved in plant production and sales. They often require professional-grade products for disease management.
- Agricultural:While distinct from home and garden, this segment includes small-scale agricultural operations and community gardens that may use products approved for residential food crops.
Residential users represent the largest volume of consumers; Landscaping services drive significant bulk product procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Horticultural activity zones, particularly in states with extensive landscaping, drive significant concentration in the US home and garden fungicide market. These regions exhibit robust demand for both preventative and curative fungal treatments. Consumer preference for organic gardening solutions also influences product availability within these areas.
California
California's extensive landscaping and vibrant home vegetable cultivation create substantial demand for fungicides. The state's Department of Pesticide Regulation (DPR) imposes rigorous requirements, influencing product formulations. The Central Valley and coastal regions see high demand for biological and reduced-risk fungicides for diverse plant types.
Florida
Florida's year-round gardening climate and high humidity foster consistent demand for fungal disease control. The EPA's expedited review process for biopesticides supports new product introductions tailored for the state's conditions. Southern Florida's dense residential areas show consistent demand for lawn and ornamental plant treatments.
Texas
Texas presents diverse climates and large residential areas, driving increasing interest in home gardening across its metropolitan centers. USDA guidelines for organic produce influence product selection for edible plants across the state. Major metropolitan areas like Houston and Dallas-Fort Worth generate substantial sales for convenient liquid formulations.
Northeast Corridor
The Northeast Corridor, characterized by high population density and significant suburban landscaping investments, represents a concentrated demand pocket. State environmental protection agencies often promote integrated pest management strategies, encouraging targeted solutions. Wealthy suburban counties from New Jersey to Massachusetts demonstrate strong demand for specialized turfgrass fungicides.
US Home and Garden Fungicides Market Key Industry Players
Top-tier vendors anchor the market for systemic and contact solutions, while specialized firms and regional players focus on niche biological offerings. The competitive landscape is tiered, with established chemical companies alongside innovative biological solution providers and dominant retail brands. Strategic archetypes include chemical research powerhouses, biological specialists, and consumer brand leaders. Dominant competitive moves include portfolio diversification into biologicals and strategic partnerships for distribution reach.
Specialists in different product types and distribution channels include Bayer AG, Certis USA, and The Scotts Company. Bayer AG, a German-based chemical giant, exemplifies a chemical research powerhouse, leveraging its extensive portfolio for systemic and contact solutions. Certis USA, an American firm, represents a biological specialist, focusing on environmentally benign options for organic gardening. The Scotts Company, another US-based entity, anchors the retail brand leader archetype through its strong presence in garden centers.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta |
| BASF |
| Corteva |
| Certis USA |
| Central Garden & Pet Company |
| The Scotts Company |
| Spectrum Brands |
| Nufarm US |
| Others |
Cost & Logistics Intelligence
Production costs for biological fungicides, driven by complex quality control for live microbial cultures, significantly influence downstream pricing. This upstream cost structure dictates the premium price points for residential organic gardening solutions.
Pricing Analysis
Premium pricing for short lead times on specialized biological fungicides reflects their higher input costs and specific handling requirements. Tiered pricing stratifies across premium biologicals, standard chemical solutions, and economy contact fungicides. Certification level, particularly organic approval, and strong brand recognition from companies like The Scotts Company, drive price differentiation. Pricing softness reflects the regulatory push for lower-risk ingredients, increasing competition within the biological segment. Residential users are generally price-sensitive for conventional products, but less so for organic-certified biologicals used on edible plants.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like the US, Germany, and Switzerland influences production capacity for active ingredients. The supply chain relies on specialized microbial cultures and inert carrier materials as critical raw material dependencies. Cold chain distribution for certain biological agents poses a significant logistics chokepoint, increasing supply chain risk. Distribution runs through large national retail chains, specialized local garden centers, and emerging direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US home and garden fungicides market is a consolidation play. Stringent state-level regulations and high R&D costs for new biological formulations force smaller, undifferentiated players out.
For Market Incumbents: Cement market leadership through continuous innovation in reduced-risk formulations. Diversify portfolios with biological solutions to counter the threat of evolving EPA guidelines favoring biopesticides. Invest in R&D for advanced application technologies, leveraging existing distribution networks. Control channel access by forming strategic partnerships with major garden centers.
For New Entrants and Emerging Players: Enter via niche biological formulations targeting specific turfgrass diseases like dollar spot. The direct-to-consumer segment, particularly subscription models for suburban homeowners, offers the most penetrable market. Focus go-to-market on digital channels and educational content for proper biological fungicide application. Emphasize product safety and environmental benefits for organic gardeners.
For Investors and Strategic Acquirers: Accelerated EPA biopesticide registrations is the leading indicator that regulatory tailwinds favor biological solutions long-term. Acquisition targets include specialized biological fungicide developers with strong intellectual property in microbial strains. Monitor consumer adoption rates of smart-spray technologies as a signal for future market shifts. Focus on companies with established cold-chain logistics capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Biologicals | Expands market reach to meet consumer demand for organic and reduced-risk solutions. |
| Direct-to-Consumer Channel Development | Establishes direct relationships with residential users, bypassing traditional retail intermediaries. |
| Advanced Formulation R&D | Improves product efficacy and user convenience, addressing limitations of current biologicals. |
| Strategic Regulatory Compliance Investment | Ensures product eligibility for favorable EPA designations and access to critical state markets. |
| Cold Chain Logistics Optimization | Maintains viability of temperature-sensitive biological products throughout the supply chain. |
Research Approach
EPA FIFRA guidelines, state Department of Pesticide Regulation reports, and horticultural association publications formed the secondary backbone. Primary interviews with R&D directors, product managers, garden center owners, and residential landscapers provided crucial insights. This approach combined bottom-up market intelligence with top-down industry trends for comprehensive analysis.
Historical trendline analysis established foundational growth patterns across the modeling period. The analytical framework segmented the market by product type, formulation, application method, end user, and regional horticultural activity. Compound annual growth rates were derived from projected demand shifts and regulatory impacts. Key forecast inputs included consumer organic gardening interest and biopesticide registration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid climate shifts or unforeseen regulatory changes. The analysis reflects assumptions on consumer adoption of biologicals and EPA policy stability. Material deviation in biopesticide approval rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
Neem Extract Market
Agricultural Chemicals
Global Agricultural Fumigants Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
South America Plant Growth Regulators Market