
 Artificial Humus Market | 2026-2036
Artificial Humus Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Humus Market Outlook
The EU Green Deal's soil health and carbon sequestration targets is repositioning artificial humus from niche organic input to mandated soil amendment across European commercial agriculture. Novihum Technologies GmbH leverages its German manufacturing base and patented lignite-humification process to dominate technical-grade supply for precision farming systems. The Fertrell Company anchors North American distribution through direct-sales relationships with certified organic operations. Humintech competes on concentrated liquid formulations that reduce freight costs for remote horticultural buyers.
Artificial humus comprises chemically stabilized organic matter derived from lignitic brown coal or composted biomass, engineered to contain 60-80% humic and fulvic acids with cation exchange capacity exceeding 300 meq per 100 grams, functioning primarily to restore soil structure, nutrient retention, and microbial activity in degraded agricultural land. Granular formulations lead volume shipments due to compatibility with existing spreader equipment and slower release profiles favored in broadacre grain operations. Liquid concentrates represent the fastest-expanding product category as drip-irrigation and fertigation systems penetrate protected-cropping facilities in Spain, the Netherlands, and California. The agriculture application segment occupies the dominant margin pool, though erosion-control contracts for post-mining land rehabilitation in Australia and Poland are extending addressable demand.
The European Commission's F-Gas Regulation and REACH compliance requirements for soil amendment imports are tightening product documentation and carbon-footprint disclosure across the value chain. Germany's Federal Office for Consumer Protection and Food Safety (BVL) enforces humic substance purity standards that exclude non-lignite synthetic alternatives from organic certification eligibility. The USDA's National Organic Program maintains parallel but divergent input lists that fragment market access for European producers. Stakeholders must monitor divergence between EU and North American regulatory frameworks to anticipate reformulation costs and certification pathway investments.
Market Dynamics
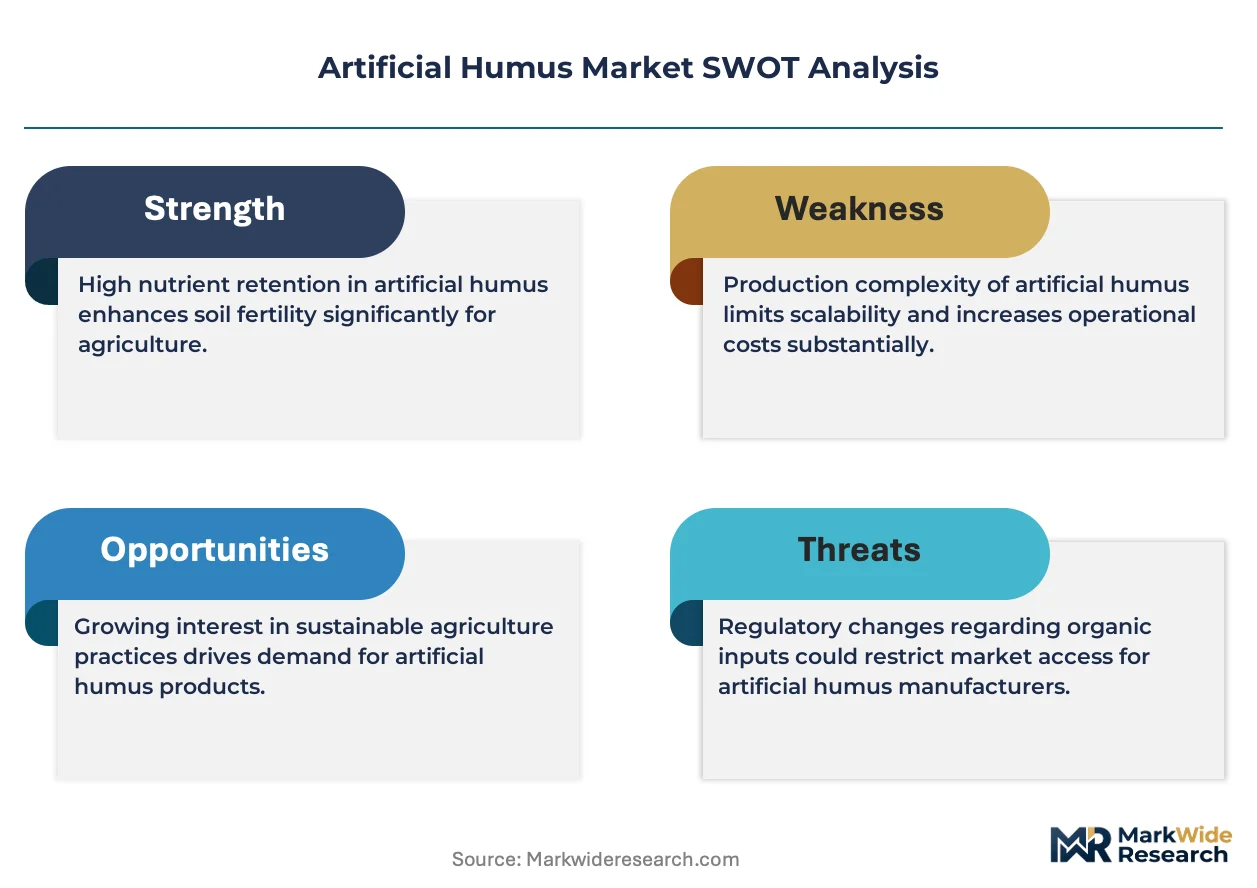
The EU Green Deal's soil health mandates are compressing adoption timelines for artificial humus across European commercial agriculture, forcing input suppliers to reconfigure certification pathways and manufacturing footprints ahead of binding 2030 targets.
Growth Catalysts
- Peat substitution mandates:Germany's Federal Office for Consumer Protection and Food Safety (BVL) excludes non-lignite synthetic alternatives from organic certification eligibility, creating protected demand channels for lignite-derived humus in certified operations.
- REACH compliance documentation:The European Commission's F-Gas Regulation and carbon-footprint disclosure requirements for soil amendment imports are standardizing product traceability across member state borders.
- Fertigation infrastructure:Drip-irrigation system penetration in protected-cropping facilities across Spain and the Netherlands is pulling liquid concentrate formulations into high-value horticultural supply chains.
Market Restraints
- Lignite feedstock concentration:Production gravity centers on Central European brown coal deposits, exposing supply chains to energy transition policy volatility and mining license uncertainties in Germany and Poland.
- USDA-NOP divergence:The USDA's National Organic Program maintains input lists that diverge from EU REACH standards, fragmenting market access and forcing dual certification investments for cross-Atlantic suppliers.
- Composted biomass substitutes:Municipal waste stream processing advances in the Netherlands and Denmark are yielding lower-cost organic matter alternatives that compete on price in non-certified applications.
Strategic Opportunities
- Post-mining rehabilitation:Erosion-control contracts in Australia and Poland are extending addressable demand beyond agriculture into land remediation services with multi-year contract horizons.
- Liquid formulation freight optimization:Concentrated humic acid products reduce shipping volumes for remote horticultural buyers in California and South Africa, opening distribution to previously uneconomical geographies.
- Carbon sequestration crediting:The EU Green Deal's soil carbon accounting frameworks are positioning artificial humus as a measurable input for farm-level carbon offset generation.
Industry Challenges
- Humic substance assay standardization:Analytical method divergence between German BVL protocols and USDA reference standards creates batch rejection risk at import checkpoints.
- Controlled-environment agronomy staffing:Precision farming system operators lack training protocols for artificial humus integration with sensor-based nutrient management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Humus Market |
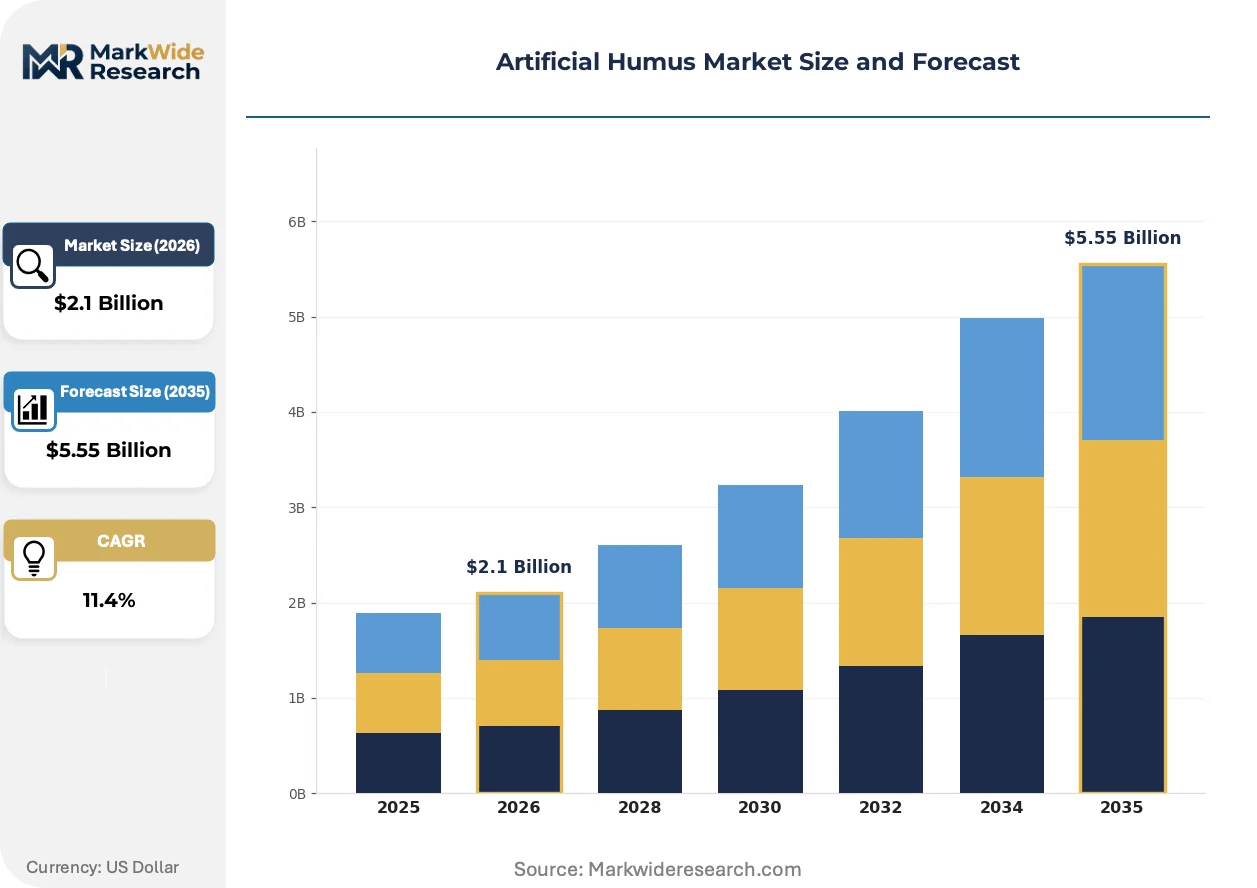
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powdered, Concentrate Application: Agriculture, Horticulture, Landscaping, Erosion Control Distribution Channel: Online Retail, Direct Sales, Wholesale, Garden Centers End User: Farmers, Nurseries, Commercial Growers, Residential Customers |
| Companies Covered | Novihum Technologies GmbH, Organic Approach, LLC, Humusolver, FAUST BIO-AGRICULTURAL SERVICES, INC., Nature's Force Organics, The Fertrell Company, Humintech, Nutri-Tech Solutions Pty Ltd., Ohio Earth Food, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Humus Market Strategic Shifts
Product formulation chemistry and regulatory carbon accounting are converging to reposition artificial humus from commodity input to precision agriculture infrastructure, with liquid concentrates and granular slow-release variants diverging toward distinct end-use verticals.
Enzymatic catalysis of lignite oxidation is expanding into commercial-scale humification, accelerating production cycles from months to days while preserving cation exchange capacity above 300 meq per 100 grams. Spanish greenhouse operators are piloting these bio-catalyzed formulations in tomato and pepper substrates. The technology is expanding into premium horticultural supply chains previously served by peat-based alternatives.
REACH registration requirements for humic substance imports are tightening purity documentation and supply chain carbon footprint disclosure across EU member states. Importers must now submit third-party assay certificates for heavy metal content and polycyclic aromatic hydrocarbon limits. German distributors are consolidating supplier relationships to reduce audit complexity, compressing the vendor base for non-EU producers.
Buyer concentration among large-scale controlled-environment agriculture operators is compressing purchasing cycles and unbundling technical advisory services from product supply. Dutch greenhouse cooperatives now negotiate direct manufacturing contracts, bypassing traditional agricultural input distributors. This pattern is most visible in the Netherlands, where three grower cooperatives account for the majority of technical-grade humus procurement.
Artificial Humus Market Segmentation
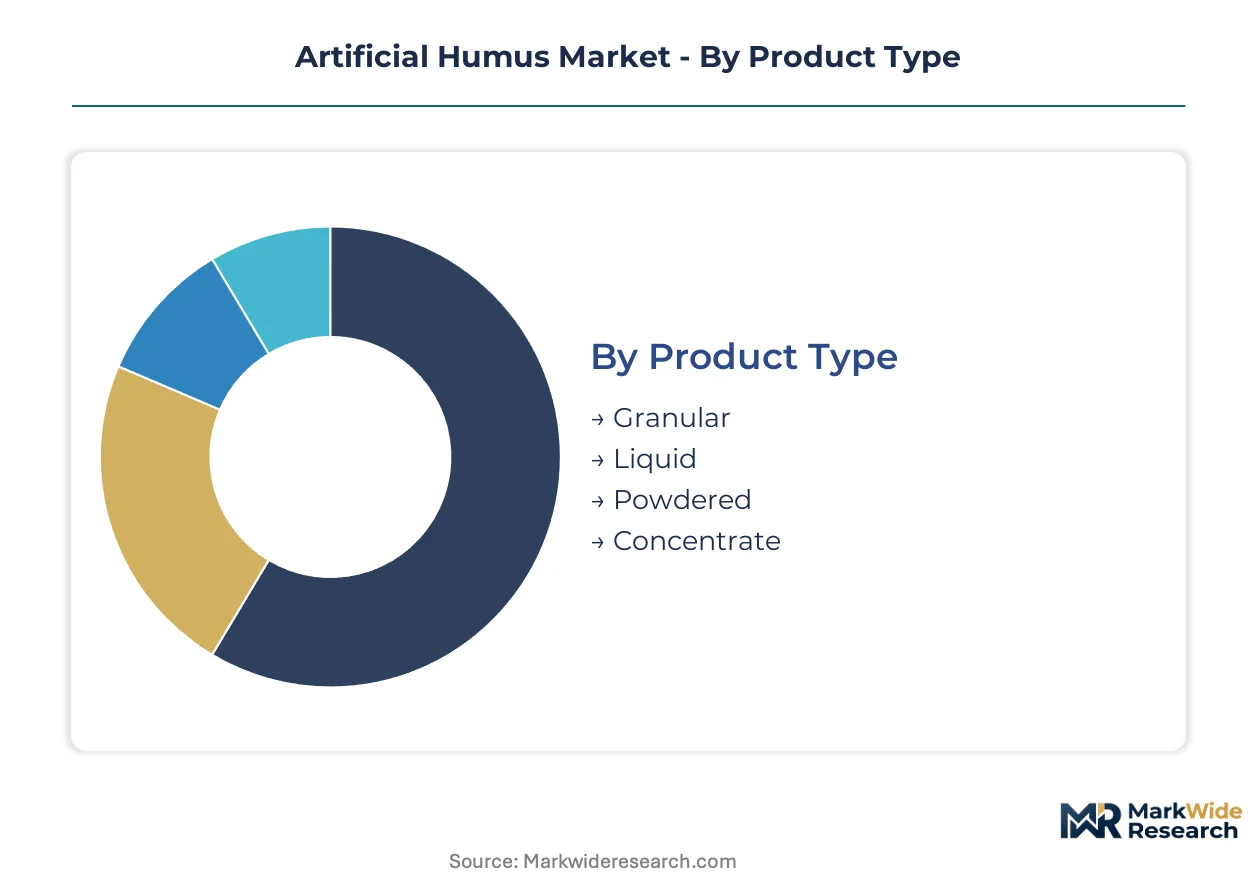
Artificial humus buyers select formulations based on equipment compatibility, freight economics, and certification requirements that vary sharply across end-use verticals. Segmentation reveals how granular and liquid variants diverge toward distinct customer profiles while distribution channel choices reflect scale and technical support needs.
Product Type:
Equipment compatibility and freight cost sensitivity drive formulation selection among commercial buyers.
- Granular:Slow-release pellets containing 60-80% humic acids integrate with existing spreader infrastructure across German and Polish broadacre grain operations. German BVL certification requirements for organic operations protect lignite-derived granular supply from synthetic substitute competition.
- Liquid:Concentrated humic acid solutions reduce shipping volumes by 70-85% versus dry equivalents, enabling economical distribution to remote horticultural buyers in California and South Africa. Drip-irrigation penetration in Spanish and Dutch protected-cropping facilities pulls liquid formulations into high-value tomato and pepper supply chains.
- Powdered:Fine-milled humus serves specialty blending operations and export markets requiring containerized bulk shipment.
- Concentrate:Ultra-concentrated extracts target precision fertigation systems with automated dosing capabilities.
Granular leads on scale; liquid leads on momentum.
Application:
Regulatory mandates and contract horizons reshape demand concentration across use cases.
- Agriculture:Soil structure restoration and nutrient retention applications dominate volume consumption across EU commercial farming operations subject to Green Deal soil health targets. Carbon sequestration crediting frameworks position artificial humus as a measurable input for farm-level offset generation.
- Erosion Control:Post-mining land rehabilitation contracts in Australia and Poland extend demand into multi-year service agreements with government and mining sector clients. These projects require engineered humus with cation exchange capacity exceeding 300 meq per 100 grams for substrate stabilization.
- Horticulture:Greenhouse substrate amendments for tomato, pepper, and ornamental production concentrate demand in Dutch and Spanish cooperative purchasing networks.
- Landscaping:Turf establishment and golf course maintenance applications favor cost-optimized formulations in non-certified channels.
Agriculture dominates absolute volume; erosion control commands the longest contract durations.
Distribution Channel:
Scale and technical advisory requirements determine channel selection across buyer tiers.
- Direct Sales:Large-scale controlled-environment agriculture operators in the Netherlands negotiate manufacturing contracts directly, bypassing distributors to unbundle technical advisory services from product supply. Three Dutch greenhouse cooperatives now account for the majority of technical-grade humus procurement.
- Wholesale:Agricultural input distributors consolidate supplier relationships to reduce REACH audit complexity, compressing the vendor base for non-EU producers seeking EU market access.
- Online Retail:E-commerce penetration remains limited to small-scale residential and nursery buyers with standardized product requirements.
- Garden Centers:Point-of-sale availability targets residential customers and small commercial landscapers in suburban and rural markets.
Direct sales captures the largest transaction values; wholesale maintains the broadest geographic coverage.
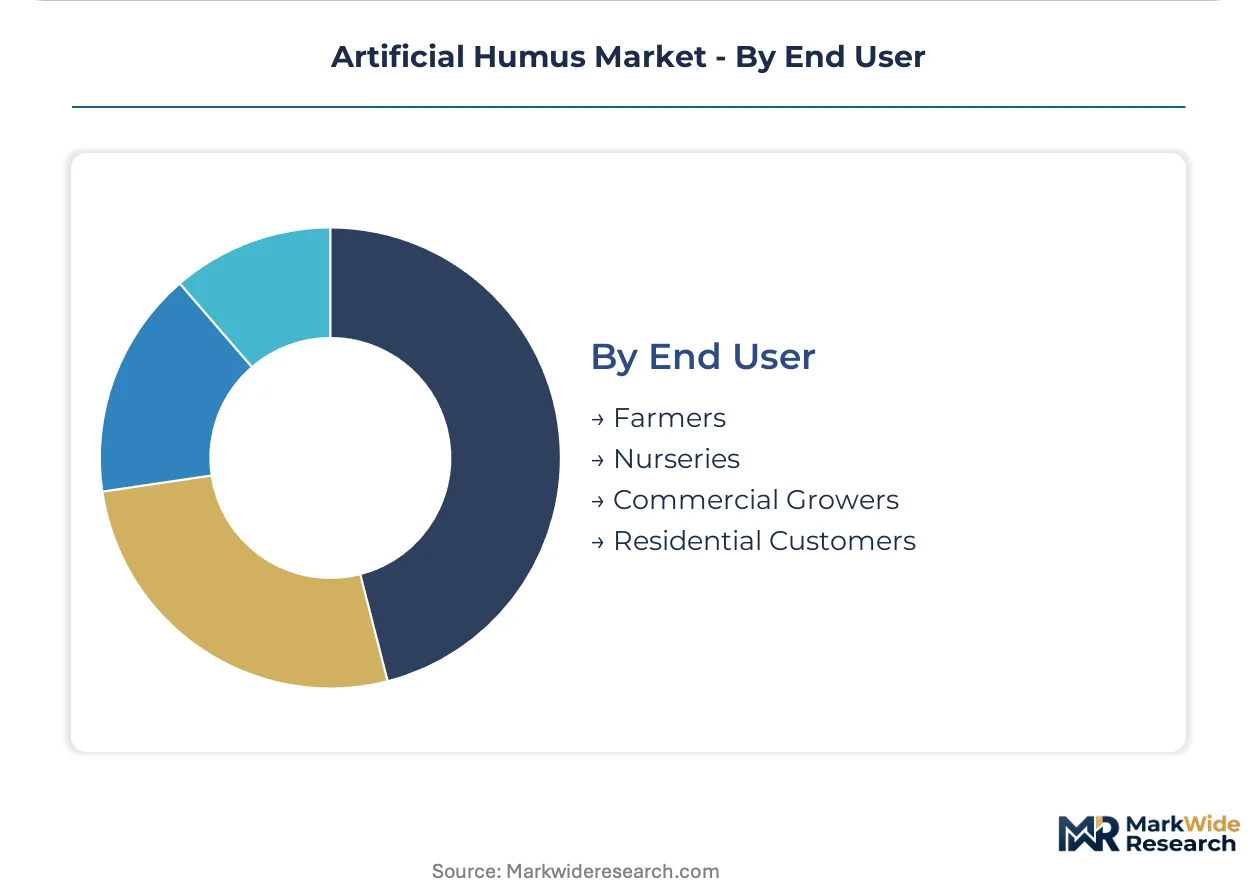
End User:
Certification status and technical sophistication fragment procurement behavior across customer categories.
- Commercial Growers:Controlled-environment agriculture operators in Spain, the Netherlands, and California demand liquid concentrates compatible with sensor-based nutrient management platforms. Staffing gaps in precision farming agronomy create adoption friction requiring manufacturer technical support.
- Farmers:Broadacre grain producers in Germany and Poland select granular formulations based on BVL organic certification eligibility and spreader equipment compatibility.
- Nurseries:Containerized plant production operations balance substrate cost against batch consistency requirements.
- Residential Customers:Home garden applications prioritize convenience and price over technical specifications in non-certified channels.
Commercial growers drive formulation innovation; farmers provide the volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered commercial-scale lignite-humification for artificial humus production during the post-war agricultural modernization period. Central European brown coal deposits anchored the industry's technical standards and regulatory frameworks before expansion into North American and Asia-Pacific markets.
Germany
Commercial growers in Lower Saxony and Brandenburg deploy granular formulations to meet BVL organic certification requirements for depleted peat substitution. The EU Green Deal's soil health targets compress adoption timelines ahead of binding 2030 benchmarks. Novihum Technologies GmbH operates production facilities in Dresden, supplying technical-grade humus for precision farming systems across the country.
United States
California greenhouse operators and Midwest grain producers drive liquid concentrate procurement for drip-irrigation and broadacre applications respectively. USDA National Organic Program standards diverge from EU REACH protocols, fragmenting certification pathways for imported European products. The Fertrell Company maintains distribution relationships with certified organic operations throughout Pennsylvania and surrounding states.
Netherlands
Dutch greenhouse cooperatives in Westland and Aalsmeer negotiate direct manufacturing contracts for tomato and pepper substrate amendments. REACH compliance documentation requirements standardize product traceability across member state borders. Three grower cooperatives now account for the majority of technical-grade humus procurement in the country's protected-cropping sector.
Spain
Andalusian and Murcian protected-cropping facilities pull liquid formulations into high-value horticultural supply chains through fertigation infrastructure expansion. The country's national agricultural regulator enforces humic substance purity standards aligned with EU F-Gas Regulation carbon-footprint disclosure mandates. Almería's greenhouse cluster represents the densest concentration of artificial humus integration with sensor-based nutrient management platforms.
Australia
Post-mining land rehabilitation contracts in Western Australia and Queensland extend demand into erosion-control applications with multi-year service horizons. The country's environmental protection authority requires engineered humus with cation exchange capacity exceeding 300 meq per 100 grams for substrate stabilization projects. Perth-based technical services firms coordinate multi-year rehabilitation agreements with government and mining sector clients.
Artificial Humus Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across distinct value chain positions. The vendor base concentrates around lignite-processing specialists with captive feedstock access and formulation laboratories serving remote horticultural markets. Three archetypes dominate: integrated brown-coal processors, concentrated-liquid specialists, and regional distribution anchors. Capacity expansion and direct sales channel development represent the dominant competitive moves as buyer concentration among large-scale greenhouse cooperatives compresses purchasing cycles.
Among German-integrated processors, Novihum Technologies GmbH exemplifies the capital-intensive archetype with patented lignite-humification capabilities. Humintech occupies a position within the liquid formulation tier, while The Fertrell Company anchors North American distribution through relationships with certified organic operations. These three entities represent the structural segmentation between manufacturing gravity and market access specialization.
| Leading Market Players |
|---|
| Novihum Technologies GmbH |
| Organic Approach, LLC |
| Humusolver |
| FAUST BIO-AGRICULTURAL SERVICES, INC. |
| Nature's Force Organics |
| The Fertrell Company |
| Humintech |
| Nutri-Tech Solutions Pty Ltd. |
| Ohio Earth Food |
| Others |
Value Chain & Pricing Dynamics
Lignite benchmark prices in Central European energy markets cascade through artificial humus production economics, compressing margins for non-integrated processors while amplifying pricing power for brown-coal miners with captive humification capacity. Buyers face three-tier pricing stratification across premium certified-organic, standard agricultural-grade, and economy non-certified tiers, with freight costs to remote horticultural markets widening spreads between liquid concentrate and granular formulations.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between German producers and Dutch greenhouse cooperatives, with spot transactions limited to smaller agricultural distributors. Price differentiation rests on BVL organic certification eligibility and cation exchange capacity assay thresholds above 300 meq per 100 grams. Cost compression in standard-grade granular supply is intensifying because municipal compost substitutes are undercutting lignite-derived products in non-certified channels. Residential gardeners exhibit highest price sensitivity, while Dutch cooperative buyers prioritize batch consistency over per-tonne savings.
Supply Chain Analysis
Empty container repositioning from European horticultural export corridors creates backhaul opportunities for liquid concentrate shipments to South African and Australian buyers, reducing effective freight rates by 15-20 percent versus dry bulk alternatives. Production gravity centers on Germany, Poland, and the Czech Republic, with brown coal deposits feeding integrated humification facilities. Feedstock supply draws from lignite mining operations facing energy transition license uncertainties, creating single-source vulnerability for non-integrated processors. Distribution runs through agricultural input distributors consolidating supplier relationships to manage REACH audit complexity, compressing vendor access for non-EU producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial humus market functions as a stable compounder anchored by irreversible peat substitution mandates across EU commercial agriculture, with regulatory soil health targets generating demand inelasticity regardless of commodity cycle positioning.
For Market Incumbents: To counter municipal compost substitute encroachment in non-certified channels, deepen backward integration into captive lignite feedstock through long-term mining concessions in Poland and the Czech Republic. Augment technical advisory capacity for precision farming system operators facing staffing gaps in artificial humus integration protocols.
For New Entrants and Emerging Players: Begin with liquid concentrate formulation targeting California greenhouse operators and South African remote horticultural buyers where freight economics exclude German granular suppliers. Pursue direct manufacturing contracts with Spanish protected-cropping cooperatives in Almería and Murcia, leveraging REACH compliance documentation investments as competitive barrier against non-EU rivals.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH audit complexity and carbon-footprint disclosure requirements fragment the vendor base for non-integrated distributors. The five-to-ten year viability thesis rests on EU Green Deal soil carbon accounting frameworks positioning artificial humus as measurable offset infrastructure. Target asset-light liquid formulation specialists with established fertigation channel relationships. Monitor divergence between German BVL and USDA-NOP certification standards as signal for reformulation cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignite Mining | Captive feedstock access insulates margin structure from energy transition policy volatility in Germany and Poland. |
| Liquid Concentrate Capacity Expansion | Fertigation infrastructure penetration in Spanish and Dutch protected-cropping facilities pulls concentrated formulations into premium supply chains. |
| REACH Compliance Documentation Investment | Third-party assay certification for heavy metal and PAH limits secures EU market access as audit complexity compresses vendor base. |
| Direct Sales Channel Development | Bypassing agricultural input distributors captures margin from Dutch greenhouse cooperatives consolidating technical-grade procurement. |
| Carbon Sequestration Crediting Partnership | EU Green Deal soil carbon accounting frameworks position artificial humus as measurable input for farm-level offset generation. |
Study Parameters
Coverage spans Germany, the Netherlands, Spain, the United States, and Australia, with primary inputs from each market triangulated against secondary validation. Interviews with agricultural input distributors, greenhouse cooperative procurement managers, lignite mining operation planners, REACH compliance consultants, and precision farming system operators informed demand-side and supply-side dynamics. Secondary sources include EU F-Gas Regulation filings, German BVL certification databases, USDA National Organic Program input lists, customs trade data for humic substance imports, and SEC filings from publicly traded agricultural input distributors. Bottom-up volume modeling across product type, application, and end-user segments was cross-validated against top-down market sizing from production capacity assessments.
Granularity extends to formulation chemistry differentiation, certification pathway fragmentation between EU and North American frameworks, and channel structure evolution toward direct manufacturing contracts. Modeled dimensions include product type, application vertical, distribution channel, and end-user certification status, with CAGRs derived from regression analysis of historical adoption curves against regulatory mandate implementation timelines. Forecast inputs incorporated peat substitution mandate enforcement schedules, drip-irrigation infrastructure deployment rates in protected-cropping facilities, and post-mining rehabilitation contract award patterns in Australia and Poland.
Several conditions sit outside the modeled scope, including abrupt lignite mining license revocation under accelerated energy transition scenarios, breakthrough enzymatic catalysis technologies disrupting production economics, and harmonization between EU REACH and USDA-NOP standards eliminating dual certification costs. Forecasts reflect documented assumptions regarding regulatory implementation fidelity and commercial grower technical capacity development. Practitioners should monitor German Federal Office for Consumer Protection and Food Safety enforcement patterns, Dutch greenhouse cooperative consolidation rates, and municipal compost processing cost curves for early signals of demand or supply inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Soil Treatment Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
India Fungicide Market