
 Asia-Pacific Feed Minerals Market | 2026-2036
Asia-Pacific Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Minerals Market Outlook
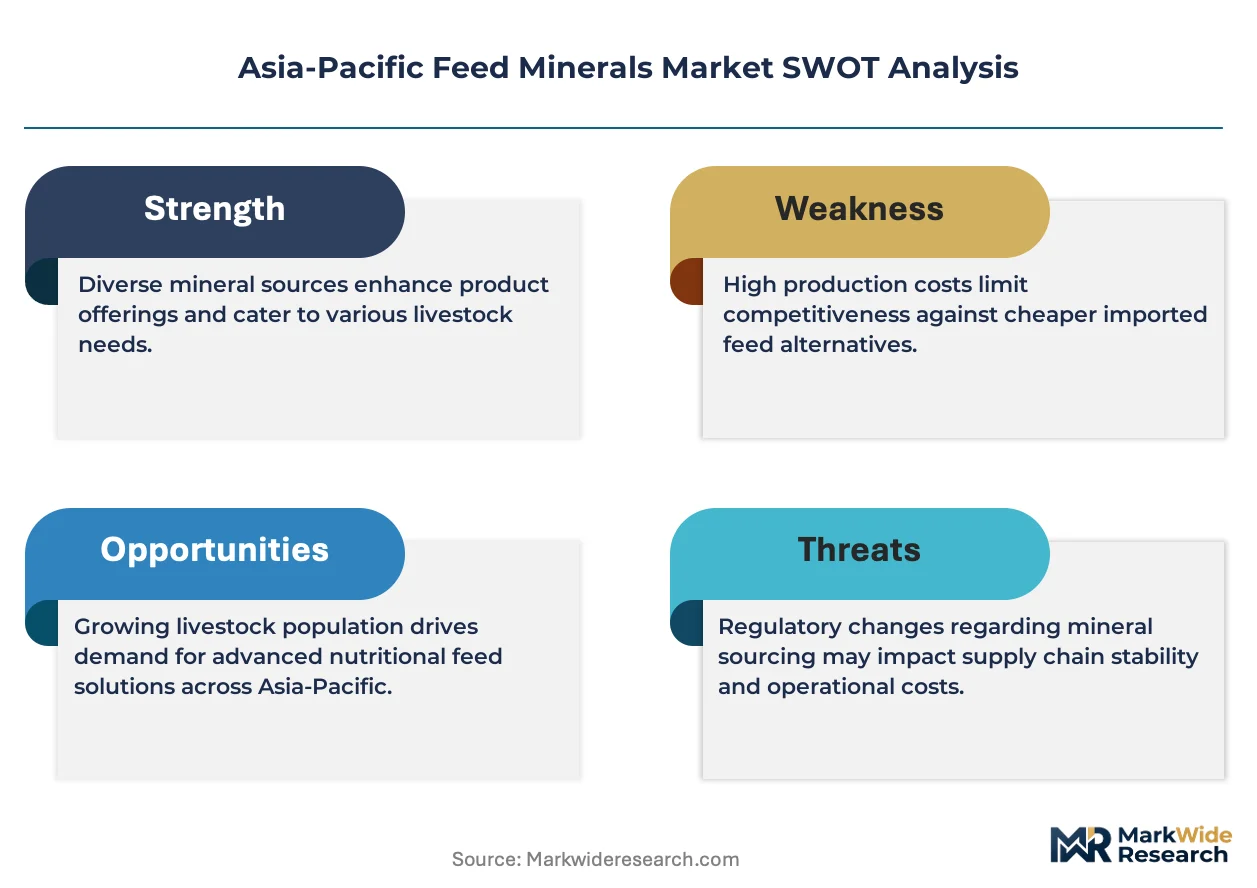
Aftermarket nutrition consulting revenue is tilting toward integrated mineral auditing services, capturing margin pools that once sat with basic commodity sales. Cargill Inc leverages its regional grain origination network to secure captive supply of phosphate and limestone precursors. BASF SE anchors its position through R&D intensity in chelated trace element formulations. Nutreco NV competes via species-specific mineral programs tailored to tropical climate stressors.
Asia-Pacific feed minerals comprise inorganic and organic compounds added to animal diets to correct micronutrient deficiencies, typically formulated as premixes containing 0.5-2% copper, zinc, manganese, iron, selenium, or iodine by weight, manufactured through spray-drying, crystallization, or chelation processes to ensure bioavailability and homogeneous distribution in finished feed. Their primary commercial purpose is optimizing feed conversion ratios, reproductive performance, and immune function in intensively raised livestock. Mineral mixtures dominate volume due to established cost structures, while trace elements command premium positioning as aquaculture intensifies and shrimp producers adopt precision nutrition protocols. Powdered forms retain share in ruminant operations, though liquid mineral systems gain traction in automated pig and poultry houses where dosing accuracy reduces waste.
India's BIS feed-grade standards, China's SAMR mineral maximum-residue limits, and Australia's TGA veterinary chemical guidelines collectively elevate compliance costs while filtering out substandard suppliers. These frameworks push manufacturers toward third-party certified premixes and full-chain traceability documentation. Stakeholders must monitor how Indonesia's emerging feed safety regulations and Vietnam's tightening aquaculture drug-residue rules reshape mineral specification requirements and import clearance protocols.
Market Dynamics
China's SAMR mineral maximum-residue limits and Indonesia's emerging feed safety regulations are compressing formulation flexibility while forcing manufacturers toward third-party certified premixes and full-chain traceability documentation across Southeast Asian livestock operations.
Growth Catalysts
- Integrated poultry sector expansion:Indonesia's large-scale broiler farms require precision mineral supplementation protocols, driving demand for fortified premixes containing copper, zinc, and selenium compounds.
- GB standards compliance pressure:China's feed safety mandates reshape product formulation requirements, filtering substandard suppliers and elevating certified premix adoption among domestic compound feed manufacturers.
- Aquaculture intensification:Shrimp producers across Vietnam and Thailand adopt precision nutrition protocols, creating premium positioning for chelated trace elements in marine feed applications.
Market Restraints
- Phosphate precursor cost volatility:Captive supply constraints for limestone and phosphate rock inputs expose formulators to raw material price swings affecting margin stability.
- Import clearance friction:Vietnam's tightening aquaculture drug-residue rules and inconsistent customs protocols delay mineral premix shipments, extending working capital cycles.
- Inorganic mineral commoditization:Established cost structures for basic mineral mixtures limit pricing power, compressing returns for non-differentiated suppliers.
Strategic Opportunities
- Automated dosing systems penetration:Liquid mineral systems gain traction in Thailand's pig and poultry houses, where dosing accuracy reduces waste and enables service-based revenue models.
- PLI scheme alignment:India's production-linked incentive frameworks for feed-grade manufacturing attract domestic capacity expansion for trace element formulations.
- Tropical climate stressor protocols:Species-specific mineral programs addressing heat stress in Indonesian and Philippine livestock operations command technical consulting premiums.
Industry Challenges
- Chelated formulation expertise scarcity:R&D intensity in organic trace element manufacturing outpaces available technical talent pools across regional research institutions.
- Multi-jurisdiction certification timelines:Simultaneous compliance with India's BIS feed-grade standards, Australia's TGA veterinary chemical guidelines, and China's GB standards extends product registration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Minerals Market |
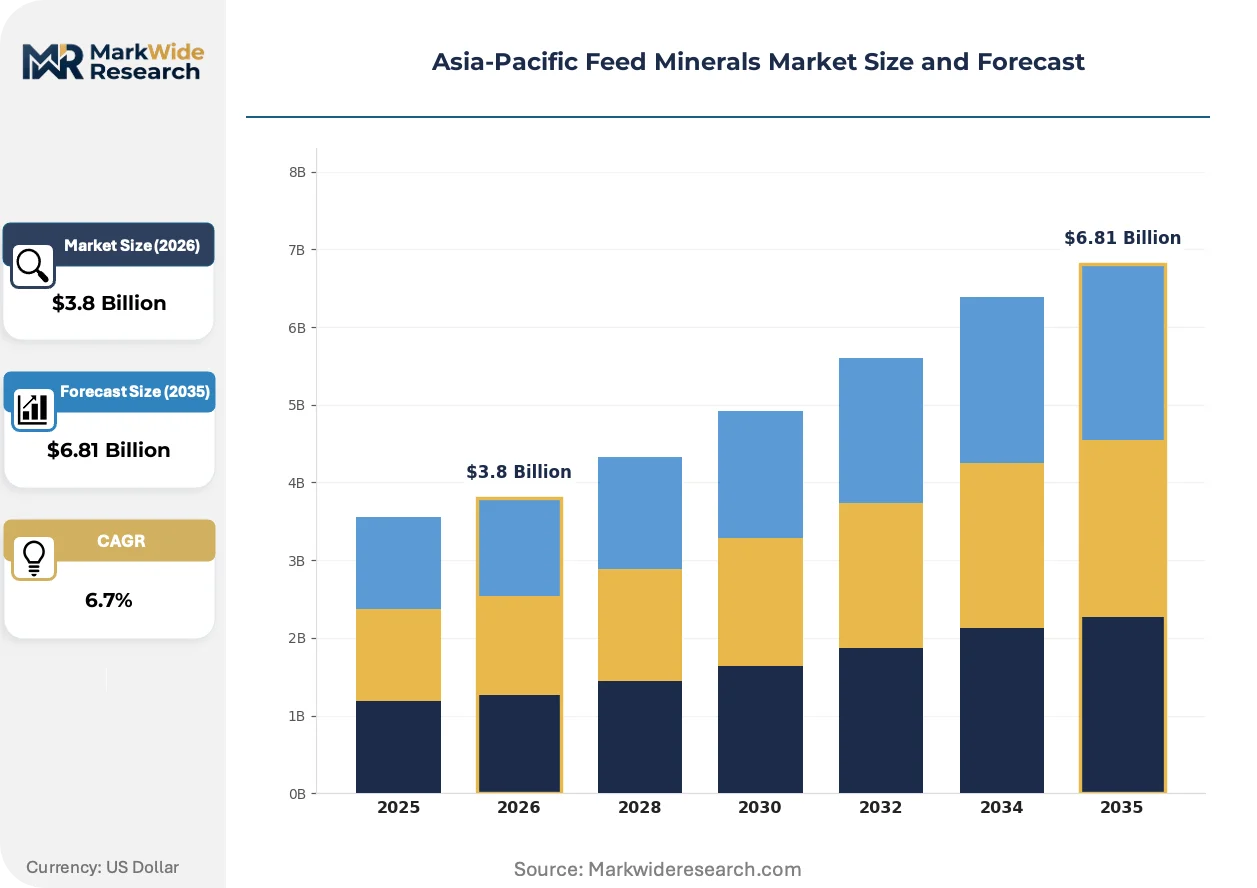
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Mixtures, Trace Elements, Vitamins, Amino Acids End User: Poultry, Ruminants, Swine, Aquaculture Form: Granulated, Liquid, Powdered, Pelleted Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Archer Daniels Midland Co, Cargill Inc, BASF SE, Adisseo, Kemin Industries, Nutreco NV, Novus International Inc, Solvay S.A., Koninklijke DSM NV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Minerals Market Strategic Shifts
Digital mineral auditing platforms and precision dosing hardware are compressing the traditional premix value chain, shifting margin capture toward data-integrated service models and away from commodity mineral sales.
Nano-encapsulated trace mineral delivery systems are virtualizing bioavailability optimization in shrimp and high-value aquaculture feeds. Thai and Vietnamese marine feed producers adopt these systems at accelerating pace to meet export market residue requirements. This technology is virtualizing the competitive advantage of legacy chelation processes, compressing differentiation timelines for established organic mineral suppliers.
Australia's TGA veterinary chemical guidelines and India's FSSAI feed-grade specifications are tightening maximum-residue thresholds for selenium and iodine compounds. These frameworks force reformulation of existing premix portfolios and accelerate third-party laboratory certification investments. Aquaculture exporters across Southeast Asia face the steepest compliance costs as destination markets align with these standards.
Integrated livestock operations in Indonesia and the Philippines now specify outcome-based mineral supplementation contracts tied to feed conversion ratios rather than input tonnage. This purchasing model displaces traditional commodity premix procurement and concentrates supplier selection among firms offering technical field support. The shift is most visible in contract broiler farming clusters around Jakarta and Manila where processor integration is deepest.
Asia-Pacific Feed Minerals Market Segmentation
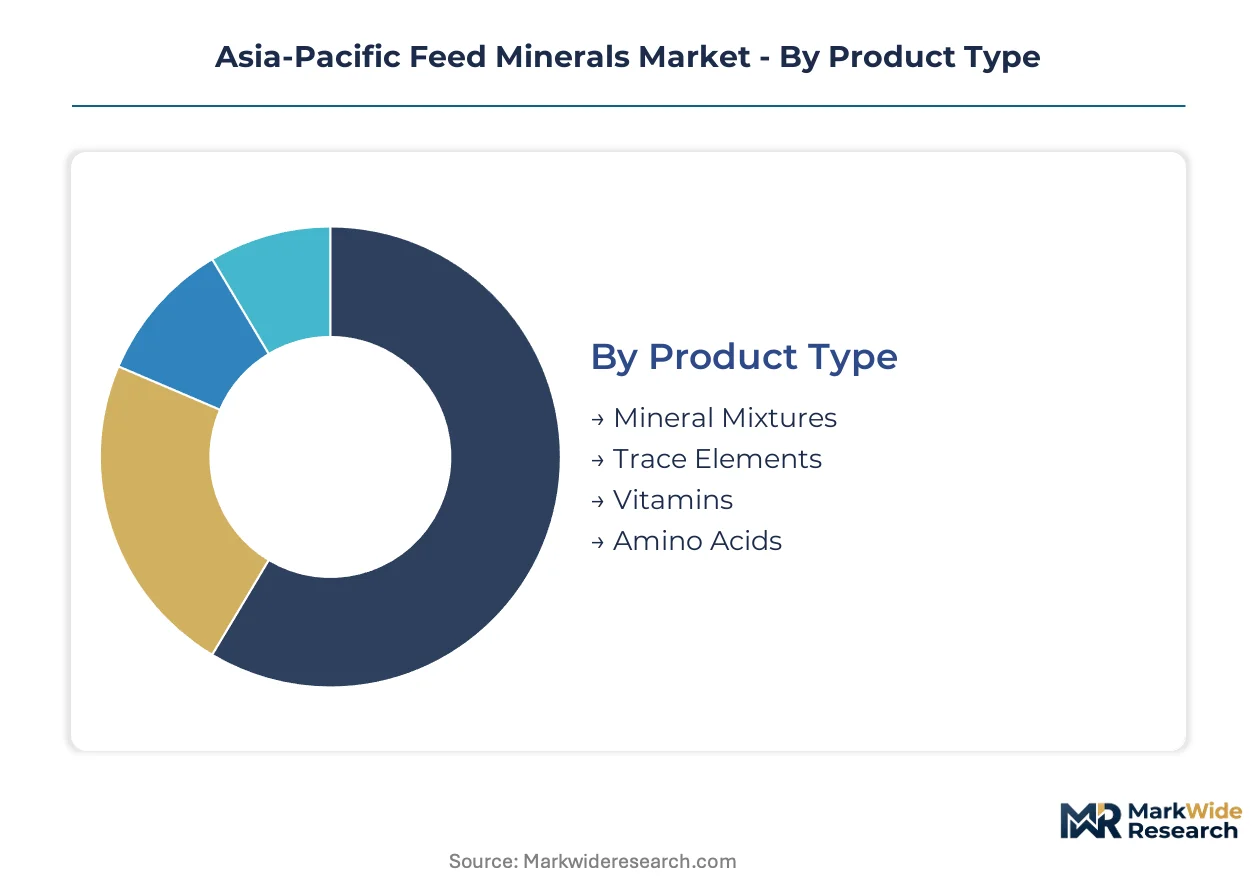
Segmentation in Asia-Pacific feed minerals reveals how formulation requirements diverge across livestock species and operational scales. Understanding these divides exposes where premium pricing power concentrates versus where commoditization pressures dominate procurement decisions.
Product Type:
Mature inorganic formulations coexist with emerging organic alternatives, creating a bifurcated technology landscape across regional feed mills.
- Mineral Mixtures:Bulk premixes containing macro-minerals like calcium, phosphorus, and magnesium dominate volume in ruminant and swine operations. Indonesian integrated poultry farms specify these formulations for basal diet fortification, though SAMR compliance costs are compressing margins for non-certified suppliers.
- Trace Elements:Chelated copper, zinc, and selenium compounds deliver superior bioavailability in intensive aquaculture systems. Vietnam's shrimp exporters specify these to meet Australia's TGA residue thresholds, creating technical differentiation that commands 40-60% pricing premiums over inorganic equivalents.
- Vitamins:Fat-soluble and water-soluble vitamin premixes stabilize against oxidation in tropical storage conditions. Philippine feed compounders prioritize these for layer hen diets to sustain egg production under heat stress.
- Amino Acids:Synthetic lysine, methionine, and threonine supplementation reduces crude protein requirements. Thai swine nutritionists specify these to lower nitrogen excretion costs in environmental compliance zones.
Mineral mixtures retain volume leadership; trace elements hold the steepest expansion curve.
End User:
Customer concentration varies sharply, with contract farming integration determining whether procurement centralizes at processor level or fragments across independent operations.
- Poultry:Broiler and layer operations consume the largest mineral tonnage, driven by Indonesia's vertically integrated farming clusters around Jakarta and Surabaya. GB standards compliance now mandates third-party certified premixes for export-oriented processors.
- Aquaculture:Marine shrimp and finfish farming generates the fastest-growing demand for chelated trace minerals. Vietnamese exporters to EU markets face EFSA-aligned residue limits that disqualify basic inorganic formulations.
- Ruminants:Dairy and beef cattle operations in India and Australia rely on mineral mixtures for forage-based diets. BIS feed-grade specifications reshape product registration requirements for domestic manufacturers.
- Swine:Pig farming across Thailand and Vietnam drives liquid mineral system adoption in automated housing. Heat stress protocols in tropical climates create demand for electrolyte and trace element combinations.
Poultry dominates absolute consumption; aquaculture generates the fastest-growing trajectory.
Form:
Physical formulation determines dosing precision, storage stability, and compatibility with automated feed mill infrastructure.
- Powdered:Fine-ground mineral premixes blend uniformly into mash feeds for ruminant and backyard poultry operations. India's smallholder dairy sector relies on these for cost-effective supplementation.
- Liquid:Pump-dosed mineral systems integrate with automated pig and poultry houses in Thailand's commercial sector. Dosing accuracy reduces waste and enables real-time adjustment based on flock performance data.
- Granulated:Free-flowing mineral carriers prevent segregation during transport and storage. Australian feed mills specify these for remote delivery to extensive cattle operations.
- Pelleted:Compressed mineral blocks suit self-feeding systems in Philippine grazing operations. Limited adoption in intensive sectors due to higher unit costs and inflexible dosing.
Powdered forms retain volume leadership; liquid systems gain share fastest in automated facilities.
Distribution Channel:
Channel structure reflects farm scale concentration, with direct sales capturing integrated operations while distributors serve fragmented smallholder markets.
- Direct Sales:Major premix manufacturers contract directly with Indonesia's integrated poultry processors and Thailand's aquafeed conglomerates. Technical service bundling secures multi-year supply agreements.
- Distributors:Regional wholesalers aggregate demand across India's fragmented dairy sector and Vietnam's independent pig farms. Working capital financing and local language support sustain their intermediary role.
- Wholesalers:Bulk mineral traders serve compound feed mills with established formulation capabilities. Price transparency pressures margins in standardized mineral mixture categories.
- Online Retail:E-commerce platforms emerge for small-scale aquaculture and backyard poultry operators. Limited to non-prescription mineral supplements due to feed-grade regulatory restrictions.
Direct sales capture the highest-value accounts; distributor networks retain deepest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's integrated poultry processors show the lowest price elasticity, accepting technical premiums for certified premixes, while India's fragmented dairy sector forces suppliers toward commodity mineral mixtures with thin margins.
China
GB standards compliance and SAMR mineral maximum-residue limits reshape formulation requirements for domestic compound feed manufacturers. The national feed safety regulator filters substandard suppliers through mandatory third-party certification protocols. Jiangsu and Shandong provinces concentrate premix manufacturing capacity where export-oriented processors demand full-chain traceability documentation.
Indonesia
Vertically integrated broiler farms around Jakarta and Surabaya drive precision mineral supplementation protocols at scale. The country's emerging feed safety regulations compress formulation flexibility while elevating certified premix adoption. Commercial farming clusters in West Java specify fortified copper, zinc, and selenium compounds tied to feed conversion ratio performance metrics.
Vietnam
Shrimp exporters to EU markets adopt chelated trace minerals to meet tightening aquaculture drug-residue rules. The Ministry of Agriculture and Rural Development's tightening protocols delay import clearances for mineral premix shipments. Mekong Delta aquaculture zones specify nano-encapsulated delivery systems to satisfy Australia's TGA-aligned residue thresholds.
India
BIS feed-grade standards and FSSAI specifications reshape product registration requirements for domestic manufacturers. The PLI scheme for feed-grade manufacturing attracts capacity expansion for trace element formulations. Maharashtra and Gujarat dairy cooperatives rely on powdered mineral premixes for cost-effective smallholder supplementation programs.
Thailand
Automated pig and poultry houses drive liquid mineral system adoption where dosing accuracy reduces waste. The national agricultural regulator aligns with ASEAN harmonized standards for mineral maximum-residue limits. Central Plains commercial farming zones specify pump-dosed systems integrated with real-time flock performance data platforms.
Asia-Pacific Feed Minerals Market Competitive Environment
Integrated nutrition platforms and commodity mineral suppliers split the market along a technical sophistication fault line. The structure concentrates premium positioning among firms bundling field consulting with certified premix formulations, while undifferentiated mineral mixture producers compete on input cost alone. Three archetypes dominate: captive supply integrators controlling phosphate and limestone precursors; R&D-intensive chelation specialists; and species-specific program providers tailoring tropical climate protocols. Capacity expansion and strategic partnerships represent the dominant competitive moves, with firms securing multi-year supply agreements through technical service bundling.
Among the integrated nutrition platforms, Cargill Inc anchors the captive supply archetype through regional grain origination networks securing phosphate and limestone precursors. BASF SE occupies a position exemplifying R&D intensity in chelated trace element formulations. Nutreco NV represents the species-specific program specialist, competing via mineral protocols tailored to tropical climate stressors in Indonesian and Philippine livestock operations.
| Leading Market Players |
|---|
| Archer Daniels Midland Co |
| Cargill Inc |
| BASF SE |
| Adisseo |
| Kemin Industries |
| Nutreco NV |
| Novus International Inc |
| Solvay S.A. |
| Koninklijke DSM NV |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Shandong provinces concentrate premix manufacturing capacity where export-oriented processors demand full-chain traceability documentation, compressing margins for non-certified suppliers while elevating pricing power for third-party verified producers. This geographic concentration of formulation expertise creates tiered value capture across the mineral premix landscape.
Pricing Analysis
Technical consulting and mineral auditing services now drive lifetime value beyond commodity premix sales. Three-tier pricing structure across certified-premium, standard-grade, and economy mineral mixtures dominates procurement, with GB standards compliance and SAMR certification acting as the primary price differentiation drivers. Pricing pressure stems from inorganic mineral commoditization in India's fragmented dairy sector, where smallholders exhibit extreme price sensitivity. Indonesia's integrated poultry processors show the lowest price sensitivity, accepting technical premiums for certified premixes tied to feed conversion performance.
Supply Chain Analysis
Phosphate rock and limestone feedstock sourcing draws from captive supply networks anchored in China's grain origination corridors and Australian mining operations. Key inputs include chelated copper and zinc compounds, selenium premixes, and iodine formulations. Single-source vulnerability concentrates around phosphate precursor supply, exposing formulators to raw material cost swings. Distribution runs through direct sales channels for integrated poultry processors and aquafeed conglomerates, with regional distributors serving fragmented smallholder markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral auditing and precision dosing services are expanding faster than commodity premix sales, creating a service-attach opportunity where technical consulting margins exceed hardware margins by substantial multiples.
For Market Incumbents: Build captive supply moats through backward integration into phosphate and limestone precursor networks. Secure multi-year supply agreements with Indonesia's integrated poultry processors by bundling certified premix formulations with real-time flock performance monitoring. Counter chelated formulation expertise scarcity by anchoring R&D partnerships with regional agricultural universities. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's shrimp export sector by specializing in nano-encapsulated trace mineral delivery systems aligned with Australia's TGA residue thresholds. Target India's PLI-incentivized trace element manufacturing capacity as a white-space entry point. Lead with automated liquid dosing system integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors species-specific program providers with tropical climate stressor protocols over undifferentiated mineral mixture producers. Long-term viability hinges on technical service bundling capabilities and regulatory certification depth. Monitor Indonesia's emerging feed safety regulations as the critical inflection signal for certified premix demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Precursors | Cargill's regional grain origination network secures captive limestone supply for margin stability. |
| Chelated Trace Element R&D Expansion | BASF's organic mineral formulations command premium positioning in Vietnam's shrimp export sector. |
| Species-Specific Tropical Climate Programs | Nutreco's heat stress protocols capture technical consulting premiums in Philippine livestock operations. |
| Automated Liquid Dosing System Deployment | Thailand's pig and poultry houses reduce mineral waste through pump-integrated precision delivery. |
| Third-Party Certification Investment | SAMR and BIS compliance filters substandard suppliers from China's compound feed supply base. |
Study Parameters
Operator-level perspectives from feed mill procurement managers, poultry farm nutritionists, aquaculture technical directors, and regulatory affairs leads anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, FSSAI and SAMR regulatory filings, and compound feed industry association reports. Bottom-up mineral premix volume estimates triangulated against top-down livestock production forecasts.
Scenario-bracketing framed the analytical approach across the analysis window, modeling segmentation by product type, livestock species, physical form, and distribution channel. CAGRs derived from mineral inclusion rate trajectories, livestock inventory projections, and aquaculture intensification curves. Feed conversion ratio improvement assumptions and regulatory compliance cost escalation fed into value projections.
Macroeconomic conditions sit as an overlay; deviation in phosphate rock pricing, currency volatility in Southeast Asian markets, or feed safety regulation acceleration would shift the trajectory. Cross-checking against livestock production statistics from national agricultural ministries and compound feed industry output data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market