
 Feed Pigments Market | 2026-2036
Feed Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Pigments Market Intelligence
Asset-light manufacturing models, relying on contract production and specialized sourcing, are reconfiguring the competitive landscape for new entrants. This allows smaller firms to compete without heavy capital investment in production facilities. In contrast, established players like BASF SE leverage extensive chemical synthesis capabilities. Kemin Industries, Inc. differentiates with its focus on natural pigment solutions, while Cargill Incorporated integrates pigments into its broader animal nutrition services.
Feed pigments are additives used in animal nutrition to impart color to animal tissues and products like egg yolks and fish flesh. These compounds, often specific carotenoids like canthaxanthin, must meet precise purity standards for bioavailability. The poultry and aquaculture sectors represent the largest applications, driven by consumer preference for specific coloration. Carotenoids dominate the product landscape, though demand for natural source pigments is accelerating.
Regulatory approvals create significant market access barriers and influence product formulation. The U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) maintain stringent approval processes for new feed additives. In China, the Ministry of Agriculture and Rural Affairs sets standards for feed quality and safety. Navigating these disparate regional requirements is a critical competency for suppliers.
Market Dynamics
The central dynamic shaping the feed pigments market is the tension between consumer-driven demand for natural coloration in animal products and the stringent, costly regulatory frameworks governing additive safety and efficacy. This conflict forces producers to navigate complex approval processes while investing in alternative sourcing to meet end-market preferences.
Growth Catalysts
- Aquaculture Sector Expansion:Intensifying production in the global aquaculture industry, particularly for salmonids and crustaceans, directly increases the need for carotenoids like astaxanthin to achieve desired flesh coloration demanded by consumers.
- Chinese Feed Standardization:Policies from China's Ministry of Agriculture and Rural Affairs mandating higher standards for animal feed quality are compelling large-scale producers to use standardized, high-purity pigments to ensure product consistency and safety.
- Natural Pigment Preference:A pronounced consumer shift towards clean-label and natural food products is creating a strong pull for pigments derived from sources like paprika, marigold, and microalgae over their synthetic counterparts in the food chain.
Market Restraints
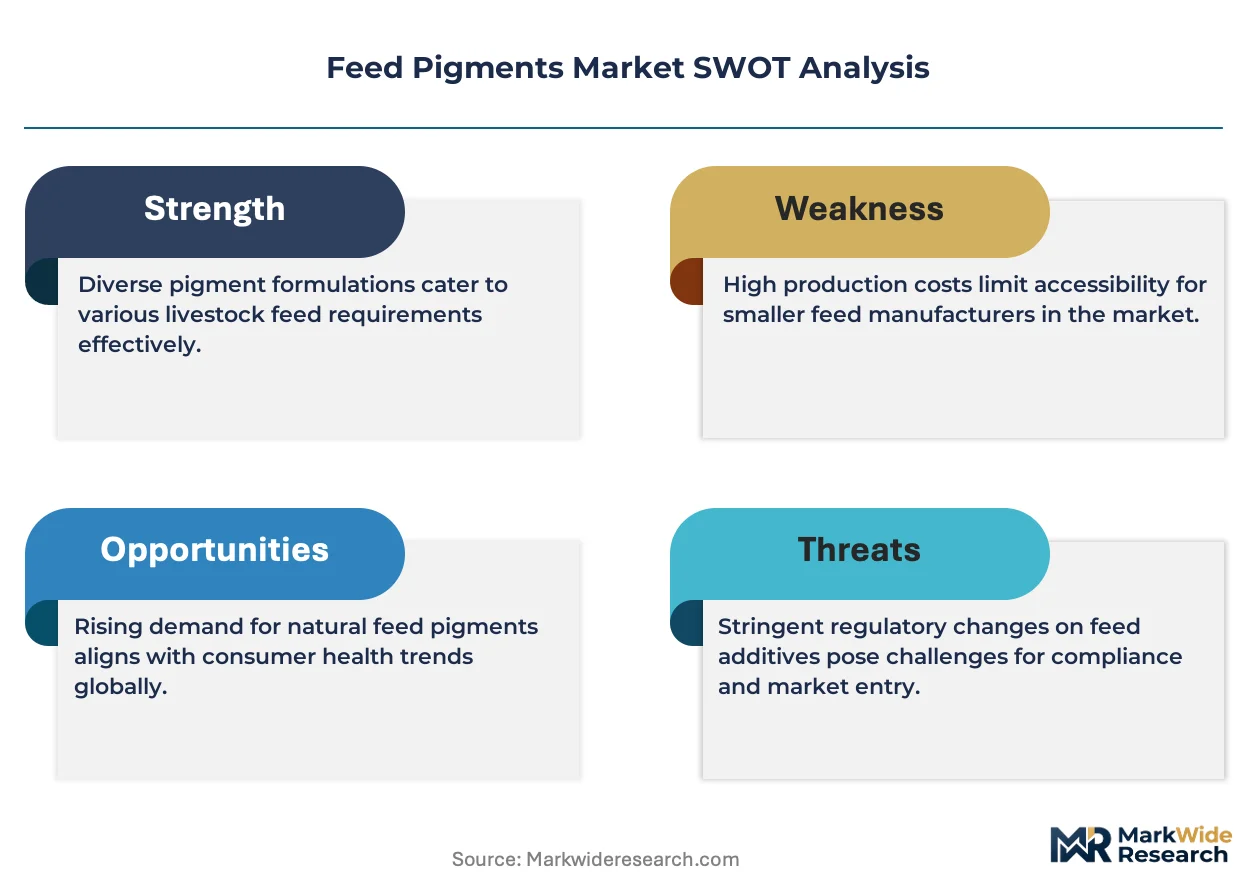
- Cost Disparity:The production costs for natural pigments, involving agricultural sourcing and complex extraction, remain significantly higher than for chemically synthesized carotenoids, limiting their adoption in cost-sensitive segments of the livestock industry.
- Regulatory Approval Hurdles:The rigorous and lengthy approval processes enforced by bodies like the European Food Safety Authority (EFSA) and the U.S. FDA for new feed additives create substantial barriers to market entry and slow down innovation.
- Feedstock Volatility:Supply of natural pigment sources, such as marigold flowers or specific algae strains, is subject to agricultural risks including weather events and crop diseases, leading to price volatility and supply chain instability.
Strategic Opportunities
- Pet Food Formulation:The premium pet food segment represents an underpenetrated market for natural pigments, where owners' willingness to pay for high-quality, visually appealing products creates an opportunity for specialized color formulations.
- Microalgae Cultivation:Advances in bioreactor technology and algae strain development offer a path to create a scalable, consistent, and sustainable supply of high-value carotenoids like astaxanthin, independent of agricultural or chemical synthesis pathways.
- Emerging Aquaculture Hubs:Targeting developing aquaculture markets in Southeast Asia and Latin America provides an opportunity to establish market position as these regions professionalize their production and adopt higher feed quality standards.
Industry Challenges
- Cross-Regional Compliance:Suppliers face significant operational complexity and cost in managing product dossiers to meet the disparate and evolving regulatory requirements of the EFSA in Europe, the FDA in the United States, and agricultural ministries in Asia.
- Natural Source Inconsistency:A key technical challenge is maintaining consistent color expression and bioavailability from natural pigment sources, which can vary significantly based on crop variety, harvest time, and processing methods.
- Sourcing Chain Transition:Shifting production from established synthetic chemical supply chains to agricultural or biotechnological sourcing requires substantial capital investment and the development of new logistical and quality assurance competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Pigments Market |
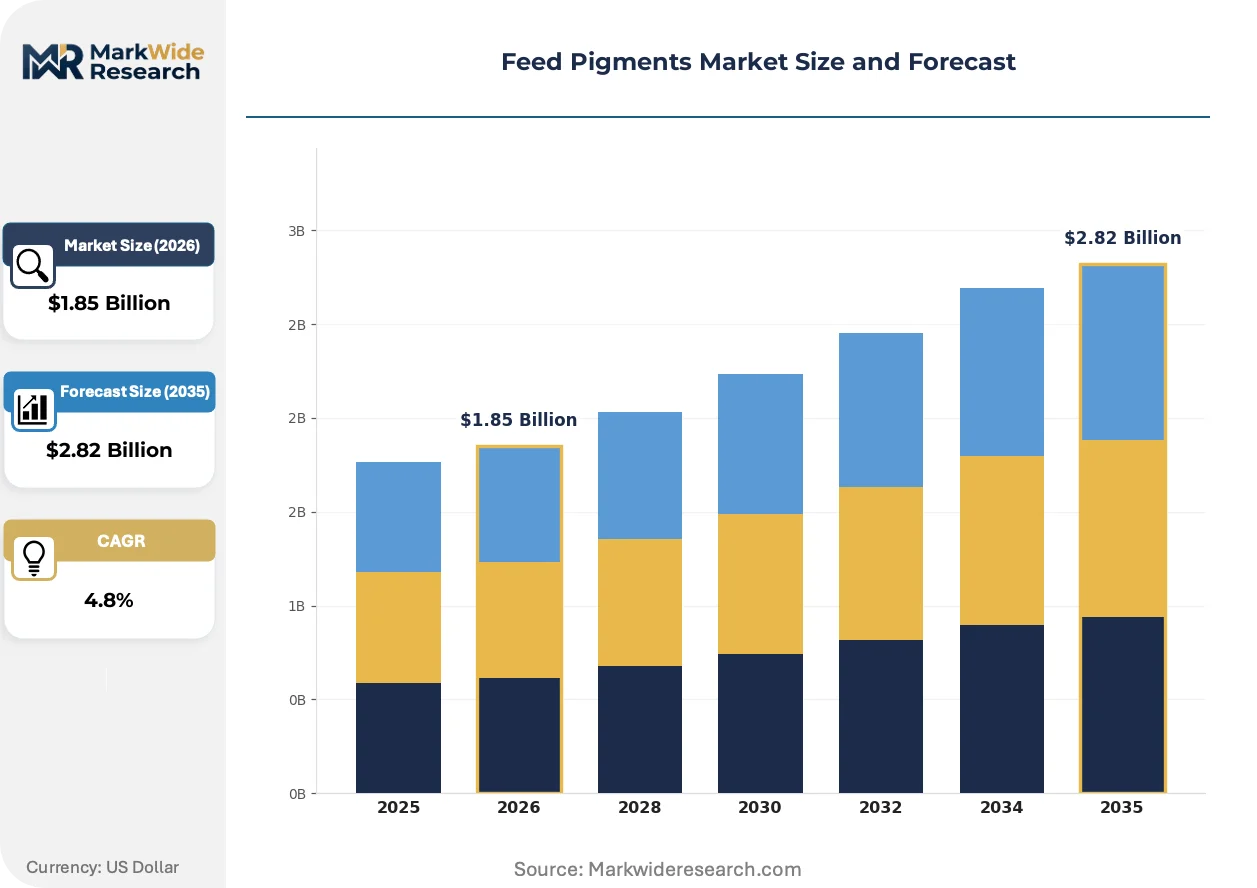
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carotenoids, Spirulina, Beetroot Red, Anthocyanins Application: Poultry, Swine, Aquaculture, Ruminants Source: Natural, Synthetic, Organic, Inorganic Form: Powder, Liquid, Granules, Emulsions |
| Companies Covered | Novus International, Inc., Archer-Daniels-Midland Company, BASF SE, Zhejiang NHU Co., Ltd., Cargill Incorporated, DSM-Firmenich AG, Synthite Industries Ltd., Adisseo, Kemin Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Pigments Market Strategic Shifts & Innovations
The market's evolution is defined by a dual pursuit of scientific validation and cost-efficient scale. This involves both enhancing the bioavailability of natural extracts and developing novel synthesis pathways that mimic nature while meeting the economic realities of large-scale animal production.
Fermentation-derived carotenoids are a significant technological development, producing nature-identical pigments via microbial processes. Large-scale poultry and aquaculture operators are adopting these solutions to satisfy consumer demand for non-synthetic ingredients without the price volatility of agricultural extracts. This technology is hybridizing the supply chain, creating a new category that blends the cost structure of synthesis with the marketing appeal of natural sources.
Regulatory scrutiny from the European Food Safety Authority (EFSA) is actively influencing product development through its systematic re-evaluation of all authorized feed additives. This process requires manufacturers to submit updated safety and efficacy data, increasing compliance costs significantly. Pigment producers, especially those offering synthetic carotenoids like canthaxanthin, are most affected, forcing investment in new toxicological studies or a strategic pivot toward natural alternatives.
Buying patterns are evolving from transactional ingredient purchases to integrated service models. This change disrupts the role of traditional distributors, as large livestock producers increasingly favor comprehensive nutrition contracts that bundle pigments with other additives and technical support. This trend is most pronounced in the consolidated swine and poultry industries of North America and China, where operators seek holistic solutions to optimize feed conversion and final product quality.
Feed Pigments Market Segmentation
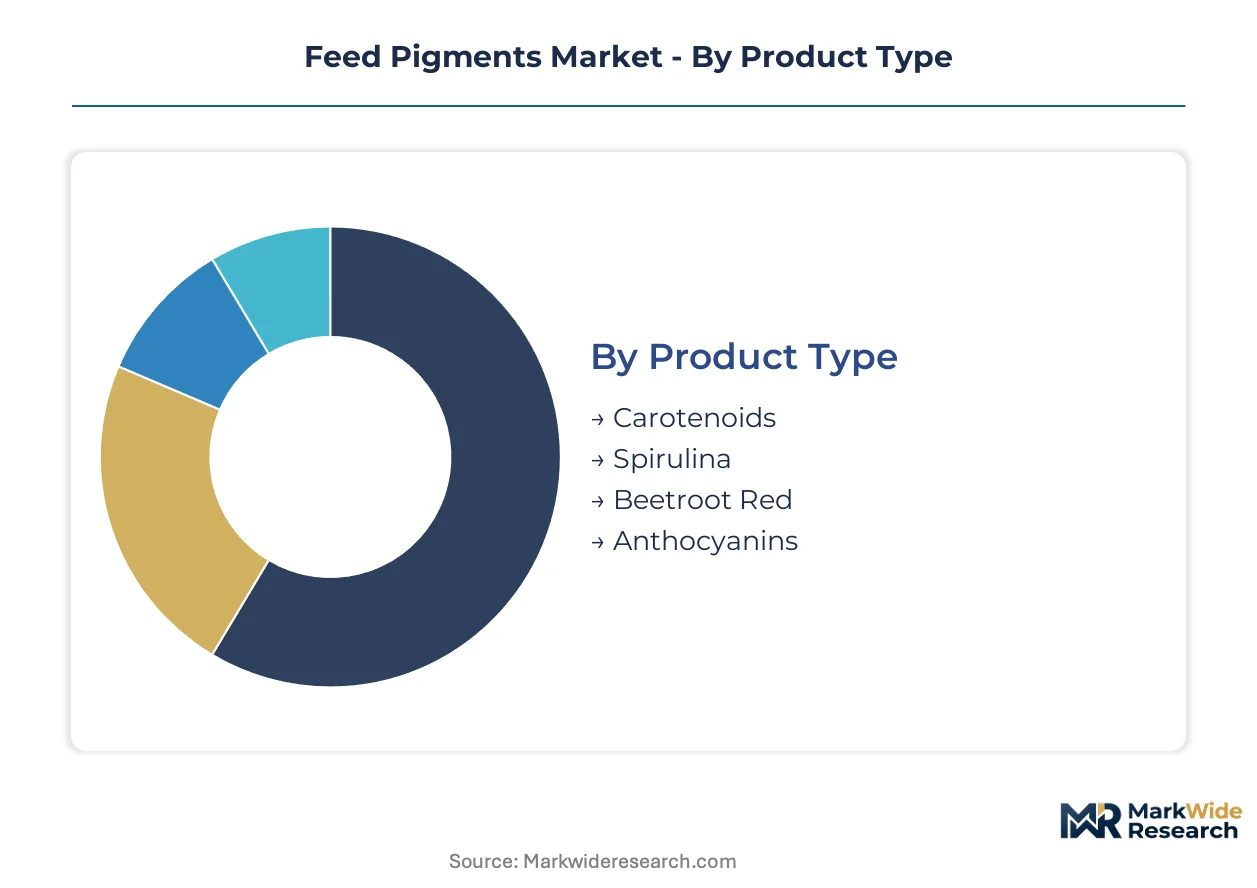
Understanding the varied applications and compositions of feed pigments is crucial for navigating the market's complexities. This segmentation highlights the distinct product types, their end-use applications, the sources from which they are derived, and their physical forms, each influencing market dynamics and supplier strategies.
Product Type:
The use-case spectrum for feed pigments ranges from enhancing visual appeal in animal products to providing nutritional benefits, driving demand for specific chemical compounds.
- Carotenoids:These lipid-soluble organic pigments, including astaxanthin and canthaxanthin, are widely utilized for imparting yellow, orange, and red hues. Demand concentrates in the aquaculture sector for salmon and shrimp coloration and in poultry for egg yolk pigmentation, driven by consumer preference for vibrant color.
- Spirulina:A biomass derived from blue-green algae, Spirulina contains phycocyanin and other natural pigments that provide blue and green coloration. Its demand is increasing in natural and organic feed formulations, particularly for poultry and aquaculture, due to its clean-label appeal and protein content.
- Beetroot Red:This natural food coloring, primarily betanin, produces red to purplish-red shades in feed applications. It finds niche applications in pet food and specialty livestock diets where natural, non-synthetic coloring is preferred.
- Anthocyanins:These water-soluble flavonoid pigments create red, purple, and blue colors, derived from fruits and vegetables. They are explored for natural coloration in poultry and aquaculture, offering antioxidant properties alongside visual enhancement.
The dominant share belongs to Carotenoids, while Spirulina is closing the gap fastest.
Application:
The diversity of animal nutrition applications dictates the specific types and volumes of feed pigments required to meet distinct production goals and consumer expectations.
- Poultry:This segment primarily uses pigments like lutein and canthaxanthin to enhance the yellow and orange coloration of egg yolks and broiler skin. Consumer preferences in countries like China and the United States for specific yolk color drive consistent high-volume demand.
- Aquaculture:Astaxanthin and canthaxanthin are critical in this sector for coloring the flesh of salmonids and crustaceans, mimicking natural diets. Intensifying global aquaculture production, particularly in Norway and Chile, directly correlates with increased pigment consumption.
- Swine:Pigments in swine feed are less about direct tissue coloration and more about overall animal health and subtle visual appeal in certain niche markets. They contribute to general animal well-being and feed palatability.
- Ruminants:Pigment use in cattle and other ruminants is minimal, primarily focused on specific health benefits or very specialized dairy products. These applications are less about aesthetic enhancement of the final product.
Poultry consumption drives substantial demand, while aquaculture presents a significant expansion trajectory.
Source:
The origin and processing methods of feed pigments significantly influence their cost, regulatory approval pathways, and market acceptance among diverse consumer bases.
- Natural:These pigments are extracted from botanical sources such as marigold petals, paprika, and microalgae, or derived through fermentation processes. The shift towards clean-label products in Europe and North America is propelling demand for natural alternatives despite their higher production costs.
- Synthetic:Chemically manufactured pigments, including synthetic astaxanthin and canthaxanthin, offer consistent quality and lower production costs. They remain a staple in conventional feed formulations, particularly in cost-sensitive markets and large-scale operations.
- Organic:Derived from organic-certified natural sources, these pigments adhere to strict organic farming and processing standards. They cater to the premium segment of the market, aligning with the stringent requirements of organic animal farming in regions like Germany and France.
- Inorganic:This category includes mineral-based colorants, which are rarely used directly for aesthetic purposes in feed pigments due to safety concerns and regulatory restrictions. Their application is highly limited and specialized.
Natural sources are gaining preference due to consumer demand, but synthetic options maintain a strong market presence for cost efficiency.
Form:
Customer operational requirements dictate the physical presentation of feed pigments, influencing handling, storage, and dosage accuracy within feed mills and on farms.
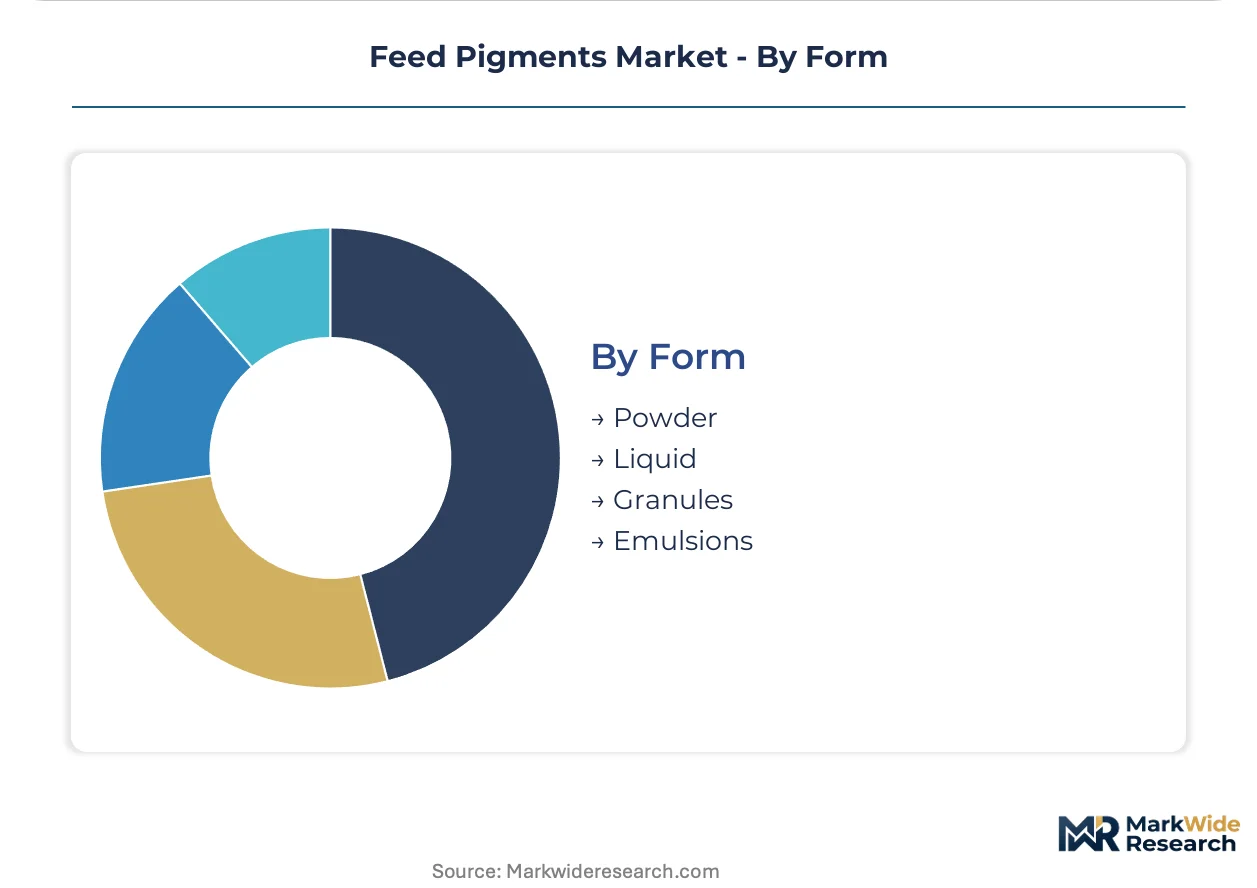
- Powder:This is the most common form, offering ease of mixing into dry feed formulations and cost-effective transportation. Powdered pigments are widely adopted across poultry and swine operations due to their simple integration into existing feed production lines.
- Liquid:Liquid pigments provide advantages in precise dosing and homogeneous dispersion, especially in liquid feed supplements or spray applications. Their use is growing in advanced aquaculture systems and specialized pet food manufacturing for enhanced bioavailability.
- Granules:Granular forms reduce dust, improve flowability, and minimize segregation during feed mixing and handling. They offer a good balance between ease of use and stability, particularly in larger-scale feed production.
- Emulsions:Pigment emulsions enhance bioavailability and stability, especially for fat-soluble carotenoids, by improving their dispersion in aqueous environments. These are often used in high-value applications where maximum absorption is critical, such as specific fish feeds.
Powder forms remain the standard for ease of handling, with liquid and emulsion formats seeing increased adoption for precision and bioavailability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global feed pigments market exhibits a complex trade dynamic, where production centers often export specialized ingredients to regions with high demand for animal protein and specific coloration requirements. This global movement of feed additives reflects diverse regulatory environments and consumer preferences across continents.
China
China's substantial demand for feed pigments stems from its large-scale swine and poultry farming operations, which require consistent product quality and appearance. The Ministry of Agriculture and Rural Affairs mandates higher feed quality standards, compelling producers to use standardized, high-purity pigments. Major feed production hubs in the Yangtze River Delta and Pearl River Delta drive significant pigment consumption.
United States
Consumer preferences for specific egg yolk and broiler skin coloration drive demand for feed pigments in the United States poultry sector. The U.S. Food and Drug Administration (FDA) maintains stringent approval processes for feed additives, influencing product formulation and market access. Large agricultural states like Iowa and North Carolina, with extensive poultry and swine operations, represent key consumption areas.
Norway
Norway's prominent aquaculture industry, particularly salmon farming, fuels high demand for astaxanthin and canthaxanthin to achieve desired flesh coloration. European Food Safety Authority (EFSA) guidelines on feed additives impact pigment selection and usage across the region. The coastal regions, home to numerous salmon farms and processing facilities, are primary pigment end-users.
Brazil
Brazil's vast livestock and emerging aquaculture sectors represent a significant growth trajectory for feed pigments, especially for export-oriented meat and fish products. The country's agricultural policies support large-scale animal production, creating consistent demand for feed additives. States like Mato Grosso and Paraná, central to Brazil's agricultural output, consume substantial volumes of feed ingredients.
Germany
Germany's market for feed pigments is characterized by a strong consumer preference for natural and organic products, influencing demand towards plant-derived and fermentation-based solutions. The European Food Safety Authority (EFSA) rigorous re-evaluation process for feed additives impacts product availability and innovation. Bavaria and North Rhine-Westphalia, with their advanced animal nutrition industries, are key centers for pigment application.
Feed Pigments Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing essential ingredients to a diverse animal nutrition sector. The feed pigments market features a tiered structure, with large chemical companies offering synthetic options and specialized firms focusing on natural or fermentation-derived solutions. Strategic partnerships and portfolio diversification represent dominant competitive moves as companies seek to expand their market reach and product offerings.
Within the established players leveraging extensive chemical synthesis capabilities, Germany-based BASF SE exemplifies a long-standing presence with a broad product portfolio. Cargill Incorporated, a U.S.-based agricultural giant, occupies a position as an integrator, bundling pigments into its broader animal nutrition services. Kemin Industries, Inc., also from the U.S., differentiates its offerings by focusing on natural pigment solutions, aligning with consumer demand for clean-label products.
| Leading Market Players |
|---|
| Novus International, Inc. |
| Archer-Daniels-Midland Company |
| BASF SE |
| Zhejiang NHU Co., Ltd. |
| Cargill Incorporated |
| DSM-Firmenich AG |
| Synthite Industries Ltd. |
| Adisseo |
| Kemin Industries, Inc. |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta's concentrated feed production capacity significantly influences downstream pricing power for feed pigments, particularly for synthetic variants. This regional dominance creates a complex interplay between supply volume and market price stability.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for feed pigments. Price differentiation stems from product purity standards and the volume scale of purchases. Pricing pressure intensifies due to consolidation among large animal nutrition integrators. Large consolidated swine and poultry operators are highly price-sensitive, while premium pet food manufacturers prioritize quality over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming more common for larger buyers. Geographic supply concentrates in China for synthetic carotenoids and in Southeast Asia for natural botanical extracts. Raw material dependencies include petrochemicals for synthetic production and marigold flowers or microalgae for natural sources. Feedstock volatility for natural pigment sources presents a structural supply chain risk. Distribution increasingly integrates into comprehensive nutrition contracts offered by large integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits a significant buyer-power shift, driven by consolidation among large animal nutrition integrators like Cargill Incorporated. This trend compels suppliers to adapt their offerings and go-to-market strategies to remain competitive.
For Market Incumbents: Entrench existing market positions by investing in fermentation-derived carotenoids, offering nature-identical solutions that appeal to evolving consumer preferences. Expand integrated service models, bundling pigments with other feed additives and technical support to counteract margin pressure from large, consolidated buyers. Invest in robust certification processes to address increasing regulatory scrutiny from the European Food Safety Authority (EFSA) and the U.S. Food and Drug Administration (FDA). For New Entrants and Emerging Players: Pursue niche opportunities within the premium pet food segment, where natural pigments command higher value due to owner willingness to pay. Target emerging aquaculture hubs in Southeast Asia and Latin America with specialized astaxanthin formulations. A strong go-to-market angle involves emphasizing product traceability, clean-label appeal, and sustainable sourcing practices, differentiating from synthetic alternatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized natural pigment producers with proprietary microalgae cultivation or fermentation intellectual property. Long-term viability rests on scalable, cost-effective bio-identical production methods that meet evolving consumer and regulatory demands for natural ingredients. The signal to watch is successful commercialization of advanced bioreactor technologies for consistent astaxanthin yields, indicating a shift in production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Fermentation | Secures scalable supply of nature-identical pigments, reducing reliance on volatile agricultural sources. |
| Integrated Service Model Development | Bundles feed pigments with broader nutrition solutions, enhancing customer stickiness and value proposition. |
| Certification Investment for Natural Products | Validates product quality and safety, crucial for market access in regions with stringent EFSA guidelines. |
| Targeted Acquisition of Microalgae IP | Gains access to sustainable, high-value astaxanthin production methods for premium aquaculture markets. |
| Geographic Expansion into Emerging Aquaculture | Establishes early market presence in high-growth regions like Southeast Asia, aligning with professionalization trends. |
Research Approach
Desk research of agricultural ministry reports, regulatory publications from the U.S. Food and Drug Administration (FDA) and European Food Safety Authority (EFSA), and company annual reports preceded structured interviews with feed manufacturers, aquaculture specialists, poultry farm managers, and regulatory experts. This approach combined primary insights with secondary validation, employing both bottom-up and top-down triangulation for robust data synthesis.
Assumptions regarding global animal protein demand and feed quality standards were held fixed across the analysis window, while variations in regional regulatory stringency were modeled. The analytical framework segmented the market by product type, application, source, form, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected demand drivers, incorporating aquaculture production forecasts and Chinese feed quality mandates.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or agricultural commodity prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and consumer preference evolution. Agricultural feedstock volatility, new regulatory approvals, and geopolitical trade shifts represent specific risk factors that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Global Crop Oil Concentrates Market