
 Africa Feed Antioxidants Market | 2026-2036
Africa Feed Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Feed Antioxidants Market Outlook
South Africa's tightened mycotoxin regulations for animal feed is expanding the compliance burden for imported and domestically blended antioxidants. Cargill leverages its coastal crushing and blending infrastructure near Durban to pre-mix antioxidant packages for regional distribution. BASF SE anchors the synthetic segment through its ethoxyquin and BHT supply relationships with large South African feed compounders. Kemin Industries differentiates via natural antioxidant formulations targeting premium poultry export operations in Zambia and Botswana.
Feed antioxidants are chemical or botanical compounds added to animal feed to inhibit lipid oxidation, preserve vitamin stability, and extend storage life in high-temperature, high-humidity environments; synthetic variants such as BHT and ethoxyquin typically function at inclusion rates of 100–200 ppm, while natural alternatives employ mixed tocopherols and rosemary extracts at higher dosages to achieve equivalent oxidative stability. The poultry application segment leads absolute volume as intensive broiler operations in Nigeria and Egypt prioritize feed conversion efficiency, though natural antioxidants represent the fastest-growing product category as Moroccan and Kenyan exporters seek EU-aligned residue profiles. Powder formulations still dominate logistics economics across poorly paved distribution corridors, yet liquid blends are gaining traction among automated feed mills in South Africa's Gauteng province.
South Africa's Department of Agriculture enforces feed safety standards that effectively mandate antioxidant certification for cross-border shipments into SACU member states. The country's national agricultural regulator coordinates with the Fertilizer, Farm Feeds, Seeds and Remedies Act inspectors to test for unauthorized ethoxyquin levels at ports of entry. Nigeria's National Agency for Food and Drug Administration and Control operates a parallel but less resourced framework, creating a compliance gap that informal feed blenders exploit. Stakeholders must monitor whether East African Community harmonization moves Kenya, Tanzania, and Uganda toward mutual recognition of antioxidant additive approvals or perpetuates fragmented national registration requirements.
Market Dynamics
Broiler poultry operations across Nigeria and South Africa are accelerating antioxidant adoption to combat feed spoilage in hot climates, while regulatory tightening around mycotoxin control is forcing feed manufacturers toward certified antioxidant blends.
Growth Catalysts
- South Africa's tightened mycotoxin regulations:The Department of Agriculture, Land Reform and Rural Development now mandates antioxidant certification for cross-border shipments, pushing domestic blenders toward compliant formulations.
- Commercial poultry belt consolidation:Integrated farms around Lagos and Ibadan are vertically consolidating feed sourcing, creating concentrated demand for bulk antioxidant procurement.
- Natural antioxidant R&D:Mixed tocopherols and rosemary extracts are achieving oxidative stability parity with synthetic alternatives, opening premium export channels to EU-aligned buyers.
Market Restraints
- Input cost volatility:Petrochemical feedstock fluctuations directly impact synthetic antioxidant production economics, squeezing margin predictability for BHT and ethoxyquin blenders.
- Supply concentration risk:Coastal crushing and blending infrastructure near Durban controls regional pre-mix distribution, creating single-point vulnerability for inland feed mills.
- Regulatory friction:Nigeria's National Agency for Food and Drug Administration and Control operates a less resourced framework than South African counterparts, enabling informal feed blenders to undercut certified suppliers.
Strategic Opportunities
- East African Community harmonization:Kenya, Tanzania, and Uganda may move toward mutual recognition of antioxidant additive approvals, collapsing fragmented national registration barriers.
- Liquid blend penetration:Automated feed mills in South Africa's Gauteng province are shifting from powder to liquid antioxidant delivery systems, opening equipment upgrade revenue streams.
- Zambian and Botswanan export poultry:Premium natural antioxidant formulations targeting residue-conscious EU buyers are capturing price premiums in landlocked southern African markets.
Industry Challenges
- Analytical certification timelines:Fertilizer, Farm Feeds, Seeds and Remedies Act inspectors require extended testing protocols for unauthorized ethoxyquin levels at ports of entry, delaying product release.
- Distribution infrastructure gaps:Poorly paved corridors across the region favor powder formulations despite their inferior handling characteristics in automated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Feed Antioxidants Market |
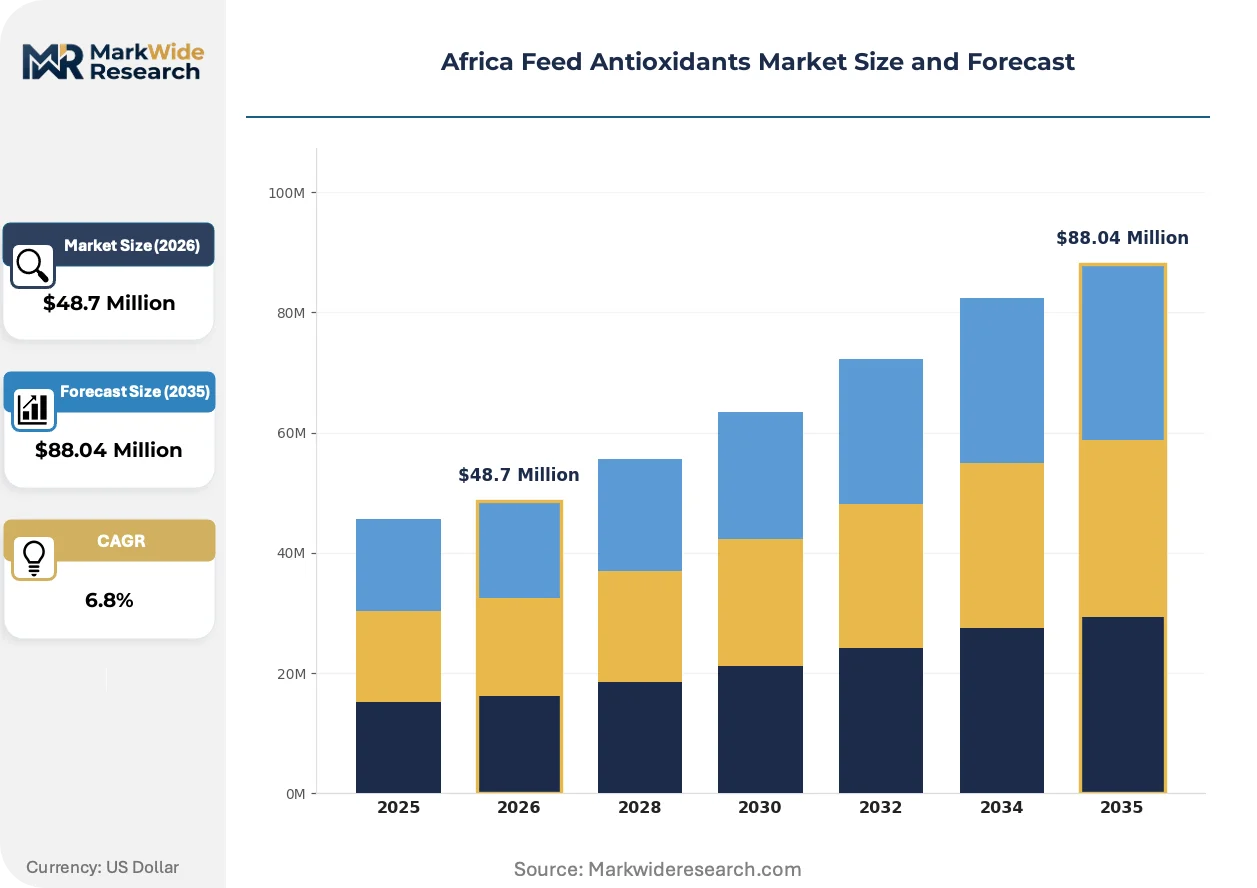
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BHA, BHT, Ethoxyquin, Natural Antioxidants Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granule, Blends End User: Farmers, Feed Manufacturers, Livestock Producers, Feed Distributors |
| Companies Covered | Cargill, DSM, Alltech, Kemin Industries, Archer Daniels Midland Company, Nutreco NV, Adisseo, BASF SE, Novus International, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Feed Antioxidants Market Strategic Shifts
Feed antioxidant technology is bifurcating between synthetic efficiency and natural compliance, with formulation science and regulatory alignment driving competitive differentiation.
Encapsulated antioxidant delivery systems are absorbing moisture and heat stress before reaching active sites in feed matrices. Large South African feed compounders are piloting these systems in coastal storage facilities. This technology is absorbing spoilage losses that previously reached 8-12% in high-humidity zones.
REACH-aligned residue standards are penetrating African export supply chains as Moroccan and Kenyan poultry operations seek EU market access. Domestic regulators are importing testing protocols from European counterparts to accelerate approval reciprocity. Natural tocopherol blends are displacing ethoxyquin in premium formulations destined for European supermarkets.
Integrated farms are consolidating antioxidant procurement through captive blending operations rather than merchant suppliers. Commercial poultry operations in Nigeria's Lagos-Ibadan corridor are installing in-house mixing equipment. This concentration is compressing spot market volumes and favoring long-term supply contracts with certified additive producers.
Africa Feed Antioxidants Market Segmentation
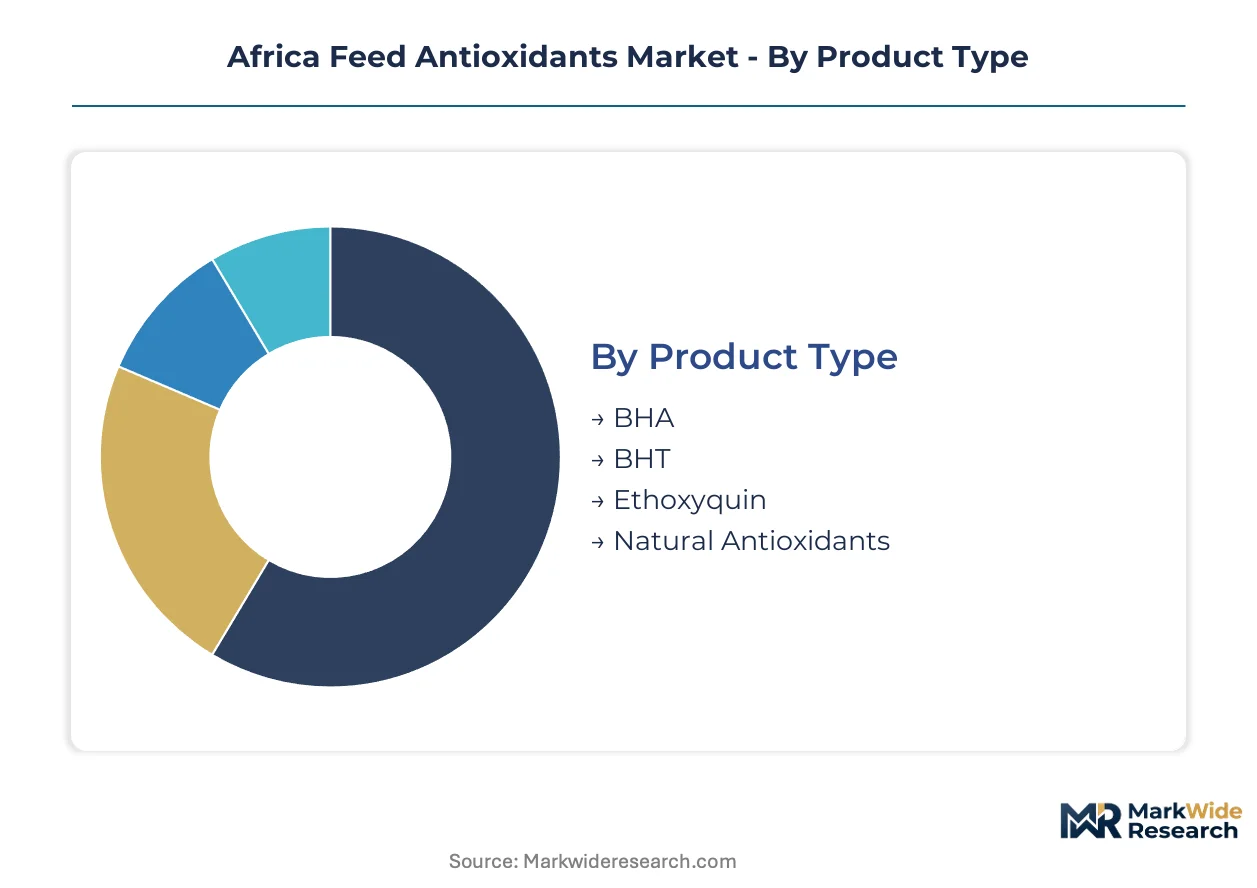
Feed antioxidant procurement in Africa fragments across regulatory thresholds, with certified synthetic formulations commanding premium pricing in South Africa while natural alternatives penetrate EU-exporting operations in Morocco and Kenya. Segmentation discipline separates volume-driven commodity buyers from residue-conscious premium purchasers.
Product Type:
South Africa's Department of Agriculture, Land Reform and Rural Development mandates antioxidant certification tiers that stratify synthetic versus natural product adoption across cross-border shipments into SACU member states.
- Ethoxyquin:Synthetic quinoline-based antioxidant functioning at 100–150 ppm inclusion rates for lipid stabilization in high-temperature storage. Demand concentrates among large South African feed compounders supplying broiler operations in Gauteng province, constrained by REACH-aligned residue testing at Durban port facilities.
- Natural Antioxidants:Mixed tocopherols and rosemary extract formulations requiring 200–400 ppm dosages to match synthetic oxidative stability. Moroccan and Kenyan poultry exporters targeting EU supermarkets are accelerating procurement, driven by EFSA-aligned maximum residue limits that exclude ethoxyquin from premium supply chains.
- BHT:Butylated hydroxytoluene synthetic antioxidant deployed in cost-sensitive bulk feed applications across Nigeria's commercial poultry belt.
- BHA:Butylated hydroxyanisole variant blended with BHT for synergistic antioxidant performance in ruminant feed formulations.
Leading the category by volume: Ethoxyquin. Growing fastest: Natural Antioxidants.
Application:
Cost tier segmentation separates intensive commercial operations investing in certified antioxidant programs from smallholder systems relying on informal feed sourcing.
- Poultry:Broiler operations across Nigeria's Lagos-Ibadan corridor and South Africa's Mpumalanga province prioritize feed conversion efficiency through antioxidant-stabilized lipid matrices. Integrated farms are vertically consolidating procurement through captive blending operations rather than merchant suppliers.
- Ruminants:Cattle feedlot operations in Botswana and Namibia utilize antioxidant-protected fat supplements to maintain energy density in finishing rations, with powder formulations dominating poorly paved distribution corridors.
- Swine:Commercial pig operations in South Africa's Western Cape deploy synthetic antioxidant blends to preserve vitamin stability in high-moisture complete feeds.
- Aquaculture:Tilapia and catfish feed producers in Egypt incorporate ethoxyquin to inhibit oxidation of fishmeal-based formulations in Nile Delta humidity conditions.
Dominating procurement spend: Poultry. Expanding most quickly: Ruminants.
Form:
Supply concentration around Durban's coastal crushing infrastructure shapes powder versus liquid availability across inland distribution networks.
- Powder:Dry antioxidant concentrates dominate logistics economics across Africa's poorly paved distribution corridors, preferred by manual mixing operations in Nigeria's informal feed sector.
- Liquid:Automated delivery systems are gaining traction among South African feed mills in Gauteng province, enabling precise dosing and reduced dust exposure. Equipment upgrade requirements create barrier to adoption for smaller compounders.
- Granule:Free-flowing particulate formulations improve handling characteristics in high-humidity coastal storage facilities near Mombasa and Dar es Salaam.
- Blends:Pre-mixed antioxidant packages combining synthetic and natural components are pre-mixed at Cargill's Durban facility for regional distribution to SACU markets.
Commanding current volume: Powder. Steepest expansion trajectory: Liquid.
End User:
Customer type determines certification burden intensity, with feed manufacturers facing full Fertilizer, Farm Feeds, Seeds and Remedies Act compliance while farmers operate in regulatory gaps.
- Feed Manufacturers:Large South African compounders in KwaZulu-Natal and Gauteng absorb full analytical certification timelines for cross-border antioxidant shipments, creating compliance moats against informal competitors.
- Farmers:Smallholder poultry producers in Nigeria's Ogun State purchase antioxidants through informal channels, exploiting gaps in NAFDAC enforcement capacity relative to South African regulatory frameworks.
- Livestock Producers:Integrated commercial operations in Zambia's Copperbelt region are installing in-house mixing equipment to consolidate antioxidant procurement through long-term supply contracts.
- Feed Distributors:Regional traders in East Africa face fragmented national registration requirements across Kenya, Tanzania, and Uganda pending potential EAC harmonization.
Capturing largest procurement volumes: Feed Manufacturers. Gaining share fastest: Livestock Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along Africa's coastal corridors concentrate feed antioxidant demand, with bonded warehousing near Durban and Lagos ports enabling duty-efficient importation of synthetic additive packages.
South Africa
The Department of Agriculture, Land Reform and Rural Development enforces Fertilizer, Farm Feeds, Seeds and Remedies Act compliance for all cross-border antioxidant shipments into SACU member states. Gauteng province hosts automated feed mills shifting from powder to liquid delivery systems. KwaZulu-Natal's coastal crushing infrastructure near Durban pre-mixes antioxidant packages for regional distribution.
Nigeria
Commercial poultry operations around Lagos and Ibadan are vertically consolidating feed sourcing through captive blending operations. The National Agency for Food and Drug Administration and Control operates a less resourced enforcement framework than South African counterparts. Ogun State's smallholder poultry belt purchases antioxidants through informal channels, exploiting regulatory gaps.
Egypt
Tilapia and catfish feed producers in the Nile Delta incorporate ethoxyquin to inhibit oxidation of fishmeal-based formulations under persistent humidity conditions. The country's national agricultural regulator coordinates with port authorities to test for unauthorized additive levels. Cairo-Alexandria corridor feed compounders serve the aquaculture concentration.
Morocco
Poultry exporters targeting EU supermarkets accelerate procurement of natural tocopherol blends to meet EFSA-aligned maximum residue limits. Domestic regulators import testing protocols from European counterparts to accelerate approval reciprocity. Casablanca-Rabat industrial zone feed manufacturers lead the natural antioxidant transition.
Kenya
Premium poultry export operations seek REACH-aligned residue profiles, driving mixed tocopherol and rosemary extract adoption. The national agricultural regulator faces fragmented registration requirements pending potential East African Community harmonization. Nairobi-Nakuru corridor integrated farms are installing in-house mixing equipment for long-term supply contracts.
Africa Feed Antioxidants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the African feed antioxidant market. Large multinational agribusinesses leverage coastal logistics infrastructure and pre-mixing capabilities to serve regional distribution networks. Three strategic archetypes dominate: petrochemical-derived synthetic suppliers, botanical extract natural formulators, and integrated feed compounders with captive additive blending. Capacity expansion near port facilities and strategic partnerships with national distributors represent the dominant competitive moves.
Among diversified agribusiness conglomerates, Cargill anchors the coastal pre-mixing infrastructure position near Durban. BASF SE exemplifies the petrochemical-derived synthetic antioxidant archetype through established supply relationships with large compounders. Kemin Industries occupies a specialist position within the natural formulation tier, targeting premium export operations in landlocked southern African markets. These three companies represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Cargill |
| DSM |
| Alltech |
| Kemin Industries |
| Archer Daniels Midland Company |
| Nutreco NV |
| Adisseo |
| BASF SE |
| Novus International |
| Others |
Value Chain & Pricing Dynamics
Captive blending operations among Nigeria's integrated poultry farms anchor both supply security and procurement leverage, compressing spot market liquidity while elevating contract-based pricing power for certified additive producers serving formal channels.
Pricing Analysis
Short lead-time premiums for certified antioxidant shipments into SACU member states stratify procurement costs, with Fertilizer, Farm Feeds, Seeds and Remedies Act compliance timelines creating urgency-driven markups. Contract-based long-term offtake dominates formal feed manufacturing, while spot purchases concentrate among Ogun State's smallholder operations. Price differentiation separates REACH-aligned natural formulations from synthetic alternatives, with EU-exporting operations absorbing certification premiums. Cost compression in ethoxyquin supply chains is intensifying because petrochemical feedstock volatility squeezes BHT blenders. Smallholder poultry producers exhibit highest price sensitivity; premium export operations in Zambia and Botswana demonstrate lowest.
Supply Chain Analysis
South Africa's domestic-content mandates through the Department of Agriculture, Land Reform and Rural Development reshape sourcing toward certified local blending capacity. Supply concentrates in South Africa, Nigeria, and Egypt, with coastal crushing infrastructure near Durban and Lagos controlling regional pre-mix distribution. Raw material dependencies draw from petrochemical feedstocks for synthetic antioxidants, botanical extracts for natural alternatives, and vitamin premix carriers. Single-source vulnerability runs through Durban's bonded warehousing facilities, where Cargill's regional pre-mixing creates chokepoint exposure for inland SACU markets. Distribution runs through formal feed compounders in Gauteng and KwaZulu-Natal, informal traders in Nigeria's Ogun State, and aquaculture feed producers in Egypt's Nile Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: South Africa's Fertilizer, Farm Feeds, Seeds and Remedies Act certification requirements erect barrier-to-entry moats that favor incumbent compounders with analytical testing capacity.
For Market Incumbents: To counter informal feed blender encroachment in Nigeria's regulatory gap, deepen backward integration into captive antioxidant storage at coastal facilities and accelerate certification investment for cross-border SACU shipments. Channel control through long-term supply contracts with Zambia's Copperbelt integrated farms reinforces pricing power against spot market volatility. For New Entrants and Emerging Players: Capture white-space in Kenya's premium poultry export corridor by targeting mixed tocopherol formulations for EU-aligned residue profiles, leveraging Nairobi-Nakuru corridor in-house mixing adoption as go-to-market entry point. Morocco's natural antioxidant transition presents parallel penetration opportunity for EFSA-compliant botanical extract suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of certified blending capacity by diversified agribusiness conglomerates seeking coastal logistics control. Long-term viability hinges on regulatory harmonization trajectory across the East African Community. Watch Kenya-Tanzania-Uganda mutual recognition negotiations as inflection signal for regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coastal Storage | Durban and Lagos bonded warehousing secures duty-efficient importation for SACU and Nigerian markets. |
| Natural Formulation Certification | EFSA-aligned mixed tocopherol blends unlock EU supermarket channels for Moroccan and Kenyan exporters. |
| Long-term Supply Agreements | Copperbelt integrated farms in Zambia consolidate procurement through captive blending contracts. |
| Liquid Delivery System Upgrade | Gauteng automated feed mills shift from powder to precise-dosing infrastructure. |
| East African Community Harmonization | Mutual recognition of antioxidant approvals collapses fragmented national registration barriers. |
Study Parameters
Multi-period observation of antioxidant certification timelines, feed mill automation adoption, and cross-border shipment volumes anchored the trend analysis, supplemented by interviews with feed compounder procurement directors, Fertilizer, Farm Feeds, Seeds and Remedies Act compliance officers, poultry farm operations managers, and aquaculture feed formulators. Secondary validation drew from South African Department of Agriculture regulatory filings, Nigerian NAFDAC enforcement records, Egyptian port authority testing protocols, and customs trade data for antioxidant additive imports. Bottom-up volume estimates from individual feed mill capacity and top-down market sizing from national poultry production statistics underwent iterative reconciliation.
Input-output matrices mapped antioxidant inclusion rates by application segment against feed production volumes across the projection horizon. Segmentation dimensions modeled include product type tier, application species, formulation state, and end-user category. CAGRs derived from regression analysis of historical certification adoption curves and regulatory enforcement intensity indices. Industry-specific forecast inputs incorporated petrochemical feedstock price volatility coefficients and EU residue limit alignment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to East African Community harmonization delays, Nigerian regulatory enforcement capacity expansion, and REACH-aligned testing protocol adoption rates. Assumptions reflect current regulatory trajectories and documented feed mill automation investment patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Europe Feed Antibiotics Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market