
 North America Herbicide Market | 2026-2036
North America Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
North America Herbicide Market Insights
Market Context
Specialty vegetable cultivation is expanding across the southeastern United States and Mexico's Sinaloa corridor, intensifying demand for selective chemistries that target broadleaf weeds without crop phytotoxicity. BASF SE leverages its glufosinate-ammonium platform to dominate the non-selective segment in Canadian prairie agriculture. Bayer AG sustains significant R&D intensity through its crop science division, while Corteva Agriscience anchors its position with novel arylpicolinate herbicides targeting resistant weed populations. FMC Corporation differentiates through proprietary diamide formulations that compete in the pre-emergent vegetable segment.
Technical Definition and Segments
North America herbicides comprise synthetic and biological chemical formulations designed to inhibit specific plant enzymes—acetolactate synthase, EPSP synthase, or auxin receptors—at application rates typically measured in grams of active ingredient per hectare, with the primary commercial purpose of protecting yield density in mechanized row-crop and specialty production systems. Selective chemistries lead volume consumption in cereal and oilseed applications where crop-weed differentiation is technically achievable, while non-selective formulations capture margin pools in pre-plant burndown and industrial vegetation management. Liquid emulsifiable concentrates represent the fastest-growing formulation category, driven by compatibility with precision sprayer systems and reduced handler exposure profiles.
Regulatory Framework
The EPA's re-registration review process and Health Canada's PMRA re-evaluation framework jointly determine market access timelines for new active ingredients, with both agencies tightening aquatic toxicity and pollinator exposure standards that shape product label restrictions. Mexico's COFEPRIS alignment with North American Free Trade Agreement successor provisions creates additional synchronization requirements for cross-border formulation distribution. Stakeholders must monitor pending EPA Endangered Species Act consultations, as these biological opinions will impose mandatory spray drift buffers and seasonal application windows that directly constrain operational flexibility across the region.
Market Dynamics
Herbicide resistance evolution in Palmer amaranth and waterhemp populations is forcing growers toward multi-mode-of-action programs and precision application infrastructure, compressing margins for single-chemistry suppliers while elevating integrated weed management service providers.
Growth Catalysts
- EPA re-registration pressure on glyphosate:Accelerating R&D pipelines toward bio-based active ingredients and novel synthetic modes of action. Formulators are prioritizing tank-mix compatibility with biologicals.
- Precision spraying infrastructure:See-and-spray computer vision systems reduce herbicide volume per hectare by targeting individual weeds, creating demand for ultra-low-volume formulations compatible with pulse-width modulation nozzles.
- Resistance management mandates:University extension services and crop consultants in Iowa, Illinois, and Indiana now prescribe mandatory rotation protocols, expanding the addressable market for PPO-inhibitor and HPPD-inhibitor chemistries.
Market Restraints
- Active ingredient supply concentration:Chinese manufacturers control over 70 percent of technical-grade glyphosate and glufosinate production, exposing North American formulators to tariff volatility and ocean freight disruptions.
- Aquatic toxicity thresholds:EPA's tightened 2,4-D and dicamba label restrictions for watershed proximity eliminate spray windows in the Mississippi River basin during critical application periods.
- Biological substitute performance gaps:Bioherbicides derived from Colletotrichum species and pelargonic acid formulations demonstrate inconsistent efficacy under variable moisture, limiting adoption in broadacre corn and soybean systems.
Strategic Opportunities
- Mexico's Sinaloa vegetable corridor:Expanding protected agriculture and drip-irrigated tomato and pepper production creates demand for selective pre-emergent chemistries with short pre-harvest intervals.
- Drone-based spot spraying:Unmanned aerial application platforms enable variable-rate treatment of field edges and terrace backslopes unreachable by ground rigs, opening service revenue streams for aerial applicators.
- Carbon intensity scoring integration:Bayer, Corteva, and FMC are piloting herbicide programs bundled with soil carbon measurement, positioning chemistry choices as qualifying practices for USDA Climate-Smart Commodity grants.
Industry Challenges
- Application technology technician shortage:Precision agriculture dealerships struggle to recruit technicians capable of calibrating PWM nozzle systems and troubleshooting RTK-GPS drift correction, delaying grower adoption of advanced sprayers.
- Label expansion timeline compression:EPA's 24-month average for new use pattern approvals conflicts with 18-month product development cycles, forcing formulators to launch with restricted geographic labels and expand via supplemental registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Herbicide Market |
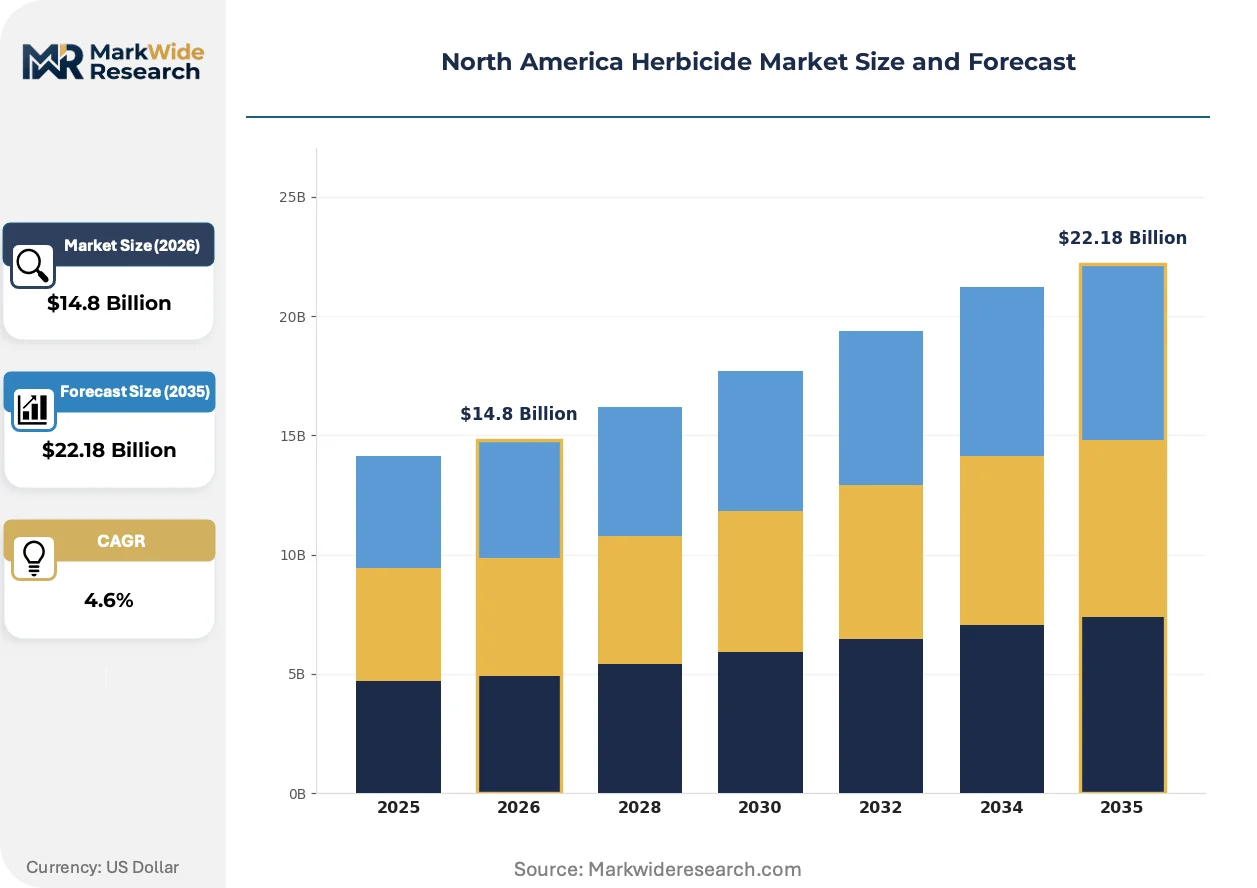
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-selective, Selective, Pre-emergent, Post-emergent Formulation Type: Granular, Liquid, Soluble Concentrate, Emulsifiable Concentrate Application Method: Broadcast Spraying, Spot Treatment, Soil Injection, Handheld Application Crop Type: Cereal Crops, Oilseed Crops, Fruits, Vegetables |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, Nufarm Ltd, Syngenta Group, ADAMA Agricultural Solutions Ltd, American Vanguard Corporation, UPL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Herbicide Market Trends and Innovations
Digital agriculture infrastructure is absorbing herbicide decision-making from calendar-based schedules toward real-time, sensor-driven prescriptions that optimize chemistry selection, rate, and timing at sub-field resolution.
Machine vision-enabled spot sprayers from John Deere and Blue River Technology are absorbing capital investment from broadacre operators in Nebraska and Kansas who face resistant weed pressure. These systems classify plants at 15 miles per hour, triggering solenoid nozzles only when targets are detected. The technology is absorbing volume demand from broadcast applications, compressing total active ingredient consumption per acre while elevating formulation quality requirements for rapid droplet formation.
Health Canada's PMRA is accelerating re-evaluation timelines for Group 2 ALS-inhibitor herbicides, with imazethapyr and thifensulfuron-methyl facing mandatory aquatic toxicity studies. The industrial consequence is withdrawal of minor-use registrations for pulse crops in Saskatchewan and Manitoba. Specialty crop growers are responding by shifting toward Group 14 PPO inhibitors, though these carry higher phytotoxicity risk under cool, wet conditions.
Vegetable processors and organic certifiers are tightening residue tolerance thresholds, forcing conventional growers toward zero-tolerance weed control programs. This behavioral shift is displacing cost-minimization procurement models with outcome-based contracts where applicators guarantee weed-free harvests. The pattern is most visible in California's Central Valley, where tomato and almond processors now specify approved herbicide lists in supply agreements.
North America Herbicide Market Segmentation
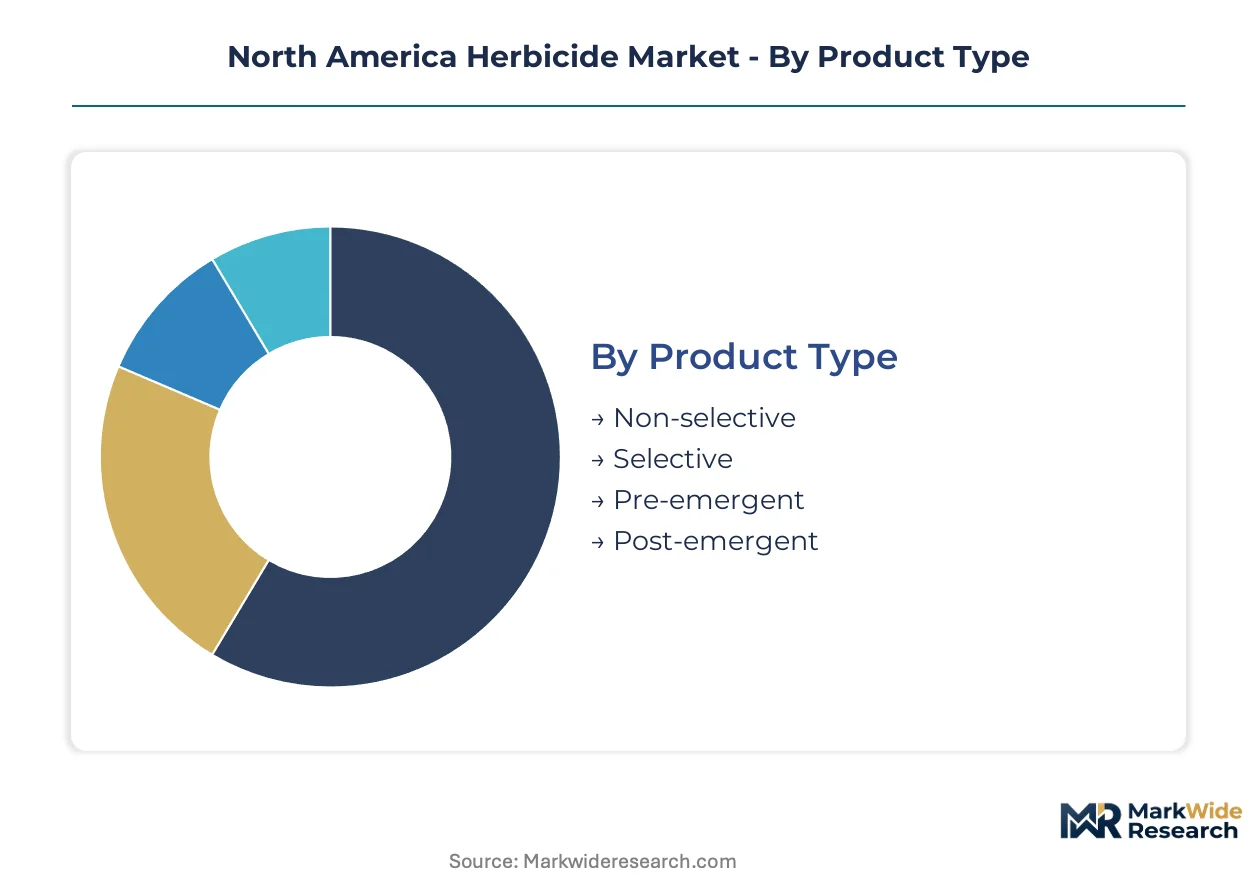
Herbicide segmentation in North America reflects divergent capital requirements across production systems, from precision-enabled specialty vegetable operations to broadacre mechanized row-crop platforms. Understanding these structural divisions enables suppliers to align formulation R&D, distribution infrastructure, and technical service capacity with profit pool concentration.
Product Type:
Non-selective formulations demand the heaviest upfront investment in manufacturing infrastructure due to high-volume active ingredient throughput and dedicated containment systems for glyphosate and glufosinate production.
- Non-selective:These chemistries destroy all vegetation indiscriminately through EPSP synthase inhibition or glutamine synthetase disruption. Demand concentrates in Canadian prairie agriculture for pre-plant burndown and industrial vegetation management along transportation corridors, driven by minimum-tillage adoption that requires chemical fallow programs.
- Selective:Formulations exploit metabolic differences between crops and target weeds, requiring sophisticated synthesis pathways for ALS-inhibitor and auxin-mimic chemistries. Iowa and Illinois corn-soybean rotations absorb the bulk of volume as resistance management protocols mandate rotation between Group 2, Group 4, and Group 15 herbicides.
- Pre-emergent:Soil-applied residual chemistries form chemical barriers at the germination zone. California's Central Valley vegetable producers prioritize these for zero-tolerance weed control in processing tomato and almond orchards.
- Post-emergent:Foliar-active formulations target emerged weeds with contact or systemic action. Texas High Plains cotton growers rely on these for mid-season Palmer amaranth control.
Non-selective herbicides absorb the bulk of installed capacity; selective chemistries are expanding most quickly.
Formulation Type:
Cost tier stratification separates commodity dry formulations from premium liquid systems engineered for precision application compatibility.
- Liquid:Emulsifiable and soluble concentrates dominate commercial value due to compatibility with pulse-width modulation nozzles and see-and-spray computer vision systems. Nebraska and Kansas broadacre operators are absorbing capital investment in these formulations to enable variable-rate application at sub-field resolution.
- Emulsifiable Concentrate:Oil-in-water systems deliver lipophilic active ingredients with reduced handler exposure profiles. Specialty crop consultants in Florida and Georgia citrus groves specify these for compatibility with aerial application platforms.
- Granular:Dry formulations reduce packaging and shipping costs for high-volume commodity herbicides. Home and garden channels in suburban markets absorb significant volume for lawn weed control.
- Soluble Concentrate:Water-based systems dissolve completely without emulsifiers, simplifying tank-mix compatibility with biological adjuvants. Organic transition growers in the Pacific Northwest are testing these for integration with bioherbicide programs.
Liquid formulations command the dominant share of formulation R&D investment; emulsifiable concentrates are climbing the fastest as precision spraying infrastructure spreads.
Application Method:
Volume concentration varies dramatically by method, with broadcast systems consuming multiples of active ingredient per hectare compared to targeted alternatives.
- Broadcast Spraying:Uniform coverage across entire fields remains the default for corn and soybean production in the U.S. Midwest, though volume per hectare is compressing as growers retrofit ground rigs with section control and automatic boom height adjustment.
- Spot Treatment:Targeted application to weed patches or field margins reduces total chemistry use. Drone-based platforms in Mexico's Sinaloa corridor are opening service revenue streams for terrace backslopes unreachable by ground equipment.
- Soil Injection:Subsurface placement places herbicides directly into the root zone, minimizing volatilization and surface runoff concerns. North Dakota sugar beet producers use these systems for pre-emergent Group 15 chemistry placement.
- Handheld Application:Backpack sprayers and wick applicators serve small-scale specialty crop operations and organic transition zones. Urban vegetation management contracts in Texas and Arizona municipalities specify these for right-of-way maintenance.
Broadcast spraying retains the largest installed equipment base; spot treatment is gaining share fastest through unmanned aerial system adoption.
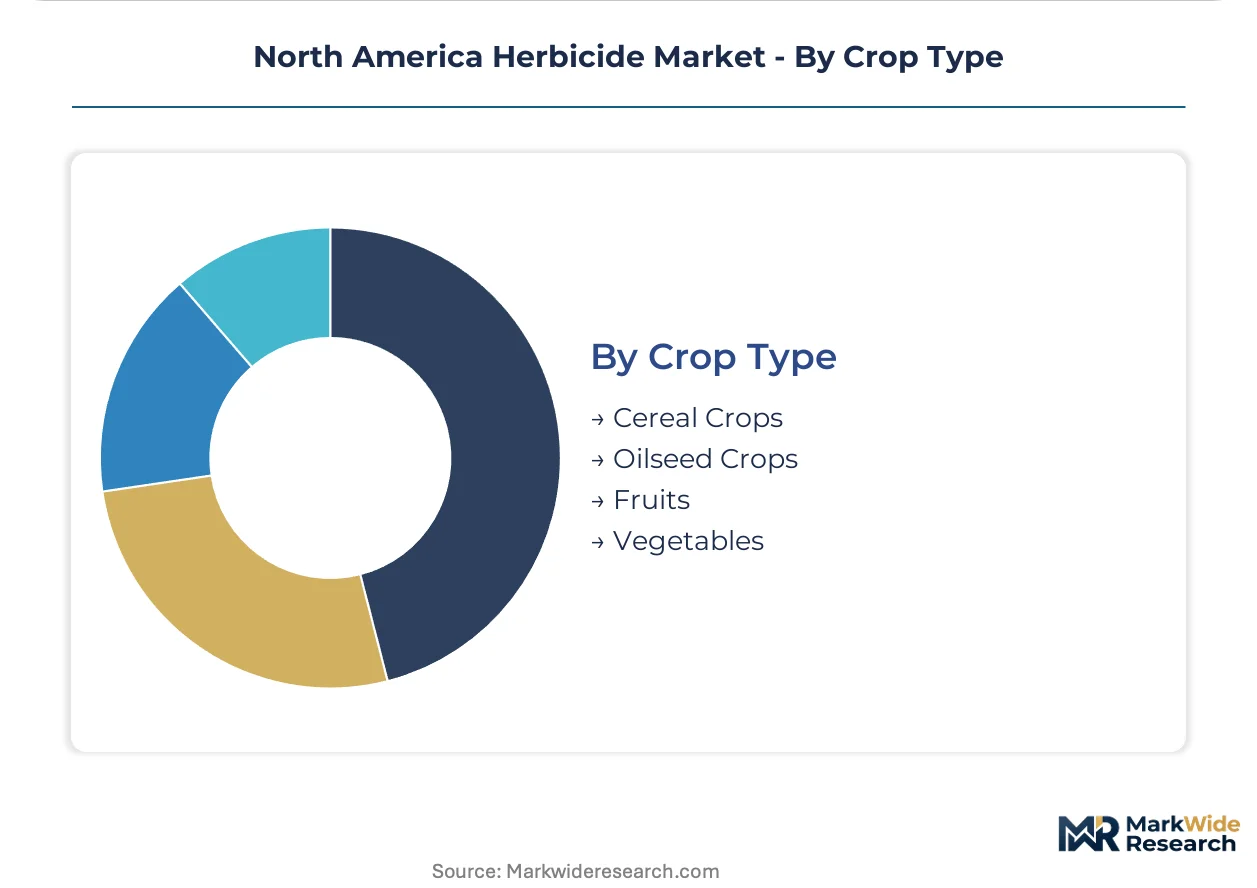
Crop Type:
Customer type segmentation separates commodity grain operations with price-sensitive procurement from specialty crop producers with zero-tolerance residue requirements.
- Cereal Crops:Wheat and barley production in the Canadian prairies and U.S. Northern Plains consumes selective Group 2 and Group 4 chemistries. Health Canada's PMRA re-evaluation of ALS inhibitors is forcing Saskatchewan growers toward alternative modes of action.
- Oilseed Crops:Canola and soybean systems require careful rotation between herbicide-tolerant trait platforms. Manitoba canola growers rotate between glyphosate-tolerant, glufosinate-tolerant, and conventional varieties to manage resistance.
- Fruits:Tree nuts and citrus demand long-residual pre-emergent chemistries with extended application windows. California almond processors now specify approved herbicide lists in supply agreements, displacing cost-minimization procurement.
- Vegetables:Processing tomatoes, peppers, and leafy greens require selective chemistries with short pre-harvest intervals. Mexico's expanding protected agriculture sector in Sinaloa is intensifying demand for drip-irrigation-compatible formulations.
Cereal crops anchor volume consumption; vegetables are expanding most quickly through protected agriculture investment in Mexico and the southeastern United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of North American herbicide volume, while Canada and Mexico concentrate production in specific crop corridors. Formulation capacity clusters near the U.S. Gulf Coast and the Canadian prairies, creating cross-border supply dependencies.
United States
Iowa and Illinois corn-soybean rotations absorb massive selective herbicide volumes as resistance management protocols mandate multi-mode-of-action programs. The EPA's re-registration review of glyphosate is accelerating R&D investment toward bio-based alternatives. California's Central Valley specialty crop producers are retrofitting precision sprayers to meet zero-tolerance residue standards from tomato and almond processors.
Canada
Saskatchewan and Manitoba cereal and canola growers face tightening PMRA re-evaluation timelines for ALS-inhibitor herbicides. Health Canada's accelerated aquatic toxicity studies are forcing withdrawal of minor-use registrations for pulse crops. The prairie provinces are shifting toward Group 14 PPO inhibitors despite elevated phytotoxicity risk under cool, wet spring conditions.
Mexico
Sinaloa's protected agriculture corridor is intensifying demand for selective pre-emergent chemistries with short pre-harvest intervals. COFEPRIS alignment with USMCA successor provisions creates synchronization requirements for cross-border formulation distribution. Drip-irrigated tomato and pepper operations in Culiacán are testing ultra-low-volume liquid formulations compatible with precision infrastructure.
North America Herbicide Market Competitive Landscape
Top-tier vendors anchor the non-selective segment, while mid-tier specialists compete in selective and biological niches. The market exhibits consolidated leadership in high-volume commodity chemistries alongside fragmented competition in specialty applications. Three archetypes dominate: integrated agrochemical conglomerates with trait-seed platforms, standalone formulation specialists, and biological technology developers. Competitive moves center on precision application technology licensing and portfolio diversification into carbon-intensity scoring services.
Among European-headquartered conglomerates, BASF SE and Bayer AG exemplify the integrated archetype through glufosinate-ammonium platforms and crop science R&D intensity. Corteva Agriscience occupies a distinct position with novel arylpicolinate development targeting resistant weed populations. These three represent the tier driving consolidation through bundled service models that combine chemistry with digital agriculture infrastructure.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| Nufarm Ltd |
| Syngenta Group |
| ADAMA Agricultural Solutions Ltd |
| American Vanguard Corporation |
| UPL Limited |
| Others |
Pricing and Supply Chain Analysis
Precision agriculture technician shortages in the U.S. Corn Belt and Canadian prairies widen labor-cost spreads between premium precision-enabled formulations and commodity dry products. These differentials compress pricing power at the standard tier while elevating premiums for ultra-low-volume liquid systems compatible with pulse-width modulation infrastructure.
Pricing Analysis
Margin tightening in standard-tier commodity herbicides traces to Chinese technical-grade concentration and ocean freight volatility. Contract-based long-term offtake dominates volume procurement, with price differentiation hinging on formulation quality grade and volume scale. Cost-down pressure on economy-tier dry formulations accelerates because tariff exposure compounds input cost swings. Midwest corn-soybean cooperatives exhibit highest price sensitivity; California specialty crop processors prioritize zero-tolerance performance over unit cost.
Supply Chain Analysis
USMCA domestic-content alignment requirements are reshaping cross-border sourcing patterns for Mexican formulators. Active ingredient production concentrates in China, India, and Germany; North American blending capacity clusters near the U.S. Gulf Coast and Canadian prairies. Technical-grade glyphosate and glufosinate supply draws from Chinese manufacturers, exposing formulators to single-source vulnerability. Distribution runs through agricultural retail cooperatives and precision equipment dealerships serving regional crop corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America herbicide market is becoming a vertical-integration race, with players pursuing backward control over bio-based active ingredient supply to secure EPA registration pipelines.
For Market Incumbents: To counter glyphosate re-registration uncertainty and Chinese supply concentration, BASF and Bayer should deepen captive production of fermentation-derived bioherbicide platforms. Channel control through precision equipment dealership networks offers defensive positioning against generic formulation erosion. For New Entrants and Emerging Players: Direct-to-grower digital platforms offer the lowest-friction route to bypass established cooperative distribution. Drone-based aerial application services in Mexico's Sinaloa corridor and the Texas High Plains represent the most penetrable white space, with outcome-based weed-free guarantees as the distinguishing go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with biological technology developers possessing EPA-registered active ingredients and precision application compatibility, given carbon-intensity scoring integration as the catalyst. Long-term viability favors platforms with multi-mode-of-action resistance management portfolios. Watch for EPA Endangered Species Act consultation outcomes as the signal for mandatory buffer zone impacts on operational flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Active Ingredients | Secures EPA registration pipelines against glyphosate re-registration pressure. |
| Precision Equipment Dealership Network Expansion | Locks in grower loyalty through PWM nozzle calibration and RTK-GPS service contracts. |
| Carbon-Intensity Scoring Program Pilot | Positions herbicide bundles for USDA Climate-Smart Commodity grant eligibility. |
| Drone-Based Aerial Application Service Launch | Captures terrace backlope and field-edge revenue unreachable by ground rigs. |
| Joint Venture with Chinese Technical-Grade Suppliers | Mitigates tariff exposure through localized blending capacity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with crop science R&D directors, agricultural retail procurement managers, precision equipment dealership technicians, and university extension weed specialists combined with EPA registration databases, Health Canada PMRA re-evaluation notices, and USMCA customs documentation. Bottom-up volume modeling and top-down value triangulation validated segment-level estimates.
Granularity-level modeling operated at formulation type, application method, and crop-specific resolution across the projection horizon. Analytical framework approach linked acreage projections, resistance management protocol adoption curves, and precision infrastructure penetration rates to derive expansion trajectories. Mode-of-action rotation requirements and aquatic toxicity regulatory thresholds served as industry-specific forecast inputs.
The model holds under stable EPA registration timelines and USMCA trade continuity; deviation in Endangered Species Act consultation outcomes or Chinese export restriction triggers would shift volume and value envelopes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market