
 Crop Sprayers Market | 2026-2036
Crop Sprayers Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Sprayers Market Analysis
Market Dynamics
Brazil is tilting toward high-capacity self-propelled sprayer manufacturing to serve South American soybean and corn operations. Deere & Company leverages its precision agriculture ecosystem to anchor premium tractor-mounted system sales across the Brazilian interior. AGCO Corporation competes through regional assembly flexibility and localized dealer networks. Kubota Corporation extends its compact equipment expertise into mid-size mounted sprayers for Japanese rice paddies and Southeast Asian smallholder markets.
Product Architecture
Crop sprayers are pressurized application machines that distribute liquid agrochemicals through calibrated nozzles at specified droplet sizes and flow rates, with modern units integrating GPS guidance, pulse-width modulation, and real-time weather sensing to minimize off-target drift. The tractor-mounted category dominates volume due to compatibility with existing farm fleets and lower capital thresholds, while UAV sprayers represent the fastest-expanding segment as battery endurance and payload capacity improve for specialty crop canopy penetration. Electrostatic technology commands margin premiums by reducing chemical volume requirements through charged droplet adhesion, though air-assisted systems retain share in dense orchard and vineyard applications.
Regulatory Environment
EPA drift-reduction technology certifications and OSHA agricultural worker protection standards govern US equipment design and operator exposure protocols, while Brazil's national environmental council enforces buffer distances that drive demand for precision application systems. The EU F-Gas Regulation and Machinery Directive pressure manufacturers toward lower-emission engine configurations and CE-compliant safety architectures for European market access. Stakeholders must weigh regulatory compliance investments against the operational savings that autonomous routing and variable-rate application promise for large-scale acreage.
Market Dynamics
Precision application mandates from EPA drift-reduction technology certifications and Brazil's national environmental council buffer distance rules are compressing equipment replacement cycles and forcing OEMs to integrate real-time weather sensing and pulse-width modulation as standard features rather than premium add-ons.
Growth Catalysts
- Brazilian Soybean Belt Expansion:Large-scale operators in Mato Grosso are replacing aging mounted sprayers with GPS-guided tractor systems to meet rising acreage demands and labor constraints.
- EPA Drift-Reduction Technology (DRT) Certification:Federal mandates for off-target spray minimization are accelerating fleet turnover among US row-crop producers seeking compliance-ready equipment.
- Electrostatic Droplet Adhesion:Charged particle application systems are reducing chemical volume requirements by 30-50% in specialty crop operations, lowering per-acre input costs.
Market Restraints
- Steel and Aluminum Input Volatility:Boom arm fabrication and tank manufacturing depend on commodity metals whose price swings compress OEM margins and destabilize equipment pricing.
- High-Voltage Battery Supply Concentration:UAV sprayer manufacturers face sourcing bottlenecks as lithium-ion cell production concentrates in East Asian contract manufacturers.
- EU F-Gas Regulation Engine Compliance:Refrigerant-based cooling systems for cab climate control face phase-down timelines that complicate European market certification pathways.
Strategic Opportunities
- Southeast Asian Smallholder Mechanization:Compact mounted sprayer demand in Vietnam and Thailand rice paddies remains underpenetrated relative to tractor ownership rates.
- Autonomous Routing Convergence:Integration of computer vision with RTK-GPS guidance enables nighttime spraying operations, expanding effective application windows.
- California Buffer Zone Mandates:State-level restrictions on spray proximity to sensitive sites create captive demand for precision boom section control and spot-spray drones.
Industry Challenges
- Certified Applicator Shortage:Commercial pesticide licensing requirements outpace training program capacity, constraining fleet utilization rates during narrow weather windows.
- Legacy Fleet Integration Complexity:Retrofitting older tractor platforms with ISOBUS-compatible control systems requires proprietary adapter hardware that fragments aftermarket support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Sprayers Market |
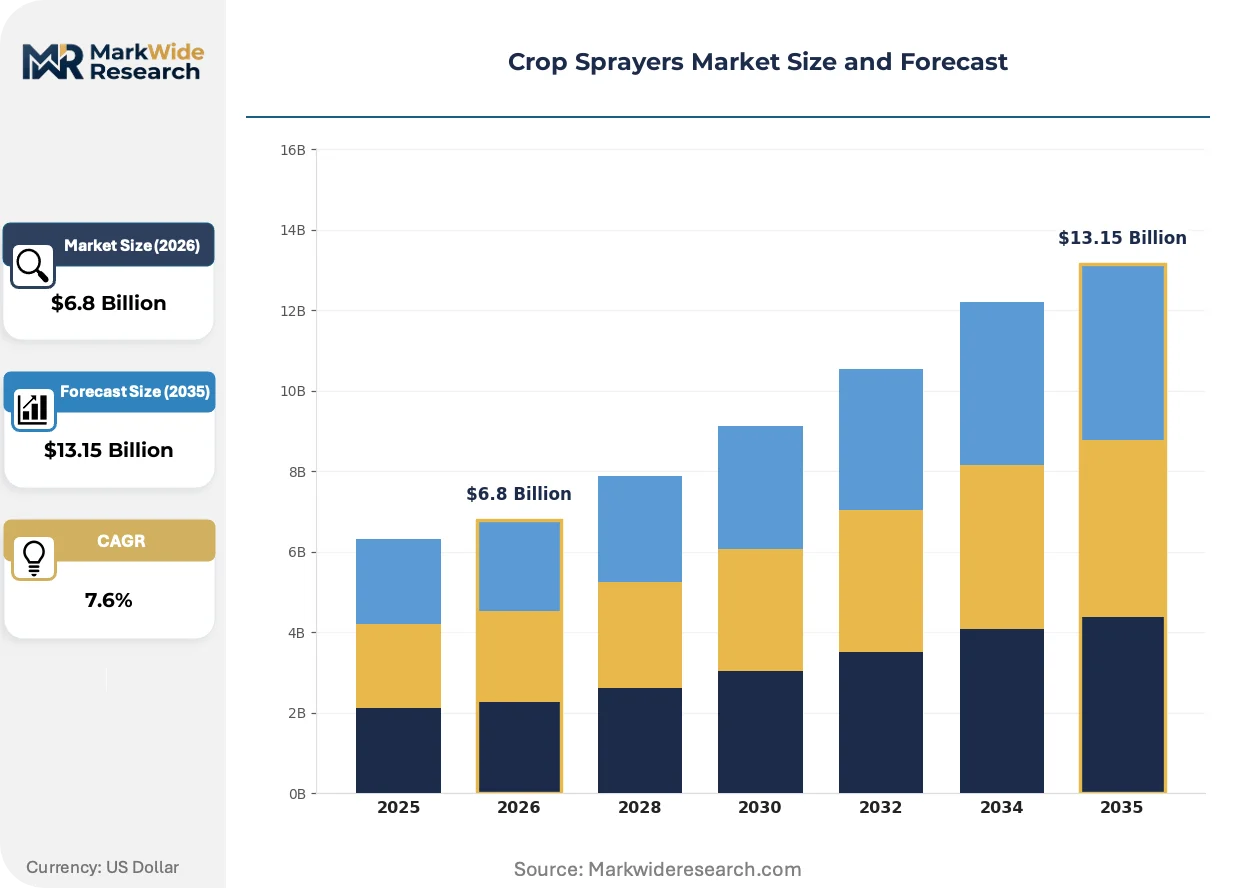
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Handheld, Tractors, UAVs, Mounted Application: Pesticide, Fertilizer, Herbicide, Fungicide End User: Farmers, Agricultural Cooperatives, Commercial Growers, Landscaping Services Technology: Air-Assisted, Electrostatic, Low-Volume, High-Volume |
| Companies Covered | Kubota Corporation, Bucher Industries, Deere & Company, Amazone H. Dreyer GmbH & Co. KG, Hardi International, AGCO Corporation, EXEL Industries, Jacto Inc., CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Sprayers Market Emerging Trajectories
Application equipment is transitioning from mechanical calibration to sensor-driven closed-loop systems, with real-time droplet size monitoring and automatic nozzle pressure adjustment becoming baseline expectations rather than premium configurations.
Variable-rate application technology is digitizing spray decision-making by correlating prescription maps with in-field biomass sensors. Large-scale corn and soybean operators in Iowa and Illinois are deploying these systems across 80% of new equipment purchases. The shift is compressing uniform-rate sprayer residual values and forcing dealers to bundle agronomic consulting with hardware sales.
OSHA agricultural worker protection standards are tightening operator exposure protocols around cab filtration and decontamination procedures. Equipment manufacturers must now engineer sealed positive-pressure cabins and onboard rinse systems as standard configurations. Specialty crop producers in Washington State apple orchards are absorbing 15-20% equipment cost premiums to meet these exposure reduction mandates.
Service-based equipment access models are displacing outright ownership among mid-scale California vegetable growers facing capital constraints and seasonal utilization challenges. Regional cooperatives and dealer rental pools now control 35% of high-clearance self-propelled capacity in the Salinas Valley. This shift is fragmenting OEM customer relationships and compressing parts-and-service margin capture.
Crop Sprayers Market Segmentation
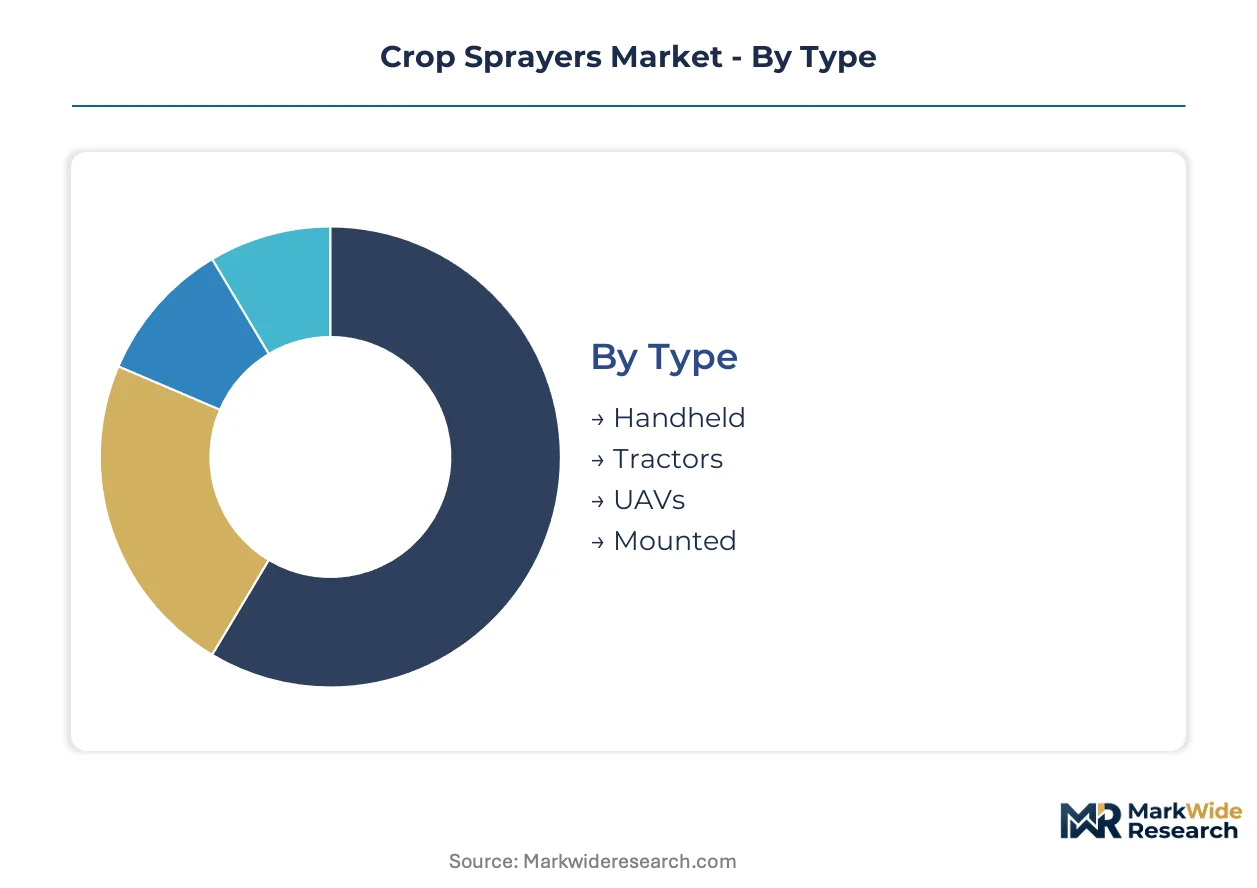
Equipment specification varies sharply across operator scale and crop architecture. Segmentation reveals where capital investment concentrates and which technology configurations command premium positioning.
Type:
Equipment format determines capital outlay, field coverage rates, and integration complexity with existing farm machinery.
- Tractors:Self-propelled high-clearance units carry tank capacities exceeding 1,000 gallons and boom widths up to 120 feet. Demand concentrates in Brazil's Mato Grosso soybean belt where operators replace aging fleets with GPS-guided systems to meet rising acreage demands and labor constraints.
- UAVs:Battery-powered aerial platforms with 10-30 liter payloads penetrate dense canopies in specialty crops. California's Central Valley vegetable growers are expanding precision application fleets as EPA drift-reduction requirements reshape equipment specifications.
- Handheld:Portable tank-and-lance systems serve smallholder plots under five hectares across Southeast Asian rice paddies.
- Mounted:Three-point hitch attachments leverage existing tractor fleets, dominating volume through lower capital thresholds.
Mounted systems command the established base. The steepest expansion runs through UAVs.
Application:
Chemical function dictates nozzle selection, droplet size parameters, and seasonal utilization windows.
- Herbicide:Broad-spectrum weed control applications require coarse droplet spectra to minimize off-target drift. Iowa and Illinois corn-soybean operators deploy variable-rate systems across the majority of new equipment purchases, compressing uniform-rate sprayer residual values.
- Pesticide:Insecticide delivery demands precise timing during narrow weather windows. Certified applicator shortages constrain fleet utilization rates during critical application periods.
- Fertilizer:Liquid nutrient application integrates with prescription mapping for site-specific dosing.
- Fungicide:Disease prevention spraying in dense vineyard and orchard canopies favors air-assisted droplet penetration.
Herbicide application anchors equipment utilization. Fungicide work shows the most rapid technology upgrade cycle.
End User:
Customer scale determines ownership models, service expectations, and financing structures.
- Commercial Growers:Large-scale specialty crop operations in Washington State apple orchards absorb 15-20% equipment cost premiums for sealed positive-pressure cabins and onboard rinse systems mandated by OSHA agricultural worker protection standards.
- Agricultural Cooperatives:Pooled ownership structures control 35% of high-clearance self-propelled capacity in California's Salinas Valley, fragmenting OEM customer relationships through rental-based access models.
- Farmers:Individual owner-operators in the US row-crop sector drive fleet turnover seeking EPA drift-reduction technology certification compliance.
- Landscaping Services:Turf and ornamental maintenance contractors favor compact mounted units for municipal and golf course contracts.
Commercial growers set the specification benchmark. Cooperative ownership is climbing the fastest.
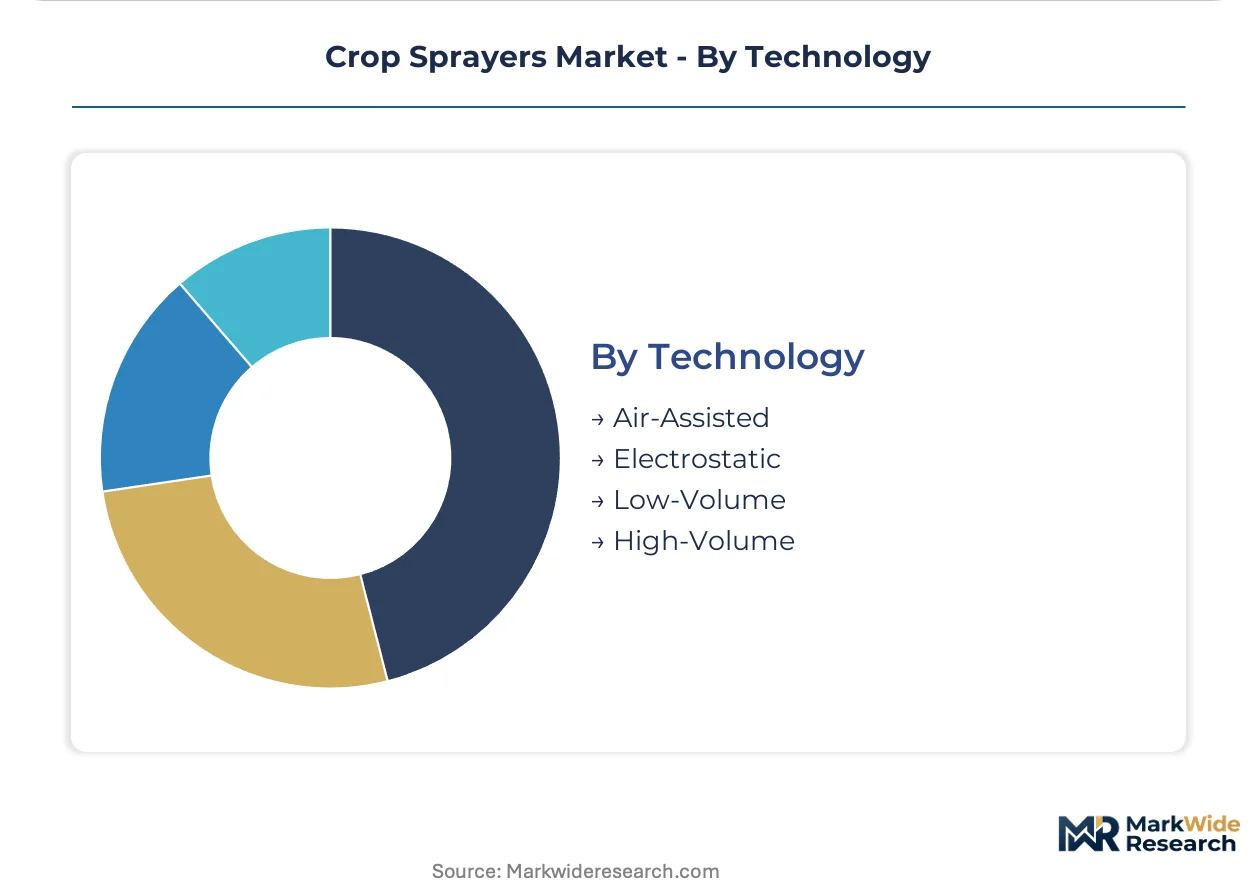
Technology:
Application physics determines chemical efficiency, drift potential, and regulatory compliance positioning.
- Electrostatic:Charged droplet adhesion reduces chemical volume requirements by 30-50% in specialty crop operations. The technology commands margin premiums through lowered per-acre input costs.
- Air-Assisted:Turbulent airflow carries droplets into dense orchard and vineyard canopies. Brazil's national environmental council buffer distance rules drive demand for precision application systems that minimize off-target movement.
- Low-Volume:Concentrate spraying with ultra-fine droplet spectra suits protected cultivation and greenhouse environments.
- High-Volume:Dilute application rates with coarse droplets dominate broad-acre row-crop spraying.
High-volume systems retain the installed base. Electrostatic application is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Brazil's high-volume soybean operations and Japan's compact rice paddy configurations, with equipment specification driven by farm scale rather than crop type alone.
United States
Row-crop producers in Iowa and Illinois are deploying variable-rate systems across the majority of new equipment purchases. EPA drift-reduction technology certifications are accelerating fleet turnover among commercial growers seeking compliance-ready configurations. The Central Valley specialty crop belt is expanding precision application fleets as state-level buffer zone mandates reshape equipment specifications.
Brazil
Large-scale operators in Mato Grosso are replacing aging mounted sprayers with GPS-guided tractor systems to meet rising acreage demands. ANVISA and the national environmental council enforce buffer distances that drive demand for precision application systems. The soybean belt is tilting toward high-capacity self-propelled sprayer manufacturing to serve South American corn and soybean operations.
Germany
Precision agriculture ecosystems anchor premium tractor-mounted system sales across the European interior. The EU F-Gas Regulation and Machinery Directive pressure manufacturers toward lower-emission engine configurations and CE-compliant safety architectures. Bavarian equipment fabricators are adapting boom section control technologies for vineyard and orchard applications.
Japan
Compact equipment expertise extends into mid-size mounted sprayers for rice paddy operations and Southeast Asian smallholder markets. METI standards govern agricultural machinery safety and emissions configurations for domestic certification. Osaka-based manufacturers are integrating electrostatic droplet adhesion systems for chemical volume reduction in specialty crop applications.
Australia
Broad-acre wheat and canola operations favor self-propelled high-clearance units with extended boom widths for efficient coverage. The country's national agricultural regulator enforces chemical application standards that align with drift-minimization technologies. Queensland and Western Australia grain belts are adopting autonomous routing convergence for nighttime spraying operations.
Crop Sprayers Market Vendor Landscape
Capability concentration sits with precision technology integrators; scale advantage sits with diversified agricultural equipment conglomerates. The vendor base organizes around three strategic archetypes: full-line agricultural machinery conglomerates, specialized application equipment fabricators, and regional compact equipment specialists. Consolidation pressure runs through precision agriculture technology acquisitions and dealership network consolidation. Geographic expansion into Southeast Asian smallholder markets and backward integration into nozzle and pump component manufacturing represent dominant competitive vectors.
Among diversified machinery conglomerates, Deere & Company and AGCO Corporation exemplify scale-driven positioning through integrated precision agriculture ecosystems and regional assembly flexibility. Kubota Corporation occupies a distinct tier as a compact equipment specialist extending expertise into mid-size mounted configurations for constrained-field environments. These three anchors illustrate the competitive tension between full-line coverage and focused specialization that defines vendor positioning across price-performance tiers.
| Leading Market Players |
|---|
| Kubota Corporation |
| Bucher Industries |
| Deere & Company |
| Amazone H. Dreyer GmbH & Co. KG |
| Hardi International |
| AGCO Corporation |
| EXEL Industries |
| Jacto Inc. |
| CNH Industrial |
| Others |
Supply Flow & Price Mechanics
South China's Guangdong manufacturing cluster anchors global nozzle and pump component production, concentrating component sourcing leverage among OEMs who control fabrication capacity there. This geographic concentration translates directly into tiered equipment pricing power, with integrated manufacturers commanding 15-25% premiums over assembly-dependent competitors.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement by large-scale Brazilian soybean operators, while spot purchasing persists among Southeast Asian smallholder cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates GPS-integrated self-propelled systems from basic mounted configurations and refurbished legacy units. Cost compression in the economy tier is intensifying because Chinese manufacturers are flooding mid-size mounted sprayer segments with ISOBUS-compatible alternatives. Commercial growers in Washington State apple orchards show the least price sensitivity, absorbing premiums for OSHA-compliant sealed cabins, while Vietnamese rice paddy cooperatives exhibit acute sensitivity to capital outlay thresholds.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for European OEMs sourcing boom arm steel from German and Italian fabricators, compressing working capital cycles for tier-two suppliers. Manufacturing concentration rests on China for lithium-ion UAV battery cells, Germany for precision pump assemblies, and Brazil for regional self-propelled sprayer final assembly. Raw material dependencies draw from commodity steel and aluminum for boom fabrication, high-grade polymers for tank construction, and semiconductor components for GPS guidance modules. Single-source vulnerability concentrates in East Asian battery cell production, where logistics chokepoints through the Strait of Malacca threaten UAV manufacturer delivery schedules. Distribution runs through authorized dealer networks for high-value self-propelled units, while direct-to-farm digital channels are displacing intermediaries for compact mounted sprayer accessories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAV spot-spray platforms represent a credible substitution threat to traditional boom sprayers in specialty crop applications, forcing incumbent OEMs to defend their installed base through precision technology integration rather than hardware alone.
For Market Incumbents: Pre-empt UAV displacement by embedding computer vision and RTK-GPS guidance as standard features across mid-tier tractor-mounted lines, not merely premium self-propelled configurations. Consolidate aftermarket service revenue through proprietary ISOBUS adapter hardware that fragments third-party retrofit support. Priority defensive investment centers on backward integration into nozzle manufacturing to capture margin currently flowing to specialized component suppliers.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Thailand compact mounted sprayer segments, where tractor ownership rates exceed sprayer penetration by 40 percentage points. Target agricultural cooperatives in California's Salinas Valley with rental-based access models that circumvent capital constraints among mid-scale vegetable growers. Go-to-market angle should emphasize agronomic consulting bundling, replicating the service-integrated positioning that has captured 35% of regional high-clearance capacity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision agriculture technology integrators who bundle subscription-based prescription mapping with hardware sales, generating multi-year service contracts. Long-term viability favors vendors with captive nozzle and pump component production, insulating margins from commodity metal volatility. Acquisition target archetype: regional specialists with established dealer networks in underpenetrated Southeast Asian smallholder markets. Signal to watch: EPA drift-reduction technology certification timelines, which will accelerate fleet turnover windows among compliance-seeking US row-crop producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Technology Integration | GPS guidance and pulse-width modulation are becoming baseline expectations rather than premium configurations across all price tiers. |
| Backward Integration into Nozzle Manufacturing | In-house production of precision application components captures margin currently flowing to specialized suppliers in Guangdong and Bavaria. |
| Service-Based Equipment Access Models | Rental pools and cooperative ownership structures address seasonal utilization challenges among California vegetable growers. |
| Southeast Asian Geographic Expansion | Compact mounted sprayer demand in Vietnam and Thailand rice paddies remains underpenetrated relative to tractor ownership rates. |
| Regulatory Compliance Certification Investment | EPA drift-reduction technology and OSHA agricultural worker protection standards are compressing equipment replacement cycles among US producers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with precision agriculture directors at equipment dealerships, regulatory compliance officers at EPA-certified manufacturers, fleet managers at Mato Grosso soybean operations, and procurement leads at California agricultural cooperatives. Secondary validation drew from EPA drift-reduction technology certification databases, ANVISA regulatory filings, SEC 10-K equipment segment disclosures, and OEM parts-and-service revenue breakdowns. Bottom-up unit shipment estimates by equipment type and region were triangulated against top-down addressable acreage calculations.
Calibration against historical replacement cycle data and regulatory compliance deadline clustering anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment format, application chemistry, operator scale, and precision technology tier. CAGRs were derived from slope analysis of fitted trend lines applied to annual shipment trajectories. Industry-specific forecast inputs incorporated lithium-ion battery cost curves for UAV platforms and steel price volatility indices for boom arm fabrication.
Sensitivities concentrate around EPA certification timeline shifts, Brazilian buffer zone mandate enforcement intensity, and East Asian battery supply disruption scenarios. Forecasts reflect documented assumptions regarding replacement cycle compression and technology adoption S-curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Hay Making Machinery Market