
 Neem Extract Market | 2026-2036
Neem Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Neem Extract Market Intelligence
Modular formulation kits is repositioning buyer choice in the neem extract sector, allowing farmers to blend concentrates with adjuvants at point of use rather than purchasing finished products. GreeNeem Agri Pvt Ltd anchors its position through captive orchards in Tamil Nadu that guarantee azadirachtin consistency. Fortune Biotech leverages pharmaceutical-grade extraction infrastructure to serve European cosmetics buyers. EID Parry dominates bulk powder supply to Indian agricultural cooperatives through decades-old channel relationships.
Neem extract comprises bioactive compounds derived from Azadirachta indica kernels and leaves, with azadirachtin concentrations typically ranging from 0.03% to 5% depending on solvent and cold-press methods, serving primarily as a botanical pesticide, dermatological agent, and oral hygiene ingredient. Oil formulations command premium pricing due to cold-press processing costs and limited azadirachtin degradation, while powder segments compete on volume in agricultural applications where stability during monsoon storage determines repeat purchase. Pharmaceutical applications extract margin from certified organic supply chains that pharmaceutical and cosmetics buyers audit for heavy metal content and solvent residues.
India's Central Insecticides Board regulates neem-based pesticide registration under the Insecticides Act, while the FSSAI governs extract purity in nutraceutical and oral care applications; both frameworks push manufacturers toward standardized azadirachtin labeling. The EU REACH framework and EFSA botanical guidance constrain export-bound extractors to submit full toxicological dossiers for novel formulations. Stakeholders must monitor whether India's PLI scheme for agrochemical manufacturing extends processing subsidies to neem-based biopesticide facilities.
Market Dynamics
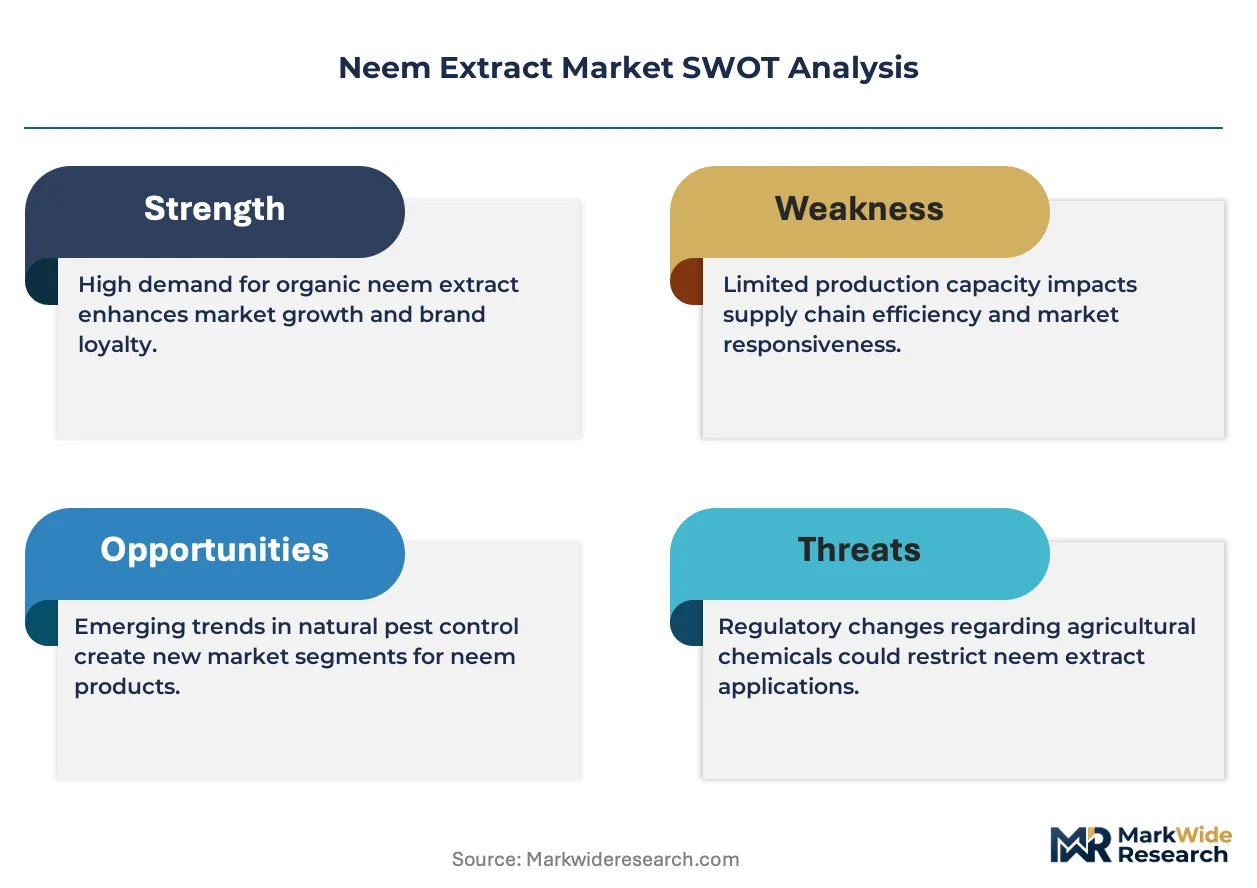
Agricultural input manufacturers now bundle neem-based biopesticides with soil health services rather than selling standalone extracts, compressing margins for pure-play extractors while rewarding vertically integrated operators with captive orchard capacity.
Growth Catalysts
- EU REACH framework:Botanical pesticide registration under REACH toxicological dossier requirements is accelerating demand for certified organic supply chains among European cosmetics buyers.
- Maharashtra's agrarian belt:Concentrated vegetable cultivation clusters are driving bulk procurement of azadirachtin concentrates for integrated pest management programs.
- Cold-press extraction methods:Oil formulations with limited azadirachtin degradation command premium pricing in pharmaceutical applications where stability determines repeat purchase.
Market Restraints
- Input cost volatility:Neem kernel prices fluctuate with monsoon-dependent harvests in Tamil Nadu and Karnataka, squeezing cold-press processor margins.
- Supply concentration risk:Overreliance on India's BIS-certified organic agricultural input corridors creates vulnerability to purity benchmark tightening.
- Substitution threat:Synthetic pyrethroids and Bacillus thuringiensis formulations compete on cost in price-sensitive agricultural cooperatives.
Strategic Opportunities
- Gujarat's pharmaceutical corridors:Underpenetrated dermatological and oral hygiene ingredient demand offers expansion paths for pharmaceutical-grade extractors.
- India's PLI scheme:Potential processing subsidies for agrochemical manufacturing facilities could reduce capital barriers for biopesticide production scaling.
- Modular formulation kits:Point-of-use blending systems allow farmers to customize adjuvant ratios, opening service revenue streams beyond commodity powder sales.
Industry Challenges
- Azadirachtin standardization:Variability between 0.03% and 5% concentrations across solvent methods complicates FSSAI-compliant labeling for nutraceutical applications.
- Heavy metal audit compliance:Pharmaceutical and cosmetics buyers require certified organic supply chain documentation that many small-scale extractors cannot furnish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neem Extract Market |
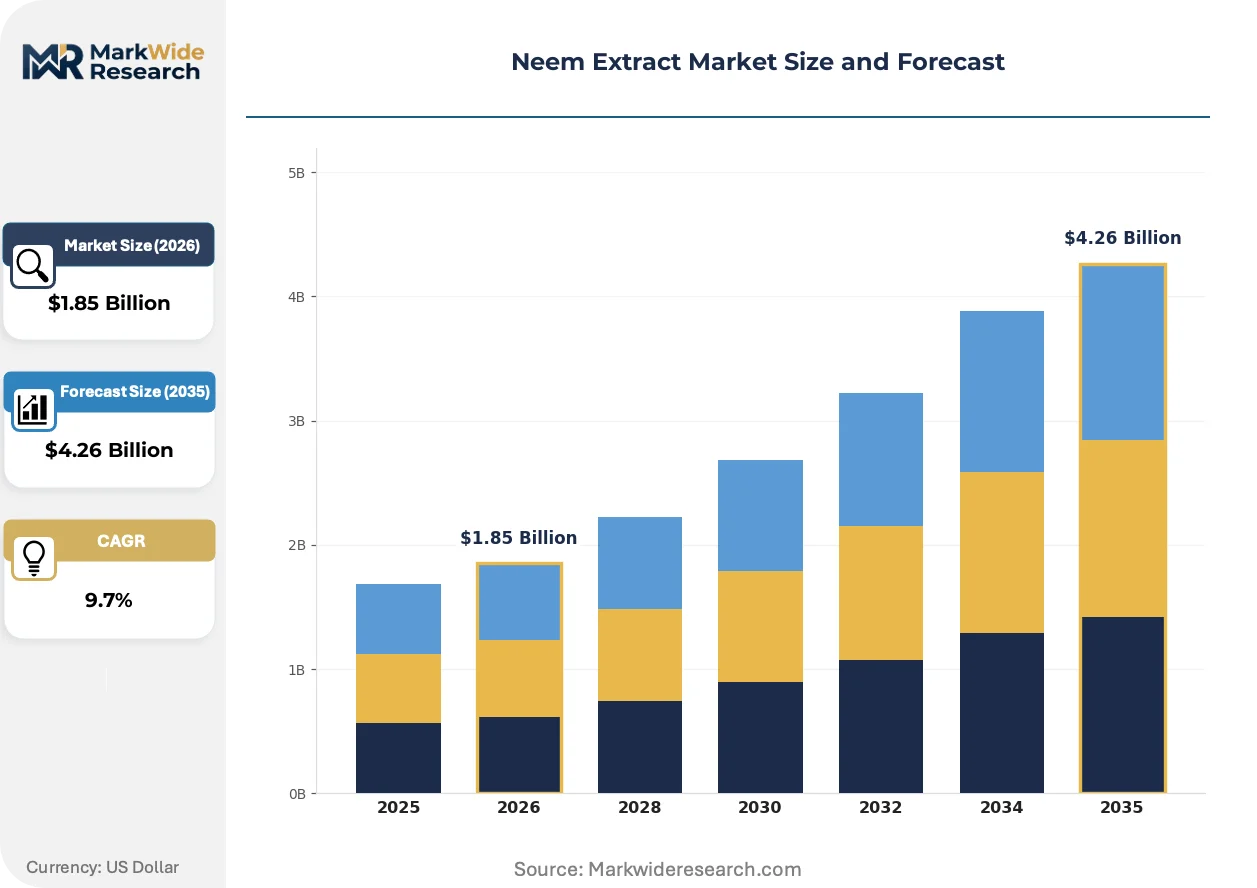
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Powder, Paste, Capsule Application: Agricultural, Pharmaceuticals, Cosmetics, Personal Care Formulation: Organic, Synthetic, Natural, Hybrid Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Gramin India Agri BusiNest, Neeming Australia, Agro Extracts Limited, Parker Biotech Private Limited, Ozone Biotech, Fortune Biotech, GreeNeem Agri Pvt Ltd, EID Parry, PJ Margo Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neem Extract Market Strategic Shifts & Innovations
Formulation technology and regulatory documentation standards are reshaping competitive advantage in neem extract supply, with differentiation shifting from raw material access to certified processing capabilities and point-of-use customization systems.
Supercritical CO2 extraction technology is expanding into pharmaceutical-grade azadirachtin production by preserving bioactive compound integrity without solvent residues. European cosmetics manufacturers are adopting these extracts at accelerated procurement cycles to meet EFSA botanical guidance purity thresholds. This technology is expanding into mid-tier agricultural applications previously served by conventional cold-press methods, compressing price premiums for basic oil formulations.
India's BIS certification requirements for organic agricultural inputs are tightening purity benchmarks for heavy metal content and solvent residues. The Central Insecticides Board now mandates standardized azadirachtin labeling under the Insecticides Act, forcing reformulation of legacy product registrations. Agricultural cooperatives in Maharashtra and Gujarat are responding by consolidating procurement around BIS-certified suppliers with documented supply chain audit trails.
Buyer concentration among agricultural input manufacturers is displacing fragmented distributor networks with direct-to-cooperative supply contracts. Channel disintermediation is most visible in Maharashtra's vegetable cultivation belt, where large cooperatives now negotiate bulk powder supply agreements with EID Parry and similar integrated processors. This consolidation rewards extractors with captive orchard capacity and penalizes traders dependent on spot market kernel sourcing.
Neem Extract Market Segmentation
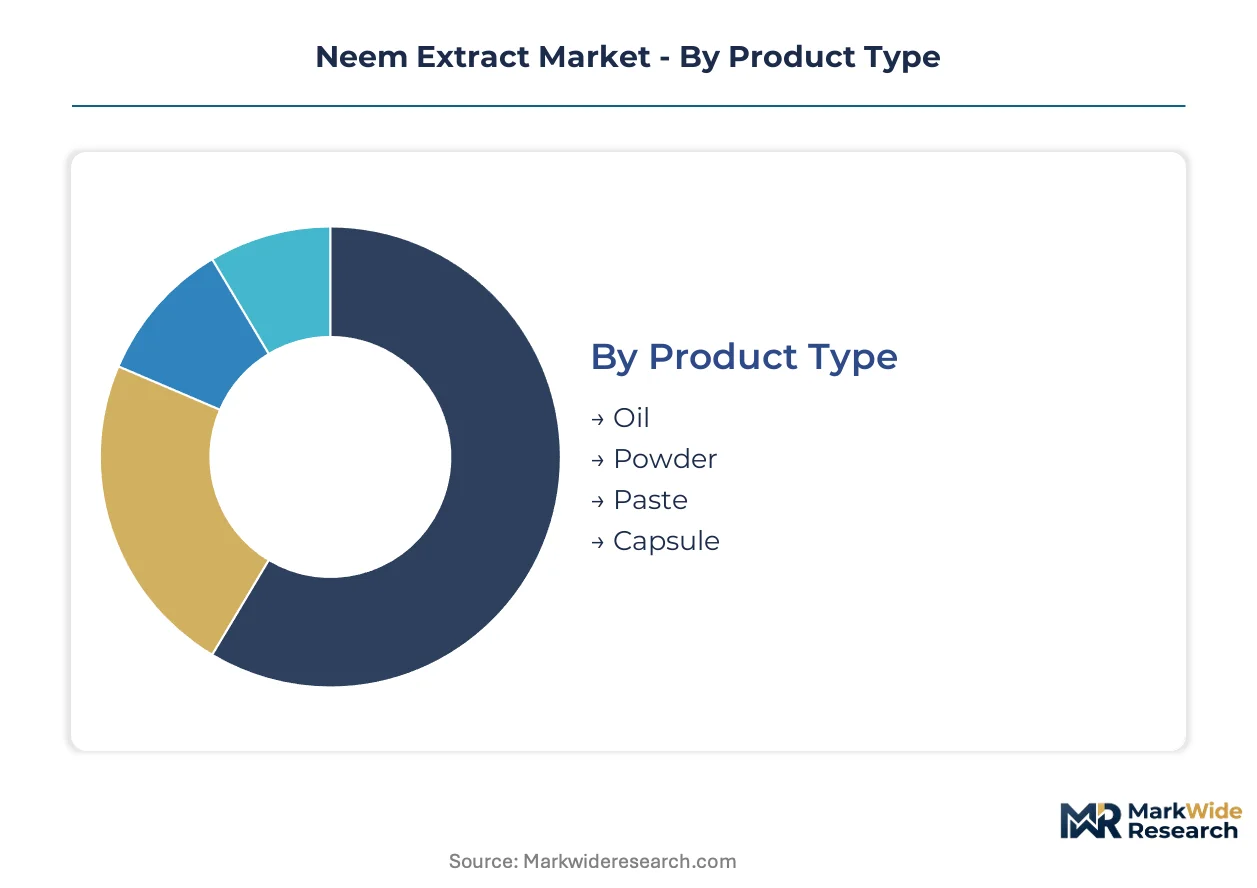
Neem extract segmentation reflects divergent processing intensities across agricultural and pharmaceutical end-uses. Specification standards vary sharply between FSSAI-regulated oral care applications and Central Insecticides Board pesticide registrations.
Product Type:
Cold-press and solvent extraction methods create distinct azadirachtin preservation profiles that determine end-use suitability.
- Oil:Cold-pressed formulations retain azadirachtin concentrations between 0.03% and 5% with minimal thermal degradation. Maharashtra's vegetable cultivation clusters procure oil concentrates for integrated pest management programs where stability during monsoon storage determines repeat purchase.
- Powder:Spray-dried extracts compete on volume in agricultural cooperatives, with BIS-certified purity benchmarks now mandatory for organic input registration. EID Parry dominates bulk supply relationships with decades-old channel positioning in Tamil Nadu and Karnataka procurement zones.
- Paste:Semi-processed intermediates serve regional Ayurvedic manufacturers requiring customizable concentration blending.
- Capsule:Encapsulated formats target nutraceutical applications under FSSAI extract purity governance with standardized labeling requirements.
Oil leads on scale; capsules lead on momentum.
Application:
End-use concentration drives regulatory pathway complexity and margin structure.
- Agricultural:Biopesticide registrations under India's Insecticides Act require full toxicological dossiers for azadirachtin-based formulations. Bundling with soil health services is compressing margins for pure-play extractors while rewarding operators with captive orchard capacity.
- Pharmaceuticals:Dermatological and oral hygiene ingredient demand concentrates in Gujarat's pharmaceutical corridors where Fortune Biotech leverages pharmaceutical-grade extraction infrastructure.
- Cosmetics:European buyers audit for heavy metal content and solvent residues under EFSA botanical guidance, accelerating procurement of supercritical CO2 extracts.
- Personal Care:Toothpaste and soap formulations utilize lower-concentration extracts with FSSAI-compliant labeling for mass-market distribution.
Agricultural applications dominate volume; cosmetics is expanding most quickly.
Formulation:
Certification tier determines pricing structure and customer access.
- Organic:Certified supply chains with documented audit trails command premium positioning among European cosmetics manufacturers and Indian agricultural cooperatives consolidating procurement around BIS-certified suppliers.
- Natural:Minimally processed extracts without synthetic adjuvants serve mid-tier agricultural applications and domestic Ayurvedic product manufacturers.
- Synthetic:Azadirachtin-isolated formulations with laboratory-verified concentration standardization support pharmaceutical applications requiring batch consistency.
- Hybrid:Blended formulations combining neem extracts with complementary bioactives target specialized pest management protocols.
Organic leads on scale; synthetic leads on momentum.
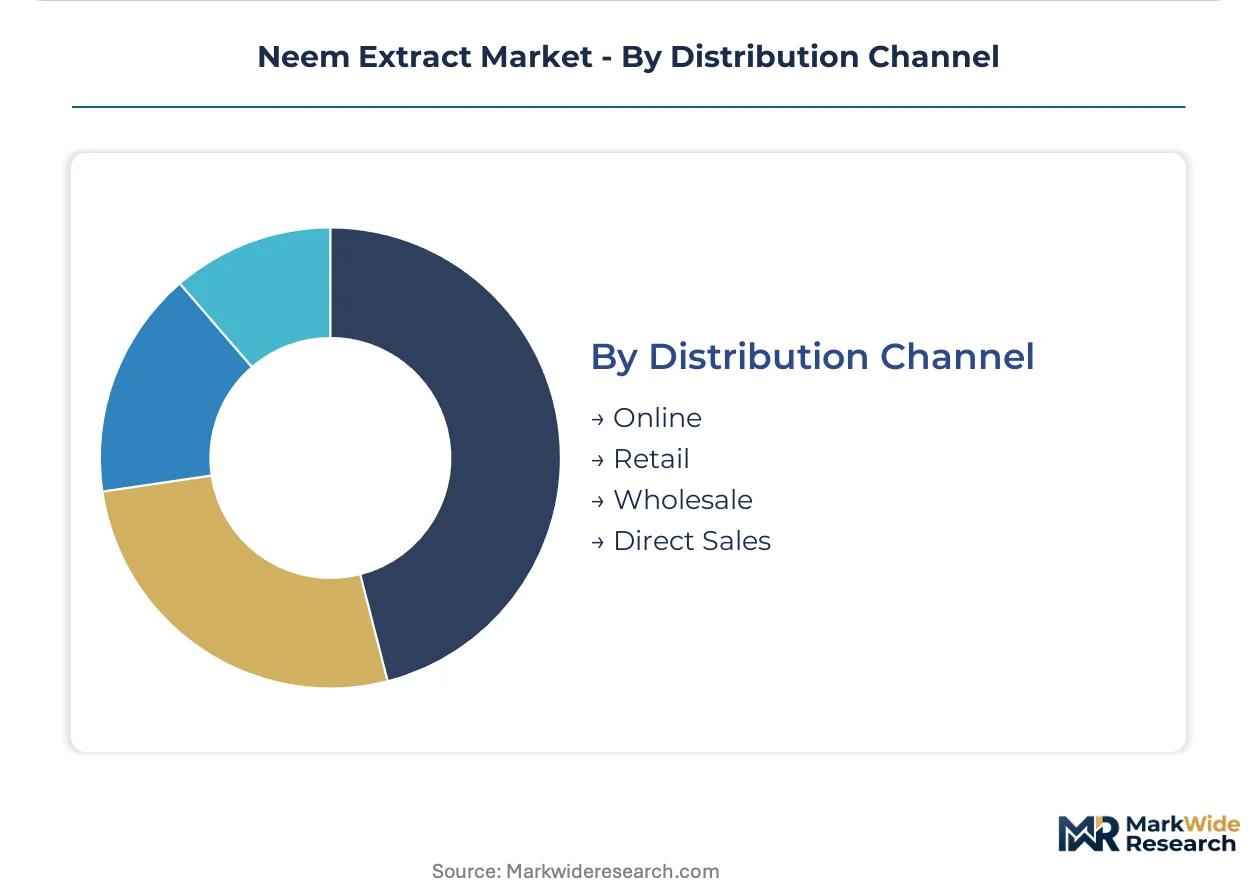
Distribution Channel:
Channel structure is displacing fragmented networks with direct relationships.
- Direct Sales:Large cooperatives in Maharashtra and Gujarat negotiate bulk powder supply agreements that bypass traditional distributor markups.
- Wholesale:Regional aggregators serve smaller agricultural input manufacturers without captive procurement infrastructure.
- Retail:Pharmacy and agricultural supply stores stock finished formulations for individual farmer and consumer purchase.
- Online:E-commerce platforms enable modular formulation kit distribution for point-of-use blending systems.
Direct sales leads on scale; online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neem extract commercialization traces its industrial lineage to post-independence India, where state agricultural extension programs first standardized azadirachtin-based biopesticide formulations for cotton and vegetable cultivation. The sector's geographic footprint now spans five distinct national markets where regulatory frameworks and cultivation clusters shape procurement patterns.
India
Maharashtra's vegetable cultivation belt and Gujarat's pharmaceutical corridors concentrate domestic demand for agricultural and pharmaceutical-grade extracts respectively. India's BIS certification requirements for organic agricultural inputs are tightening purity benchmarks for heavy metal content and solvent residues. The Central Insecticides Board mandates standardized azadirachtin labeling under the Insecticides Act, forcing reformulation of legacy product registrations.
United States
EPA registration of botanical pesticides under FIFRA drives demand for toxicologically documented azadirachtin formulations in organic specialty crop sectors. The USDA National Organic Program certifies neem-based input eligibility for certified organic operations. California's Central Valley vegetable and nut cultivation clusters procure concentrated extracts for integrated pest management programs in almond, strawberry, and leafy green production.
Germany
EFSA botanical guidance and EU REACH framework toxicological dossier requirements constrain import-bound extractors to full documentation compliance. The Federal Office of Consumer Protection and Food Safety enforces residue monitoring for botanical active substances in cosmetic and pharmaceutical applications. Baden-Württemberg's natural cosmetics manufacturing cluster sources supercritical CO2 extracts for premium skincare formulations.
Brazil
ANVISA registration pathways for phytosanitary products accelerate demand for standardized azadirachtin concentrates in soybean and citrus pest management. The Ministry of Agriculture's organic agriculture program subsidizes biopesticide adoption among smallholder cooperatives. São Paulo state's citrus belt and Mato Grosso's soybean frontier represent concentrated procurement zones for bulk agricultural formulations.
Australia
APVMA registration requirements for agricultural chemical products govern azadirachtin-based biopesticide market entry. The Department of Agriculture's biosecurity framework prioritizes botanical alternatives for export-oriented horticulture residue compliance. Queensland's banana and mango cultivation regions drive regional demand for monsoon-stable powder formulations.
Neem Extract Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and captive supply control. The market structure fragments between integrated operators with orchard ownership and toll processors dependent on spot kernel markets. Three archetypes dominate: plantation-integrated extractors with azadirachtin consistency guarantees, pharmaceutical-grade specialists with supercritical CO2 infrastructure, and bulk agricultural suppliers with decades-old cooperative channel relationships. Competitive moves concentrate on backward integration into captive neem orchards and formulation technology licensing for point-of-use blending systems.
Among India-based integrated operators, GreeNeem Agri Pvt Ltd and EID Parry occupy positions spanning plantation control through bulk powder supply. Fortune Biotech exemplifies the pharmaceutical-grade specialization archetype with extraction infrastructure targeting European cosmetics and dermatological ingredient demand. These three anchors represent distinct margin-tier strategies: orchard-captive consistency, cooperative channel scale, and certified purity premium extraction respectively.
| Leading Market Players |
|---|
| Gramin India Agri BusiNest |
| Neeming Australia |
| Agro Extracts Limited |
| Parker Biotech Private Limited |
| Ozone Biotech |
| Fortune Biotech |
| GreeNeem Agri Pvt Ltd |
| EID Parry |
| PJ Margo Private Limited |
| Others |
Cost & Logistics Intelligence
Neem kernel costs in Tamil Nadu and Karnataka harvest cycles feed directly into three-tier pricing stratification across premium pharmaceutical-grade extracts, standard agricultural concentrates, and economy bulk powders. Monsoon-dependent supply volatility compresses cold-press processor margins while rewarding operators with captive orchard capacity and forward-contracted kernel sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates neem extract commercialization. Pharmaceutical-grade cold-pressed oils with certified organic documentation command the highest tier; spray-dried agricultural powders compete on volume in the economy segment. Price differentiation hinges on azadirachtin concentration standardization and BIS certification status. Cost compression in the economy tier is intensifying because agricultural cooperatives consolidate procurement around documented supply chain audit trails. Smallholder farmers in Maharashtra's vegetable belt exhibit the highest price sensitivity, while European cosmetics manufacturers demonstrate the lowest.
Supply Chain Analysis
Neem kernel supply rests on orchard networks concentrated across India, with secondary sourcing corridors in Myanmar and limited African cultivation. Raw material dependencies include azadirachtin-rich kernels, cold-press processing equipment, and pharmaceutical-grade solvent systems for extraction. Single-source vulnerability emerges from India's dominance of BIS-certified organic agricultural input corridors and monsoon-dependent harvest concentration. Distribution runs through direct-to-cooperative bulk agreements in Maharashtra and Gujarat, bypassing traditional distributor markups for large agricultural input manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neem extract margin expansion hinges on supercritical CO2 extraction technology cost curves flattening and European cosmetics buyers accelerating premium-tier procurement. Captive orchard control and certification infrastructure investments separate viable long-term operators from commodity-margin toll processors.
For Market Incumbents: Deploy captive orchard expansion to secure azadirachtin consistency guarantees against synthetic pyrethroid substitution threats. Backward integration into Tamil Nadu and Karnataka kernel sourcing buffers monsoon price volatility. Reinforce BIS certification infrastructure to maintain access to consolidating agricultural cooperative procurement in Maharashtra and Gujarat. For New Entrants and Emerging Players: Capture underpenetrated dermatological and oral hygiene ingredient demand in Gujarat's pharmaceutical corridors. Gujarat offers the most penetrable geography due to Fortune Biotech's singular pharmaceutical-grade positioning and limited mid-tier competition. A toll-processing partnership with established extraction infrastructure accelerates market entry without capital-intensive orchard development. For Investors and Strategic Acquirers: Consolidation pressure builds where small-scale extractors lack certified organic supply chain documentation for European cosmetics and pharmaceutical buyer compliance. Long-term viability favors plantation-integrated operators with supercritical CO2 capabilities and documented BIS audit trails. The signal to watch is India's PLI scheme extension to biopesticide processing facilities, which would reshape capital barriers and competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Orchard Expansion | Azadirachtin consistency guarantees defend margin position against commodity powder competitors. |
| Supercritical CO2 Infrastructure Investment | European EFSA-compliant extraction opens pharmaceutical-grade premium tiers previously inaccessible. |
| BIS Certification Acceleration | Documented audit trails maintain access to consolidating Maharashtra and Gujarat cooperative procurement. |
| Modular Formulation Kit Development | Point-of-use blending systems create service revenue beyond commodity powder sales to agricultural buyers. |
| Direct-to-Cooperative Channel Buildout | Bypassing distributor markups captures margin from agricultural input manufacturer bundling strategies. |
Research Approach
Bottom-up agricultural and pharmaceutical end-use modeling reconciled against top-down neem kernel supply tracking forms the analytical core of this study. Primary interviews with extraction plant managers, agricultural cooperative procurement heads, pharmaceutical R&D directors, and European cosmetics formulation scientists combined with secondary validation from Central Insecticides Board registration databases, FSSAI extract purity filings, EU REACH toxicological dossier submissions, and BIS certification records. Trade data from India's DGFT and customs records triangulate against cooperative procurement volume disclosures.
Input-output matrices map azadirachtin concentration tiers, formulation types, and certification grades against regional cultivation clusters and regulatory compliance pathways over the projection horizon. Segmentation dimensions include product type, application end-use, formulation certification tier, and distribution channel structure. CAGRs derive from volume-weighted average growth across these segments, incorporating kernel harvest yield assumptions, BIS purity benchmark tightening trajectories, and European cosmetics procurement acceleration patterns.
Monsoon failure frequency, BIS regulatory tightening velocity, and synthetic biopesticide substitution rates are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Stored Grain Insecticides Market