
 Poultry Feed Premix Market | 2026-2036
Poultry Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Feed Premix Market Outlook
Premium and commodity poultry feed premix tiers is decoupling along traceability and certification lines. Cargill leverages its captive ingredient sourcing to lock in supply security for large integrators. DSM-Firmenich differentiates through precision vitamin matrices tailored to regional flock genetics. Kemin Industries anchors its position with antioxidant and gut health premixes that reduce prophylactic antibiotic dependence.
Poultry feed premix denotes a concentrated blend of vitamins, minerals, amino acids, and functional additives dosed at 0.5–3% of finished feed weight, manufactured via multi-stage micro-dosing and thermal-stabilized blending to ensure nutrient homogeneity and shelf stability. Its commercial purpose centers on closing dietary gaps in base grain rations to optimize feed conversion ratios, egg shell quality, and breast meat yield in broiler and layer operations. Medicated premix retains volume leadership where regulatory windows permit coccidiostat inclusion, while amino acid premix captures margin expansion as low-protein diet formulations spread among cost-sensitive integrators. Specialty premix, spanning enzymes and organic acidifiers, is outgrowing legacy mineral premix in markets with phased antibiotic reduction mandates.
The EU Green Deal and FDA's Veterinary Feed Directive reshape product portfolios by restricting medicated premix claims and elevating documentation burdens for cross-border shipments. Brazil's MAPA and India's FSSAI enforce divergent mycotoxin and heavy metal thresholds, forcing multi-plant operators to maintain parallel formulation registries. Stakeholders must monitor how carbon-accounting rules migrate from voluntary feed lifecycle programs into binding import standards for poultry meat exports.
Market Dynamics
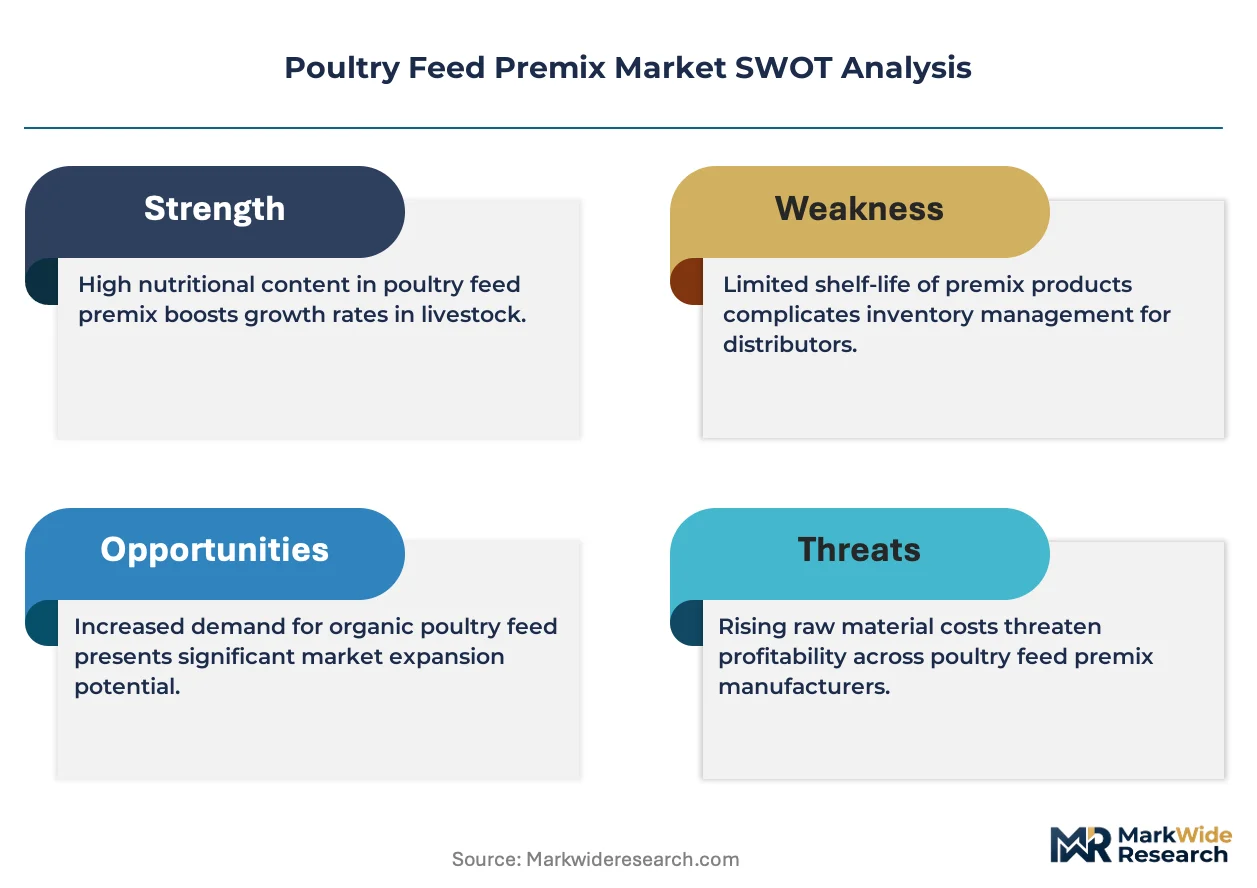
Antibiotic reduction mandates across Brazil, the EU, and the US are forcing premix formulators to rebuild portfolios around gut health modulators and precision micronutrient delivery systems that maintain performance without prophylactic drugs.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Binding antibiotic-use ceilings in member states are redirecting integrator procurement toward functional premix alternatives that support flock health through nutrition rather than medication.
- Layer operations in Brazil's integrated belt:Vertically aligned producers are standardizing premix specifications across their feed mills to achieve traceable micronutrient uniformity at scale.
- Near-infrared spectroscopy:Real-time premix composition verification at receiving bays is reducing nutrient variance penalties and accelerating contract renewals with quality-guaranteed suppliers.
Market Restraints
- Vitamin D3 and B12 input volatility:Concentrated production of these micronutrients in China creates price transmission risk that compresses premix margin structures during supply shocks.
- Technical limitation of organic mineral bioavailability:Chelate stability under high-temperature pelleting remains inconsistent, forcing formulators to overfortify and absorb cost premiums.
- Regulatory friction from divergent mycotoxin thresholds:Brazil's MAPA and India's FSSAI enforce non-aligned heavy metal limits, compelling multi-plant operators to maintain parallel formulation registries and duplicate testing protocols.
Strategic Opportunities
- Carbon-accounting migration into binding import standards:Feed lifecycle programs in the EU are positioning low-carbon premix sourcing as a compliance gateway for poultry meat exports into member states.
- Enzyme-premix convergence with phytase and NSPase cocktails:Low-protein diet formulations among cost-sensitive integrators are opening margin expansion in amino acid premix categories that reduce soybean meal dependence.
- Direct-to-integrator digital channels:Large Brazilian and US producers are bypassing distributor tiers for micronutrient procurement, creating disintermediation pathways for formulators with technical service capabilities.
Industry Challenges
- Micro-dosing equipment calibration expertise:Premix plants require technicians capable of maintaining CV below 5% across vitamin inclusion rates measured in parts per million, a skill scarce in emerging production geographies.
- Dual-registration burden for medicated premix:FDA's Veterinary Feed Directive and state-level feed control officials impose overlapping documentation requirements that extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Feed Premix Market |
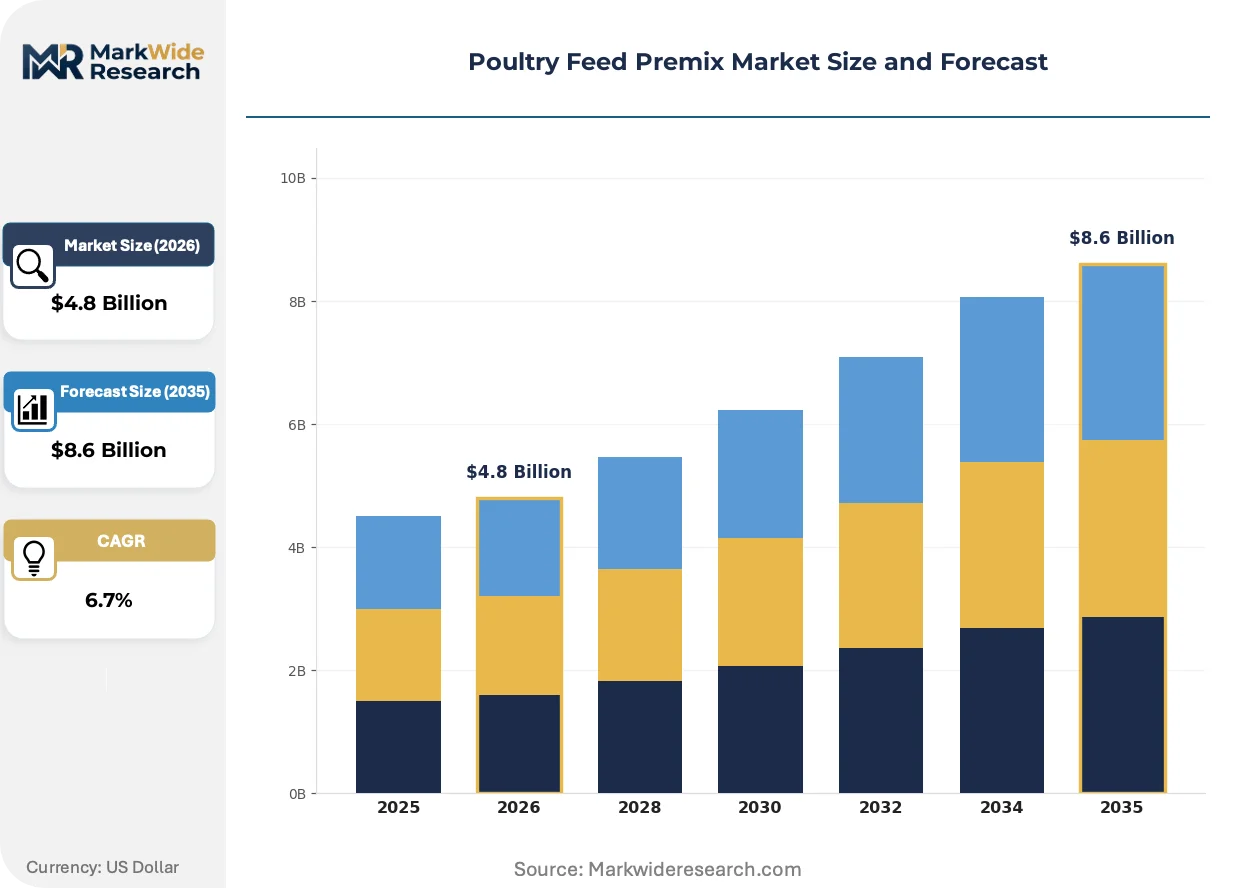
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medicated, Non-Medicated, Specialty, Organic Formulation Type: Vitamin Premix, Mineral Premix, Amino Acid Premix, Herbal Premix End User: Poultry Farms, Commercial Producers, Integrators, Feed Manufacturers Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Cargill, Kemin Industries, Alltech, ForFarmers, Novus International, ADM, DSM-Firmenich, Nutreco, Land O'Lakes Purina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Feed Premix Market Strategic Shifts
Formulation science is pivoting from standard fortification toward precision nutrition systems that align micronutrient matrices with genetic potential, climate stress exposure, and residue-free production protocols.
Robotic micro-dosing lines with gravimetric loss-in-weight feeders are automating batch consistency in high-throughput premix plants. Large integrators in Brazil and the US are retrofitting facilities with these systems to reduce human error in vitamin inclusion. This automation is compressing the competitive window for smaller regional blenders lacking capital access to equivalent quality infrastructure.
REACH and the EU Green Deal are tightening documentation burdens for cross-border premix shipments containing coccidiostats or antibiotic growth promoters. Industrial consequence includes portfolio pruning of medicated claims in favor of zootechnical additive registrations. Layer operations in northern EU member states are most affected, responding by consolidating supplier bases to those with established EU-wide regulatory affairs capabilities.
Integrator procurement departments are unbundling premix specifications from compound feed contracts to negotiate micronutrient supply separately. This disintermediation is disrupting traditional feed mill channels in Brazil's São Paulo and Paraná clusters. The shift is most visible among top-ten Brazilian poultry producers seeking direct relationships with vitamin and trace mineral houses for price transparency and supply security.
Poultry Feed Premix Market Segmentation
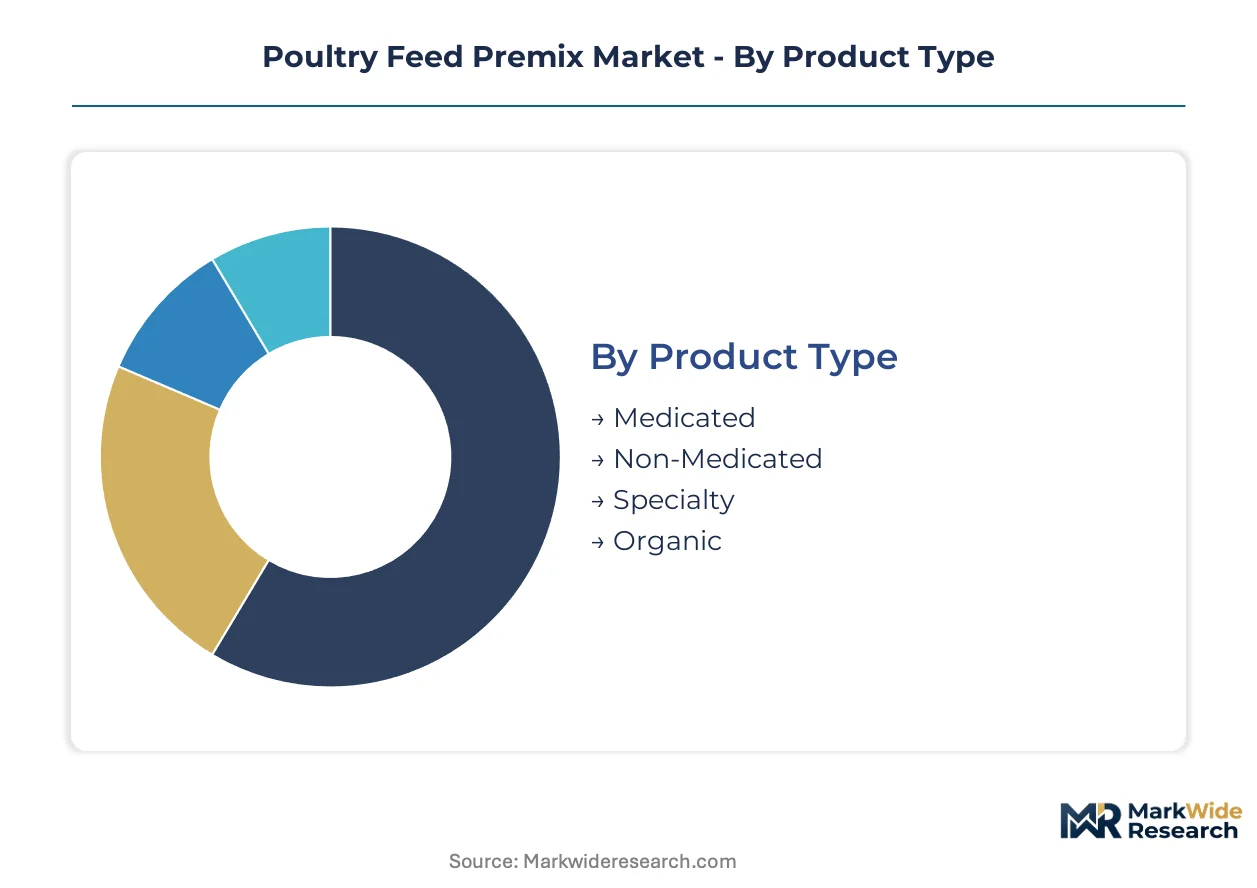
Poultry feed premix segmentation reflects divergent paths between standardized commodity blends and precision-formulated solutions tailored to genetic lines, climate stress, and residue-free production mandates. Formulators calibrate portfolio depth across each axis to capture margin pools opened by antibiotic reduction timelines and integrator consolidation.
Product Type:
The customization-vs-standardization spectrum runs from legacy medicated formulations with constrained regulatory windows to fully traceable organic premixes commanding certification premiums.
- Medicated:Concentrated blends incorporating coccidiostats and antibiotic growth promoters where FDA Veterinary Feed Directive and EU Green Deal timelines still permit therapeutic claims. Demand concentrates among US and Brazilian integrators operating in jurisdictions with phased reduction schedules.
- Specialty:Enzyme, probiotic, and organic acidifier matrices engineered for gut health modulation without prophylactic drugs. Expansion is steepest in northern EU member states where binding antibiotic ceilings have already taken effect.
- Non-Medicated:Standard vitamin-mineral fortification for residue-free production protocols, typically specified by export-oriented Brazilian and Thai integrators supplying EU retail channels.
- Organic:Certified organic micronutrient sourcing with full batch traceability, capturing price premiums from EU and North American retail label requirements.
Most installed capacity flows through Medicated. Expansion is steepest in Specialty.
Formulation Type:
Margin structures vary by input concentration and thermal stability requirements, with amino acid premixes capturing widening spreads as low-protein diet formulations proliferate.
- Amino Acid Premix:Precision-balanced lysine, methionine, and threonine matrices enabling 1-2 percentage point reductions in soybean meal inclusion. Demand concentrates among cost-sensitive Brazilian integrators facing volatile oilseed futures.
- Vitamin Premix:Thermally stabilized fat- and water-soluble vitamin matrices dosed at 0.5-1.5% inclusion, with D3 and B12 sourcing concentrated in Chinese supply chains creating price transmission risk.
- Mineral Premix:Inorganic and organic trace element blends, with chelate bioavailability limitations under high-temperature pelleting forcing overfortification cost absorption.
- Herbal Premix:Phytogenic additive matrices positioned as natural performance enhancers, gaining trial among EU layer operations seeking zootechnical claim alternatives.
Volume leadership sits with Vitamin Premix. Value expansion concentrates in Amino Acid Premix.
End User:
Procurement sophistication determines specification granularity, with vertically aligned integrators unbundling micronutrient supply from compound feed contracts.
- Integrators:Vertically coordinated poultry operations standardizing premix specifications across owned feed mills, demanding direct supplier relationships for price transparency and supply security.
- Commercial Producers:Large independent operations prioritizing flock uniformity and feed conversion optimization through precision micronutrient matrices.
- Feed Manufacturers:Compound feed mills sourcing premix as intermediate input, increasingly disintermediated as integrators bypass distributor tiers.
- Poultry Farms:Smaller independent operations typically served through wholesale channels with standardized specification portfolios.
Contract value concentrates with Integrators. Technical service intensity is highest with Commercial Producers.
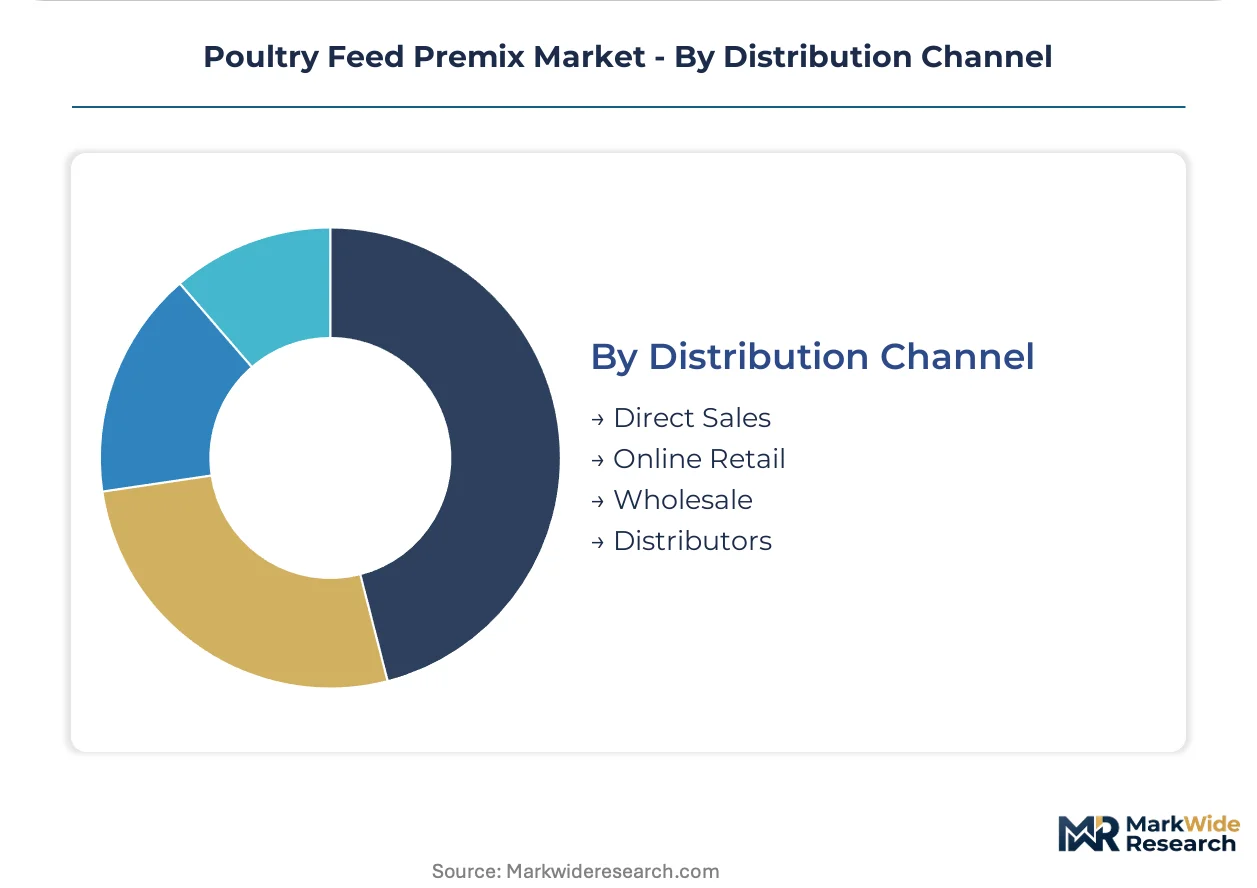
Distribution Channel:
Channel selection tracks customer scale and specification complexity, with digital procurement penetrating largest accounts first.
- Direct Sales:Technical service teams embedded with top-ten Brazilian and US poultry producers, handling specification negotiation and real-time formulation adjustments.
- Distributors:Regional blenders and agricultural supply houses serving mid-tier operations with inventory buffering and credit terms.
- Wholesale:Volume throughput channels for standardized premix specifications with limited customization.
- Online Retail:Emerging platform procurement for smaller operations, constrained by micronutrient stability concerns in non-temperature-controlled logistics.
Revenue concentration flows through Direct Sales. Platform investment is accelerating in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized feed formulators and regulatory compliance specialists concentrate in jurisdictions with stringent antibiotic reduction mandates and vertically integrated poultry production. Talent pools with expertise in micronutrient matrix calibration and mycotoxin risk management anchor regional competitive advantages.
Brazil
Vertically aligned integrators in São Paulo and Paraná states are standardizing premix specifications across owned feed mills to achieve traceable micronutrient uniformity. ANVISA and MAPA enforce phased antibiotic reduction schedules that redirect procurement toward functional gut health premixes. The São Paulo-Paraná poultry belt hosts the densest concentration of direct supplier relationships between vitamin houses and top-ten producers.
United States
Large integrators in the Southeast and Midwest are retrofitting feed mills with robotic micro-dosing lines to reduce human error in vitamin inclusion rates. FDA's Veterinary Feed Directive imposes overlapping documentation requirements with state-level feed control officials that extend product launch timelines. Georgia and Arkansas operations lead adoption of near-infrared spectroscopy for real-time premix composition verification at receiving bays.
Germany
Northern layer operations are consolidating supplier bases to firms with established EU-wide regulatory affairs capabilities following REACH and EU Green Deal documentation tightening. The EU Green Deal's farm-to-fork binding antibiotic-use ceilings have already eliminated most medicated premix claims. Lower Saxony's intensive poultry zones exhibit the fastest shift toward zootechnical additive registrations and organic-certified micronutrient sourcing.
China
Concentrated vitamin D3 and B12 production creates price transmission risk that compresses premix margin structures during supply shocks. The country's national feed safety regulator enforces evolving mycotoxin and heavy metal thresholds that force reformulation for export-oriented processors. Shandong and Guangdong provinces host the primary manufacturing clusters serving both domestic integrators and international premix blenders.
India
Cost-sensitive integrators in Haryana and Telangana are trialing low-protein diet formulations that expand amino acid premix demand to reduce soybean meal dependence. FSSAI enforces mycotoxin thresholds that diverge from Brazilian and EU standards, compelling multi-plant operators to maintain parallel formulation registries. The Haryana-Punjab poultry corridor shows accelerating procurement disintermediation as mid-sized producers bypass compound feed distributors.
Poultry Feed Premix Market Competitive Environment
Top-tier vendors anchor integrated micronutrient supply, while regional blenders compete on specification agility and technical service proximity. The vendor base stratifies across three tiers: multinational nutrition houses with captive ingredient sourcing, mid-scale specialists in functional additives, and commodity blenders serving price-sensitive independents. Two strategic archetypes dominate: precision nutrition formulators aligning matrices with genetic lines, and supply security providers locking in backward integration over vitamin and trace mineral inputs. Capacity expansion in robotic micro-dosing infrastructure and geographic licensing of zootechnical additive registrations represent the dominant competitive moves.
Among diversified agribusiness conglomerates, Cargill exemplifies the supply security archetype through its captive ingredient sourcing capabilities. DSM-Firmenich occupies a position within the precision nutrition tier, while Kemin Industries anchors the functional additive specialist segment. These three entities represent distinct strategic postures: integrated supply chain control, regional genetic customization, and gut health modulation expertise respectively.
| Leading Market Players |
|---|
| Cargill |
| Kemin Industries |
| Alltech |
| ForFarmers |
| Novus International |
| ADM |
| DSM-Firmenich |
| Nutreco |
| Land O'Lakes Purina |
| Others |
Value Chain & Pricing Dynamics
Robotic micro-dosing line adoption across Brazilian and US feed mills simultaneously compresses per-unit production costs and consolidates manufacturing scale among capital-rich integrators, squeezing regional blenders unable to match equivalent quality infrastructure. This automation-driven bifurcation concentrates pricing power with suppliers of precision-formulated matrices while commoditizing standardized vitamin-mineral blends.
Pricing Analysis
Bundled compound feed contracts are unbundling into separate micronutrient procurement negotiations, with integrators demanding price transparency on standalone premix specifications. Three-tier pricing structure across organic-certified, precision-formulated, and commodity-standard levels reflects traceability grade and thermal stability performance. Pricing pressure stems from vitamin D3 and B12 input volatility concentrated in Chinese supply chains. Cost-sensitive independent poultry farms exhibit highest price sensitivity; vertically aligned integrators prioritize supply security over unit cost.
Supply Chain Analysis
Workforce scarcity in robotic micro-dosing equipment calibration across São Paulo and Paraná feed mill clusters is forcing producers to import technical talent from established EU premix manufacturing centers. Vitamin D3 and B12 production concentrates in China, while robotic dosing equipment draws from German and Japanese precision engineering suppliers. Single-source vulnerability in Chinese micronutrient supply creates margin compression risk during export restriction episodes. Distribution runs through direct technical service teams for top-ten integrators, with regional distributors serving mid-tier independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as antibiotic reduction mandates across the EU Green Deal and FDA Veterinary Feed Directive redirect procurement toward precision-formulated gut health matrices commanding certification premiums.
For Market Incumbents: Anchor market position through backward integration into captive vitamin and trace mineral sourcing to insulate margin structures from Chinese supply shocks. Consolidate supplier relationships with top-ten Brazilian and US integrators by embedding technical service teams capable of real-time formulation adjustments. Defensive priority rests on maintaining EU-wide regulatory affairs capabilities as REACH documentation burdens tighten. For New Entrants and Emerging Players: Launch via direct-to-integrator digital channels bypassing traditional compound feed distributor tiers in Brazil's São Paulo-Paraná poultry belt. White-space targets include mid-sized Indian integrators in Haryana trialing low-protein diet formulations and EU layer operations seeking zootechnical additive alternatives to medicated claims. Specialty enzyme-premix convergence with phytase cocktails offers the most penetrable entry vector. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders with established mycotoxin risk management capabilities and parallel formulation registries for multi-jurisdiction compliance. Long-term viability over the next decade hinges on carbon-accounting migration into binding import standards for poultry meat exports. Monitor EU feed lifecycle program adoption rates as the inflection signal for low-carbon premix sourcing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Micro-Dosing Infrastructure Deployment | Reduces human error in vitamin inclusion rates below 5% CV for Brazilian integrators. |
| Backward Integration into Vitamin Sourcing | Locks supply security for D3 and B12 inputs against Chinese export restriction risk. |
| EU Regulatory Affairs Capability Buildout | Enables zootechnical additive registrations as REACH eliminates medicated premix claims. |
| Direct-to-Integrator Digital Channel Launch | Bypasses distributor tiers for price transparency with top-ten poultry producers. |
| Carbon-Accounting Certification Program | Positions low-carbon premix sourcing as compliance gateway for EU poultry meat imports. |
Study Parameters
Bottom-up integrator procurement modeling reconciled against top-down vitamin house production tracking forms the analytical core of this study. Primary interviews with feed mill operations directors, premix formulation scientists, regulatory affairs specialists at ANVISA and FDA, and procurement leads at vertically aligned poultry producers combined with secondary validation from EU Green Deal policy documents, FDA Veterinary Feed Directive filings, Brazilian MAPA mycotoxin threshold regulations, and customs trade data on vitamin concentrate imports.
Input-output matrices mapping micronutrient inclusion rates to finished feed tonnage across the projection horizon generate volume estimates segmented by product type, formulation category, end-user procurement sophistication, and distribution channel structure. CAGRs derive from regression analysis of historical premix adoption curves against antibiotic reduction timeline enforcement. Industry-specific forecast inputs include near-infrared spectroscopy adoption rates and robotic dosing line installation data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt Chinese vitamin export restrictions or accelerated EU carbon-border adjustment implementation. Forecasts reflect documented assumptions regarding regulatory phase-in schedules and integrator consolidation trajectories. Practitioners should monitor ANVISA antibiotic reduction enforcement intensity and EU feed lifecycle program binding adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
China Feed Enzymes Market
Agricultural Chemicals
Global Agricultural Fumigants Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Europe Swine Feed Premix Market