
 Middle East Feed Binders Market | 2026-2036
Middle East Feed Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Feed Binders Market Foresight
The capital-intensity divergence between multinational suppliers and regional distributors is rotating competitive advantage toward integrated manufacturers with captive raw material sourcing. Borregaard leverages its lignin-based binder technology to dominate premium pellet formulations across Gulf state feed mills. Cargill Incorporated anchors its position through backward integration into guar gum supply chains originating from Indian subcontinent processing plants. Kemin Industries Inc. differentiates via specialized coating technologies that improve pellet durability in arid storage conditions prevalent across Middle Eastern logistics networks.
Feed binders comprise adhesive compounds—typically lignosulfonates, bentonite clays, or molasses-based formulations—that mechanically stabilize compound feed pellets during handling, transport, and rumen exposure, with binding strength measured by pellet durability index (PDI) thresholds exceeding 90% for commercial ruminant applications. Binders within the product type category command the deepest margin pools due to technical formulation complexity and customer switching costs, while pellet formulations sustain the fastest growth trajectory as large-scale feed mills automate pelleting lines across Saudi Arabia and UAE. The livestock end-user segment occupies the volume core, though aquaculture applications in Oman and Bahrain are extending demand into specialized marine binder chemistries resistant to water degradation.
SFDA enforcement of feed safety standards and UAE's MOHAP veterinary product registration requirements are elevating documentation burdens for imported binder formulations, effectively filtering non-compliant suppliers from Gulf distribution channels. Saudi Arabia's Quality of Life Program and national food security strategies are directing capital toward domestic feed manufacturing capacity, tightening local content expectations for binder procurement. Stakeholders must monitor how GCC harmonization of feed additive regulations reshapes cross-border product registration requirements and manufacturing location decisions.
Market Dynamics
SFDA enforcement of pellet durability standards is compressing supplier margins while rotating procurement authority toward feed mill technical teams capable of validating binder performance under arid storage protocols.
Growth Catalysts
- Saudi Quality of Life Program:Capital allocation toward domestic feed manufacturing capacity is expanding automated pelleting line deployment across the central dairy corridor.
- SFDA Feed Safety Protocols:Mandatory pellet durability index thresholds above 90% for commercial ruminant applications are eliminating low-performance binder formulations from Gulf distribution channels.
- Aquaculture expansion:Specialized marine binder chemistries resistant to water degradation are capturing new demand from shrimp and finfish operations in Oman and Bahrain.
Market Restraints
- Guar gum supply concentration:Backward integration into Indian subcontinent processing plants leaves regional distributors exposed to monsoon-driven harvest volatility and export duty fluctuations.
- Lignin technical limitation:Borregaard's proprietary extraction technology creates formulation lock-in that prevents feed mills from multi-sourcing premium pellet binders without revalidating entire production runs.
- UAE MOHAP registration friction:Veterinary product documentation burdens extend approval timelines for imported binder formulations, filtering non-compliant suppliers from Emirates distribution networks.
Strategic Opportunities
- Qatar underpenetration:Limited domestic feed manufacturing infrastructure creates first-mover advantage for binder suppliers establishing technical service partnerships with emerging dairy cooperatives.
- Coating technology convergence:Integration of specialized moisture-barrier chemistries with traditional binding agents addresses pellet degradation during high-temperature Gulf logistics.
- Kuwait food security mandate:National self-sufficiency targets for protein production are redirecting procurement budgets toward localized feed additive sourcing with domestic blending requirements.
Industry Challenges
- Formulation chemist scarcity:Gulf universities produce limited graduates capable of optimizing binder-pelleting parameter interactions for high-temperature extrusion systems.
- SFDA certification timeline compression:Accelerated feed safety audit cycles strain quality assurance teams at regional distributors managing multi-origin product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Feed Binders Market |
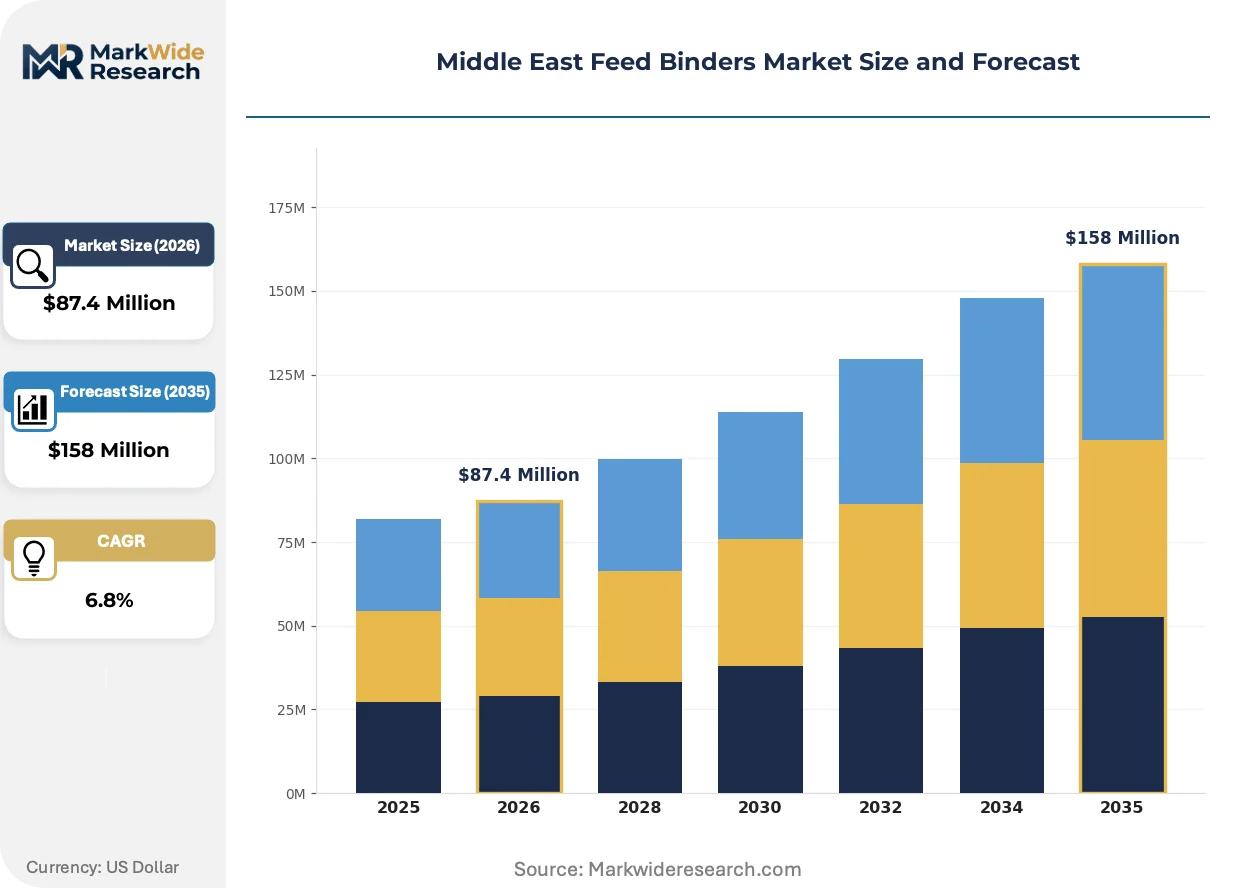
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binders, Additives, Coatings, Fillers Formulation: Granules, Powders, Liquids, Pellets End User: Livestock, Poultry, Aquaculture, Pet Food Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Kemin Industries Inc., Borregaard, Cargill Incorporated, CP Kelco, Beneo GmbH, Archer Daniels Midland Company, Adisseo, FMC Corporation, Alltech, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Feed Binders Market Shifts & Advancements
Active reformulation of binder chemistries is reshaping competitive positioning as feed mills prioritize pellet stability metrics over raw material cost minimization in procurement decisions.
Encapsulated lignosulfonate complexes with modified release profiles are replacing conventional molasses-based binders in high-value dairy concentrates. Saudi Arabia's largest vertically integrated feed operations are adopting these formulations at pilot scale before full pelleting line conversion. This technology is miniaturizing the performance gap between premium imported binders and locally blended alternatives.
SFDA alignment with Codex Alimentarius feed additive standards is elevating documentation requirements for cross-border binder shipments. Regional distributors must now maintain batch-specific stability testing records traceable to manufacturing origin. Large compound feed mills in Riyadh and Dammam are responding by consolidating supplier relationships with integrated manufacturers possessing captive laboratory certification capabilities.
Technical service unbundling from product supply is compressing traditional distributor margins across UAE poultry clusters. Feed mill procurement teams now separately negotiate formulation advisory contracts with independent nutrition consultants while sourcing commodity binders through lowest-validated-bid channels. This pattern is most visible among mid-scale broiler operations in Al Ain seeking to decouple pellet quality accountability from material procurement decisions.
Middle East Feed Binders Market Segmentation
Feed binder procurement across the Middle East fragments across technical specifications, formulation formats, and species-specific end-uses. SFDA and MOHAP regulatory frameworks create divergent compliance pathways that reshape how suppliers structure their product portfolios for Gulf state markets.
Product Type:
SFDA feed safety protocols impose distinct documentation burdens on each product category, with pellet durability index validation requirements varying by functional classification.
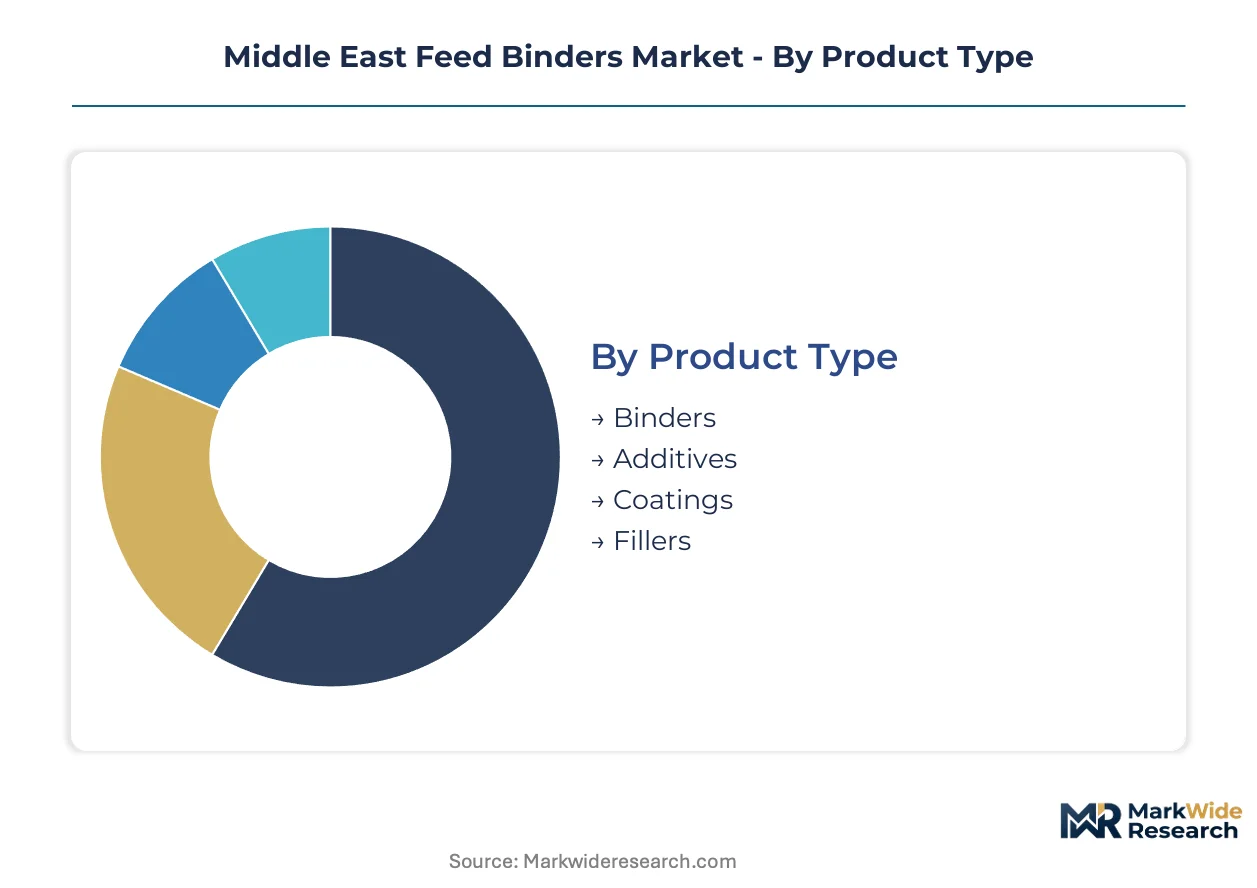
- Binders:Adhesive compounds—lignosulfonates, bentonite clays, molasses-based formulations—mechanically stabilize compound feed pellets during handling, transport, and rumen exposure. Binding strength measured by pellet durability index thresholds exceeding 90% for commercial ruminant applications concentrates demand in Saudi Arabia's central dairy corridor where large-scale feed mills automate pelleting lines.
- Additives:Functional compounds that enhance nutritional uptake or preservation characteristics beyond mechanical binding. Procurement authority for these formulations is rotating toward feed mill technical teams capable of validating performance under arid storage protocols prevalent across Middle Eastern logistics networks.
- Coatings:Specialized moisture-barrier chemistries applied to finished pellets. Kemin Industries leverages proprietary coating technologies to improve pellet durability in high-temperature Gulf logistics conditions.
- Fillers:Inert bulking agents that adjust pellet density and cost structure. These formulations face margin compression as feed mills prioritize pellet stability metrics over raw material cost minimization.
Established volume favors binders; emerging adoption favors coatings.
Formulation:
Physical format selection determines compatibility with automated pelleting infrastructure and storage resilience across Saudi Arabia and UAE distribution networks.
- Granules:Coarse particulate formulations suited for batch mixing operations in mid-scale feed operations. Al Ain broiler clusters favor these formats for flexibility in ration adjustment.
- Powders:Fine-ground binder chemistries requiring dust-controlled handling systems. Large compound feed mills in Riyadh and Dammam are consolidating supplier relationships with integrated manufacturers possessing captive laboratory certification capabilities for powder stability validation.
- Liquids:Molasses-based and synthetic resin solutions applied via spray systems during extrusion. These formats are gaining share fastest among vertically integrated dairy operations in Saudi Arabia's Quality of Life Program expansion zones.
- Pellets:Pre-formed binder concentrates that disperse uniformly during feed processing. Automated pelleting line deployment across the central dairy corridor is expanding demand for this format.
Volume concentration sits with powders; steepest expansion trajectory belongs to liquids.
End User:
Species-specific digestive physiology and feed handling requirements create distinct binder performance specifications across livestock categories.
- Livestock:Ruminant applications command the deepest margin pools due to technical formulation complexity and customer switching costs. Saudi Arabia's national food security strategies are directing capital toward domestic feed manufacturing capacity for this segment.
- Poultry:Broiler and layer operations in UAE poultry clusters are decoupling pellet quality accountability from material procurement decisions through separate advisory contracts.
- Aquaculture:Specialized marine binder chemistries resistant to water degradation are capturing new demand from shrimp and finfish operations in Oman and Bahrain.
- Pet Food:Premium companion animal formulations requiring palatability-enhancing binders. This segment remains underpenetrated relative to production animal applications across Gulf state markets.
Revenue concentration favors livestock; technology differentiation favors aquaculture.
Distribution Channel:
Channel selection reflects feed mill scale, technical service requirements, and regulatory documentation burdens under SFDA and MOHAP frameworks.
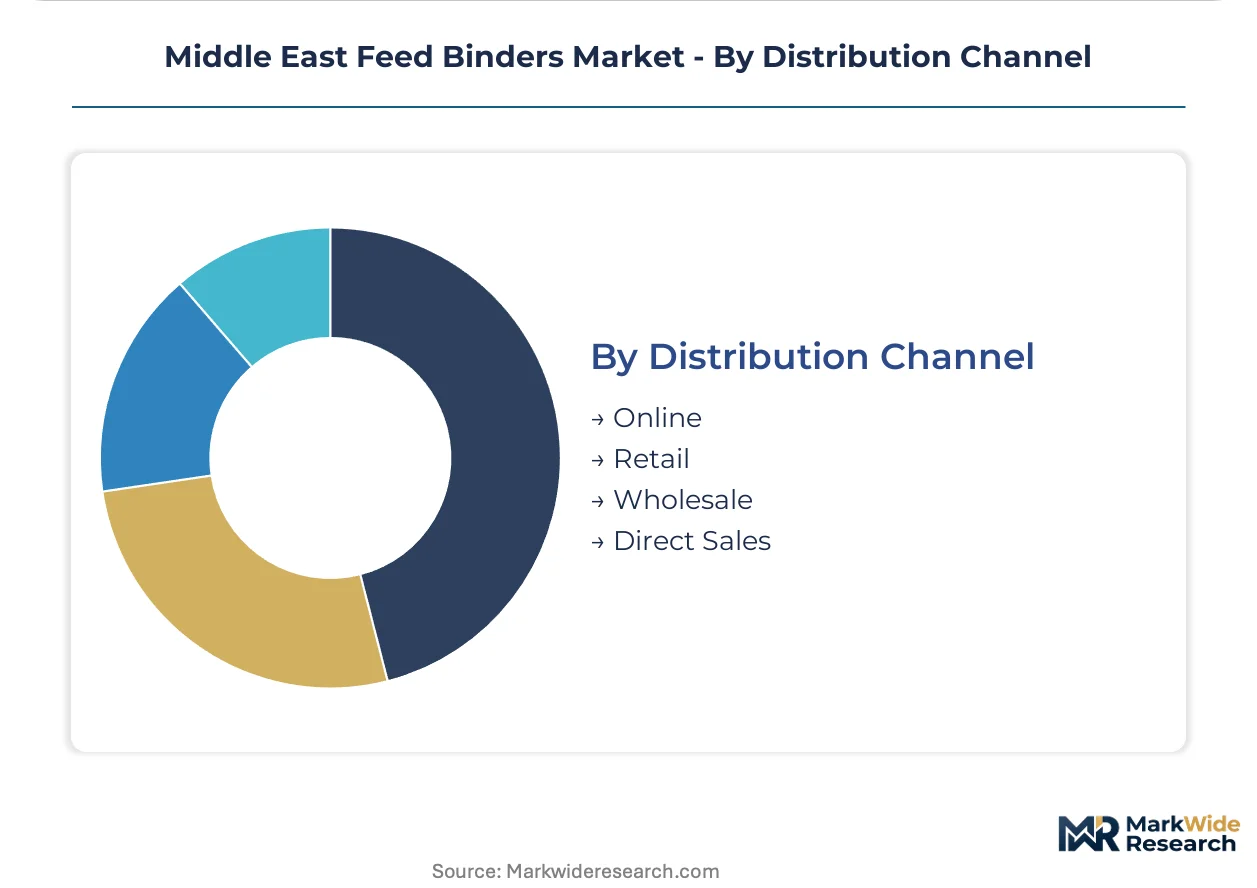
- Online:Digital procurement platforms emerging for standardized binder formulations with established stability profiles. Limited penetration in premium pellet applications requiring technical validation.
- Retail:Counter sales serving smallholder operations and specialty feed producers. This channel faces compression as large-scale feed mills consolidate supplier relationships.
- Wholesale:Bulk distribution through regional distributors managing multi-origin product portfolios. SFDA certification timeline compression is straining quality assurance teams at these intermediaries.
- Direct Sales:Manufacturer-to-mill relationships for integrated technical service and formulation support. Large compound feed operations in Riyadh and Dammam are migrating toward this channel to consolidate pellet quality accountability.
Transaction volume flows through wholesale; margin capture shifts toward direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed binder trade flows across the Middle East tilt toward import dependency, with Gulf states sourcing lignosulfonate and guar gum raw materials from Indian subcontinent processors while exporting finished compound feed formulations to regional livestock operations.
Saudi Arabia
Domestic dairy herd expansion and automated pelleting line deployment across the central dairy corridor drive binder consumption. SFDA enforcement of pellet durability index thresholds above 90% filters low-performance formulations from distribution channels. Riyadh and Dammam host large compound feed mills consolidating supplier relationships with integrated manufacturers.
United Arab Emirates
UAE poultry clusters in Al Ain and Abu Dhabi generate concentrated demand for moisture-resistant pellet coatings. MOHAP veterinary product registration requirements extend approval timelines for imported formulations. Technical service unbundling from product supply compresses traditional distributor margins as procurement teams separately negotiate advisory contracts.
Oman
Shrimp and finfish aquaculture operations along the Batinah coast capture specialized marine binder chemistries resistant to water degradation. The country's national food security initiatives redirect capital toward localized feed additive sourcing. Muscat-based processors are piloting encapsulated lignosulfonate complexes for high-value marine concentrates.
Qatar
Limited domestic feed manufacturing infrastructure creates first-mover positioning for suppliers establishing technical service partnerships with emerging dairy cooperatives. National protein self-sufficiency targets accelerate procurement budget allocation toward automated pelleting infrastructure. Doha industrial zones attract regional distributors seeking warehousing proximity to underserved livestock operations.
Kuwait
National food security mandates redirect procurement budgets toward localized feed additive sourcing with domestic blending requirements. Poultry and ruminant operations in Jahra and Al Ahmadi governorates sustain demand for molasses-based liquid binders applied via spray extrusion systems. Quality assurance teams face compressed SFDA certification audit cycles when managing multi-origin product portfolios.
Middle East Feed Binders Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive raw material sourcing and specialized coating technology capabilities. The vendor base organizes around three strategic archetypes: lignin-based premium formulators, guar gum supply chain integrators, and coating technology specialists. Competitive moves center on backward integration into Indian subcontinent processing plants and technical service partnerships with large-scale feed mill operators.
Among specialty chemical and nutrition companies, Kemin Industries Inc., Borregaard, and Cargill Incorporated occupy distinct positioning vectors. Kemin Industries exemplifies the coating technology archetype through proprietary moisture-barrier chemistries. Borregaard represents lignin-based formulation leadership with extraction technology capabilities. Cargill Incorporated anchors the supply chain integration tier through upstream control over guar gum processing networks.
| Leading Market Players |
|---|
| Kemin Industries Inc. |
| Borregaard |
| Cargill Incorporated |
| CP Kelco |
| Beneo GmbH |
| Archer Daniels Midland Company |
| Adisseo |
| FMC Corporation |
| Alltech |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Saudi feed mills and Indian guar gum processors lock in supply access while capping price visibility against monsoon-driven harvest volatility. These contracts concentrate procurement authority with vertically integrated manufacturers capable of absorbing duty fluctuations without destabilizing pellet cost structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by pellet durability index certification and captive raw material sourcing. Price differentiation rests on SFDA compliance tier and volume scale, with large Riyadh compound feed operations commanding leverage unavailable to mid-scale Al Ain poultry clusters. Cost compression in economy-grade molasses binders is intensifying as feed mills automate pelleting lines and consolidate supplier relationships. Mid-scale broiler operations exhibit highest price sensitivity; vertically integrated dairy corridors show least elasticity due to food security procurement mandates.
Supply Chain Analysis
Inventory buffers at Dubai Jebel Ali free zone warehouses extend to twelve weeks for lignosulfonate formulations, compressing lead-time flexibility for mills requiring rapid formulation switches. Geographic supply concentrates in India for guar gum, Norway for lignin derivatives, and Thailand for bentonite clays. Raw material dependencies include monsoon-sensitive guar seed harvests, sulfite liquor availability from pulp mills, and energy-intensive clay calcination. Single-source vulnerability pervades premium lignin binders where Borregaard's proprietary extraction technology prevents multi-sourcing. Distribution runs through regional distributors managing multi-origin portfolios, though direct manufacturer-to-mill channels are capturing margin from technical service consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulated lignosulfonate complexes and moisture-barrier coating technologies pose credible substitution threats to conventional molasses and bentonite formulations, forcing incumbents to defend formulation lock-in through accelerated certification investments.
For Market Incumbents: Shield premium positioning by deepening captive laboratory certification capabilities that accelerate SFDA audit cycles and compress approval timelines for cross-border shipments. Anchor backward integration into Indian subcontinent guar processing networks to neutralize monsoon volatility and export duty exposure. Prioritize technical service bundling that consolidates pellet quality accountability with material supply, reversing the unbundling pattern eroding distributor margins across UAE poultry clusters. For New Entrants and Emerging Players: SFDA fast-track certification pathways for Codex-aligned binder formulations create entry leverage for suppliers willing to invest in batch-specific stability documentation. Target Qatar's emerging dairy cooperatives where limited domestic feed manufacturing infrastructure leaves procurement teams dependent on external technical partnerships. Pursue coating technology convergence strategies that integrate moisture-barrier chemistries with traditional binding agents, addressing the high-temperature logistics degradation that Kemin Industries currently dominates. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers possessing captive raw material sourcing and specialized coating capabilities, as these archetypes capture margin pools unavailable to pure-play distributors. Monitor Kuwait's domestic blending requirements and Saudi Arabia's Quality of Life Program capital allocation as inflection signals for localized feed additive demand acceleration. The long-term viability window favors suppliers with laboratory certification infrastructure capable of navigating harmonized GCC feed additive regulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Guar Processing | Captive supply from Indian subcontinent plants neutralizes monsoon-driven price volatility for Gulf mills. |
| SFDA Certification Fast-Track Investment | Accelerated audit cycles filter non-compliant suppliers and consolidate procurement authority with certified manufacturers. |
| Coating Technology Convergence | Integration of moisture-barrier chemistries with lignosulfonate binders addresses arid-storage degradation in Saudi logistics. |
| Direct Technical Service Partnerships | Manufacturer-to-mill relationships reverse margin compression from unbundled advisory contracts in UAE poultry clusters. |
| Localized Blending Capacity | Kuwait domestic content requirements redirect procurement budgets toward regional suppliers with in-country formulation facilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with feed mill procurement directors, SFDA regulatory affairs specialists, compound feed plant managers, and veterinary product registration consultants; and secondary validation through customs trade records, SFDA feed safety bulletins, GCC harmonization framework documents, and integrated manufacturer SEC disclosures. Bottom-up volume estimates from species-specific feed consumption patterns triangulated against top-down binder intensity assumptions derived from automated pelleting line deployment rates across the central dairy corridor.
Across the projection horizon, the analytical framework modeled demand trajectories by product type, formulation format, end-user species, and distribution channel, with regional clusters disaggregated by national regulatory pathway. CAGRs were derived from weighted average growth rates across these segmentation dimensions, incorporating inputs from feed manufacturing capacity expansion schedules under Saudi Arabia's Quality of Life Program and aquaculture infrastructure investments in Oman and Bahrain.
Decision-makers should treat outputs as directional under assumptions of sustained SFDA enforcement intensity and stable Indian monsoon patterns; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Feed Minerals Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
North America Agricultural Disinfectants Market