
 South America Plant Growth Regulators Market | 2026-2036
South America Plant Growth Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
South America Plant Growth Regulators Market Analytics
Agricultural input distribution across South America is tilting toward specialized agronomic advisory networks that bundle plant growth regulators with precision farming services. Bayer Crop Science AG leverages its integrated seed-and-crop-protection platform to anchor premium cytokinin formulations across Brazil's soybean frontier. Syngenta Group competes through localized blending operations that sustain shorter lead times for Brazilian citrus cooperatives. Valent BioSciences differentiates via fermentation-derived gibberellin technologies that occupy niche positions in Argentine pome fruit production.
Plant growth regulators comprise synthetic or biologically derived organic compounds that modulate physiological processes in vascular plants, including cell elongation, fruit ripening, and senescence delay, typically applied at concentrations measured in parts per million to achieve targeted hormonal responses without phytotoxicity. Their primary commercial purpose centers on optimizing yield quality, synchronizing harvest windows, and reducing post-harvest losses in high-value cropping systems. Auxin formulations dominate volume flows across South American cereal programs, while cytokinin blends command margin concentration in Brazilian vegetable seedling propagation. Ethylene management applications in climacteric fruit logistics represent the fastest-expanding use case as export cold chains lengthen.
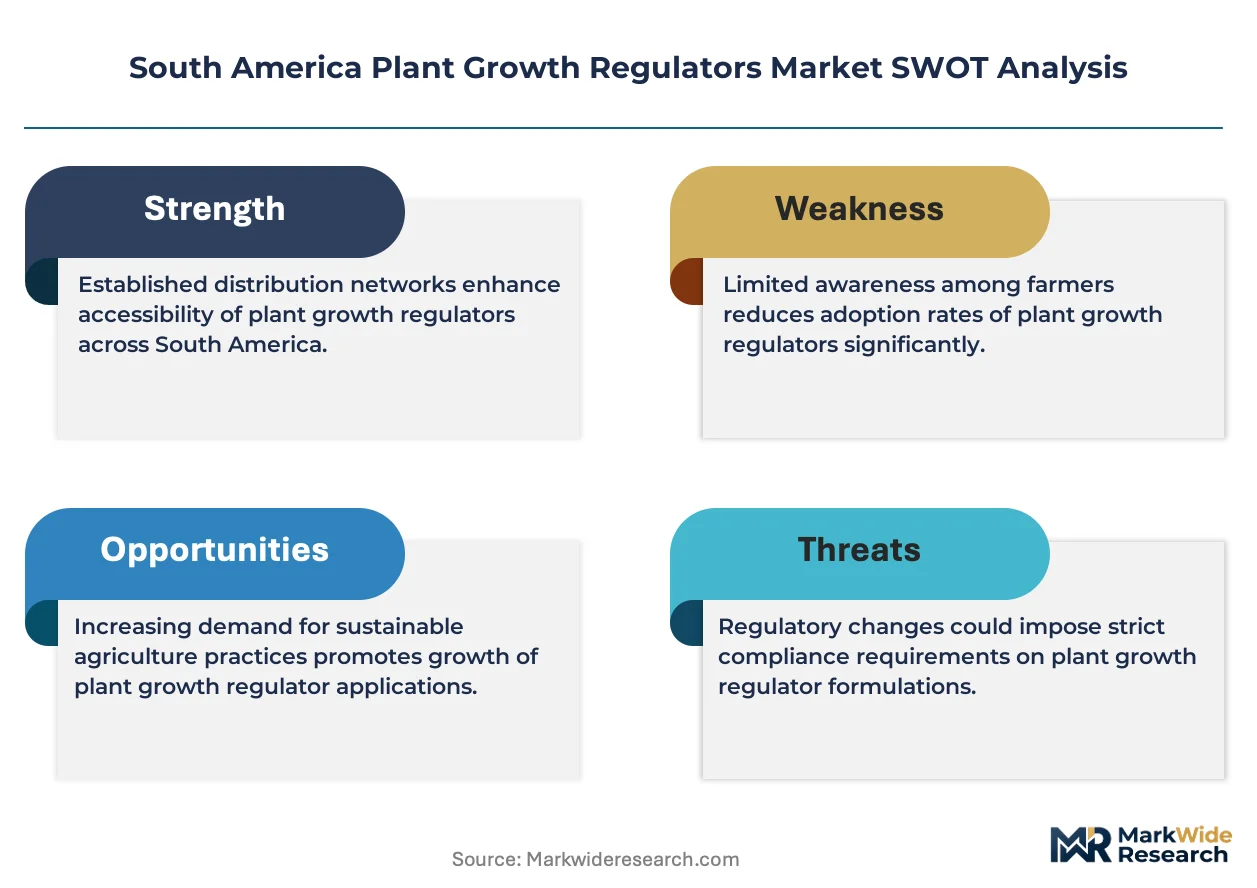
Brazil's national agrochemical regulator, ANVISA, alongside Argentina's SENASA and Colombia's ICA, enforce residue tolerance schedules that directly determine which active ingredients gain commercial registration and farmer trust. REACH-aligned hazard classifications from Europe increasingly influence import acceptance criteria, pressuring formulators to re-register legacy products under tightened toxicological standards. Stakeholders must monitor pending biocide re-evaluations across MERCOSUR harmonization talks, as regulatory divergence between Brazilian and Argentine protocols threatens to fragment procurement strategies for multinational distributors.
Market Dynamics
ANVISA's tightened residue tolerance schedules are compressing registration timelines for imported gibberellin and cytokinin formulations, forcing distributors toward local synthesis partnerships and fragmenting supply reliability across Brazil's citrus belt.
Growth Catalysts
- Cytokinin precision application:Specialty fruit growers in Colombia's coffee highlands deploy targeted cytokinin protocols to synchronize cherry ripening for containerized export. This technology reduces labor costs and improves cup quality scores.
- Ethylene inhibitor cold-chain integration:Brazilian citrus cooperatives in São Paulo state mandate ethylene management treatments as a condition for export-grade certification. Cold storage operators now bundle these applications with logistics contracts.
- REACH-aligned hazard reclassification:Argentina's SENASA adopts European toxicological standards for legacy auxin products. This accelerates reregistration of safer formulations while phasing out chlorinated compounds.
Market Restraints
- Fermentation feedstock volatility:Gibberellin acid production depends on corn steep liquor and soybean meal pricing. Argentine biofermentation facilities face margin compression when commodity markets spike.
- Import concentration risk:Over sixty percent of formulated cytokinin products enter through Santos port. Customs delays at this single node disrupt application windows for time-sensitive vegetable propagation cycles.
- Phytotoxicity threshold limitations:Synthetic auxin formulations carry narrow concentration bands between efficacy and crop damage. Extension agents in Paraguay report farmer reluctance following 2023 tomato field losses.
Strategic Opportunities
- Uruguay's underpenetrated rice sector:Paddy cultivation in Treinta y Tres and Rocha departments currently applies minimal plant growth regulator inputs. Seed treatment protocols for lodging resistance remain undeveloped.
- MERCOSUR biocide harmonization:Pending regulatory convergence between Brazilian ANVISA and Argentine SENASA protocols would enable single-registration products. Formulators preparing unified dossiers gain first-mover advantage.
- Drone-based precision application:UAV spraying services in Brazil's Mato Grosso soybean frontier now integrate variable-rate cytokinin deployment. Equipment-as-service models reduce farmer capital requirements.
Industry Challenges
- Formulation chemist scarcity:Brazilian universities graduate fewer than forty specialized agricultural chemists annually. Multinational distributors compete for this limited talent pool to staff local blending facilities.
- Residue testing laboratory bottlenecks:SENASA-accredited labs in Buenos Aires and Córdoba face six-month backlogs for export certification. Citrus shippers miss optimal shipping windows awaiting clearance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Plant Growth Regulators Market |
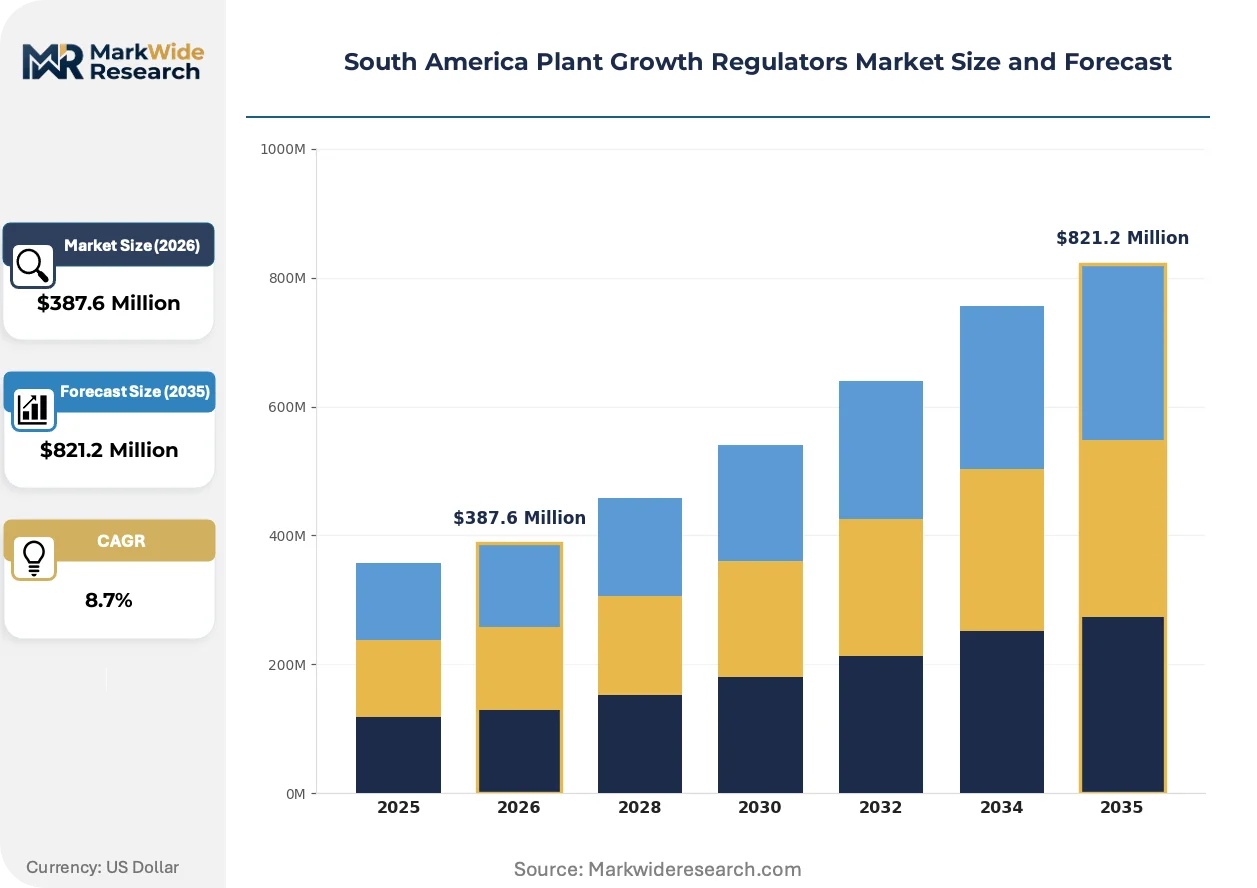
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auxins, Gibberellins, Cytokinins, Ethylene Application: Cereals, Fruits, Vegetables, Ornamentals Distribution Channel: Direct Sales, Online Retail, Distributors, Retail Stores End User: Agriculture, Horticulture, Forestry, Gardening |
| Companies Covered | NuFarm Ltd, Microquimica Tradecorp, Valent BioSciences, Corteva Agriscience, Bayer Crop Science AG, BASF SE, Fine Americas, Inc., FMC Corporation, Syngenta Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Plant Growth Regulators Market Evolving Landscape
Biological fermentation pathways and precision application hardware are displacing synthetic chemistry and broadcast spraying as the dominant technical paradigms across South American high-value cropping systems.
Microbial fermentation of gibberellin GA3 is rendering obsolete petrochemical synthesis routes that dominated Argentine pome fruit programs for decades. Local biotech startups in Mendoza province now supply wineries and orchards with fermentation-derived alternatives at comparable unit economics. This shift compresses capital requirements for new market entrants while reducing hazardous waste disposal liabilities.
ANVISA's 2024 implementation of maximum residue limits aligned with EU Regulation 396/2005 is disqualifying legacy organochlorine formulations from citrus export certification. Brazilian formulators accelerate substitution with microbial-derived ethylene inhibitors to maintain cold-chain access. The regulatory friction most severely affects smallholder cooperatives lacking technical staff to navigate re-registration protocols.
Specialized agronomic advisory networks now bundle plant growth regulator prescriptions with soil sensor data and satellite imagery subscriptions. Brazilian vegetable seedling producers in Minas Gerais state purchase cytokinin protocols through these integrated service contracts rather than standalone chemical procurement. This channel consolidation concentrates purchasing influence among four major advisory platforms operating across the Southeast region.
South America Plant Growth Regulators Market Segmentation
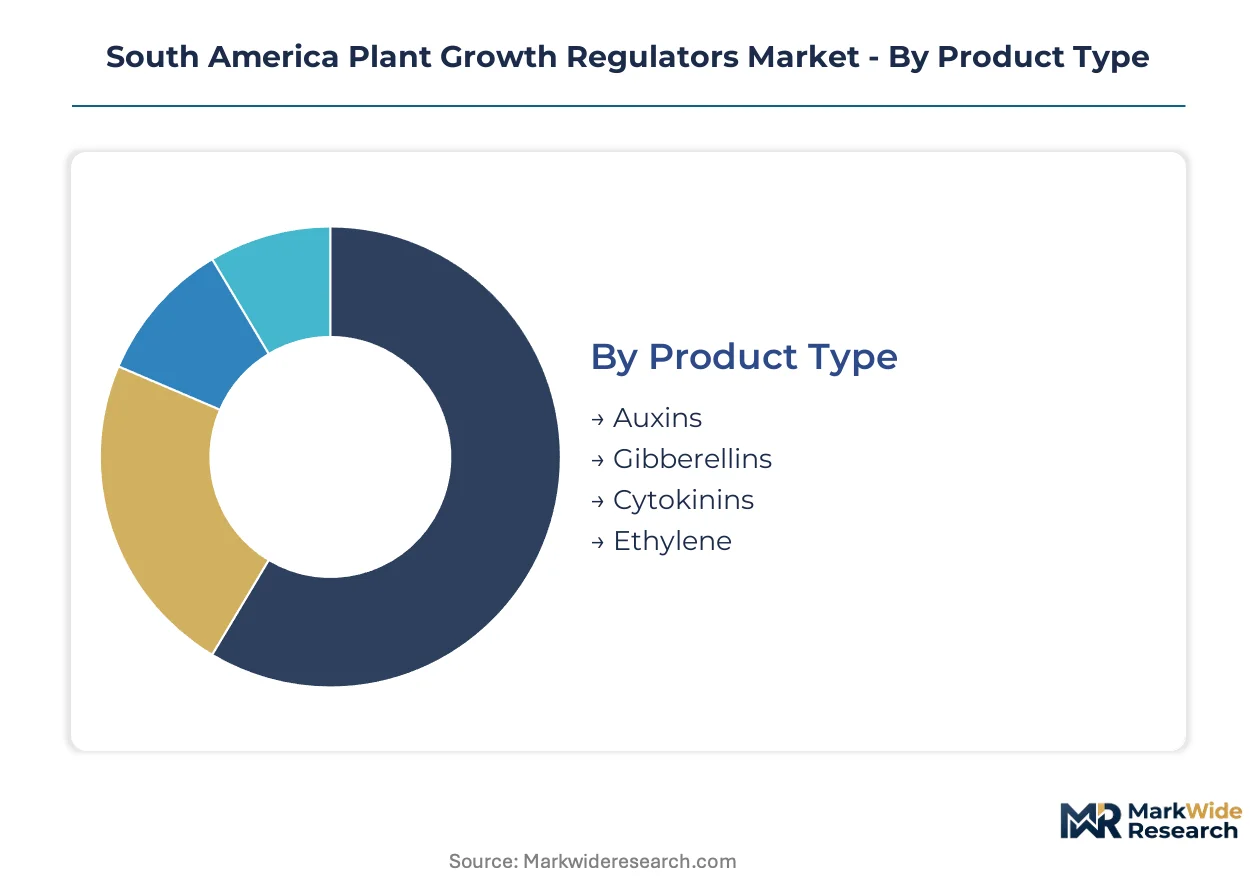
Plant growth regulator demand across South America fragments sharply by crop physiology and distribution logistics. Cycle times for inventory turnover vary from weeks for vegetable cytokinin programs to annual procurement for cereal auxin treatments.
Product Type:
Cytokinin formulations turn over fastest due to narrow application windows in vegetable propagation, while gibberellin acid programs stretch across multi-month pome fruit development cycles.
- Auxins:Synthetic and natural indole compounds regulate cell elongation and root initiation in vascular tissues. Brazilian soybean and maize operations in Mato Grosso and Rio Grande do Sul concentrate demand for pre-planting root stimulation protocols, though narrow phytotoxicity bands constrain farmer self-application.
- Gibberellins:Diterpenoid acids, primarily GA3, trigger stem elongation and seedless fruit development. Argentine apple and pear orchards in Mendoza and Rio Negro provinces drive fermentation-derived sourcing as SENASA tightens residue tolerances on synthetic alternatives.
- Cytokinins:Adenine-derived compounds that promote cell division and delay senescence in coffee cherry and citrus flowering. Colombian specialty growers in Antioquia and Cauca deploy precision protocols for harvest synchronization.
- Ethylene:Gaseous hormone and inhibitor formulations managing climacteric ripening in cold-chain logistics. São Paulo citrus cooperatives mandate ethylene management as export certification condition.
Auxins dominate installed base across South American broadacre cropping. Cytokinins are where expansion concentrates as precision application technology penetrates high-value fruit sectors.
Application:
Margin concentration aligns with perishability risk, where post-harvest loss exposure justifies premium regulator investment.
- Fruits:Climacteric and non-climacteric species require stage-specific hormonal modulation for export quality. Brazilian citrus and Colombian coffee anchor regional demand for ethylene inhibitors and cytokinin synchrony programs.
- Vegetables:Transplant establishment and flowering uniformity drive cytokinin and auxin protocols in protected cultivation. Minas Gerais tomato and pepper seedling producers purchase through integrated advisory platforms.
- Cereals:Lodging prevention and yield stabilization in wheat and rice deploy gibberellin inhibitors and auxin carriers. Uruguay's Treinta y Tres rice belt remains underpenetrated relative to Brazilian and Argentine adoption rates.
- Ornamentals:Floriculture and nursery stock apply growth retardants for compact habit and shelf-life extension. Colombian export rose operations near Bogotá represent concentrated demand for height control chemistry.
Cereals dominate volume throughput across South American procurement channels. Fruits capture margin concentration as cold-chain integration lengthens and quality premiums widen.
Distribution Channel:
Channel selection reflects farm scale and technical advisory requirements, with larger operations bypassing retail intermediaries.
- Distributors:Regional agrochemical wholesalers maintain formulation blending facilities and technical field staff. Brazilian cooperatives in São Paulo state citrus belt rely on distributor-stored ethylene inhibitor inventories for harvest timing flexibility.
- Direct Sales:Manufacturer-to-grower contracts for volume accounts with on-farm storage and precision application equipment. Argentine pome fruit exporters in Mendoza negotiate direct gibberellin supply agreements.
- Retail Stores:Smallholder access points in Paraguay and Bolivia with limited technical support capacity. Tomato phytotoxicity incidents in 2023 trace to unsupervised auxin purchases through this channel.
- Online Retail:Emerging platform procurement for standardized formulations with documented application protocols. Brazilian Mato Grosso soybean operators source drone-compatible cytokinin through digital channels.
Distributors anchor installed base through embedded technical relationships. Direct sales is where expansion concentrates as large-scale specialty operations consolidate procurement authority.
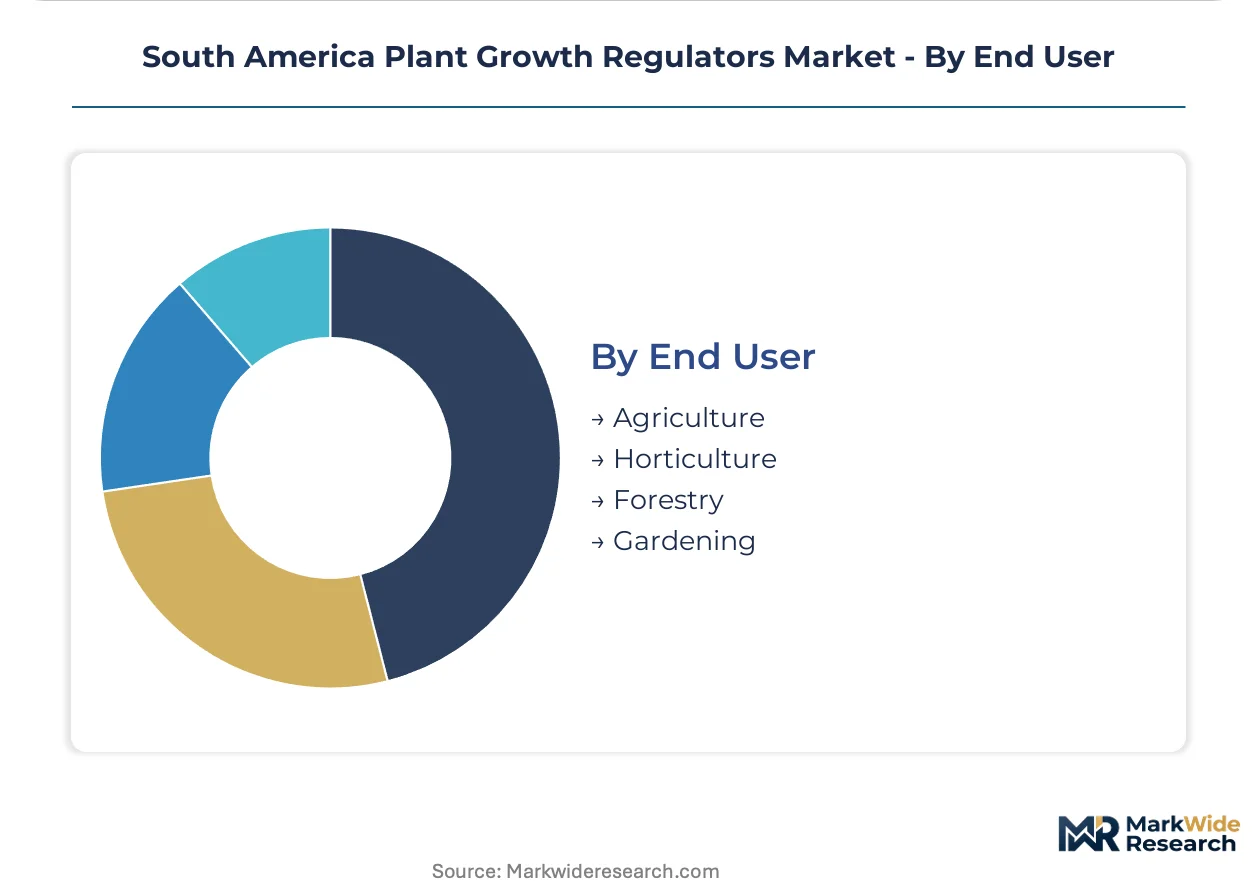
End User:
User category boundaries blur as commercial agriculture integrates horticultural techniques and forestry adopts precision chemical management.
- Agriculture:Broadacre and specialty crop operations generating commodity and export-grade production. Brazilian soybean frontier and Argentine wheat belts represent volume concentration for auxin and gibberellin programs.
- Horticulture:Intensive fruit, vegetable, and ornamental production with quality-sensitive market access requirements. Colombian coffee and Ecuadorian rose exports demand residue-compliant cytokinin and retardant protocols.
- Forestry:Plantation establishment and timber quality management in eucalyptus and pine programs. Southern Brazil and Chilean pulpwood operations deploy auxin rooting hormones for clonal propagation.
- Gardening:Consumer and amenity applications with lower technical sophistication and regulatory exposure. Urban gardening growth in Buenos Aires and São Paulo drives retail-packaged cytokinin demand.
Agriculture dominates installed base through sheer hectare scale. Horticulture is where expansion concentrates as export quality premiums justify precision regulator investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cytokinin formulations command 40% higher unit prices in Colombia's coffee highlands than in Paraguay's smallholder vegetable belts, creating arbitrage opportunities for distributors with cross-border logistics capabilities.
Brazil
São Paulo state's citrus belt concentrates ethylene inhibitor demand for export-grade orange certification. ANVISA's 2024 residue limit alignment with EU Regulation 396/2005 disqualifies legacy organochlorine formulations. Precision application service providers in Mato Grosso's soybean frontier now bundle cytokinin protocols with drone-based variable-rate deployment.
Argentina
Mendoza and Rio Negro provinces drive fermentation-derived gibberellin sourcing as SENASA tightens residue tolerances on synthetic alternatives. The national agrochemical regulator's biocide re-evaluation timeline compresses registration windows for imported formulations. Pome fruit exporters in Mendoza negotiate direct supply agreements bypassing distributor intermediaries.
Colombia
Antioquia and Cauca specialty coffee growers deploy precision cytokinin protocols for harvest synchronization and containerized export. ICA enforcement of maximum residue schedules determines which active ingredients gain commercial registration. Bogotá-area export rose operations represent concentrated demand for height control chemistry in floriculture.
Uruguay
Treinta y Tres and Rocha rice departments currently apply minimal plant growth regulator inputs for lodging resistance. The country's national agricultural regulator maintains import acceptance criteria aligned with MERCOSUR harmonization talks. Seed treatment protocols for paddy cultivation remain technically undeveloped relative to Brazilian and Argentine adoption benchmarks.
Chile
Southern pulpwood operations deploy auxin rooting hormones for clonal eucalyptus and pine propagation. The national agricultural service enforces residue testing backlogs that delay export certification for fruit shippers. Forestry biotechnology clusters near Concepción source fermentation-derived growth regulators for plantation establishment programs.
South America Plant Growth Regulators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation and formulation chemistry. The South American plant growth regulator market structures around three tiers: multinational crop protection platforms with integrated seed-and-chemical portfolios, regional distributors maintaining blending facilities and technical field staff, and local biotech startups specializing in microbial fermentation pathways. Consolidation pressure intensifies as ANVISA and SENASA registration costs favor dossier-sharing partnerships and shared-toxicology-data alliances over standalone filings.
Within the multinational platform tier, Bayer Crop Science AG and Syngenta Group exemplify divergent regional strategies—Bayer anchoring premium cytokinin formulations through seed-and-crop-protection integration, Syngenta competing via localized blending operations with shorter lead times for Brazilian citrus cooperatives. Valent BioSciences occupies a distinct position as a fermentation-derived gibberellin specialist serving Argentine pome fruit production niches.
| Leading Market Players |
|---|
| NuFarm Ltd |
| Microquimica Tradecorp |
| Valent BioSciences |
| Corteva Agriscience |
| Bayer Crop Science AG |
| BASF SE |
| Fine Americas, Inc. |
| FMC Corporation |
| Syngenta Group |
| Others |
Value Network & Pricing Analysis
Mendoza's fermentation-derived gibberellin cluster anchors Argentine supply capacity, concentrating upstream pricing power among biotech startups while compressing margins for distributors dependent on imported synthetic formulations. ANVISA's residue tolerance tightening and SENASA's biocide re-evaluation timeline feed directly into formulation cost structures across the Southern Cone.
Pricing Analysis
Configured-to-order cytokinin protocols for Colombian coffee cherry synchronization command 40% premiums over standard auxin formulations for Brazilian broadacre cereals. Three-tier pricing structure across premium fermentation-derived, standard synthetic, and economy generic tiers reflects certification grade and volume scale differentiation. Pricing pressure stems from ANVISA's accelerated re-registration costs and REACH-aligned toxicology data requirements. Smallholder vegetable cooperatives in Paraguay exhibit highest price sensitivity, while Argentine pome fruit exporters absorb premiums for residue-compliant direct supply agreements.
Supply Chain Analysis
Export-control restrictions on fermentation technology transfer from European biotech licensors limit Argentine domestic capacity expansion for gibberellin GA3 production. Supply concentrates in Brazil's São Paulo formulation blending facilities, Argentine Mendoza biotech fermentation sites, and Colombian Bogotá distribution hubs. Raw material dependencies include corn steep liquor, soybean meal feedstocks, and specialty solvent carriers. Single-source vulnerability runs through Santos port customs clearance for time-sensitive cytokinin propagation cycles. Distribution runs through regional agrochemical wholesalers maintaining technical field staff and harvest-timing inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among four major Brazilian agronomic advisory platforms bundling precision application services, fragmenting standalone chemical procurement and compressing distributor margins across the Southeast region.
For Market Incumbents: Insulate premium positioning by deepening captive supply of fermentation-derived gibberellin through backward integration into Mendoza biotech facilities, and by securing ANVISA registration data-sharing alliances to amortize toxicology dossier costs. Synthetic formulation specialists face substitution risk from microbial-derived alternatives as SENASA tightens residue tolerances.
For New Entrants and Emerging Players: Build out drone-based variable-rate cytokinin deployment capabilities in Brazil's Mato Grosso soybean frontier, where equipment-as-service models reduce farmer capital barriers. Uruguay's Treinta y Tres rice belt offers the most penetrable white space for lodging-resistant seed treatment protocols. Target direct sales relationships with large-scale specialty exporters bypassing distributor intermediaries.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision application service providers bundling regulator prescriptions with sensor data subscriptions. Long-term viability across the analysis window favors fermentation technology platforms with SENASA-compliant residue profiles over legacy synthetic chemistry. Acquisition targets should demonstrate established ICA or ANVISA registration pathways and embedded technical advisory relationships. The signal to watch is MERCOSUR biocide harmonization progress as an inflection indicator for single-registration product scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive GA3 production in Mendoza insulates Argentine formulators from synthetic import restrictions. |
| Precision Application Platform Integration | Drone-based cytokinin deployment in Mato Grosso reduces farmer capital requirements and locks in recurring service revenue. |
| Regulatory Data-Sharing Alliance | Joint ANVISA registration dossiers amortize toxicology costs for mid-tier distributors facing consolidation pressure. |
| Direct Supply Agreement Structuring | Bypassing distributor intermediaries for Colombian coffee exporters captures margin concentration in quality-sensitive segments. |
| Underpenetrated Geography Development | Uruguay rice sector seed treatment protocols remain technically undeveloped relative to regional benchmarks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Brazilian citrus cooperative technical managers, Argentine pome fruit export procurement leads, Colombian coffee agronomists, formulation chemists at regional blending facilities, and ANVISA regulatory affairs specialists. Secondary validation drew from ANVISA residue limit schedules, SENASA biocide re-evaluation timelines, ICA registration databases, MERCOSUR harmonization protocols, and customs trade flow records. Bottom-up crop-acreage application rates and top-down manufacturer shipment volumes were triangulated to calibrate market sizing.
Calibration against historical registration approval timelines and cold-chain logistics expansion patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, crop application, distribution channel, and end-user category, with regulatory jurisdiction clusters treated as a cross-cutting variable. CAGRs were derived from weighted scenario analysis incorporating precision technology penetration curves and biocide harmonization probability assessments. Forecast inputs included ANVISA-EU regulatory alignment implementation pace and drone service provider network density trajectories.
Stress conditions across commodity feedstock price volatility, customs clearance delay distributions, and regulatory re-evaluation acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding MERCOSUR harmonization progress and cold-chain infrastructure investment continuity. Material shifts in ANVISA residue tolerance schedules or SENASA import acceptance criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
Agricultural Antibacterials Market