
 Global Agricultural Fumigants Market | 2026-2036
Global Agricultural Fumigants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Fumigants Market Intelligence
The EU F-Gas Regulation is broadening the addressable market for non-ozone-depleting fumigant chemistries across European grain handling and storage networks. BASF SE sustains technology leadership through its phosphine stabilization platforms, while Syngenta Group leverages integrated seed treatment-to-fumigation portfolios across Latin American soybean corridors. Nufarm Limited anchors southern hemisphere supply through regional manufacturing and distribution scale in Australia and Brazil.
Agricultural fumigants are volatile or gaseous biocidal compounds, typically deployed at concentrations between 50 and 2000 ppm depending on pest species and enclosure integrity, that penetrate commodity bulk or soil matrices to eliminate nematodes, insects, and fungal pathogens. Their primary commercial purpose is to secure yield recovery and phytosanitary compliance in export-oriented supply chains. Phosphine formulations dominate stored grain applications due to residue tolerance and handler safety profiles, while sulfuryl fluoride occupies structural and post-harvest niches where mammalian toxicity thresholds permit operational use. Soil treatment remains the most mature application segment, though greenhouse fumigation exhibits faster growth as controlled-environment agriculture expands.
The EPA regulates fumigant registration and buffer zone requirements under FIFRA in the United States, while REACH governs active substance authorization and worker exposure limits across EU member states. Brazil's ANVISA and the national environmental agency jointly oversee import tolerances and application protocols that determine market access for phosphine and chloropicrin products. Stakeholders must monitor evolving residue maximum limits in destination markets and pre-position alternative chemistries before existing registrations face non-renewal pressures.
Market Dynamics
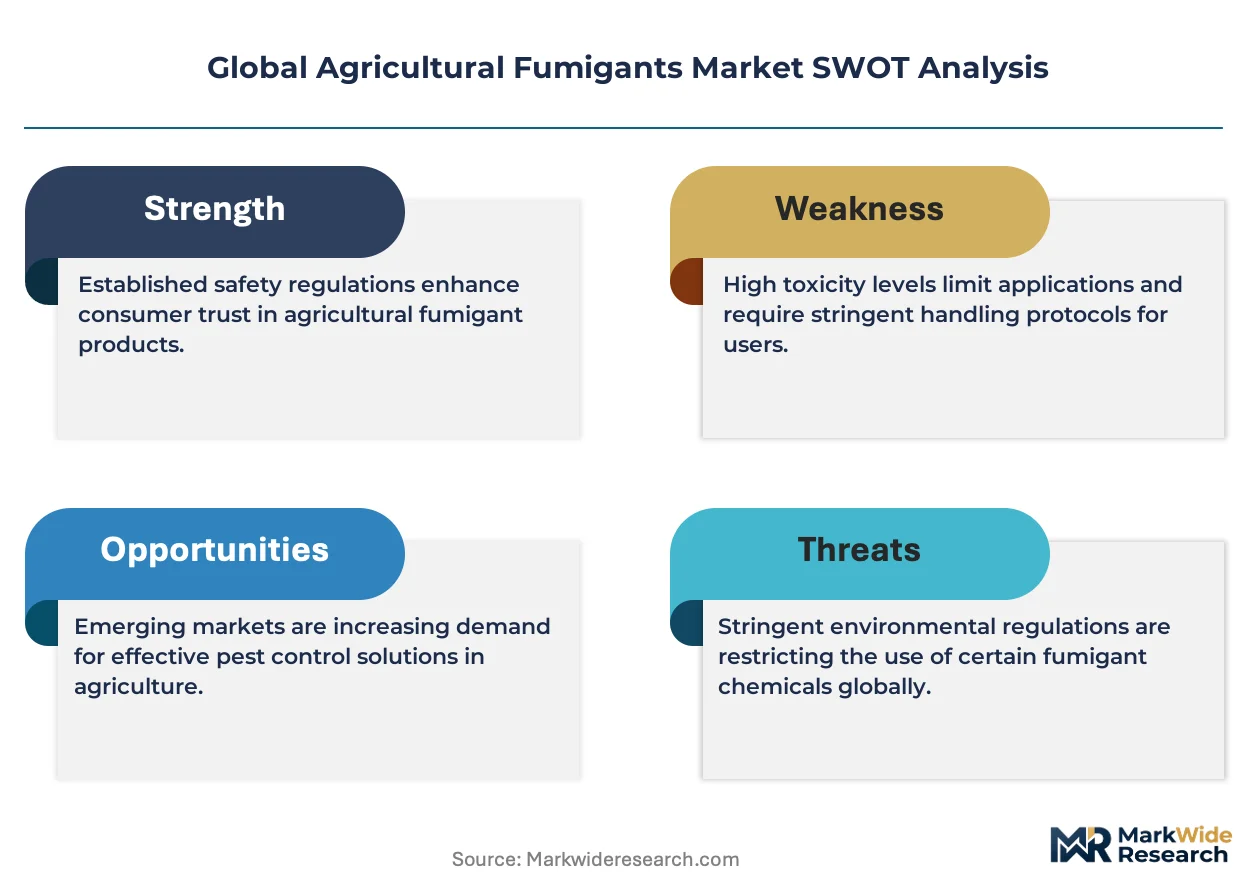
The EU F-Gas Regulation phase-down of methyl bromide alternatives is redirecting R&D investment toward phosphine-based and sulfuryl fluoride formulations, compressing legacy chemistry margins while opening formulation white space for compliant alternatives.
Growth Catalysts
- Integrated Pest Management Mandates:Specialty crop growers in California and Spain face tightening residue protocols that favor precision fumigation over broad-spectrum pesticide applications.
- REACH Authorization Pathways:The EU's streamlined active substance renewal process is accelerating market access for novel soil fumigant candidates with favorable toxicological profiles.
- Brazilian Post-Harvest Infrastructure:Soybean and corn storage expansion across Mato Grosso and Paraná is driving phosphine tablet adoption for commodity protection.
Market Restraints
- Aluminum Phosphide Supply Concentration:Three Chinese manufacturers control 70% of global technical-grade phosphine precursor output, exposing formulators to input volatility.
- Buffer Zone Expansion Requirements:EPA FIFRA amendments have extended setback distances for chloropicrin applications in California's Central Valley, constraining treated acreage per permit.
- Biological Nematicide Substitution:Pasteuria penetrans and Purpureocillium lilacinum soil treatments are capturing strawberry and tomato grower budgets in Florida and Mexico.
Strategic Opportunities
- Controlled-Environment Agriculture:Greenhouse fumigation protocols in the Netherlands and Canada lack standardized application equipment, creating first-mover equipment rental potential.
- India Cold Chain Modernization:The country's PLI scheme for food processing infrastructure is funding phosphine generator installations in Punjab and Haryana grain aggregation centers.
- Digital Fumigation Monitoring:Integration of wireless gas sensors with automated ventilation systems enables remote concentration management in Australian bulk terminals.
Industry Challenges
- Fumigant Handler Certification Bottlenecks:EPA-approved training providers in the US cannot scale instructor capacity to match applicator demand ahead of methyl bromide phase-out deadlines.
- Cross-Border Residue Harmonization:Brazil's ANVISA and Australia's TGA maintain divergent maximum residue limits for sulfuryl fluoride on almonds, complicating export logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Fumigants Market |
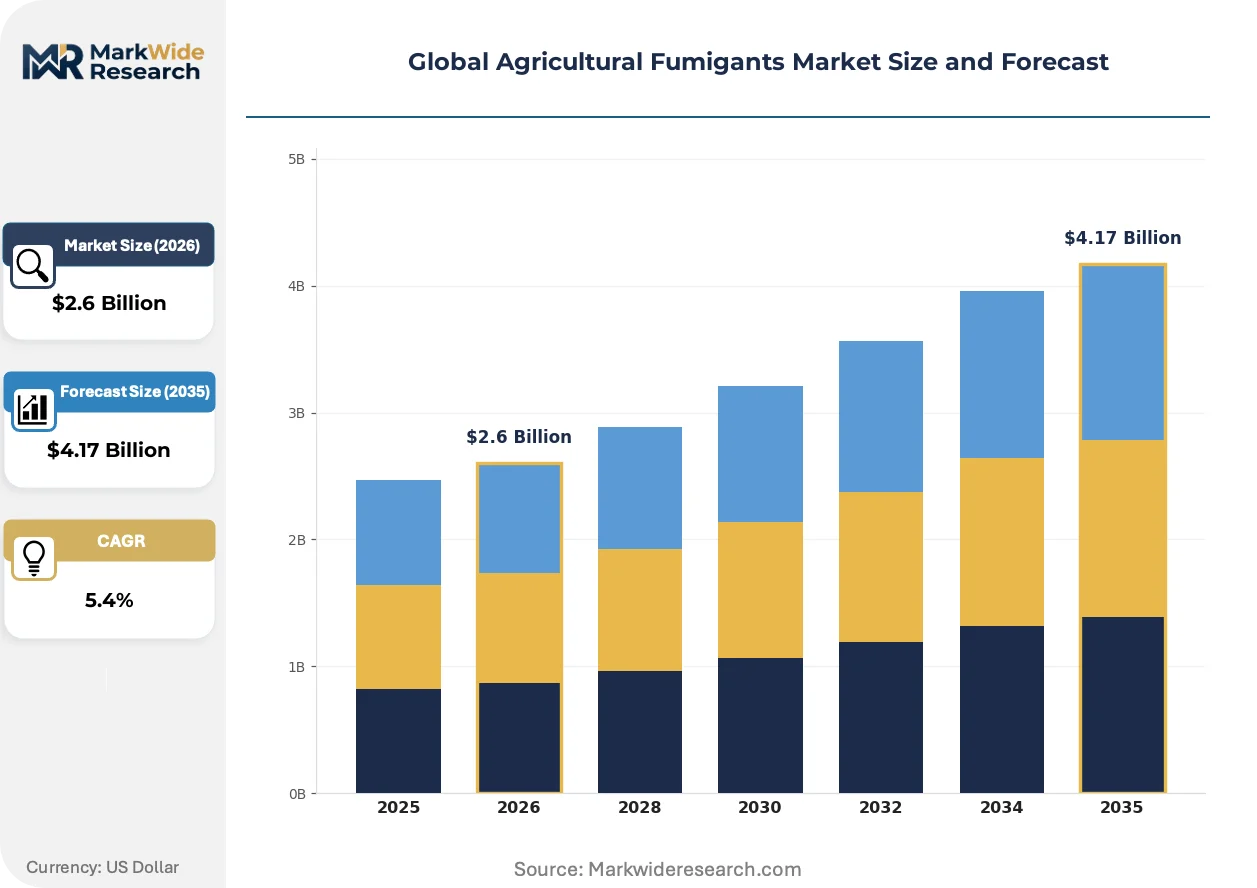
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.17 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chloropicrin, Methyl Bromide, Sulfuryl Fluoride, Phosphine, Carbon Disulfide Formulation: Liquid, Gas, Solid, Vapor, Fog Application Type: Soil Treatment, Post-Harvest Treatment, Seed Treatment, Greenhouse Fumigation, Storage Protection End User: Seed Producers, Crop Growers, Storage Facilities, Agricultural Consultants |
| Companies Covered | Syngenta Group, BASF SE, Corteva Agriscience, Bayer AG, UPL Limited, FMC Corporation, Nufarm Limited, AMVAC Chemical Corporation, Detia Degesch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Fumigants Market Strategic Shifts & Innovations
Phosphine stabilization chemistry and precision application hardware are converging to reduce commodity losses while tightening environmental containment standards across grain handling networks.
Recirculation-based phosphine generation is overtaking traditional aluminum phosphide tablet methods in large-scale grain terminals. Cargill and Bunge facilities in Louisiana and Washington State have retrofitted 500,000-tonne capacity silos with closed-loop systems. The technology is compressing fumigation cycle times from 14 days to 7 days while eliminating handler exposure during application.
The EU F-Gas Regulation ban on hydrofluorocarbon propellants is forcing reformulation of sulfuryl fluoride packaged goods. Fumigation service providers in Germany and France face equipment retrofit costs for compliant pressure vessels. The structural fumigation segment is responding with membrane-based containment systems that reduce total active ingredient requirements per treatment.
Grain elevator procurement teams are consolidating supplier relationships from multi-chemical portfolios to single-source phosphine service contracts. The shift displaces independent fumigant distributors in the US Corn Belt and Argentine Pampas. Cooperative buying arrangements through regional grain handler associations are most visible in Iowa, Illinois, and Buenos Aires province.
Global Agricultural Fumigants Market Segmentation
Product chemistry, physical state, and application setting determine fumigant selection protocols across agricultural supply chains. Segmentation reveals where formulation innovation concentrates versus where commodity purchasing dominates procurement patterns.
Product Type:
Standalone fumigants operate without carrier systems in soil and storage matrices, while embedded chemistries require propellant or stabilizer integration for controlled release.
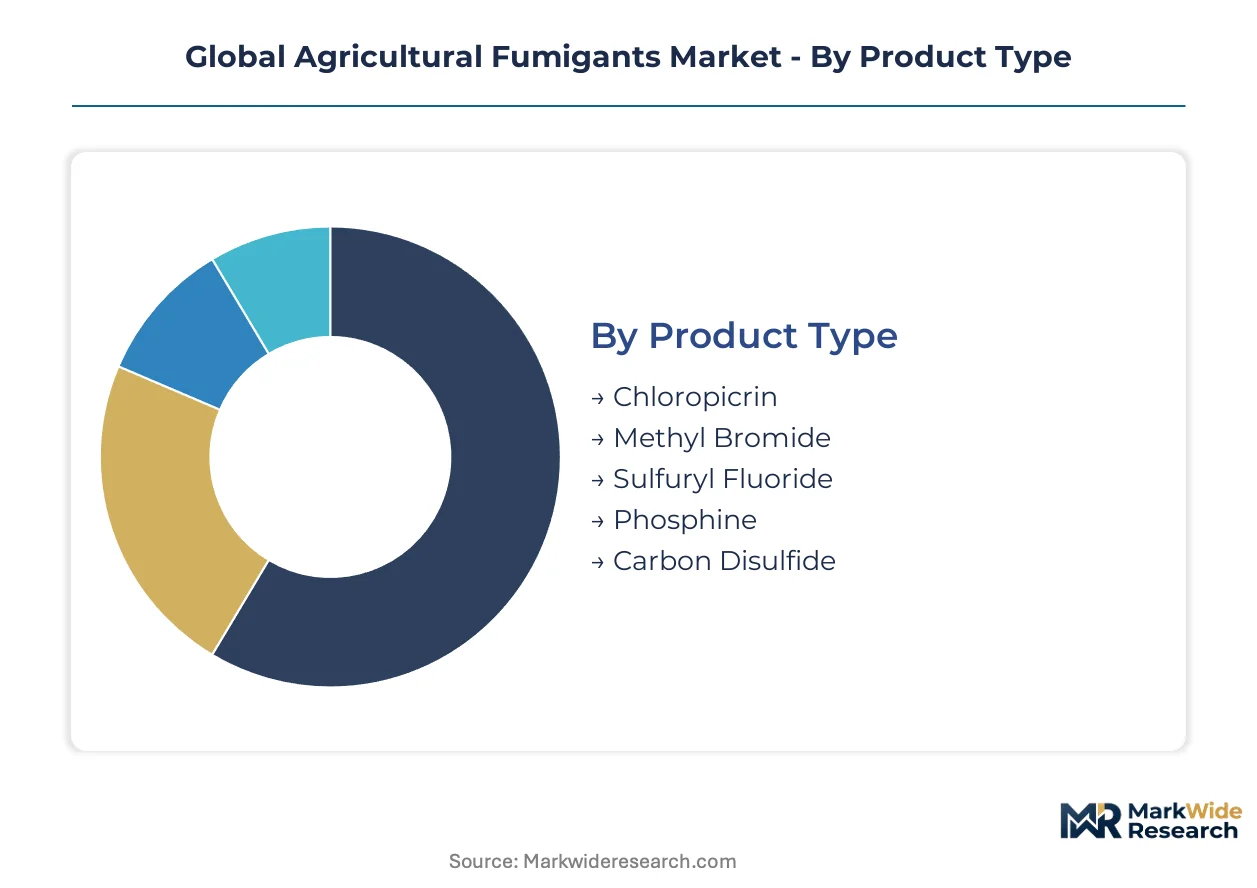
- Phosphine:Aluminum and magnesium phosphide formulations generate toxic gas through moisture-activated hydrolysis, achieving 200-2000 ppm concentrations in sealed grain silos. Brazilian soybean elevators in Mato Grosso and Paraná drive tablet and pellet consumption for post-harvest loss prevention.
- Sulfuryl Fluoride:This halogenated sulfuryl compound penetrates wood and commodity bulk with lower residue persistence than methyl bromide. Structural fumigation of almond processing facilities in California's Central Valley and wine storage vaults in France's Bordeaux region sustains demand amid EU F-Gas Regulation compliance deadlines.
- Chloropicrin:Nitrochloroform compound deployed primarily as a soil pre-plant treatment against nematodes and fungal pathogens in strawberry and vegetable production systems.
- Methyl Bromide:Ozone-depleting bromomethane facing phased elimination under Montreal Protocol schedules; residual use confined to critical use exemptions in quarantine and pre-shipment applications.
- Carbon Disulfide:Historical grain fumigant with declining commercial relevance due to flammability hazards and handler exposure concerns; limited specialty applications in Southeast Asian rice storage networks.
Phosphine leads volumes today; sulfuryl fluoride is gaining share fastest.
Formulation:
Physical state dictates equipment requirements, handler certification tiers, and enclosure integrity specifications across treatment settings.
- Solid:Compressed tablets and pellets of aluminum phosphide enable controlled moisture-activated gas release in grain storage. Australian bulk terminal operators favor solid formulations for remote site logistics and extended shelf stability.
- Gas:Direct cylinder delivery of phosphine or sulfuryl fluoride eliminates residue handling and accelerates fumigation cycle times. Large-scale grain handlers in Louisiana and Washington State deploy gas systems for 500,000-tonne capacity silo complexes.
- Liquid:Chloropicrin and metam sodium solutions require injection equipment for soil matrix penetration; California's Central Valley specialty crop sector maintains substantial liquid formulation demand.
- Vapor:Heat-activated or pressure-dispersed formulations suit greenhouse and controlled-environment agriculture applications in the Netherlands and Canada.
- Fog:Ultra-low volume aerosol systems for space treatment in empty storage structures and transport containers; limited adoption due to penetration depth constraints.
Solid formulations dominate procurement tonnage; gas systems are expanding most quickly in automated terminal infrastructure.
Application Type:
Pre-harvest soil interventions operate on seasonal cycles with permit-dependent buffer zones, while post-harvest treatments run continuously through storage and logistics networks.
- Soil Treatment:Pre-plant fumigation of nematode-infested fields in Florida strawberry production and Mexico's Sinaloa tomato corridors. EPA FIFRA buffer zone expansions in California constrain treated acreage per permit issuance.
- Storage Protection:Post-harvest phosphine application in grain elevators, silos, and warehouse structures across Iowa, Illinois, and Buenos Aires province cooperative networks. Cargill and Bunge facilities have retrofitted closed-loop recirculation systems.
- Post-Harvest Treatment:Commodity-specific fumigation of packaged nuts, dried fruits, and spices for export phytosanitary compliance; almond and pistachio processors in California's San Joaquin Valley represent concentrated demand.
- Greenhouse Fumigation:Controlled-environment agriculture protocols for soil and substrate sterilization in the Netherlands and Canadian protected cultivation sectors; equipment standardization gaps create first-mover opportunities.
- Seed Treatment:Integrated fumigation within seed processing and conditioning flows; Syngenta Group leverages seed-to-fumigation portfolio coordination across Latin American soybean corridors.
Soil treatment commands the largest revenue base; greenhouse fumigation is climbing the fastest as controlled-environment agriculture expands.
End User:
Volume procurement concentrates in integrated storage and trading operations, while specialized advisory services mediate regulatory compliance for fragmented grower bases.
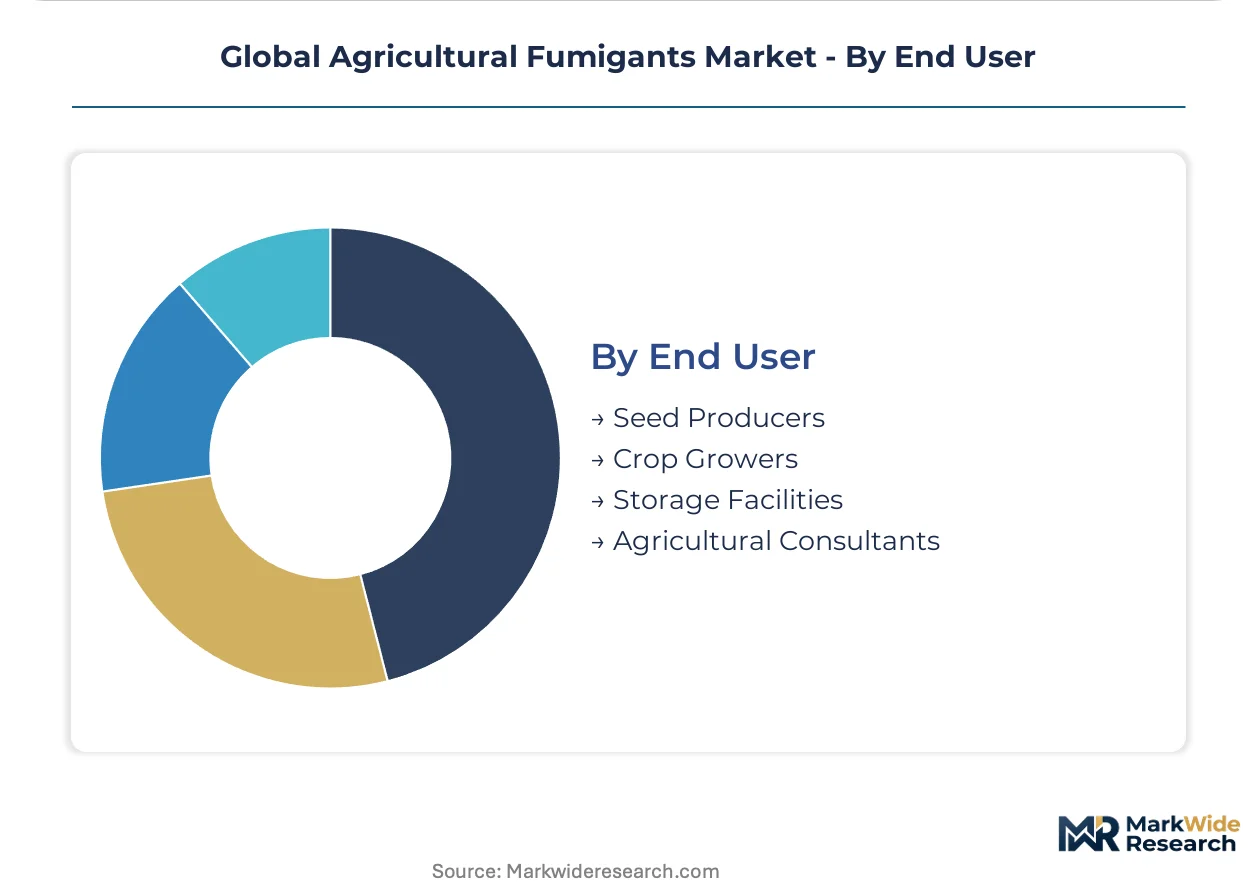
- Storage Facilities:Grain elevator operators and bulk terminal managers purchase phosphine through cooperative buying arrangements. Regional grain handler associations in the US Corn Belt and Argentine Pampas consolidate supplier relationships toward single-source service contracts.
- Crop Growers:Specialty crop producers in California and Spain face tightening integrated pest management mandates that favor precision fumigation protocols over broad-spectrum pesticide applications.
- Seed Producers:Conditioning and treatment operations requiring phytosanitary certification for export markets; quality assurance protocols drive consistent fumigant consumption.
- Agricultural Consultants:Advisory services facilitating permit acquisition, handler certification, and application timing optimization for independent growers navigating EPA and REACH compliance requirements.
Storage facilities lead absolute consumption; agricultural consultants are expanding fastest as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The agricultural fumigants industry traces its commercial origins to post-war grain storage networks in the United States and Germany, where phosphine and methyl bromide first displaced mechanical pest control methods at scale.
United States
EPA FIFRA buffer zone expansions for chloropicrin applications constrain treated acreage per permit in California's Central Valley, where strawberry and vegetable growers face tightening residue protocols. The San Joaquin Valley almond processing corridor sustains sulfuryl fluoride demand for structural fumigation of export-oriented nut facilities.
Brazil
Soybean and corn storage expansion across Mato Grosso and Paraná drives phosphine tablet adoption for post-harvest loss prevention. ANVISA and IBAMA jointly oversee import tolerances and application protocols that determine market access for phosphine and chloropicrin products. Cooperative buying arrangements through regional grain handler associations concentrate procurement in Paraná's elevator networks.
Germany
Detia Degesch GmbH anchors European phosphine formulation supply from its Ludwigshafen manufacturing base. The EU F-Gas Regulation ban on hydrofluorocarbon propellants forces sulfuryl fluoride reformulation and equipment retrofit costs for fumigation service providers. The Rhine-Ruhr industrial corridor hosts membrane-based containment system development for reduced active ingredient requirements.
Australia
Bulk terminal operators favor solid aluminum phosphide formulations for remote site logistics and extended shelf stability across Western Australia's grain belt. TGA maintains divergent maximum residue limits for sulfuryl fluoride on almonds compared to destination markets, complicating export logistics. Queensland's phosphine generator installations benefit from cold chain modernization funding.
India
The PLI scheme for food processing infrastructure funds phosphine generator installations in Punjab and Haryana grain aggregation centers. FSSAI and the Central Insecticides Board jointly regulate active substance authorization and worker exposure limits across state-level agricultural networks. Maharashtra's seed processing corridors drive integrated fumigation demand within conditioning and treatment flows.
Global Agricultural Fumigants Market Key Industry Players
Capital-heavy integrated agrochemical producers compete with asset-light formulation specialists across the agricultural fumigants value chain. The market structure concentrates around multinational conglomerates with captive active ingredient supply and regional distributors dependent on toll manufacturing arrangements. Three strategic archetypes dominate: integrated seed-to-fumigation portfolio operators, phosphine stabilization technology specialists, and regional manufacturing-scale anchors. Competitive dynamics center on backward integration into aluminum phosphide precursor supply and geographic expansion through cooperative service contracts with grain handler associations.
Among European-integrated conglomerates, BASF SE and Bayer AG exemplify the capital-intensive archetype with phosphine stabilization platforms and broad agrochemical portfolios. Nufarm Limited occupies a position as the southern hemisphere manufacturing anchor through regional production and distribution scale in Australia and Brazil. These three entities represent the tiered structure where technology leadership, geographic anchoring, and portfolio breadth define competitive positioning.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Corteva Agriscience |
| Bayer AG |
| UPL Limited |
| FMC Corporation |
| Nufarm Limited |
| AMVAC Chemical Corporation |
| Detia Degesch GmbH |
| Others |
Cost & Logistics Intelligence
Captive backward integration into aluminum phosphide precursor production anchors both supply security and pricing power for integrated formulators serving Brazilian soybean elevators and Australian bulk terminals. This upstream control insulates BASF and Nufarm from Chinese manufacturer volatility while compressing margins for toll-dependent regional distributors in the US Corn Belt.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between grain handler cooperatives and phosphine service providers, with pricing stratifying across premium certified-handler tiers, standard cooperative membership rates, and economy spot-market purchases. Price differentiation hinges on EPA certification grade and bundled advisory services. Cost compression in economy tiers is intensifying because biological nematicide substitutes capture strawberry grower budgets. Storage facility cooperatives exhibit highest price sensitivity; seed producers with export compliance mandates show lowest.
Supply Chain Analysis
Empty aluminum phosphide tablet packaging and spent generator units flow through licensed hazardous waste channels back to Detia Degesch's Ludwigshafen reclamation facility. Active ingredient supply concentrates in China, Germany, and Australia. Technical-grade phosphine precursor production draws from yellow phosphorus and aluminum powder feedstocks. Single-source vulnerability pervades the three-Chinese-manufacturer concentration for aluminum phosphide. Distribution runs through regional grain handler associations consolidating toward single-source phosphine service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural fumigants market functions as a regulatory compounder where EU F-Gas Regulation methyl bromide phase-down deadlines redirect R&D investment and consolidate compliant formulation demand.
For Market Incumbents: Hedge aluminum phosphide supply exposure by securing toll manufacturing agreements with Indian or Australian precursor producers before Chinese export license volatility materializes. Deepen phosphine stabilization R&D to defend margin position against sulfuryl fluoride substitution in structural fumigation segments. Channel control through cooperative service contracts with Iowa and Illinois grain handler associations remains the priority defensive lever. For New Entrants and Emerging Players: Begin with equipment rental services for greenhouse fumigation protocols in the Netherlands and Canada, where application standardization gaps create first-mover potential without active substance registration burdens. Target digital fumigation monitoring integration as the most penetrable white space, pairing wireless gas sensor hardware with automated ventilation system software. A joint venture with Australian bulk terminal operators offers the clearest go-to-market path. For Investors and Strategic Acquirers: Roll-up economics work for regional phosphine formulation specialists because handler certification bottlenecks and EPA permit complexity prevent rapid new entrant scaling. The five-to-ten year viability window favors acquiring asset-light distributors with captive relationships to Brazilian or Australian grain handler cooperatives. Monitor EU F-Gas Regulation enforcement acceleration as the inflection signal for sulfuryl fluoride reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive aluminum phosphide production insulates BASF and Nufarm from Chinese manufacturer concentration risk. |
| Phosphine Stabilization Platform Investment | Extended-release formulations command premium pricing in Brazilian soybean elevator service contracts. |
| Digital Fumigation Monitoring Partnership | Wireless sensor integration with Cargill and Bunge terminal automation reduces handler exposure liability. |
| Greenhouse Fumigation Equipment Standardization | First-mover protocol development in Netherlands protected cultivation captures controlled-environment agriculture expansion. |
| Cooperative Service Contract Consolidation | Single-source phosphine agreements with Iowa and Illinois grain handler associations displace independent distributors. |
Research Approach
Direct dialogue with phosphine formulation plant managers, grain elevator procurement leads at cooperative networks, fumigation service technical directors, and EPA certification training providers grounded qualitative findings in operational reality. Secondary validation drew from customs trade data, EPA FIFRA registration filings, ANVISA tolerance determinations, and EU ECHA authorization decisions. Bottom-up volume estimates from individual facility consumption patterns triangulated against top-down national grain storage capacity assessments.
Segment-level value outputs across the projection horizon reflect modeled interactions between product chemistry, physical formulation state, and application setting dimensions. CAGRs derived from regression analysis against historical grain production, storage infrastructure investment, and regulatory phase-down schedules. Industry-specific forecast inputs included Brazilian soybean post-harvest loss rates and EU F-Gas Regulation compliance cost trajectories for sulfuryl fluoride reformulation.
Several conditions sit outside the modeled scope, including potential biological nematicide efficacy breakthroughs in Florida strawberry production and unscheduled Montreal Protocol critical use exemption extensions for methyl bromide quarantine applications. Forecasts reflect documented assumptions about aluminum phosphide Chinese export license stability and REACH authorization pathway timelines. Practitioners should monitor EPA buffer zone expansion rulings and ANVISA residue limit harmonization negotiations with Australia's TGA for early demand shift signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Feed Antioxidants Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
Global Feed Palatability Enhancers Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
South America Feed Enzymes Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
Agricultural Surfactants Market