
 Feed Acid Market | 2026-2036
Feed Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Acid Market Analysis
FAMI-QS certification is collapsing the supplier base for compound feed acidifiers across Europe, forcing non-certified blenders out of the value chain. BASF SE leverages its backward integration into propionic acid to sustain cost leadership in preservation-grade formulations. Yara International ASA anchors its position through ammonia-based acid salt technology that dominates Nordic ruminant applications. Kemin Industries Inc. differentiates via encapsulated acid delivery systems that compete on gut-targeted release performance.
Feed acids comprise organic acids and their salts added to animal diets to inhibit pathogenic bacteria, reduce gastric pH, and improve nutrient digestibility, with formic acid and propionic acid representing the most widely specified active ingredients due to their broad antimicrobial spectra. The primary commercial purpose centers on replacing antibiotic growth promoters in poultry and swine rations while extending feed shelf life through mold inhibition. Formic acid formulations lead the product type landscape on unit volume, yet lactic acid blends command premium positioning in aquaculture acidification where pH buffering demands precision. The poultry end-user segment generates the deepest margin pools as integrators consolidate procurement around acidified pre-starter feeds, while powdered and granular forms are displacing liquid alternatives in automated dosing systems across Brazilian and Indonesian feed mills.
The European Food Safety Authority evaluates all new feed acid submissions under the reformed EU 1831/2003 additive framework, while the FDA's GRAS self-affirmation pathway shapes U.S. market entry timelines for novel acid blends. China's Ministry of Agriculture and Rural Affairs maintains a positive-list approach that restricts which organic acids may appear in compound feeds, directly constraining formulation flexibility for exporters. Stakeholders must monitor evolving residue-testing protocols and decide whether to pursue multi-jurisdictional additive registrations or specialize in single-market compliance.
Market Dynamics
Antibiotic growth promoter bans across major protein-producing regions are forcing rapid acidifier adoption, while FAMI-QS certification requirements in Europe collapse the supplier base and concentrate procurement power among integrated poultry operators.
Growth Catalysts
- EU 1831/2003 Additive Framework:The reformed regulation accelerates novel organic acid approvals for swine and poultry rations, creating compliant pathways for formic acid derivatives.
- Southeast Asia Poultry Integration:Vietnam's large-scale farms are standardizing acidification protocols in pre-starter feeds, pulling demand for preservation-grade formulations.
- Encapsulation Technology:Gut-targeted release systems improve antimicrobial efficacy in ruminant applications, expanding addressable species beyond monogastrics.
Market Restraints
- Propionic Acid Supply Concentration:Backward-integrated chemical majors control feed-grade propionic acid supply, limiting price negotiation leverage for independent blenders.
- China Positive-List Constraints:The Ministry of Agriculture and Rural Affairs restricts which organic acids appear in compound feeds, constraining formulation flexibility for exporters.
- Residue-Testing Protocol Fragmentation:Divergent analytical methods across importing jurisdictions raise compliance costs for multi-market suppliers.
Strategic Opportunities
- Indonesian Feed Mill Automation:Powdered and granular acid forms are capturing share in automated dosing systems as Brazilian and Indonesian facilities upgrade.
- Aquaculture pH Precision:Lactic acid blends command premium positioning in shrimp and finfish operations where buffering demands exceed poultry tolerance ranges.
- Nordic Ruminant Salt Technology:Ammonia-based acid salts dominate dairy applications, with technology transfer potential to Baltic and Polish herds.
Industry Challenges
- FAMI-QS Certification Timelines:Non-certified European blenders face forced exit from compound feed acidifier supply chains, compressing qualification windows.
- Multi-Jurisdictional Registration Burden:Stakeholders must choose between pursuing parallel FDA GRAS self-affirmation and EFSA evaluations or specializing in single-market compliance.
- Legacy Liquid System Retrofit Costs:Feed mills transitioning to automated powder handling incur capital expenditure for conveying and dosing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Acid Market |
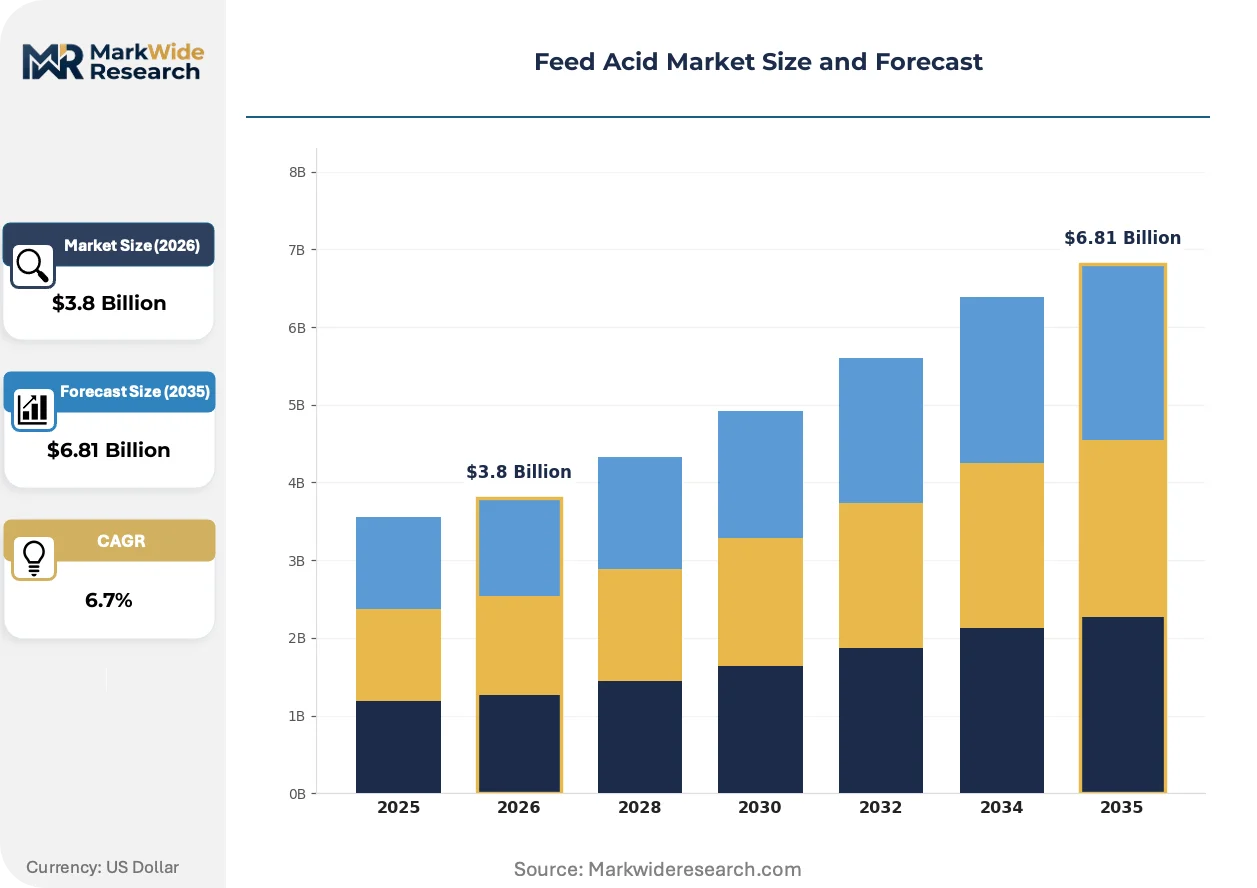
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Acid, Citric Acid, Lactic Acid, Formic Acid End User: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powdered, Granular, Solid Application: Feed Preservation, Nutritional Additive, Acidification, pH Regulation |
| Companies Covered | BASF SE, Yara International ASA, Cargill Incorporated, Archer Daniels Midland Company, Kemin Industries Inc., Eastman Chemical Company, DSM, Perstorp Holding AB, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Acid Market Emerging Trajectories
Formulation science is pivoting toward species-specific delivery mechanisms, while regulatory convergence around residue testing and certification standards reshapes competitive entry barriers across protein-producing regions.
Encapsulated acid delivery systems are displacing conventional unprotected acids in premium poultry rations. Integrators in Vietnam and Thailand specify microencapsulated formic acid for pre-starter feeds to achieve targeted gastric release. The technology is displacing commodity acid purchases in margin-sensitive procurement contracts.
EFSA's reformed EU 1831/2003 additive framework tightens safety and efficacy documentation requirements for new feed acid submissions. The regulation forces reformulation of legacy blends to meet updated purity thresholds. Poultry acidifiers face the steepest compliance costs due to higher residue sensitivity in broiler carcass testing protocols.
Integrated poultry operators are consolidating acidifier procurement around acidified pre-starter feed specifications. Large-scale Vietnamese farms now mandate standardized acidification protocols from contract hatcheries, compressing supplier diversity. The behavior is most visible in Southeast Asia where integrators capture margin pools through centralized additive specification.
Feed Acid Market Segmentation
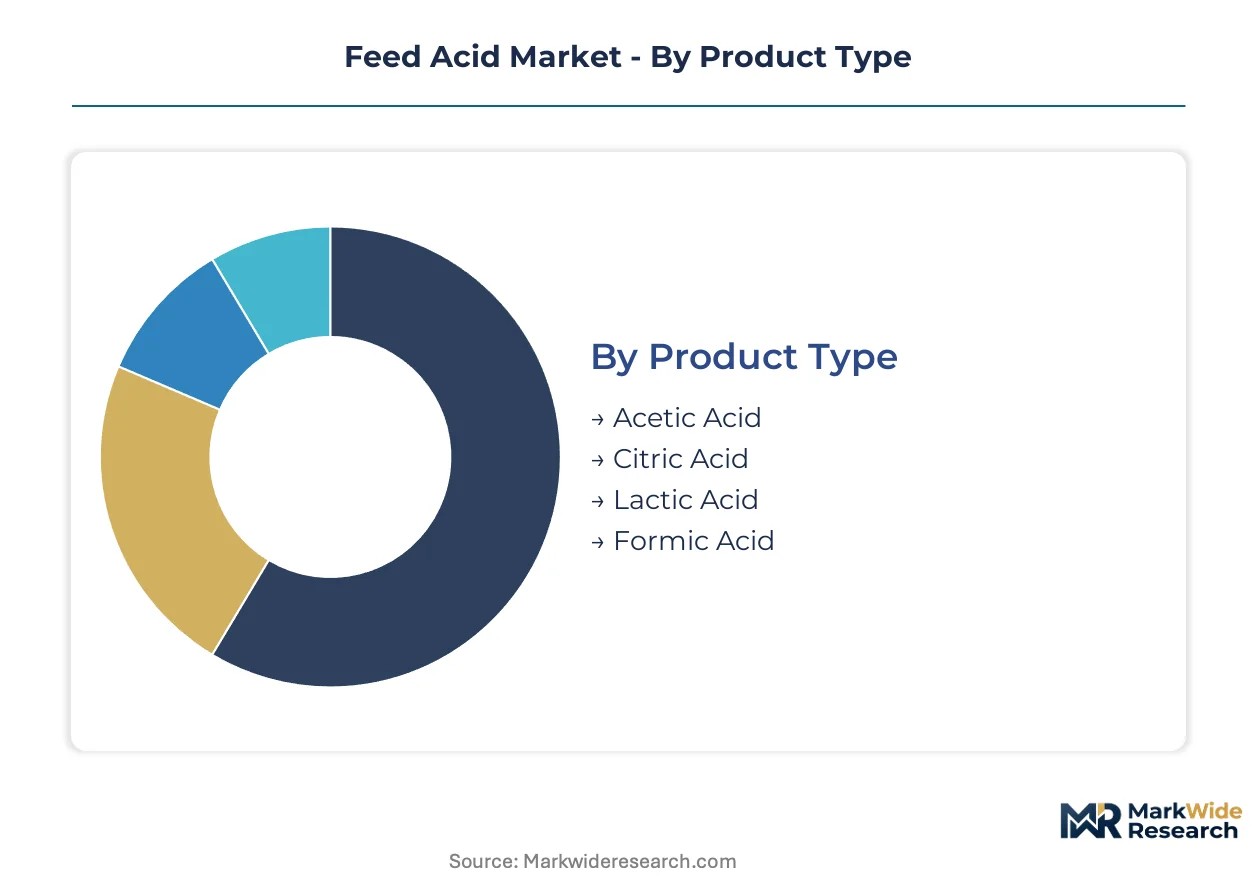
Feed acid segmentation reveals how formulation chemistry, delivery mechanics, and species-specific efficacy requirements create distinct competitive arenas. Procurement patterns diverge sharply between preservation-focused commodity acids and precision-targeted nutritional additives.
Product Type:
Domestic consumption dominates acetic and citric acid categories, while formic and lactic acid segments operate on export-led demand structures tied to integrated protein operations.
- Formic Acid:The most widely specified active ingredient in poultry and swine rations due to broad antimicrobial spectra against Salmonella and E. coli. Vietnamese integrators and Thai contract farms are standardizing formic-based pre-starter specifications, pulling volume through centralized procurement contracts.
- Lactic Acid:Precision-buffering characteristics command premium positioning in aquaculture acidification where shrimp and finfish operations require tighter pH control than monogastric tolerance ranges. Baltic and Nordic producers specify lactic blends for species-specific delivery systems.
- Acetic Acid:Lower-cost preservation alternative with established feed-grade supply chains in domestic compound feed operations.
- Citric Acid:Flavor-masking and mineral chelation properties find use in starter feed palatability enhancement.
Formic acid commands the established base. The steepest expansion runs through lactic acid precision applications.
End User:
Cost tier stratification separates species segments, with poultry and aquaculture commanding formulation premiums against ruminant commodity positioning.
- Poultry:The deepest margin pool generator as integrators consolidate procurement around acidified pre-starter feeds. Southeast Asian large-scale farms mandate standardized acidification protocols from contract hatcheries, compressing supplier diversity and favoring certified blenders.
- Aquaculture:Premium pricing environment driven by pH buffering precision demands in shrimp and finfish operations. Indonesian and Vietnamese marine farms specify acid blends exceeding poultry tolerance ranges for water quality management.
- Swine:Post-weaning diarrhea prevention drives acidifier inclusion in nursery diets across European and Asian operations.
- Ruminants:Ammonia-based acid salt technology dominates Nordic dairy applications with technology transfer potential to Baltic and Polish herds.
Poultry anchors volume concentration. Aquaculture is climbing the fastest on value-per-ton metrics.
Form:
Volume distribution is shifting from liquid legacy systems toward solid forms as Brazilian and Indonesian feed mills automate dosing infrastructure.
- Liquid:Historical standard for commodity acid delivery with established tank-and-pump infrastructure. Retrofit costs for powder handling are accelerating displacement in new mill construction.
- Powdered:Capturing share in automated dosing systems across Indonesian and Brazilian facilities upgrading conveying infrastructure. Ease of blending with dry feed premixes reduces handling complexity.
- Granular:Flowability advantages in high-throughput pelleting operations with reduced dust generation versus powdered alternatives.
- Solid:Encapsulated and coated variants enabling gut-targeted release in premium ruminant and poultry specifications.
Liquid retains the installed base. Powdered forms are gaining share fastest on automation tailwinds.
Application:
Customer type bifurcation separates preservation buyers seeking commodity cost efficiency from nutritional additive purchasers demanding species-specific efficacy documentation.
- Feed Preservation:Mold inhibition and shelf-life extension drive propionic acid demand in grain storage and finished feed protection. Backward-integrated chemical majors control feed-grade supply.
- Nutritional Additive:Gut health and nutrient digestibility improvement command premium positioning with encapsulated delivery systems competing on targeted release performance.
- Acidification:Gastric pH reduction in young animals supports post-weaning transition and pathogen suppression in monogastric operations.
- pH Regulation:Water and feed matrix buffering requirements in aquaculture and specific ruminant diet formulations.
Feed preservation commands the volume base. Nutritional additive applications are expanding most quickly on value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU 1831/2003 additive reforms are accelerating feed acid approvals across major protein-producing regions. Southeast Asian poultry integration and Latin American feed mill automation are pulling demand toward preservation-grade and precision-delivery formulations.
United States
GRAS self-affirmation pathways streamline novel acid blend introductions for swine and poultry integrators. FDA oversight shapes residue-testing protocols that constrain multi-jurisdictional suppliers. Iowa and North Carolina concentrate procurement power among large-scale pork and broiler operations standardizing acidified nursery and pre-starter specifications.
Germany
FAMI-QS certification mandates collapse the supplier base for compound feed acidifiers across Bavaria and Lower Saxony. EFSA evaluations under EU 1831/2003 force reformulation of legacy propionic acid blends. Chemical majors with backward integration into feed-grade acid production anchor cost positions in preservation applications.
Vietnam
Large-scale poultry farms in the Mekong Delta standardize acidification protocols for contract hatcheries. The Ministry of Agriculture and Rural Affairs restricts organic acid selections to positive-list additives. Integrated operators in Dong Nai and Long An provinces consolidate procurement around encapsulated formic acid for pre-starter feeds.
Brazil
Automated dosing system upgrades in Paraná and Rio Grande do Sul feed mills accelerate powdered acid adoption. ANVISA regulates additive safety documentation for export-oriented pork and poultry operations. São Paulo state integrators specify granular acid forms for high-throughput pelleting infrastructure.
China
Positive-list constraints from the Ministry of Agriculture and Rural Affairs restrict formulation flexibility for compound feed exporters. GB standards govern organic acid purity thresholds in Shandong and Guangdong feed manufacturing clusters. Yangtze River Delta operations face the steepest compliance costs under dual carbon goals affecting chemical acid production.
Feed Acid Market Vendor Landscape
Player mix skews toward backward-integrated chemical majors and encapsulated-delivery specialists. Three tiers structure the vendor base: multinational chemical conglomerates controlling propionic acid supply, regional blenders pursuing FAMI-QS certification, and technology-focused innovators competing on gut-targeted release. Dominant competitive moves include capacity expansion in feed-grade acid production and strategic partnerships for automated dosing system integration.
Within the chemical-major tier, BASF SE and Yara International ASA exemplify upstream-controlled positioning. BASF SE leverages captive propionic acid production to sustain cost leadership in preservation-grade formulations. Yara International ASA anchors ammonia-based acid salt technology that dominates Nordic ruminant applications. Kemin Industries Inc. occupies the specialist tier, representing encapsulated delivery system innovation competing on targeted gastric release performance.
| Leading Market Players |
|---|
| BASF SE |
| Yara International ASA |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Kemin Industries Inc. |
| Eastman Chemical Company |
| DSM |
| Perstorp Holding AB |
| Corbion |
| Others |
Supply Flow & Price Mechanics
FAMI-QS certification gates both supplier qualification and price differentiation simultaneously, compressing non-certified European blenders into commodity tiers while accredited operators capture preservation-grade premiums through backward-integrated propionic acid supply.
Pricing Analysis
Certification level creates the primary spread between FAMI-QS accredited and non-accredited supply tiers. Pricing stratifies across premium encapsulated delivery systems, standard preservation-grade formulations, and economy liquid acid commodities. Cost compression in the economy tier is intensifying because Vietnamese and Indonesian integrators consolidate procurement around pre-starter specifications. Poultry integrators exhibit the lowest price sensitivity due to margin capture through centralized additive specification, while independent regional blenders face acute margin pressure from chemical major cost leadership.
Supply Chain Analysis
Inventory cycles for feed-grade propionic acid extend through German and Dutch chemical production clusters, creating lead-time vulnerability for non-integrated blenders. Supply concentrates in Germany, China, and the United States for feed-grade organic acid manufacturing. Raw material flows draw from methanol carbonylation for acetic acid derivatives and petroleum refining byproducts for propionic acid feedstocks. Single-source vulnerability runs through BASF SE's captive propionic acid capacity in Ludwigshafen. Distribution runs through regional compound feed mill networks with direct-to-integrator contracts displacing distributor channels in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as species-specific delivery requirements and divergent regulatory compliance standards create niche specialization openings for targeted entrants.
For Market Incumbents: Fortify cost leadership through captive propionic acid supply expansion in preservation-grade formulations. Deepen certification moats by accelerating FAMI-QS accreditation timelines for European compound feed channels. Capacity addition in Vietnam's Mekong Delta captures integrator procurement consolidation. Encapsulation R&D investment defends against technology-focused specialists competing on gut-targeted release performance. For New Entrants and Emerging Players: Anchor in Baltic and Polish ruminant markets where ammonia-based acid salt technology transfer from Nordic operations remains incomplete. Aquaculture pH precision applications in Indonesian shrimp operations represent the most penetrable segment due to specification complexity exceeding incumbent commodity focus. Direct technical sales to marine farm operators bypasses consolidated poultry procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across encapsulated delivery system manufacturing due to microencapsulation equipment requirements and specialized coating infrastructure. Long-term viability favors technology-focused specialists with species-specific formulation capabilities over commodity acid blenders facing chemical major price pressure. Acquisition target archetype: regional European blenders possessing FAMI-QS certification and established integrator relationships in Vietnam or Indonesia. The signal to watch is automated dosing system adoption rates in Brazilian and Indonesian feed mills as an indicator of powder-form demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propionic Acid | BASF SE's captive supply anchors cost leadership in preservation-grade formulations against independent blenders. |
| Encapsulation Technology Scale-Up | Gut-targeted release systems enable premium positioning in Vietnamese pre-starter feed specifications. |
| FAMI-QS Certification Investment | Accreditation compliance gates European compound feed channel access and sustains margin premiums. |
| Automated Dosing System Partnership | Integration with Indonesian and Brazilian feed mill upgrades accelerates powdered acid form adoption. |
| Aquaculture pH Precision Development | Lactic acid blend specialization captures premium pricing in shrimp operations exceeding poultry tolerance ranges. |
Methodological Framework
A standing panel of feed mill procurement directors, poultry integrator nutritionists, acid blender technical sales managers, and regulatory affairs specialists provided ongoing calibration throughout the study period. Primary interviews with compound feed manufacturers and integrated protein operators combined with secondary validation from EU 1831/2003 additive framework documentation, FAMI-QS certification registries, and customs trade data for organic acid shipments. Bottom-up volume builds across formic acid, propionic acid, lactic acid, and blended formulations triangulated against top-down chemical industry production disclosures.
Consistency checks against EFSA evaluation timelines and Vietnamese Ministry of Agriculture positive-list amendments validated projection outputs across the analysis window. Segmentation modeling incorporated product type chemistry, end-user species requirements, physical form handling characteristics, and application purpose dimensions. CAGRs derived from fitted growth curves applied to baseline consumption estimates, with cross-reference to poultry integration rates in Southeast Asia and feed mill automation capex cycles in Latin America.
Material uncertainties — regulatory approval delays for novel acid derivatives, propionic acid supply disruptions from chemical production outages, and integrator procurement consolidation beyond modeled concentration levels — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding antibiotic growth promoter ban enforcement timelines and certification adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Global Cattle Feed and Feed Additives Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
China Feed Enzymes Market