
 North America Feed Amino Acids Market | 2026-2036
North America Feed Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Amino Acids Market Analytics
Pharmaceutical-grade amino acid specifications for antibiotic-free poultry diets is collapsing the gap between commodity lysine and premium methionine derivatives. Archer Daniels Midland Company leverages its Midwest corn processing footprint to anchor captive fermentation capacity for lysine output. Evonik Industries AG differentiates through methionine hydroxy analog technology that sustains higher bioavailability claims in ruminant applications. Kemin Industries specializes in microencapsulated delivery formats that protect amino acids from rumen degradation.
Feed amino acids are crystalline or liquid organic compounds containing amino and carboxyl functional groups, produced via bacterial fermentation of carbohydrate feedstocks or chemical synthesis, formulated to precise digestible amino acid coefficients for monogastric and ruminant nutrition. Lysine dominates volume demand as the first limiting amino acid in corn-soybean meal formulations for swine and poultry, while methionine commands premium positioning due to synthetic production complexity and its essential role in feather synthesis and muscle development. Threonine and tryptophan represent faster-growing specialty categories where precision nutrition protocols are displacing crude protein minimums with balanced amino acid ratios.
The FDA's Veterinary Feed Directive restricts medically important antibiotics in livestock feed, redirecting formulation investment toward amino acid density as a growth performance substitute. EPA nutrient management plans for concentrated animal feeding operations in Iowa and North Carolina mandate phosphorus and nitrogen budgets that favor amino acid-supplemented low-protein diets to reduce excretion loads. The USDA Organic Livestock and Poultry Practices rule creates a parallel certification tier requiring synthetic amino acid documentation that shapes supplier qualification protocols. Stakeholders must monitor whether state-level right-to-farm litigation in the Carolinas constrains expansion permits for new amino acid blending facilities near growing poultry complexes.
Market Dynamics
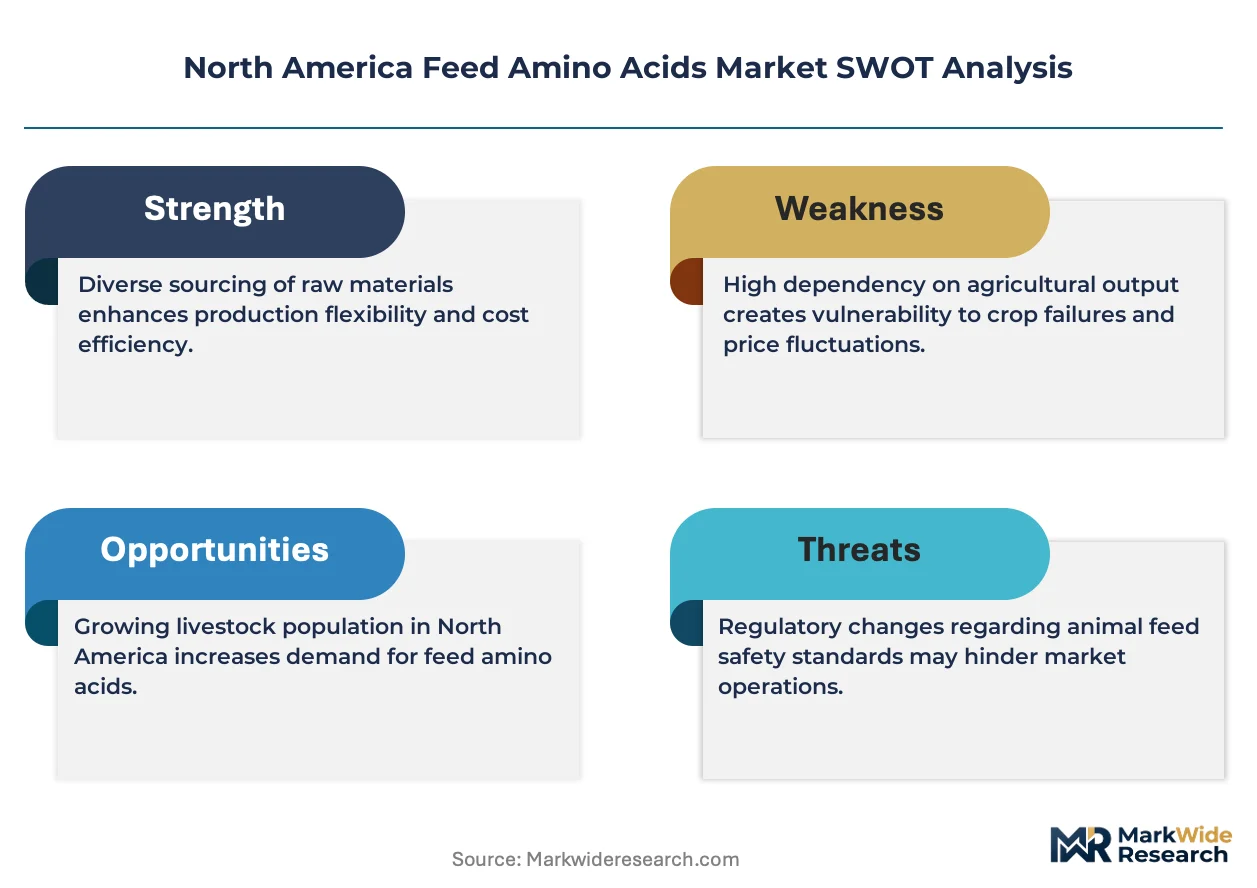
EPA nutrient management mandates for concentrated animal feeding operations are forcing feed formulators across Iowa and North Carolina to adopt low-protein, amino acid-dense diets that reduce nitrogen and phosphorus excretion while maintaining livestock performance metrics.
Growth Catalysts
- FDA Veterinary Feed Directive:Restrictions on medically important antibiotics in livestock feed redirect investment toward amino acid density as a primary growth performance substitute in swine and poultry operations.
- Broiler integrators in the southeastern United States:Vertically integrated poultry complexes are expanding amino acid offtake volumes faster than any other buyer segment in the North American market.
- Precision fermentation capacity:Bacterial fermentation of Midwest corn-derived carbohydrate feedstocks anchors domestic lysine production and reduces import dependency for limiting amino acids.
Market Restraints
- Feedstock price volatility:Corn and soybean meal input costs fluctuate with Midwest harvest yields and biofuel policy shifts, compressing margin predictability for amino acid blenders.
- Production concentration risk:A majority of synthetic methionine capacity sits with European and Asian chemical manufacturers, exposing North American buyers to transatlantic shipping disruptions and currency exposure.
- Rumen degradation limitation:Unprotected amino acids face rapid microbial breakdown in ruminant digestive systems, requiring expensive microencapsulation or analog formulations to achieve bioavailability targets.
Strategic Opportunities
- USDA Organic certification tier:The Organic Livestock and Poultry Practices rule creates supplier qualification protocols for documented synthetic amino acid sourcing, opening premium positioning for compliant manufacturers.
- Threonine and tryptophan specialty categories:Precision nutrition protocols displacing crude protein minimums with balanced amino acid ratios accelerate demand for faster-growing specialty amino acids beyond lysine and methionine.
- Methionine hydroxy analog convergence:Liquid analog technology paired with automated feed mill dosing systems enables ruminant applications with superior bioavailability claims compared to crystalline DL-methionine.
Industry Challenges
- Blending facility siting complexity:State-level right-to-farm litigation in the Carolinas constrains expansion permits for new amino acid production and blending facilities near growing poultry complexes.
- Digestible amino acid coefficient calibration:Feed mills must invest in laboratory infrastructure and technical staff to formulate to precise coefficients rather than crude protein percentages, stretching operational capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Amino Acids Market |
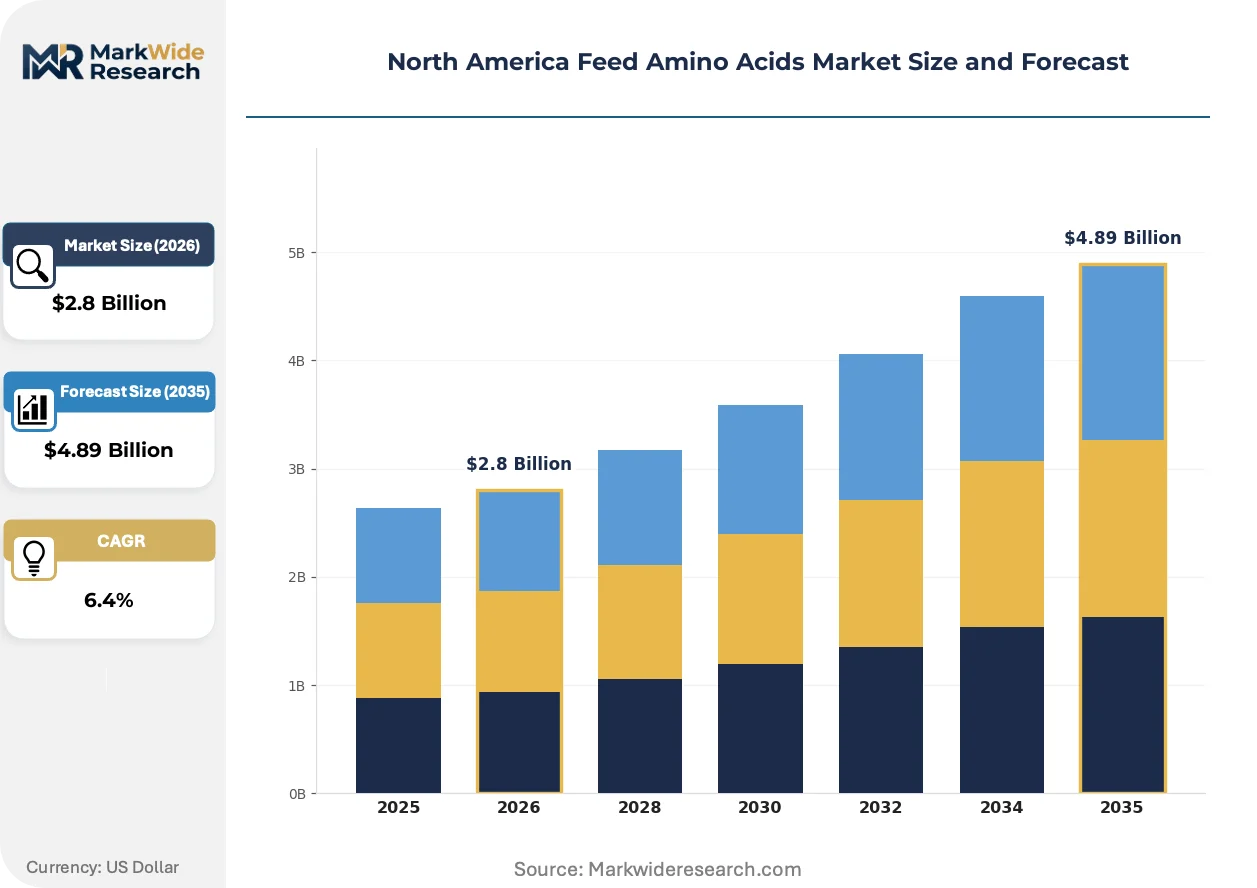
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lysine, Methionine, Threonine, Tryptophan End User: Poultry, Aquaculture, Swine, Ruminants Form: Liquid, Powder, Granular, Blend Distribution Channel: Direct Sales, Distributors, Retail, E-commerce |
| Companies Covered | Ajinomoto Co., Inc., Kemin Industries, Archer Daniels Midland Company, Alltech Inc, Adisseo, Cargill, Incorporated, Novus International, Inc., Land O'Lakes, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Amino Acids Market Evolving Landscape
Formulation science is pivoting from crude protein targets to precise digestible amino acid coefficients, compressing the historical gap between commodity lysine and premium methionine derivatives while opening specialty categories for threonine and tryptophan.
Microencapsulated delivery formats are displacing unprotected crystalline amino acids in ruminant feed applications. Dairy nutritionists in Wisconsin and New York are adopting lipid-coated lysine and methionine products at accelerating rates. This technology is displacing conventional bypass protein sources and enabling lower-cost total mixed ration formulations without sacrificing milk yield or component quality.
EPA revised Clean Water Act permitting for concentrated animal feeding operations tightens nutrient management requirements across Iowa hog operations and North Carolina poultry complexes. Industrial consequence includes mandatory phosphorus and nitrogen budgets that favor amino acid-supplemented low-protein diets. Swine integrators in the Corn Belt are responding by reformulating around standardized ileal digestible lysine coefficients rather than crude protein minimums.
Integrator procurement departments are consolidating amino acid purchasing through long-term supply agreements with fermentation-based domestic producers. Traditional spot-market buying through distributors is contracting as vertically integrated pork and poultry complexes negotiate direct mill-delivered contracts. This concentration is most visible across the southeastern United States, where broiler integrators now command sufficient volume to justify dedicated logistics infrastructure and technical service support from lysine suppliers.
North America Feed Amino Acids Market Segmentation
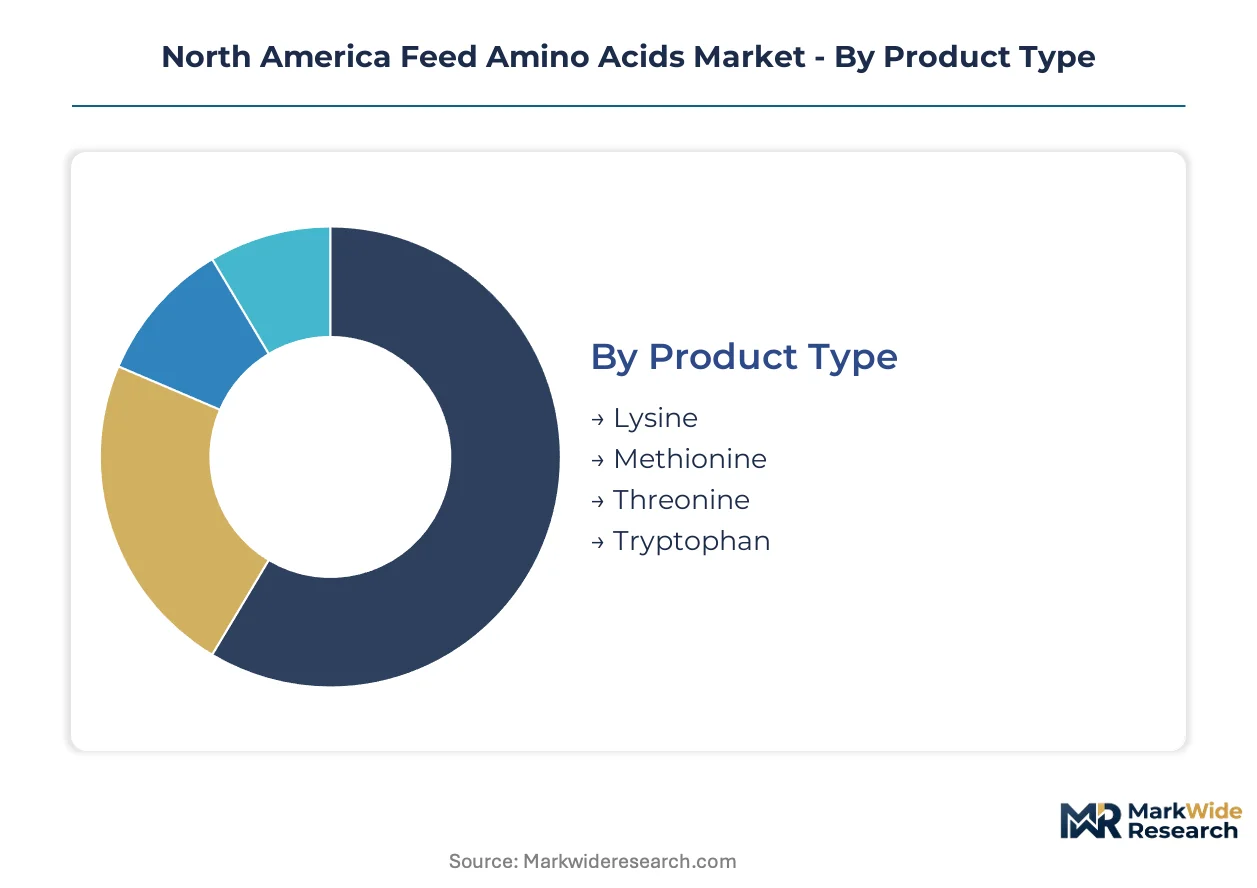
Feed amino acid suppliers configure production and logistics around distinct product specifications, animal species requirements, and channel economics. Segmentation discipline reveals where formulation investment concentrates and which delivery formats command premium positioning.
Product Type:
Lysine moves primarily through direct mill contracts with vertically integrated pork and poultry complexes, while methionine derivatives flow through technical distributors serving ruminant nutritionists.
- Lysine:Crystalline L-lysine produced via bacterial fermentation of corn-derived carbohydrate feedstocks serves as the first limiting amino acid in corn-soybean meal formulations. Demand concentrates across Iowa and North Carolina, where vertically integrated hog and broiler operations mandate standardized ileal digestible coefficients under EPA nutrient management plans.
- Methionine:Synthetic DL-methionine and hydroxy analog liquid formulations address sulfur amino acid requirements in feather synthesis and muscle development. Southeastern broiler integrators represent the fastest-expanding buyer segment, driving volume through automated feed mill dosing systems that favor liquid analog delivery.
- Threonine:Precision nutrition protocols displacing crude protein minimums accelerate threonine adoption in low-protein diet formulations for swine and poultry.
- Tryptophan:Specialty category gaining traction in antibiotic-free poultry diets where balanced amino acid ratios substitute for growth-promoting pharmaceuticals.
By volume, lysine leads. By growth pace, methionine hydroxy analogs are expanding most quickly.
End User:
Species-specific digestive physiology dictates bioavailability requirements and formulation complexity, with monogastric applications driving volume and ruminant segments commanding premium pricing for protected formats.
- Poultry:Broiler and layer operations across the southeastern United States consume lysine and methionine at the largest scale, with integrators consolidating procurement through long-term supply agreements that displace spot-market buying.
- Swine:Corn Belt hog operations reformulate around digestible amino acid coefficients to meet EPA phosphorus and nitrogen budgets, reducing excretion loads while maintaining feed conversion ratios.
- Ruminants:Dairy nutritionists in Wisconsin and New York adopt microencapsulated lysine and methionine products at accelerating rates, displacing conventional bypass protein sources in total mixed rations.
- Aquaculture:Salmon and shrimp feed producers on the Pacific Coast and Gulf Coast represent a developing specialty channel with distinct marine protein formulation requirements.
Poultry commands the largest volume share. Ruminant applications generate the highest margin per kilogram due to encapsulation technology premiums.
Form:
Physical format selection hinges on feed mill automation infrastructure, with liquid systems favoring large integrators and powder formats retaining relevance for smaller compounders.
- Liquid:Methionine hydroxy analogs delivered via automated dosing systems enable precise inclusion rates and superior bioavailability claims in ruminant applications.
- Powder:Crystalline lysine and methionine retain dominance among mid-sized feed compounders lacking liquid handling infrastructure.
- Granular:Flowability-enhanced formats reduce dust exposure and improve handling characteristics in high-volume poultry feed mills.
- Blend:Pre-mixed amino acid complexes simplify procurement for smaller operations but sacrifice formulation flexibility.
Liquid formats are gaining share fastest in new mill construction. Powder maintains the broadest installed base across existing infrastructure.
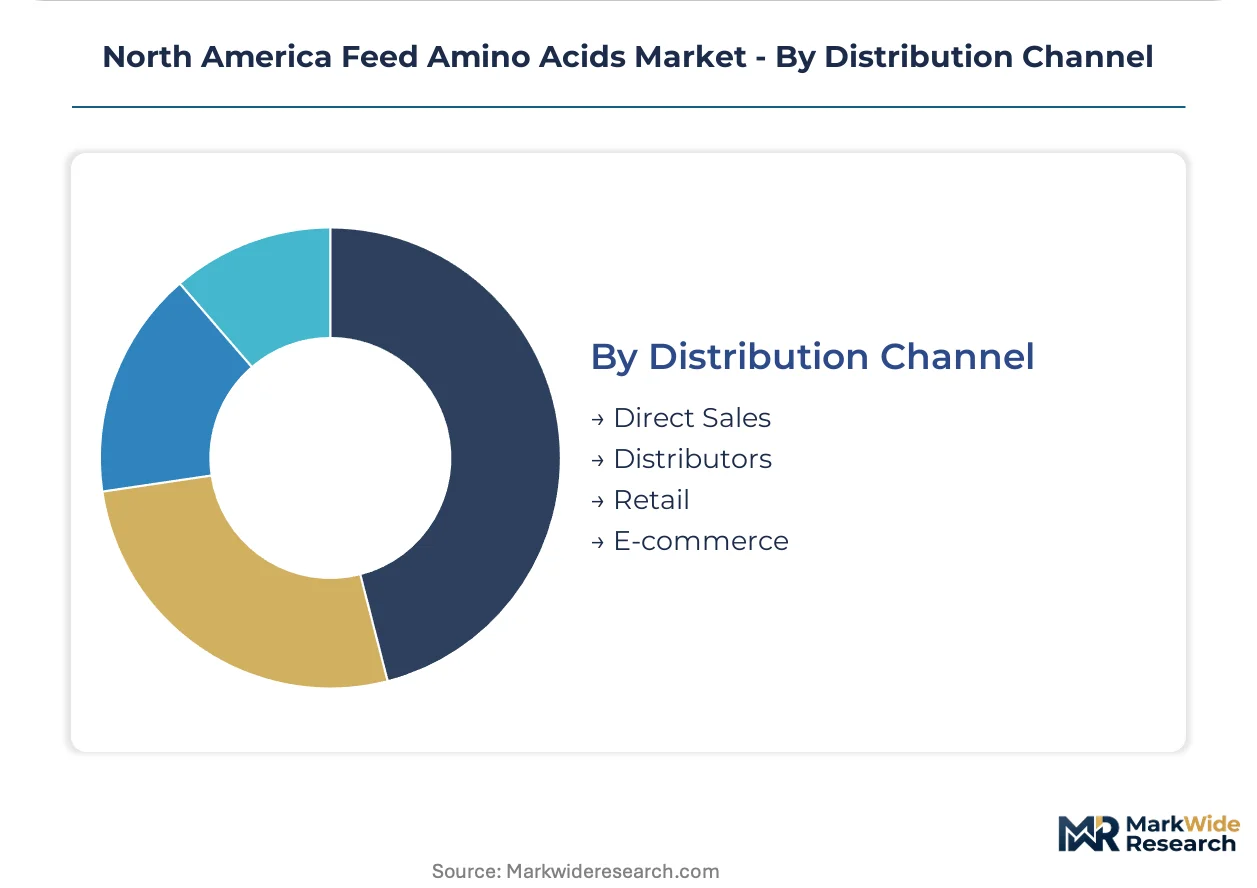
Distribution Channel:
Channel structure is bifurcating between direct contracts for volume buyers and distributor networks for technical service and smaller accounts.
- Direct Sales:Vertically integrated pork and poultry complexes negotiate mill-delivered contracts with fermentation-based domestic producers, consolidating purchasing power and securing dedicated logistics infrastructure.
- Distributors:Technical distributors retain relevance for methionine analogs and specialty amino acids requiring nutritionist support and formulation expertise.
- Retail:Farm supply stores and cooperatives serve smaller livestock operations with bagged and small-batch amino acid products.
- E-commerce:Emerging channel for specialty amino acid samples and research quantities, with limited penetration in bulk feed ingredient procurement.
Direct sales capture the largest volume flow. Distributor relationships sustain the steepest expansion trajectory in technical specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based fermentation capacity exports lysine and methionine derivatives to Canadian and Mexican livestock operations under integrated North American supply chains. Cross-border trade flows concentrate on bulk liquid amino acids for large-scale poultry and swine integrators.
United States
Midwest corn processing clusters anchor bacterial fermentation capacity for L-lysine production, with Iowa hog operations and North Carolina poultry complexes driving the largest domestic offtake volumes. EPA Clean Water Act permitting tightens nutrient management requirements, mandating phosphorus and nitrogen budgets that favor low-protein, amino acid-dense feed formulations. Southeastern broiler integrators in Georgia and Alabama represent the fastest-expanding buyer segment, consolidating procurement through direct mill-delivered contracts.
Canada
Prairie livestock operations in Alberta and Saskatchewan source methionine hydroxy analogs for ruminant feed applications, with dairy nutritionists adopting microencapsulated delivery formats at accelerating rates. Health Canada feed ingredient regulations align with FDA Veterinary Feed Directive restrictions on antibiotic growth promoters, redirecting formulation investment toward amino acid density. Ontario-based feed compounders serve as distribution hubs for specialty threonine and tryptophan products targeting antibiotic-free poultry diets.
Mexico
Central Mexico poultry complexes in Guanajuato and Querétaro import synthetic methionine from U.S. Gulf Coast production facilities, with vertically integrated broiler operations expanding amino acid offtake faster than traditional spot-market channels. Mexican agricultural regulators enforce feed safety standards that mirror USDA documentation requirements for synthetic amino acid sourcing. Baja California aquaculture producers represent an emerging specialty channel for marine protein formulations requiring distinct amino acid profiles.
North America Feed Amino Acids Market Competitive Landscape
Listed leaders compete with private specialists across fermentation capacity and formulation technology. The vendor base consolidates around three to five dominant fermentation-based producers, with mid-sized compounders occupying technical specialty niches. Strategic archetypes include Midwest corn processors with captive lysine output, European chemical manufacturers with methionine analog technology, and microencapsulation specialists serving ruminant nutritionists. Capacity expansion and long-term supply agreements constitute the dominant competitive moves, displacing traditional spot-market relationships.
Among fermentation-based producers, Archer Daniels Midland Company exemplifies the Midwest corn processor archetype with integrated carbohydrate feedstock access. Evonik Industries AG occupies a position within the methionine hydroxy analog tier, while Kemin Industries represents the microencapsulation specialist archetype protecting amino acids from rumen degradation. These three anchors illustrate how geographic feedstock control, synthetic production complexity, and delivery format innovation stratify competitive positioning across species-specific applications.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Kemin Industries |
| Archer Daniels Midland Company |
| Alltech Inc |
| Adisseo |
| Cargill, Incorporated |
| Novus International, Inc. |
| Land O'Lakes |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Fermentation scale economies at Midwest corn processing clusters concentrate lysine supply among three to five dominant producers, compressing price floors for crystalline grades while elevating premiums for microencapsulated and analog formulations. This concentration dynamic grants volume buyers direct contract leverage while fragmenting pricing power across specialty delivery formats.
Pricing Analysis
Current-generation liquid methionine hydroxy analogs command 15-25% premiums over prior-generation crystalline DL-methionine, while next-generation microencapsulated ruminant formats sustain the steepest markups. The dominant structure runs through contract-based long-term offtake agreements consolidating procurement for vertically integrated poultry and pork complexes. Price differentiation hinges on bioavailability certification tiers and volume scale, with EPA nutrient management compliance documentation adding further standard-to-premium separation. Pricing pressure stems from Midwest corn feedstock volatility compressing fermentation margins, while spot-market buyers exhibit the highest price sensitivity against locked-in integrator contracts.
Supply Chain Analysis
Inventory cycles for synthetic methionine stretch 8-12 weeks given transatlantic shipping dependencies, while domestic lysine fermentation maintains 3-4 week lead times from Midwest carbohydrate feedstocks. Supply concentrates in the United States for bacterial fermentation capacity, Germany and Belgium for methionine hydroxy analog chemical synthesis, and China for crystalline methionine precursor intermediates. Raw material dependencies center on corn dextrose, petrochemical methanol, and sulfur-based synthesis inputs. Single-source vulnerability runs through European methionine analog capacity exposed to Rhine logistics disruptions. Distribution runs through direct mill-delivered contracts for volume buyers and technical distributors for specialty amino acid formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA Veterinary Feed Directive's antibiotic restrictions have triggered a formulation inflection toward amino acid density as the primary growth performance substitute, creating a high-growth disruption window for precision nutrition suppliers.
For Market Incumbents: Fortify captive fermentation capacity through backward integration into Midwest corn processing assets to secure carbohydrate feedstock cost advantages against import-dependent competitors. Deepen technical service infrastructure for automated feed mill dosing systems to lock in southeastern broiler integrator contracts before European methionine analog suppliers expand North American blending footprints. For New Entrants and Emerging Players: Differentiate on microencapsulation technology for ruminant bypass protection, targeting Wisconsin and New York dairy nutritionists displacing conventional protein sources with lipid-coated lysine and methionine formats. The most penetrable white space sits in threonine and tryptophan specialty categories where precision nutrition protocols are displacing crude protein minimums, with a go-to-market angle anchored on antibiotic-free poultry certification documentation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-based domestic producers with integrated feedstock access over import-dependent chemical synthesis operations. Long-term viability over a multi-year horizon rests on EPA nutrient management mandate expansion entrenching low-protein, amino acid-dense formulations as regulatory compliance infrastructure. Acquisition targets should screen for microencapsulation R&D capabilities and direct mill contract books. The critical signal to watch is state-level right-to-farm litigation outcomes in the Carolinas that could constrain or unlock blending facility expansion permits near growing poultry complexes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Midwest carbohydrate feedstock control anchors lysine fermentation cost competitiveness against Asian imports. |
| Microencapsulation R&D Expansion | Lipid-coating technology protects amino acids from rumen degradation in Wisconsin dairy applications. |
| Long-term Supply Agreements | Direct mill contracts with Georgia and Alabama broiler integrators displace spot-market distributor relationships. |
| Automated Dosing System Partnerships | Liquid analog integration with feed mill infrastructure locks in methionine hydroxy analog volume commitments. |
| EPA Compliance Documentation Investment | Nutrient management plan certification enables premium positioning for low-protein diet formulations. |
Research Methodology
Operator-level perspectives from fermentation plant managers, feed mill procurement directors, poultry nutritionists at integrator complexes, and EPA regional compliance officers anchored the qualitative base. These primary inputs combined with secondary validation from USDA Organic certification records, FDA Veterinary Feed Directive implementation reports, SEC 10-K filings of listed fermentation producers, and Iowa-North Carolina state environmental permit databases. Bottom-up volume estimates from species-specific feed conversion ratios triangulated against top-down amino acid inclusion rate trends across the analysis window.
Sensitivity analysis tested forecast robustness against corn price volatility scenarios and methionine import disruption events. The analytical framework segmented by product type, animal species, physical form, and distribution channel across the projection horizon, with CAGRs derived from trend extrapolation of integrator procurement consolidation and precision nutrition adoption curves. Industry-specific inputs included EPA nutrient management plan expansion timelines and FDA antibiotic restriction enforcement patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory pressure on crude protein minimums or accelerated adoption of automated feed mill infrastructure would require recalibration. Forecasts reflect documented assumptions about integrator vertical integration trends and fermentation capacity expansion schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Agricultural Miticides Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Europe Feed Pelletizing Agents Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Feed Preservatives Market