
 Fungicides Market | 2026-2036
Fungicides Market Size, Share, and Industry Trends Forecast 2026-2036
Fungicides Market Intelligence
Capital-intensity divergence between integrated formulators and asset-light distributors is rotating competitive advantage toward upstream molecule ownership. Syngenta AG leverages its proprietary azole chemistry pipeline to sustain premium positioning in systemic fungicides. Bayer AG anchors its portfolio through seed treatment integration with genetically resistant crop platforms. BASF SE competes on manufacturing scale in triazole active ingredients, extending cost advantages across Latin American markets.
Fungicides are crop protection chemicals formulated with active ingredients such as triazoles, strobilurins, or biological agents that inhibit fungal spore germination, mycelial growth, or cell division through disruption of ergosterol biosynthesis or mitochondrial respiration pathways. Their primary commercial purpose is to prevent yield loss in agricultural production systems by controlling powdery mildew, rusts, blights, and soil-borne pathogens. Systemic fungicides command the largest value share due to curative properties and longer residual activity, while biopesticides represent the fastest-expanding product type as residue-sensitive export markets tighten MRL thresholds. Cereal crops absorb the highest fungicide volumes globally, though horticultural crops generate superior margins per hectare through intensive spray programs targeting high-value produce.
The EPA regulates fungicide registration through FIFRA-mandated risk assessments, while the EU Green Deal and REACH framework are phasing out high-risk active ingredients and mandating substitution with lower-toxicity alternatives. Brazil's national agricultural regulator enforces residue monitoring that shapes export-oriented fungicide selection, directly influencing formulation strategies for soybean and corn producers. Stakeholders must monitor regulatory divergence between jurisdictions, as simultaneous compliance with EPA tolerances, EU MRL harmonization, and emerging market biosafety requirements will determine portfolio viability and market access trajectories.
Market Dynamics
Resistance escalation in soybean rust and wheat septoria is forcing shorter fungicide rotation cycles and stacking of multiple mode-of-action products, compressing product lifecycles and raising R&D amortization pressure on formulators.
Growth Catalysts
- EU Green Deal residue tightening:The EU Green Deal and EFSA MRL revisions are accelerating biological fungicide registrations as export-oriented growers in Spain and Italy switch to residue-compliant programs for stone fruit and vegetables.
- Brazil soybean rust intensity:Brazilian soybean producers apply three to four fungicide sprays per season against Phakopsora pachyrhizi, sustaining demand for triazole-strobilurin premixes in Mato Grosso and Paraná.
- Gene editing convergence:CRISPR-edited resistant germplasm from Bayer and Corteva is creating integrated seed-treatment-foliar bundles that lock in fungicide pull-through.
Market Restraints
- Active ingredient supply concentration:Chinese manufacturers control over 70% of technical-grade azole and strobilurin production, exposing formulators to export license volatility and freight cost spikes.
- REACH authorization costs:ECHA's REACH substance evaluation and candidate list expansion are forcing withdrawal of older triazoles, eroding portfolio breadth for European cereal growers.
- Biological efficacy gaps:Bacillus-based biofungicides show inconsistent field performance under high disease pressure, limiting substitution potential in intensive corn-soy systems.
Strategic Opportunities
- India horticultural expansion:Grape, mango, and tomato growers in Maharashtra and Karnataka are adopting protective fungicide programs as cold chain infrastructure enables export to Middle Eastern markets.
- Drone application channels:UAV-based ultra-low-volume spraying is penetrating Brazilian and Australian broadacre operations, reducing labor costs and enabling precise timing of curative applications.
- Carbon credit stacking:Biological fungicide use is qualifying for voluntary carbon market credits under Verra protocols, creating price subsidies for residue-sensitive specialty crop producers.
Industry Challenges
- Resistance monitoring infrastructure:Pathogen surveillance networks in Argentina and Ukraine lack real-time genotyping capacity, delaying detection of azole-resistant rust mutations.
- Formulation reregistration timelines:EPA FIFRA data call-ins and EU peer review extensions are stretching product defense costs across 8-12 year cycles, straining mid-tier generic portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fungicides Market |
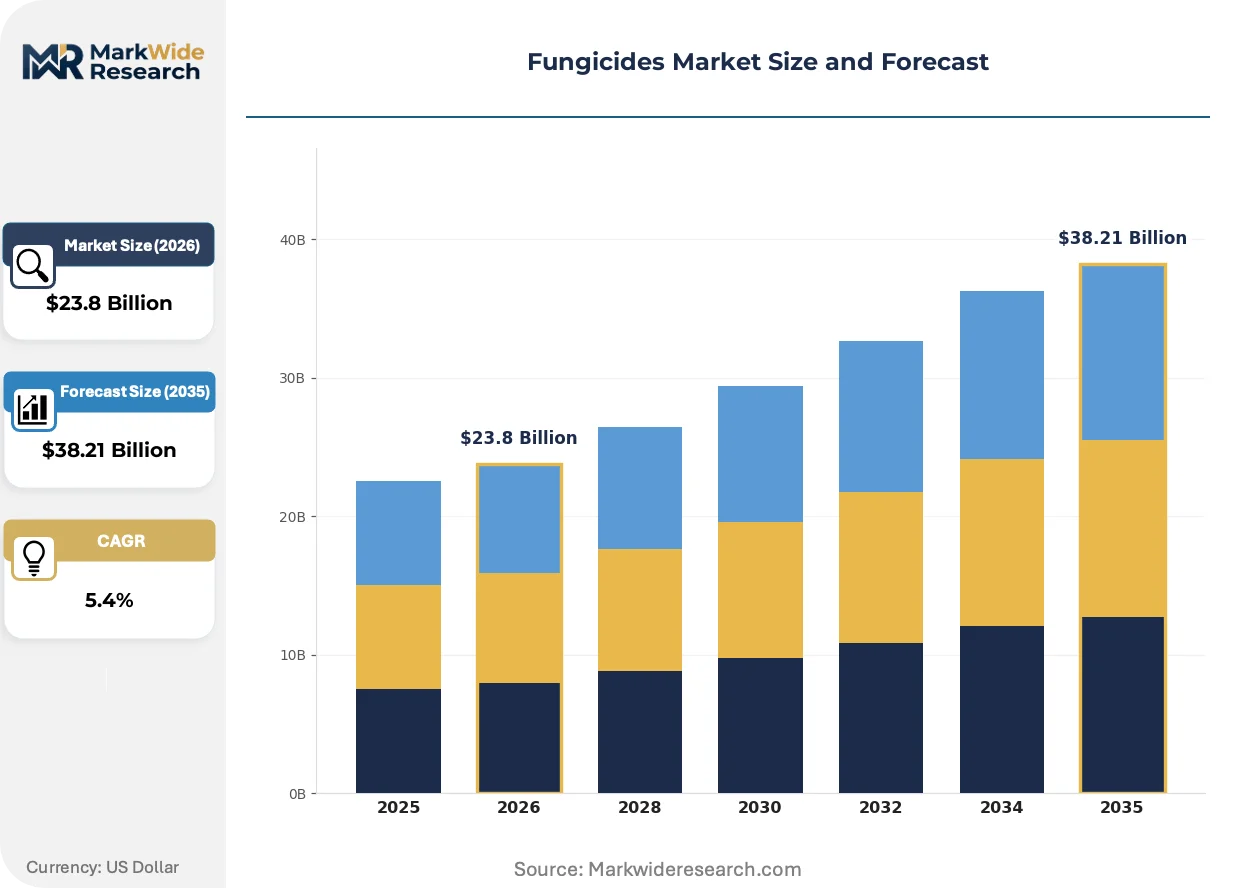
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $38.21 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Fungicides, Systemic Fungicides, Biopesticides, Seed Treatment Fungicides, Others Application: Cereal Crops, Horticultural Crops, Oilseeds & Pulses, Cash Crops, Plantation Crops Formulation: Granules, Wettable Powders, Emulsifiable Concentrates, Dusts, Flowables End User: Crop Producers, Agricultural Cooperatives, Agrochemical Distributors, Contract Growers |
| Companies Covered | Syngenta AG, Bayer AG, BASF SE, Corteva Agriscience, FMC Corporation, UPL Limited, Nufarm Limited, Sumitomo Chemical Co., Ltd., ADAMA Agricultural Solutions Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fungicides Market Strategic Shifts & Innovations
Biological and synthetic chemistries are diverging into parallel development tracks rather than substitution pathways, with each serving distinct residue-risk and efficacy requirements across crop tiers.
RNA interference fungicides targeting essential fungal genes through spray-induced gene silencing are advancing through field trials. Specialty vegetable growers in California and the Netherlands are piloting dsRNA formulations against Botrytis cinerea. The technology is bifurcating the market into precision-biologic and broad-spectrum-chemical segments with diverging price structures and service models.
EPA's revised endangered species consultation requirements under FIFRA Section 7 are extending registration timelines for new azole submissions. The agency's 2024 interim measures for salmonid protection are forcing buffer zone expansions and application rate reductions in Pacific Northwest wheat districts. Cereal fungicide portfolios are reformulating toward lower-use-rate SDHIs to maintain label viability under ecological mitigation mandates.
Aggregated purchasing cooperatives in France and Germany are consolidating procurement of cereal fungicide programs, displacing traditional distributor relationships. These farmer-owned pools negotiate direct supply contracts with BASF and Syngenta, capturing volume discounts and technical advisory bundling. The shift is most advanced in northern France's cooperative-dense wheat belt, where distributor margins have compressed by half.
Fungicides Market Segmentation
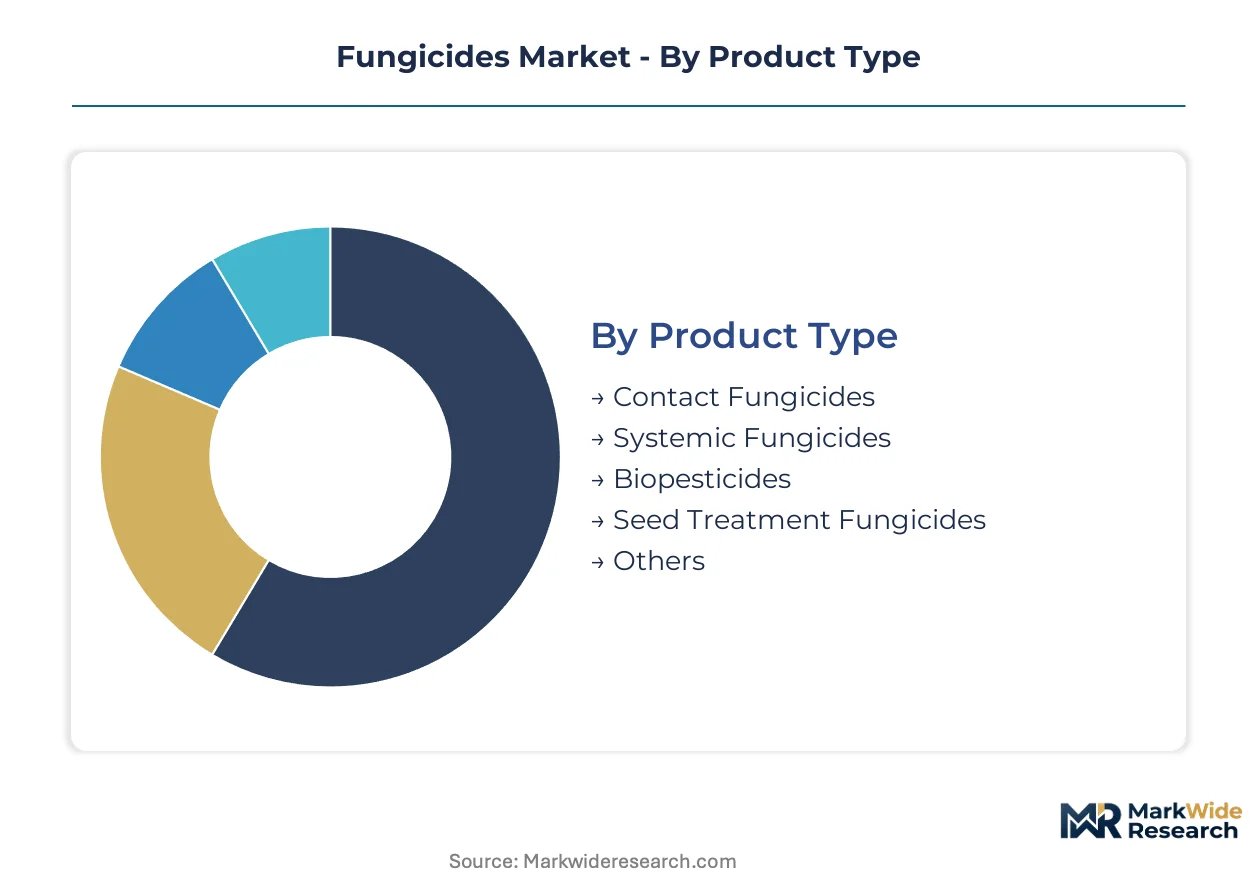
Fungicide segmentation reveals divergent pressure points across chemistry types, crop systems, and supply channels. Substitution threats from biological alternatives and resistance management protocols reshape competitive dynamics within each category.
Product Type:
Substitution pressure from residue regulations and resistance protocols varies sharply across chemistry classes, with synthetic actives facing the steepest displacement risk in export-oriented markets.
- Contact Fungicides:These surface-acting formulations create protective barriers that inhibit spore germination through multi-site biochemical disruption. Grape and vegetable growers in Spain and Italy favor contact products for pre-harvest intervals, though rainfastness limitations constrain adoption in tropical soybean systems.
- Systemic Fungicides:Xylem-mobile triazoles and SDHIs deliver curative activity with extended residual control through single-site mode-of-action targeting. Brazilian soybean rust management in Mato Grosso and Paraná absorbs the largest systemic volumes, though shorter rotation cycles compress product lifecycles under resistance pressure.
- Biopesticides:Microbial and botanical formulations derived from Bacillus subtilis, Trichoderma, and plant extracts qualify for EU organic certification and carbon credit protocols.
- Seed Treatment Fungicides:Prophylactic coatings combining triazoles and neonicotinoid synergists protect germinating cereals and oilseeds from soil-borne pathogens.
- Others:Fumigants and inorganic sulfur-based products serve niche applications in protected horticulture and organic systems.
Systemic fungicides retain volume leadership; biopesticides hold the steepest expansion curve.
Application:
Margin structure and spray intensity diverge dramatically across crop tiers, with high-value horticulture commanding premium pricing per hectare despite smaller absolute acreage.
- Cereal Crops:Wheat, rice, and barley absorb the highest fungicide tonnage globally, with septoria and rust management driving repeat applications across temperate growing regions. French and German cooperative purchasing pools negotiate direct supply contracts, compressing distributor margins in the process.
- Horticultural Crops:Stone fruit, vegetables, and berries generate superior margins per hectare through intensive protective spray programs. California specialty vegetable growers and Dutch greenhouse operators pilot RNA interference formulations against Botrytis cinerea.
- Oilseeds & Pulses:Soybean rust in Brazil and canola sclerotinia in Canada sustain demand for triazole-strobilurin premixes.
- Cash Crops:Cotton and sugarcane fungicide programs concentrate in Maharashtra and Karnataka as Indian export infrastructure expands.
- Plantation Crops:Banana black sigatoka and oil palm basal stem rot management drives fungicide use in Ecuador and Indonesia.
Cereal crops dominate procurement volume; horticultural applications deliver the highest value per treated hectare.
Formulation:
Application technology and labor cost trajectories favor liquid concentrates over solid carriers in mechanized broadacre systems.
- Granules:Slow-release carriers suit rice paddy and soil-incorporation applications where water management complicates foliar spraying.
- Wettable Powders:Dry flowables reconstitute in tank mixes for smallholder operations with limited storage infrastructure.
- Emulsifiable Concentrates:Oil-based solutions penetrate waxy cuticles and adhere under rainfall stress. Australian and Brazilian drone spraying operations favor EC formulations for ultra-low-volume aerial application.
- Dusts:Limited to seed dressing and greenhouse fumigation where precision application is secondary to cost minimization.
- Flowables:Aqueous suspensions reduce solvent exposure and enable high-loading active ingredient delivery.
Emulsifiable concentrates lead in commercial value; flowables gain share fastest in regulated markets.
End User:
Procurement consolidation and technical advisory requirements reshape channel economics across farmer typologies.
- Crop Producers:Individual farm operators in Argentina and Ukraine select fungicides based on local resistance monitoring and credit availability.
- Agricultural Cooperatives:French and German farmer-owned pools negotiate volume discounts and bundled technical services directly with formulators.
- Agrochemical Distributors:Inventory-carrying intermediaries face margin compression as cooperative purchasing and manufacturer direct channels expand.
- Contract Growers:Export-oriented producers in Brazil and India adopt residue-compliant programs specified by international buyers.
Agricultural cooperatives capture procurement volume leadership; contract growers expand most quickly under export quality protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and India exhibit acute price sensitivity to triazole cost fluctuations, while German and Dutch growers prioritize residue compliance over unit economics. This elasticity divergence fragments procurement strategies across export corridors.
Brazil
Soybean rust pressure in Mato Grosso and Paraná sustains three to four fungicide applications per season, with Phakopsora pachyrhizi resistance shortening rotation cycles. ANVISA enforces residue monitoring protocols that directly shape export-oriented formulation choices. The Cerrado agricultural frontier concentrates demand for triazole-strobilurin premixes as farm consolidation accelerates.
United States
EPA FIFRA Section 7 endangered species consultations are extending registration timelines for new azole submissions, compressing product lifecycles in Pacific Northwest wheat districts. The 2024 salmonid protection interim measures force buffer zone expansions and rate reductions. California specialty vegetable growers pilot RNA interference formulations against Botrytis cinerea in Salinas Valley.
Germany
Farmer-owned purchasing cooperatives in Schleswig-Holstein and Lower Saxony negotiate direct supply contracts with formulators, displacing traditional distributor relationships. ECHA REACH substance evaluation forces withdrawal of older triazoles from cereal programs. The northern wheat belt exhibits the most advanced cooperative procurement consolidation, with distributor margins compressing substantially.
India
Grape, mango, and tomato growers in Maharashtra and Karnataka adopt protective fungicide programs as cold chain infrastructure enables Middle Eastern export access. The country's national agricultural regulator tightens residue surveillance for export consignments. Nashik's grape cluster drives intensive strobilurin demand for downy mildew management in table grape production.
Netherlands
Greenhouse operators in Westland and Aalsmeer prioritize residue-compliant biological alternatives under EU Green Deal MRL tightening. EFSA revision schedules accelerate biofungicide registrations for ornamental and vegetable exports. The Dutch floriculture belt leads adoption of microbial formulations qualifying for voluntary carbon credit protocols under Verra standards.
Fungicides Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated formulators with proprietary molecule pipelines command premium positioning in systemic fungicides, while asset-light distributors face margin compression from cooperative purchasing and direct manufacturer channels. Three archetypes dominate: upstream chemical owners with captive active ingredient supply, seed-treatment integrators bundling genetic resistance with chemical protection, and biological specialists capturing residue-sensitive horticultural demand. Consolidation through molecule acquisition and manufacturing scale expansion represents the dominant competitive trajectory.
Among integrated agrochemical conglomerates, Syngenta AG, Bayer AG, and BASF SE exemplify the upstream-integrated archetype. Syngenta AG anchors premium positioning through proprietary azole chemistry development. Bayer AG occupies the seed-treatment convergence space, linking fungicide portfolios to genetically resistant crop platforms. BASF SE represents manufacturing scale leadership in triazole active ingredients, extending cost advantages across Latin American procurement channels.
| Leading Market Players |
|---|
| Syngenta AG |
| Bayer AG |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| UPL Limited |
| Nufarm Limited |
| Sumitomo Chemical Co., Ltd. |
| ADAMA Agricultural Solutions Ltd. |
| Others |
Cost & Logistics Intelligence
Ninety-day active ingredient inventory cycles at Chinese technical-grade manufacturers govern pricing power for triazole and strobilurin formulators, compressing margins when export license volatility disrupts just-in-time procurement for Brazilian soybean programs. This lead-time exposure concentrates cost pass-through ability among integrated molecule owners while fragmenting pricing leverage across distributor-dependent generic portfolios.
Pricing Analysis
After-sales technical advisory and resistance monitoring services drive lifetime value for systemic fungicide portfolios, with bundled agronomic support commanding 15-25% premia over commodity formulations. Three-tier pricing structure across premium proprietary chemistry, standard off-patent actives, and economy generic alternatives segments buyers by risk tolerance and export compliance requirements. Cost compression in standard-tier triazoles is intensifying because Chinese technical-grade oversupply and cooperative purchasing consolidation in France and Germany squeeze distributor markups. Contract growers in Brazil exhibit acute price sensitivity to azole cost fluctuations, while Dutch greenhouse operators prioritize residue compliance over unit economics.
Supply Chain Analysis
Inventory concentration at Chinese azole and strobilurin technical-grade manufacturers exposes formulators to single-source vulnerability when environmental compliance inspections trigger sudden production halts. Active ingredient supply draws from China, India, and Germany, with formulation capacity distributed across Brazil, the United States, and Western Europe. Raw material dependencies center on petrochemical intermediates, phosphorus derivatives, and biological fermentation feedstocks. Distribution runs through agricultural cooperatives in northern Europe, inventory-carrying distributors in South America, and direct manufacturer channels for large-scale Brazilian farm operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary molecule pipelines and real-time resistance genotyping capabilities constitute scarce assets that differentiate viable competitors from margin-compressed generic formulators. The gap between integrated upstream owners and asset-light distributors is widening as regulatory defense costs escalate.
For Market Incumbents: Shield premium positioning in systemic fungicides by deepening captive supply of azole active ingredients and accelerating RNA interference formulation development. Consolidate manufacturing scale in Latin American markets to capture cooperative procurement volume. Resistance monitoring infrastructure investments defend against biological substitution threats in EU residue-sensitive horticulture. For New Entrants and Emerging Players: Differentiate on carbon credit qualification and EU organic certification for biological fungicide portfolios targeting Dutch greenhouse and California specialty vegetable segments. Penetrate Indian horticultural expansion in Maharashtra grape and Karnataka mango clusters through cold chain-integrated distribution partnerships. Lead with drone-compatible ultra-low-volume formulation technology to capture Brazilian aerial application growth. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate agrochemical divisions seeking to divest mature off-patent portfolios amid REACH authorization cost pressure. Long-term viability favors upstream-integrated positions with proprietary pipeline assets over distributor-dependent generic exposure. Monitor EFSA MRL revision schedules and EPA FIFRA Section 7 consultation timelines as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Supply | Captive azole manufacturing insulates Brazilian formulators from Chinese export license volatility. |
| Biological Fungicide Registration Acceleration | EU Green Deal MRL tightening creates first-mover advantage in residue-compliant horticulture segments. |
| Drone Application Formulation Development | Ultra-low-volume EC compatibility captures labor cost reduction in Australian and Brazilian broadacre operations. |
| Resistance Monitoring Network Deployment | Real-time genotyping infrastructure defends azole portfolio viability against Phakopsora pachyrhizi mutation detection delays. |
| Cooperative Procurement Partnership | Direct supply contracts with French and German farmer-owned pools displace distributor intermediaries and capture volume concentration. |
Research Approach
Desk research of regulatory filings, customs trade data, and crop protection industry association reports preceded structured interviews with fungicide R&D directors, Brazilian agronomic technical advisors, EU regulatory affairs specialists, and Indian horticultural export coordinators. Primary fieldwork with resistance monitoring station operators and cooperative procurement managers validated secondary demand estimates. Bottom-up acreage-by-crop fungicide application rate modeling triangulated against top-down manufacturer revenue segmentation.
Variance decomposition across chemistry type, crop system, and regional regulatory cluster shaped the analytical framework throughout the forecast period. Modeled segmentation dimensions included product chemistry class, application crop tier, formulation technology, and end-user procurement channel. CAGRs derived from historical volume trajectories adjusted for resistance-driven rotation cycle compression and biological substitution elasticity. Key inputs incorporated EPA FIFRA registration timeline assumptions, EFSA MRL revision schedules, and Brazilian soybean rust pressure indices.
Material uncertainties — active ingredient supply disruptions, accelerated resistance mutation detection, and unscheduled regulatory withdrawals — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding cooperative purchasing consolidation velocity and drone adoption penetration curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
Agricultural Insect Pheromones Market