
 Organic Bromide Market | 2026-2036
Organic Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Bromide Market Analytics
Specialty chemical buyers is bifurcating from commodity purchasers as flame retardant and pharmaceutical intermediate specifications tighten. Albemarle Corporation leverages its vertically integrated bromine extraction and derivative production to dominate high-purity grades for electronics applications. ICL Group Ltd. anchors its position through captive Dead Sea brine reserves and downstream flame retardant compounding. LANXESS competes by specializing in tailored benzyl bromide solutions for European pharmaceutical contract manufacturers.
Organic bromides comprise bromine-carbon compounds synthesized through halogenation of alkanes, alkenes, or aromatics, typically yielding reactive intermediates with boiling points ranging from 3.6°C for methyl bromide to 198°C for benzyl bromide. These compounds serve primarily as chemical building blocks, soil fumigants, and flame-retardant precursors where bromine's high electronegativity imparts reactivity or thermal stability. Agricultural pesticides and pharmaceutical intermediates together absorb the majority of volume, though flame retardants command superior margins due to electronics-grade purity requirements and stringent halogen content specifications. Technical grade material still occupies the largest volume share, but analytical and USP grades are expanding fastest as pharmaceutical and semiconductor end users tighten impurity thresholds.
EPA assessments under the Toxic Substances Control Act and REACH authorization requirements are restricting certain methyl bromide applications while accelerating demand for alternative fumigants and higher-purity derivatives. China's MEE enforces emission controls on brominated flame retardant production facilities, reshaping regional supply patterns. India's CDSCO and BIS frameworks are tightening pharmaceutical intermediate specifications, forcing import substitution toward domestic certified producers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which product grades and applications will retain market access versus face phasedown pressures.
Market Dynamics
REACH authorization requirements and EPA assessments under the Toxic Substances Control Act are forcing flame retardant and agricultural chemical manufacturers to reformulate around lower-toxicity brominated derivatives, compressing legacy methyl bromide volumes while expanding specialty grade demand.
Growth Catalysts
- Building code tightening:Developed economies are mandating stricter fire safety standards in construction, pulling brominated flame retardant procurement from electronics and insulation manufacturers.
- REACH authorization pathways:European manufacturers are securing continued market access for critical brominated intermediates through substance-specific authorization dossiers.
- Soil fumigation demand:Agricultural intensification in India and China is concentrating methyl bromide consumption for pre-plant pest control in high-value horticulture.
Market Restraints
- Bromine supply concentration:Extraction from Dead Sea brine and Arkansas brine fields limits geographic diversification of elemental bromine feedstock.
- EPA phase-down schedules:Critical Use Exemptions for methyl bromide are narrowing annually, forcing agricultural users toward alternative fumigants.
- Phosphorus-nitrogen substitution:Intumescent halogen-free flame retardants are capturing specification share in European consumer electronics housings.
Strategic Opportunities
- Indian pharmaceutical intermediates:CDSCO and BIS certification requirements are creating import substitution openings for domestic benzyl bromide producers.
- Semiconductor-grade purity:Electronics manufacturers are tightening impurity thresholds below 10 ppm for wafer processing chemicals.
- China MEE emission controls:Environmental compliance investments are consolidating brominated flame retardant production toward integrated coastal facilities.
Industry Challenges
- Analytical chemistry talent scarcity:USP and electronics-grade certification requires specialized chromatography expertise that contract labs struggle to staff.
- Multi-jurisdiction registration timelines:Synchronous EPA, REACH, and BIS filings for new brominated derivatives extend commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Bromide Market |
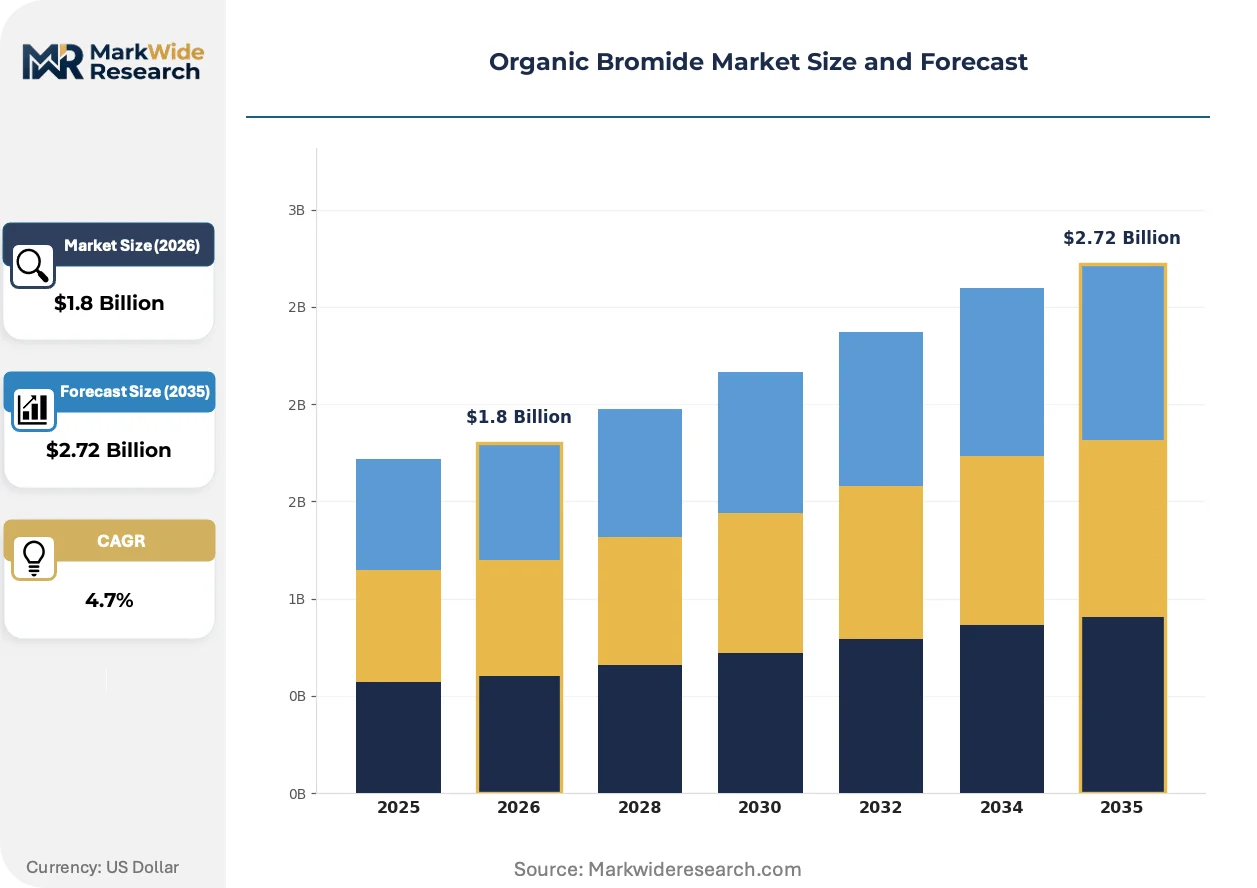
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Bromide, Ethylene Bromide, Benzyl Bromide, Isopropyl Bromide Application: Agricultural Pesticides, Pharmaceutical Intermediates, Flame Retardants, Solvents End User: Agriculture, Pharmaceuticals, Chemicals, Electronics Purity Grade: Technical Grade, Analytical Grade, USP Grade, Others |
| Companies Covered | Albemarle Corporation, ICL Group Ltd., LANXESS, Tosoh Corporation, Jordan Bromine Company, TETRA Technologies, Inc., Gulf Resources, Tata Chemicals Ltd., Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Bromide Market Evolving Landscape
Reformulation pressures and purity escalation are compressing legacy product lifecycles while opening specification gaps for advanced brominated intermediates. Three active shifts are redirecting competitive positioning.
Continuous flow bromination reactor technology is miniaturizing. Pharmaceutical contract manufacturers are adopting skid-mounted continuous processing units to replace batch halogenation vessels. This equipment footprint reduction is enabling distributed production of high-purity benzyl bromide closer to formulation facilities, compressing logistics costs and contamination risk for electronics-grade material.
REACH authorization sunset dates are hardening. ECHA's 2025-2027 review calendar for brominated flame retardant substances is forcing European compounders to pre-register alternative chemistries. Electronics cable manufacturers are responding by dual-qualifying phosphorus-bromine hybrid systems alongside legacy formulations to hedge against supply interruption.
Specification-driven supplier consolidation is accelerating. Agricultural soil fumigation distributors are narrowing approved vendor lists to producers with simultaneous EPA, CDSCO, and BIS registrations. Indian methyl bromide importers are vertically integrating toward captive fumigation service operations to secure supply priority from certified manufacturers.
Organic Bromide Market Segmentation
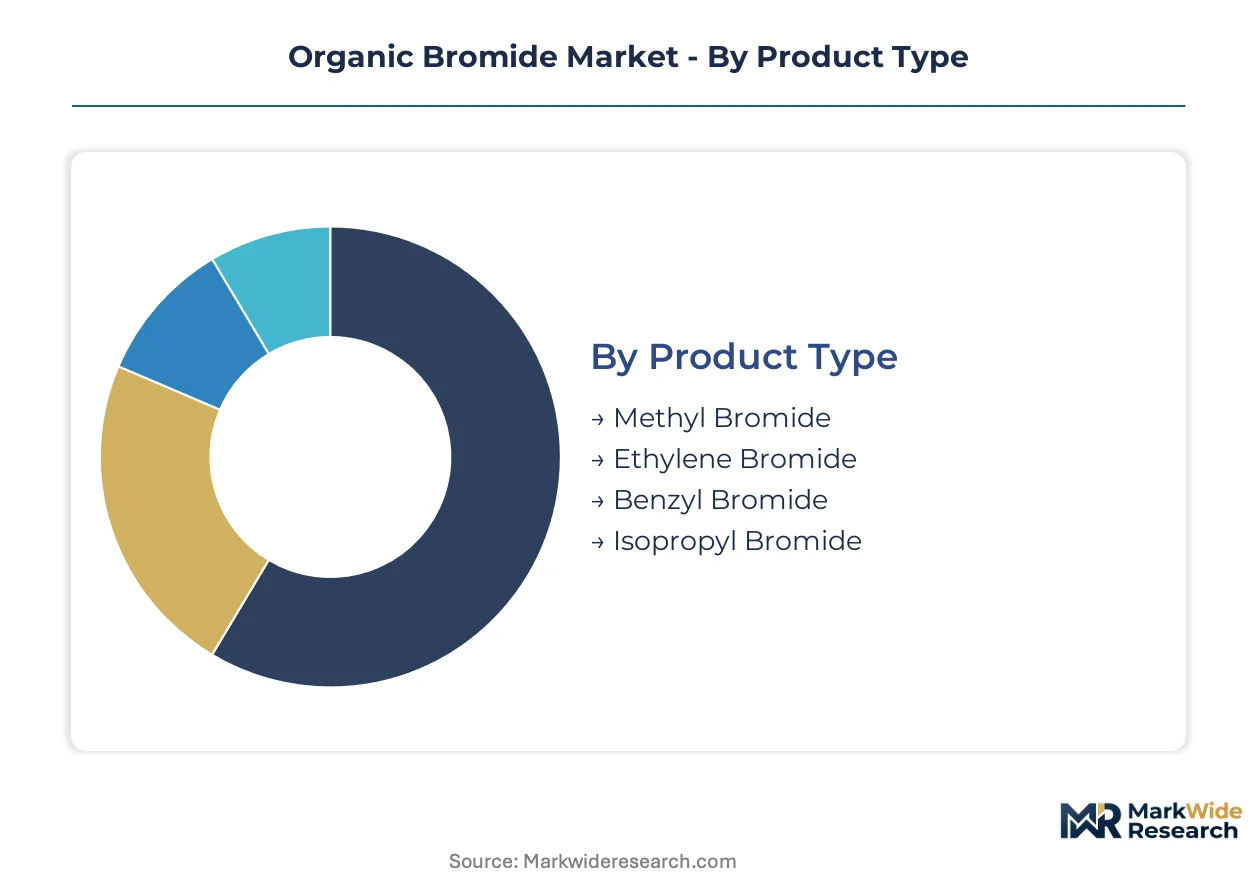
Organic bromide producers face divergent margin structures across product types and purity grades. Specification requirements from pharmaceutical and electronics end users fragment procurement patterns, forcing suppliers to position across multiple certification tiers simultaneously.
Product Type:
Methyl bromide and benzyl bromide command the widest margin spreads due to regulatory complexity and pharmaceutical-grade purification requirements.
- Methyl Bromide:A one-carbon alkyl bromide with boiling point of 3.6°C, synthesized through bromination of methane or methanol. Agricultural soil fumigation in India and China absorbs the majority of volume, though EPA Critical Use Exemptions are narrowing annually and forcing reformulation toward alternative chemistries.
- Benzyl Bromide:An aromatic bromide (C6H5CH2Br) with 198°C boiling point, serving as a reactive intermediate for Grignard reagents and quaternary ammonium compounds. European pharmaceutical contract manufacturers are tightening impurity specifications below 50 ppm, compressing qualified supplier lists to vertically integrated bromine extractors.
- Ethylene Bromide:A vicinal dibromide used historically as a gasoline additive and now concentrated in specialty polymer synthesis.
- Isopropyl Bromide:A secondary alkyl bromide finding niche application in pharmaceutical alkylating agents and solvent formulations.
The dominant share belongs to methyl bromide, while benzyl bromide is expanding most quickly through pharmaceutical intermediate demand.
Application:
End-use specifications determine pricing power, with electronics-grade flame retardants separating from commodity agricultural applications.
- Flame Retardants:Brominated compounds act as radical scavengers in polymer combustion, with electronics cable and housing manufacturers demanding halogen content below 900 ppm to meet REACH restrictions. Building code tightening across Germany, Japan, and California is pulling procurement from insulation compounders.
- Pharmaceutical Intermediates:Benzyl bromide and alkyl bromides serve as alkylating agents for active pharmaceutical ingredient synthesis. CDSCO and BIS certification requirements in India are forcing import substitution toward domestic producers with simultaneous FDA and EMA dossier capabilities.
- Agricultural Pesticides:Methyl bromide soil fumigation dominates pre-plant pest control in high-value horticulture.
- Solvents:Polar aprotic brominated solvents find declining application in industrial cleaning and extraction processes.
Flame retardants retain the dominant share, while pharmaceutical intermediates are climbing the fastest as impurity thresholds tighten.
End User:
Customer concentration and qualification timelines vary sharply across sectors, with electronics and pharmaceuticals demanding multi-year certification cycles.
- Electronics:Cable manufacturers and semiconductor fabricators require electronics-grade brominated flame retardants with metal ion impurities below 10 ppm for wafer processing. Dual-qualification of phosphorus-bromine hybrid systems is accelerating as REACH sunset dates approach.
- Pharmaceuticals:Contract manufacturers and API producers source benzyl bromide under USP and analytical grade specifications, with chromatography purity certificates mandatory for regulatory filings.
- Agriculture:Soil fumigation distributors and high-value horticulture operations concentrate methyl bromide procurement.
- Chemicals:Specialty and commodity chemical producers absorb technical grade material for downstream derivative synthesis.
Agriculture holds the dominant share, though electronics is gaining share fastest through semiconductor-grade purity requirements.
Purity Grade:
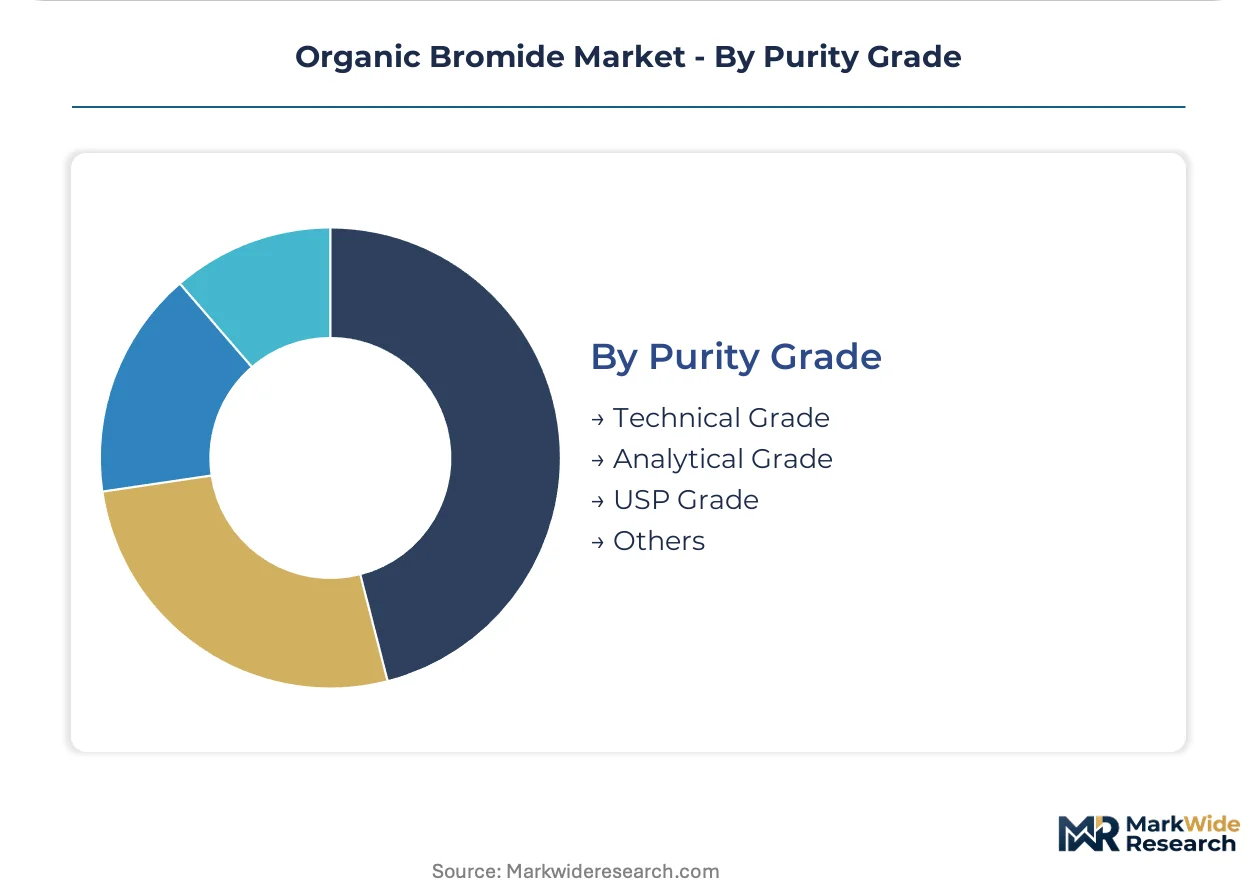
Certification tiers separate commodity producers from specialty chemical suppliers, with analytical and USP grades requiring dedicated chromatography infrastructure.
- Technical Grade:Material with 95-98% purity serves agricultural fumigation and industrial solvent applications where trace metal content is not specification-critical. China and India concentrate production of this grade through integrated bromine extraction facilities.
- Analytical Grade:Chromatography-certified material with 99%+ purity and documented impurity profiles supports pharmaceutical research and quality control laboratories. The scarcity of gas chromatography-mass spectrometry talent in contract labs is constraining certified production expansion.
- USP Grade:Pharmacopeia-compliant material meets FDA and EMA filing requirements for active pharmaceutical ingredient synthesis.
- Others:Custom specification grades for semiconductor and electronics applications with proprietary impurity thresholds.
Technical grade commands the dominant share, while analytical grade shows the steepest expansion trajectory through pharmaceutical and electronics qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elemental bromine extraction clusters around Dead Sea brine operations and Arkansas brine fields, constraining feedstock diversification and concentrating derivative production near these source points. Regulatory divergence across major consuming jurisdictions is fragmenting formulation strategies and reshaping trade flows for finished organic bromides.
United States
Flame retardant compounders in the Southeast and Gulf Coast are expanding capacity to serve electronics cable manufacturers facing REACH-equivalent state-level restrictions. EPA phase-down schedules for methyl bromide Critical Use Exemptions are narrowing agricultural applications annually. The Arkansas-Louisiana brine corridor anchors domestic bromine extraction, with downstream facilities in Texas processing technical and pharmaceutical grades.
Germany
Automotive and electronics housing manufacturers are dual-qualifying phosphorus-bromine hybrid flame retardants ahead of ECHA's 2025-2027 sunset date reviews. REACH authorization dossiers for critical brominated intermediates are compressing qualified supplier lists to vertically integrated producers. The Rhine-Ruhr industrial cluster concentrates compounding operations for European cable and insulation markets.
China
MEE emission controls on brominated flame retardant production are consolidating manufacturing toward Shandong and Jiangsu coastal provinces with integrated environmental compliance infrastructure. Agricultural methyl bromide consumption is intensifying in Shandong's greenhouse horticulture belt for high-value export crops. Yangtze River Delta electronics fabricators are tightening metal ion impurity specifications below 10 ppm for wafer processing chemicals.
India
CDSCO and BIS certification requirements for pharmaceutical intermediates are forcing import substitution toward domestic benzyl bromide producers with simultaneous FDA and EMA dossier capabilities. Soil fumigation demand is concentrating in Maharashtra and Karnataka for pre-plant pest control in grape and pomegranate orchards. Gujarat's integrated chemical parks are attracting backward integration investments from agricultural distributors seeking captive supply security.
Japan
METI guidelines on halogen content in consumer electronics housings are accelerating phosphorus-bromine hybrid adoption ahead of potential REACH-aligning domestic restrictions. Semiconductor fabricators in Kyushu and the Tokyo Bay corridor are qualifying new suppliers for sub-10 ppm purity grades. The Osaka-Kobe chemical complex maintains specialty brominated solvent production for legacy pharmaceutical synthesis contracts.
Organic Bromide Market Competitive Landscape
Concentration sits with vertically integrated bromine extractors that command captive brine reserves and downstream derivative capacity. Three archetypes define competitive positioning: Dead Sea and Arkansas-based integrated extractors with global flame retardant distribution; European pharmaceutical-grade specialists with REACH authorization expertise; and Chinese coastal producers with MEE-compliant integrated facilities. Dominant competitive moves include backward integration into brine extraction and geographic expansion of pharmaceutical-grade certification portfolios.
Among integrated bromine extractors, Albemarle Corporation exemplifies the vertically integrated archetype through its Arkansas brine operations and downstream electronics-grade production. ICL Group Ltd. anchors the Dead Sea reserve-based tier with captive brine processing and flame retardant compounding capabilities. LANXESS occupies a position within the European pharmaceutical-specialist segment, serving contract manufacturers with tailored benzyl bromide solutions and REACH compliance infrastructure.
| Leading Market Players |
|---|
| Albemarle Corporation |
| ICL Group Ltd. |
| LANXESS |
| Tosoh Corporation |
| Jordan Bromine Company |
| TETRA Technologies, Inc. |
| Gulf Resources |
| Tata Chemicals Ltd. |
| Arkema |
| Others |
Value Network & Pricing Analysis
REACH authorization requirements and EPA Critical Use Exemption schedules simultaneously gate supplier qualification and stratify price tiers across the organic bromide value chain. Certification burden concentrates pricing power with vertically integrated producers while forcing commodity-grade suppliers toward cost-competitive geographies.
Pricing Analysis
REACH authorization dictates the pricing tier structure across European pharmaceutical and flame retardant procurement, separating premium-validated suppliers from technical-grade competitors. Price differentiation rests on USP-grade certification and semiconductor-grade metal ion thresholds below 10 ppm. Cost compression in agricultural methyl bromide intensifies as EPA phase-down schedules narrow exempted applications annually. Electronics manufacturers exhibit the lowest price sensitivity due to wafer contamination risk, while soil fumigation distributors in India and China prioritize volume scale over purity premiums.
Supply Chain Analysis
Israel and Jordan anchor elemental bromine extraction through Dead Sea brine operations, while Arkansas-Louisiana brine fields feed North American derivative production. Downstream synthesis draws from captive bromine, methanol feedstock, and specialized halogenation catalysts. Single-source vulnerability concentrates in Dead Sea brine dependency where geopolitical or climatic disruption would cascade through global flame retardant supply. Distribution runs through integrated coastal facilities in China and India for Asian agricultural and pharmaceutical demand, with European compounders maintaining regional qualification hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, REACH, and CDSCO jurisdictions fragments procurement standards, creating specification niches for certified specialists and geographic arbitrage opportunities.
For Market Incumbents: Fortify captive brine reserve positions through lease extensions or joint development agreements in Arkansas and Dead Sea corridors. Expand semiconductor-grade purification capacity ahead of sub-10 ppm specification tightening by Yangtze River Delta fabricators. Defend against phosphorus-nitrogen hybrid substitution by dual-qualifying brominated formulations for electronics cable manufacturers hedging REACH sunset exposure.
For New Entrants and Emerging Players: Contract analytical certification services represent the critical service-layer gap where incumbent producers under-serve mid-tier pharmaceutical contract manufacturers lacking in-house chromatography infrastructure. Penetrate Indian benzyl bromide import substitution demand by securing simultaneous CDSCO, BIS, and FDA dossier capabilities ahead of domestic capacity buildout. Lead with distributed continuous flow reactor deployment to compress logistics costs for electronics-grade material.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across semiconductor-grade purification infrastructure as metal ion thresholds tighten below 10 ppm. Five-to-ten year viability favors producers with integrated brine-to-derivative pipelines and multi-jurisdiction certification portfolios. Acquisition targets should demonstrate REACH authorization expertise or captive Dead Sea brine access. Monitor ECHA 2025-2027 sunset date announcements as inflection signals for phosphorus-bromine hybrid substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Extraction | Captive Arkansas or Dead Sea brine reserves insulate feedstock cost volatility from regional supply shocks. |
| Semiconductor-Grade Purification Capacity Expansion | Sub-10 ppm metal ion certification opens wafer processing chemical procurement from Kyushu fabricators. |
| REACH Authorization Dossier Investment | Substance-specific approvals secure continued European market access for critical brominated intermediates. |
| Continuous Flow Reactor Deployment | Skid-mounted halogenation units enable distributed benzyl bromide production near pharmaceutical formulation facilities. |
| Multi-Jurisdiction Certification Portfolio | Simultaneous EPA, CDSCO, and BIS registrations qualify suppliers for narrowing agricultural vendor lists. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, ECHA authorization registers, and CDSCO certification databases. Primary interviews engaged plant managers at bromine extraction facilities, procurement leads at flame retardant compounders, regulatory affairs directors at pharmaceutical intermediates producers, and distribution channel partners in Indian agricultural fumigation. Bottom-up volume estimates triangulated against top-down value projections derived from trade flow analysis and capacity announcements.
Segmentation dimensions modeled include purity grade tier, end-use application, regional production hub, and regulatory jurisdiction cluster. CAGRs were derived from demand elasticity analysis across building code tightening schedules, pharmaceutical intermediate qualification timelines, and agricultural intensification patterns. Forecast inputs incorporated REACH sunset date calendars, EPA Critical Use Exemption phase-down trajectories, and MEE emission control compliance investments.
Forecasts assume regulatory continuity in REACH authorization pathways, EPA methyl bromide exemption schedules, and CDSCO certification frameworks; material policy shifts would require re-modeling. Recalibration cycles align with ECHA review calendar announcements, EPA exemption renewals, and MEE enforcement actions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
Neem Extract Market